
 Europe Multi-Cloud Networking in Fintech Market | 2026-2036
Europe Multi-Cloud Networking in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Multi-Cloud Networking in Fintech Market Analytics
Pay-as-you-grow infrastructure leasing is fragmenting competitive dynamics in European fintech cloud networking. Amazon Web Services leverages its extensive Frankfurt and Dublin region footprint to anchor institutional workloads requiring low-latency settlement. Microsoft Azure competes through specialized financial services compliance templates that streamline ECB-aligned reporting requirements.
Multi-cloud networking in fintech denotes the orchestration of secure, low-latency connectivity across two or more cloud environments, typically incorporating SD-WAN controllers with sub-50 millisecond failover thresholds to ensure continuous transaction processing. Its primary purpose centers on eliminating single-provider dependency while maintaining PCI-DSS and GDPR-compliant data flows across jurisdictional boundaries. Hybrid cloud deployment dominates current infrastructure budgets as legacy core banking systems resist full migration, yet cross-cloud management technology captures disproportionate R&D investment as institutions seek unified policy enforcement. Managed services within the service type dimension sustain higher margin profiles than infrastructure provisioning alone, reflecting the complexity of maintaining regulatory audit trails across heterogeneous environments.
GDPR, the EU AI Act, and the Digital Operational Resilience Act (DORA) collectively reshape procurement criteria by mandating demonstrable data residency, algorithmic transparency, and operational stress-testing. EBA guidelines on outsourcing further constrain how financial institutions evaluate vendor concentration risk. Stakeholders must weigh sovereign cloud certification status against interoperability standards when selecting provider portfolios.
Market Dynamics
PSD2-mandated open banking APIs are forcing European payment processors to rearchitect data flows across sovereign cloud boundaries, fragmenting traditional single-provider infrastructure commitments.
Growth Catalysts
- GDPR data residency mandates:Article 44 transfer restrictions compel fintechs to maintain EU-located processing nodes, driving multi-cloud redundancy investments.
- Real-time payment rails:TARGET Instant Payment Settlement (TIPS) adoption across eurozone banks requires sub-100 millisecond failover architectures that single clouds cannot guarantee.
- BaFin outsourcing circulars:German regulator guidelines on critical function separation push institutions toward distributed cloud strategies with documented vendor independence.
Market Restraints
- Cross-border latency physics:Fiber distance between Dublin and Frankfurt creates irreducible propagation delays for synchronous database replication.
- Concentrated certification bodies:Only three EBA-recognized auditors can validate DORA-aligned operational resilience, creating queue bottlenecks for cloud provider approvals.
- Legacy core banking lock-in:COBOL-based settlement engines resist API containerization, forcing expensive middleware layers for multi-cloud orchestration.
Strategic Opportunities
- Poland's underpenetrated market:Polish fintechs lag German counterparts in cloud-native adoption, creating first-mover advantage for managed multi-cloud service providers.
- AI Act algorithmic audit trails:Automated compliance documentation requirements favor platforms with built-in cross-cloud policy enforcement engines.
- SD-WAN and SASE convergence:Unified secure access service edge architectures reduce separate networking and security procurement cycles for mid-tier institutions.
Industry Challenges
- Site reliability engineering scarcity:European talent pools lack sufficient Kubernetes-certified engineers capable of managing heterogeneous cloud control planes.
- PCI-DSS 4.0 transition timelines:March 2025 enforcement deadlines compress migration windows for institutions running multi-tenant cardholder environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Multi-Cloud Networking in Fintech Market |
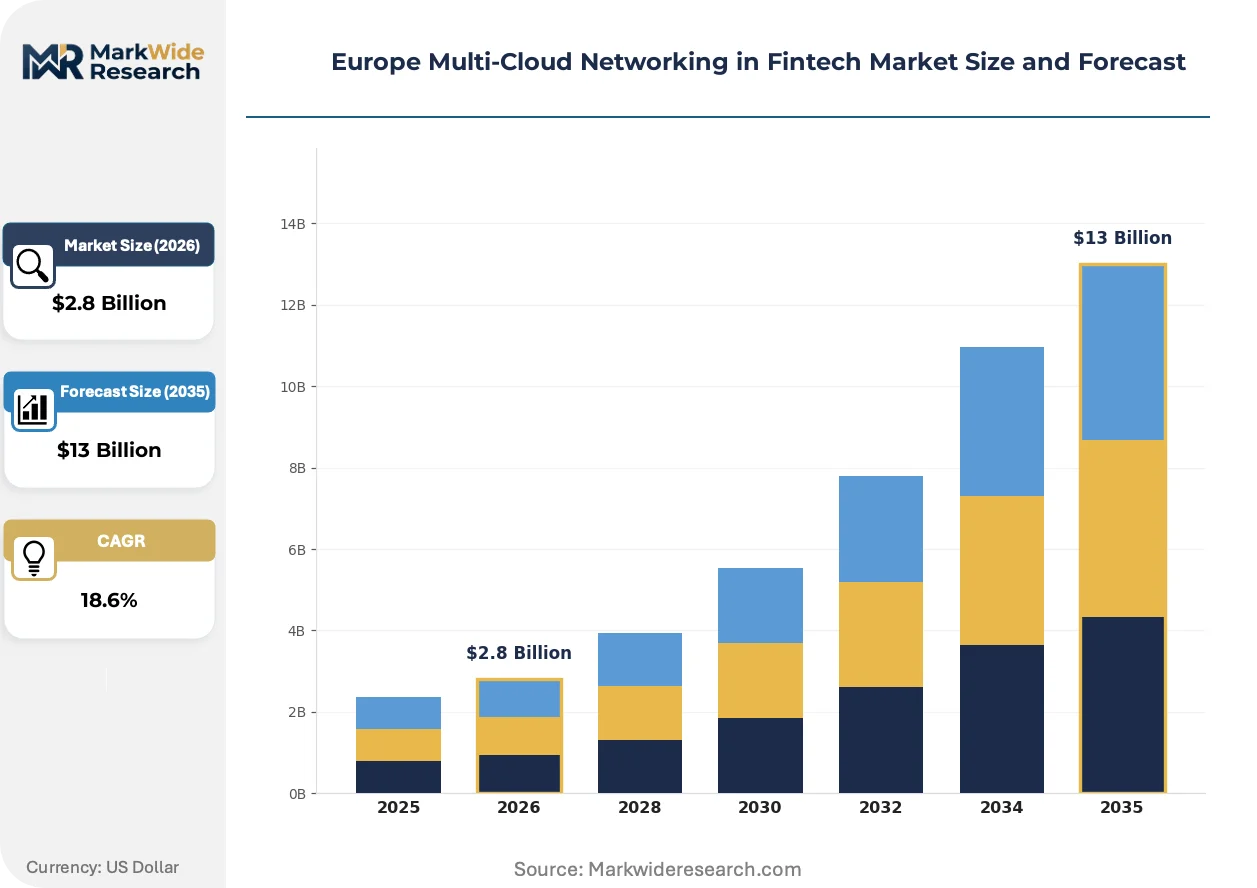
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Hybrid Cloud, Public Cloud, Private Cloud, Multi-Cloud Service Type: Managed Services, Consulting Services, Infrastructure Services, Security Services Client Type: Startups, Enterprises, Financial Institutions, Payment Processors Technology: SD-WAN, Virtual Private Network, Direct Connect, Cross-Cloud Management |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM, Oracle Corporation, VMware, Cisco Systems, OVHcloud, Cloudflare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Multi-Cloud Networking in Fintech Market Evolving Landscape
Service mesh architectures are dissolving the boundary between network infrastructure and application-layer security, enabling policy-as-code governance across previously incompatible cloud environments.
Zero-trust network access (ZTNA) is collapsing perimeter-based security models in European fintech infrastructure. Tier-1 payment processors in Frankfurt and Amsterdam are deploying identity-aware proxies at 60% of new cloud ingress points. The technology is collapsing traditional VPN concentrator spend while forcing CISOs to reclassify network segmentation budgets toward identity fabric investments.
DORA's January 2025 enforcement window is compressing vendor due diligence cycles to 90-day maximums. Financial institutions must now document end-to-end resilience testing across all cloud dependencies before board approval. Nordic banks with concentrated Azure footprints face the steepest renegotiation curves as they diversify toward sovereign-certified alternatives.
Consumption-based networking contracts are displacing committed-use infrastructure deals among neobanks and payment facilitators. Dutch and Belgian fintechs now procure 70% of cross-cloud bandwidth through metered SD-WAN marketplaces rather than term leases. This shift is most pronounced among Series C-stage companies optimizing burn rates against transaction volume volatility.
Europe Multi-Cloud Networking in Fintech Market Segmentation
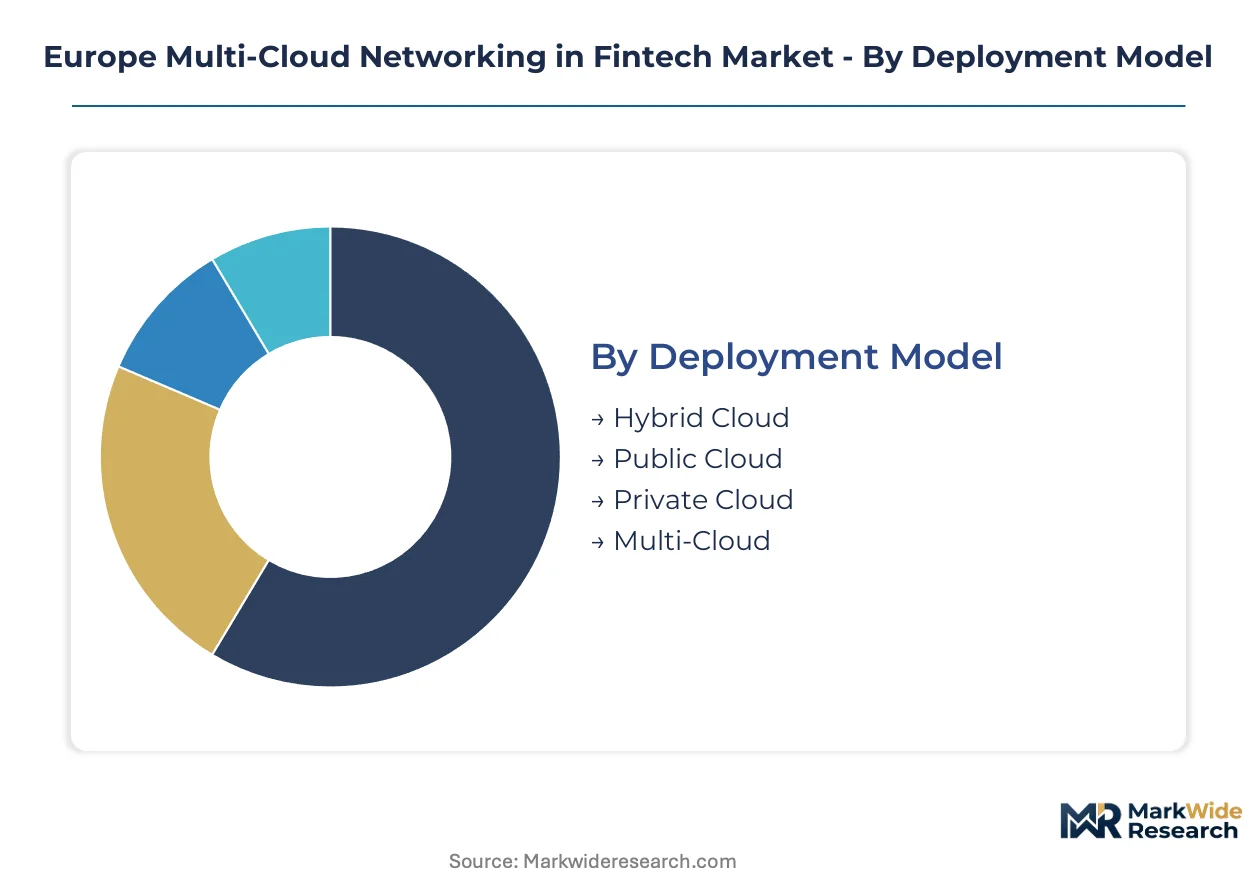
Multi-cloud networking procurement in European fintech fragments across four distinct dimensions. Deployment architecture, service packaging, client maturity, and underlying connectivity technology each shape vendor selection criteria and margin structures differently.
Deployment Model:
Cost tier determines how institutions balance capital efficiency against regulatory audit complexity.
- Hybrid Cloud:Combines on-premises core banking infrastructure with cloud-native transaction processing layers. German and Dutch payment processors favor this architecture to satisfy BaFin outsourcing circulars while preserving legacy COBOL settlement engines.
- Multi-Cloud:Orchestrates workloads across two or more hyperscaler environments with automated failover below 50 milliseconds. Nordic banks are expanding multi-cloud footprints fastest to meet DORA's vendor concentration limits.
- Public Cloud:Delivers elastic compute through shared infrastructure with standardized compliance templates. Mid-tier Belgian neobanks leverage public cloud for rapid TIPS integration without sovereign certification overhead.
- Private Cloud:Provides dedicated tenant isolation for cardholder data environments requiring PCI-DSS 4.0 segmentation. French institutional asset managers maintain private cloud nodes for algorithmic trading audit trails under EU AI Act requirements.
Hybrid Cloud holds installed capacity. Multi-Cloud is rotating up the share rankings.
Service Type:
Application complexity drives margin differentiation between commodity infrastructure and value-added orchestration.
- Managed Services:Encompasses 24/7 site reliability engineering, cross-cloud policy enforcement, and regulatory documentation automation. Polish fintechs are outsourcing entire networking stacks to managed providers to bypass Kubernetes talent scarcity.
- Security Services:Integrates zero-trust network access, identity-aware proxies, and DORA-aligned resilience testing. Tier-1 Frankfurt payment processors now mandate security service bundles for all new cloud ingress deployments.
- Consulting Services:Delivers cloud architecture design, vendor due diligence acceleration, and EBA outsourcing guideline alignment. Irish fintechs engage consultants to compress 90-day DORA compliance windows.
- Infrastructure Services:Provisions raw compute, storage, and bandwidth with metered consumption billing. Dutch Series C-stage companies procure 70% of cross-cloud bandwidth through infrastructure marketplaces rather than term commitments.
Managed Services commands premium pricing. Security Services is climbing the fastest.
Client Type:
Customer maturity shapes procurement sophistication and contract duration preferences.
- Financial Institutions:Encompasses eurozone banks with TARGET2 and TIPS settlement mandates. These clients demand sub-100 millisecond failover architectures with documented operational resilience under ECB supervision.
- Payment Processors:Includes card networks and merchant acquirers processing PSD2-mandated open banking APIs. German processors are fragmenting single-provider commitments to satisfy data sovereignty requirements.
- Enterprises:Captures corporate treasuries and captive finance units with hybrid cloud budgets. These clients prioritize unified policy enforcement across legacy core systems and cloud-native workloads.
- Startups:Comprises neobanks and payment facilitators optimizing burn rates against transaction volatility. Belgian and Dutch startups favor consumption-based networking contracts over committed-use infrastructure deals.
Financial Institutions anchor contract value. Payment Processors is expanding most quickly.
Technology:
Volume concentration in synchronous payment processing dictates latency thresholds and failover automation requirements.
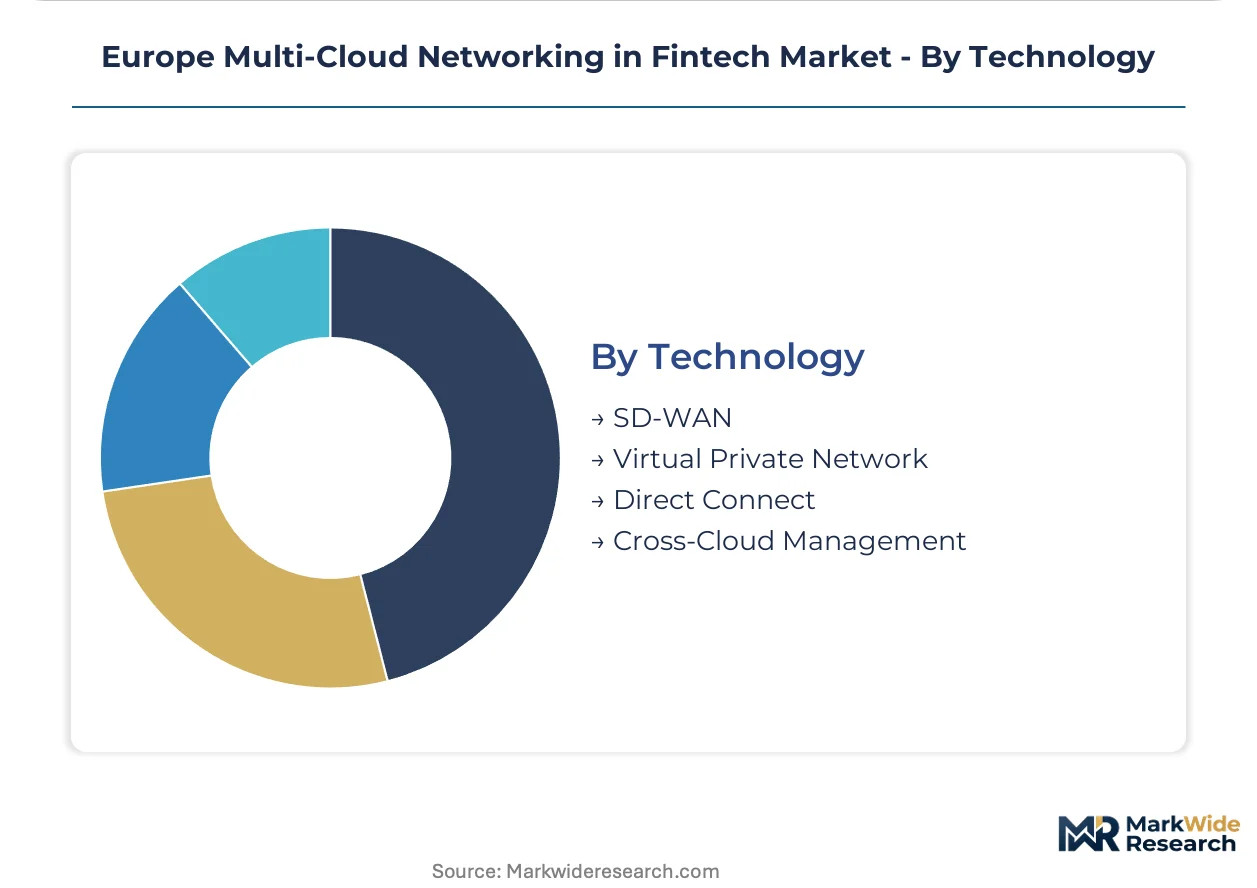
- SD-WAN:Software-defined wide area networking with sub-50 millisecond controller failover and application-aware traffic steering. Amsterdam and Frankfurt Tier-1 processors deploy SD-WAN at 60% of new cloud ingress points.
- Cross-Cloud Management:Unified control planes for policy-as-code governance across heterogeneous environments. This technology captures disproportionate R&D investment as institutions seek single-pane orchestration.
- Direct Connect:Dedicated fiber links bypassing public internet for settlement engine replication. Fiber distance between Dublin and Frankfurt creates irreducible propagation delays for synchronous database replication.
- Virtual Private Network:Encrypted tunneling for legacy application migration and inter-cloud data transfer. VPN concentrator spend is collapsing as ZTNA architectures displace perimeter-based security models.
SD-WAN dominates current procurement. Cross-Cloud Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European fintech cloud infrastructure exhibits a pronounced trade surplus in managed networking services, with Frankfurt and Amsterdam serving as primary export hubs for multi-cloud orchestration expertise while importing raw compute capacity from Dublin and Nordic data center zones.
Germany
BaFin outsourcing circulars and TARGET2 settlement mandates drive multi-cloud redundancy investments among Frankfurt-based payment processors. The Digital Operational Resilience Act compels institutions to document vendor independence across critical functions. Bavarian neobanks are expanding managed service partnerships to bypass Kubernetes talent scarcity while maintaining sovereign cloud certification.
Netherlands
Amsterdam's position as a submarine cable landing point attracts SD-WAN deployments from pan-European card networks seeking sub-50 millisecond failover. Dutch Series C-stage fintechs favor consumption-based bandwidth procurement through metered marketplaces over committed-use infrastructure leases. The Dutch Central Bank's oversight framework accelerates DORA compliance documentation requirements.
France
French institutional asset managers under EU AI Act pressure maintain private cloud nodes for algorithmic trading audit trails. Paris-based payment facilitators fragment single-provider commitments to satisfy GDPR Article 44 transfer restrictions. The Île-de-France cluster leads continental adoption of zero-trust network access at cloud ingress points.
United Kingdom
London's post-Brexit regulatory autonomy creates divergence in outsourcing guideline interpretation, with the Prudential Regulation Authority maintaining ECB-aligned stress-testing expectations. UK neobanks leverage cross-cloud management platforms for rapid TIPS-equivalent real-time payment integration. Scottish fintechs lag English counterparts in cloud-native adoption, creating first-mover opportunities for managed service providers.
Poland
Polish payment processors exhibit underpenetrated multi-cloud adoption relative to Western European benchmarks, concentrating procurement decisions in Warsaw and Kraków financial districts. The Polish Financial Supervision Authority's evolving outsourcing guidelines create compliance windows for foreign managed service entry. Domestic fintechs increasingly outsource entire networking stacks to bypass regional site reliability engineering scarcity.
Europe Multi-Cloud Networking in Fintech Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying SD-WAN controllers and identity-aware proxy technologies. The European fintech multi-cloud networking market consolidates around three hyperscaler platforms with sovereign-certified regional footprints, while mid-tier managed service providers fragment across national regulatory specializations. Two strategic archetypes dominate: full-stack orchestrators bundling compliance automation with infrastructure provisioning, and pure-play connectivity vendors optimizing cross-cloud latency. Competitive intensity centers on geographic expansion into underpenetrated Central European markets and portfolio diversification toward AI Act-aligned audit trail automation.
Within the full-stack orchestrator tier, Amazon Web Services and Microsoft Azure anchor institutional workload deployments through Frankfurt and Dublin region density. Google Cloud occupies a position among cloud-native fintechs prioritizing containerized workload portability. OVHcloud exemplifies the sovereign-certified alternative archetype, serving institutions with mandatory data residency requirements under French regulatory jurisdiction. VMware and Cisco Systems sit within the component specialist category, supplying virtualization and networking infrastructure to heterogeneous multi-cloud environments without direct hyperscaler competition.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM |
| Oracle Corporation |
| VMware |
| Cisco Systems |
| OVHcloud |
| Cloudflare |
| Others |
Value Network & Pricing Analysis
SD-WAN controller manufacturing concentrates in Taiwan and the United States, concentrating margin capture among semiconductor-dependent networking vendors while European fintech buyers absorb premium pricing for sub-50 millisecond failover certification.
Pricing Analysis
Financial institutions anchor subscription-based SaaS pricing for managed multi-cloud networking services. Three-tier pricing structure across premium sovereign-certified, standard compliant, and economy utility tiers reflects BaFin audit complexity and GDPR data residency grade. Pricing pressure stems from consumption-based SD-WAN marketplaces displacing committed-use term leases among Dutch and Belgian neobanks. Payment processors exhibit highest price sensitivity due to transaction volume volatility, while German institutional asset managers accept premium tiers for DORA-aligned resilience documentation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for encryption chip sourcing. Taiwan, the United States, and Ireland concentrate SD-WAN controller and identity-aware proxy production. Optical fiber, specialized ASICs, and sovereign-certified server hardware constitute critical input dependencies. Single-source vulnerability concentrates in EBA-recognized auditor capacity for DORA validation. Distribution runs through Frankfurt and Amsterdam as managed service hubs, with Dublin and Nordic zones supplying raw compute capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
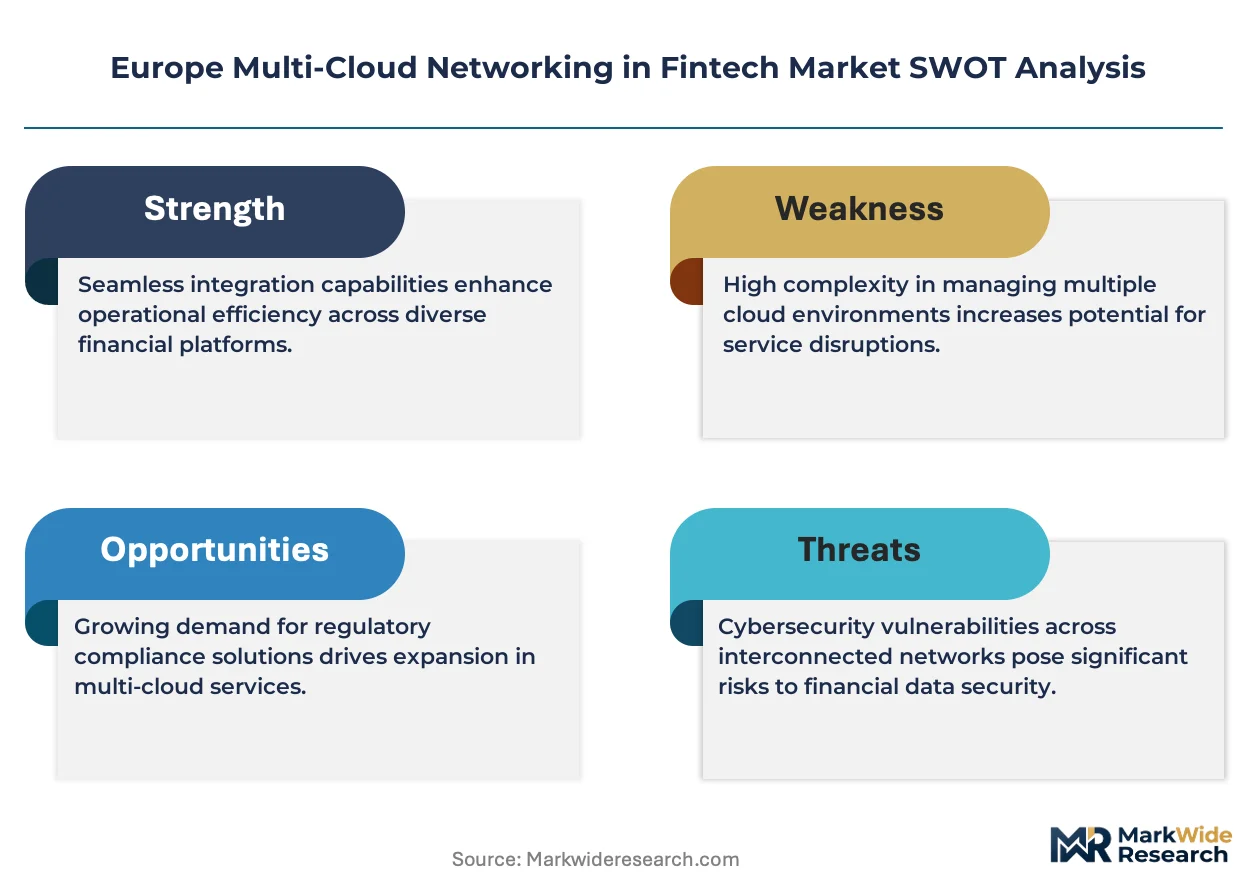
Multi-cloud networking in European fintech functions as a service-attach opportunity where managed security bundles and compliance automation layers expand faster than underlying infrastructure provisioning.
For Market Incumbents: Insulate core Frankfurt and Amsterdam region dominance through sovereign cloud certification investments that emerging hyperscaler entrants cannot replicate quickly. Deepen backward integration into SD-WAN controller development to reduce Taiwan semiconductor dependency. Prioritize Kubernetes talent acquisition pipelines to counter site reliability engineering scarcity threatening service quality commitments. For New Entrants and Emerging Players: Poland's underpenetrated multi-cloud adoption relative to Western European benchmarks offers first-mover positioning in Warsaw and Kraków financial districts. Target managed service outsourcing contracts from Polish fintechs seeking to bypass regional Kubernetes certification gaps. Lead with DORA compliance documentation automation as the differentiated go-to-market wedge against established Western European providers. For Investors and Strategic Acquirers: Capital is best deployed toward full-stack orchestrators bundling AI Act-aligned audit trail automation with cross-cloud policy enforcement engines. Long-term viability favors platforms with demonstrated EBA outsourcing guideline alignment and established relationships with the three recognized DORA auditors. Monitor Polish Financial Supervision Authority regulatory evolution as the signal indicating Central European market opening velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | BaFin and ECB outsourcing circulars mandate documented vendor independence for critical settlement functions. |
| AI Act Compliance Automation Development | Algorithmic audit trail requirements favor platforms with built-in cross-cloud policy enforcement engines. |
| Central European Geographic Expansion | Polish fintechs lag German counterparts in cloud-native adoption, creating managed service entry windows. |
| SD-WAN and SASE Convergence | Unified secure access architectures reduce separate procurement cycles for mid-tier institutions under DORA pressure. |
| Kubernetes Talent Pipeline Acquisition | Site reliability engineering scarcity constrains heterogeneous cloud control plane management capacity. |
Research Methodology
The analysis maps hybrid cloud, multi-cloud, public cloud, and private cloud deployment architectures, each validated through cloud infrastructure architects, regulatory compliance officers, payment processor CTOs, and managed service provider executives. Primary stakeholder interviews combined with secondary validation against ECB outsourcing guidelines, EBA DORA technical standards, BaFin circular documentation, and hyperscaler regional capex disclosures. Bottom-up service provider revenue triangulation against top-down European fintech IT spending estimates anchored the market sizing framework.
Assumptions held fixed include continued PSD2 open banking API mandate enforcement, sustained GDPR Article 44 transfer restriction interpretation, and DORA operational resilience deadline adherence. Segmentation dimensions modeled encompass deployment model, service packaging tier, client maturity archetype, and underlying connectivity technology. CAGRs derived from weighted average of provider growth trajectories and end-user budget allocation surveys. Forecast inputs incorporated TIPS adoption velocity and PCI-DSS 4.0 transition timeline compression effects across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate trajectories or transatlantic data transfer agreement stability would shift the trajectory. Regulatory interpretation variance across national supervisors and hyperscaler concentration limit enforcement intensity constitute specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Taiwan Data Center Networking Market
Information and Communication Technology
Global Deep Learning Neural Networks (Dnns) Market
Information and Communication Technology
Long Term Data Retention Solutions Market
Information and Communication Technology
Device Vulnerability Management Market
Information and Communication Technology
Mobile Command and Control Solutions Market
Information and Communication Technology
Discount Management Software Market
Information and Communication Technology
OTN Equipment Market
Information and Communication Technology
IoT Integration Services Market
Information and Communication Technology
Pick and Place Machines Market
Information and Communication Technology
North Macedonia E-Commerce Market
Information and Communication Technology
US Smart Thermostat Market
Information and Communication Technology
Greece ICT Market
Information and Communication Technology
Behavior Analytics Market
Information and Communication Technology
Healthcare Supply Chain BPO Market
Information and Communication Technology
Data Center Servers Market
Information and Communication Technology
Mobile Identity Management Market