
 Enterprise-Grade DLT Market | 2026-2036
Enterprise-Grade DLT Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise-Grade DLT Market Foresight
Enterprise procurement teams is reorganizing DLT investment priorities away from experimental pilots toward production-grade infrastructure. ConsenSys anchors its position through deep tooling for Ethereum-compatible permissioned networks. LeewayHertz differentiates with full-stack development capabilities spanning smart contract architecture to node deployment. HashCash Consultants dominates cross-border remittance and trade finance implementations across Asian banking consortia.
Enterprise-grade distributed ledger technology denotes cryptographically linked, tamper-evident record-keeping systems operating at throughput thresholds exceeding 10,000 transactions per second with sub-second finality, designed to eliminate reconciliation overhead in multi-party workflows. Permissioned blockchain configurations lead current deployment value as they satisfy data residency mandates, while tokenization architectures represent the fastest-expanding technology segment for asset digitization. Hybrid cloud deployment models capture widening adoption among regulated entities seeking elastic compute without surrendering cryptographic key custody.
The EU AI Act and GDPR impose algorithmic accountability and data minimization requirements that directly shape DLT node topology and zero-knowledge proof integration. The U.S. SEC and CFTC jurisdiction over digital asset classification creates compliance-driven demand for auditable consensus mechanisms with immutable transaction trails. Enterprises must monitor evolving central bank digital currency interoperability standards as these will determine which ledger infrastructures achieve systemic payment rail status.
Market Dynamics
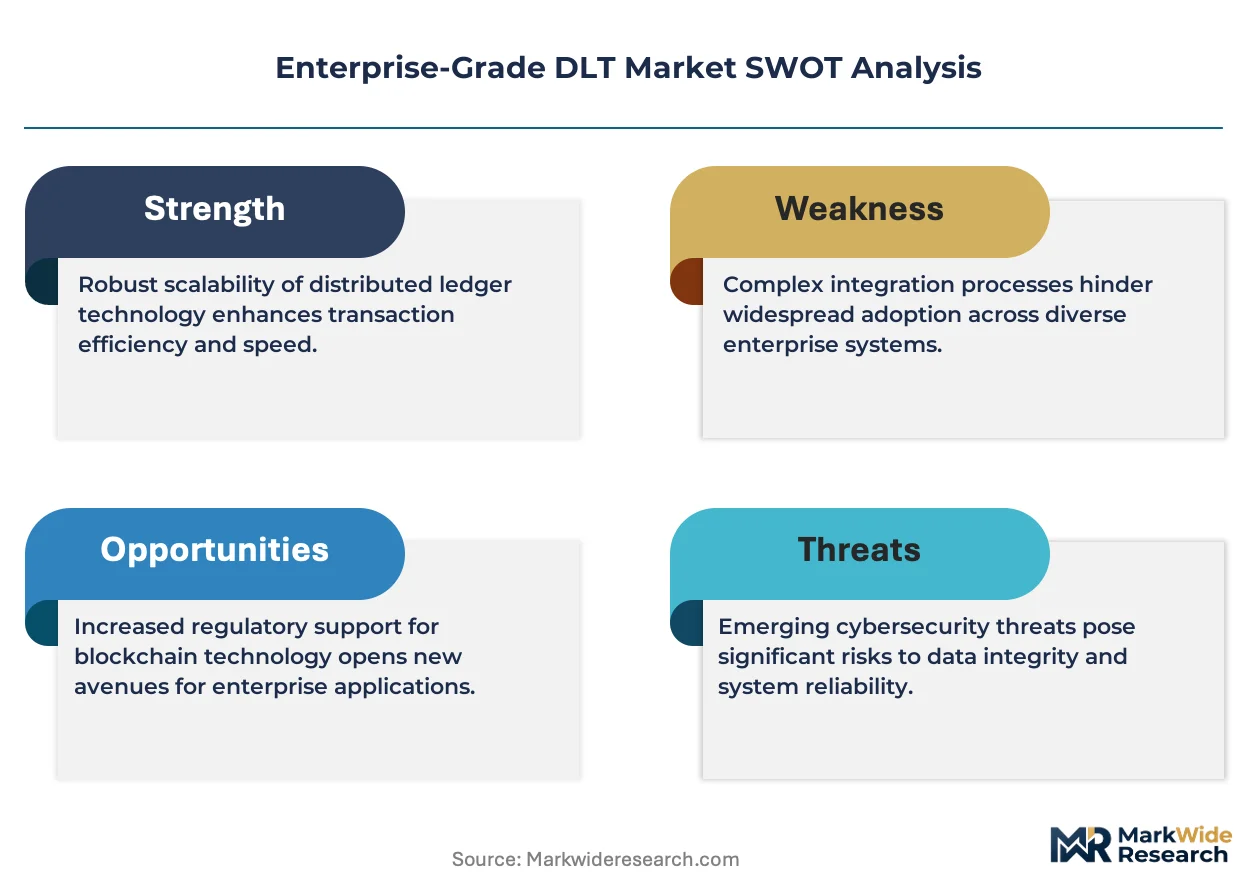
Enterprise-grade distributed ledger technology is undergoing a fundamental transition from experimental pilots to production-grade infrastructure, driven by regulatory mandates requiring immutable audit trails for financial transactions and cross-border settlement workflows.
Growth Catalysts
- EU Markets in Crypto-Assets Regulation:MiCA establishes uniform licensing frameworks for crypto-asset service providers, compelling financial institutions to deploy permissioned ledgers with cryptographic finality for compliance automation.
- Central bank digital currency interoperability:Wholesale CBDC pilot programs across Asian banking consortia are generating demand for atomic settlement rails that eliminate correspondent banking delays.
- Zero-knowledge proof integration:Privacy-preserving cryptographic techniques enable GDPR-compliant data sharing across permissioned networks without exposing underlying transaction details.
Market Restraints
- Consensus mechanism energy costs:Byzantine fault-tolerant protocols requiring extensive validator redundancy impose substantial computational overhead on enterprise data centers.
- Validator node geographic concentration:Cloud infrastructure dependencies in United States and Singapore create systemic resilience risks for cross-border settlement networks.
- Legacy core banking integration:ISO 20022 message format incompatibilities with decades-old mainframe architectures extend deployment timelines by eighteen to thirty-six months.
Strategic Opportunities
- Tokenized real-world assets:Regulatory sandboxes in Germany and Singapore permit pilot programs for securities digitization on permissioned infrastructure.
- Supply chain provenance:Convergence of IoT sensor networks with immutable ledger records creates auditable custody chains for pharmaceutical and luxury goods verticals.
- Carbon credit verification:MEE dual carbon goals in China and EU Green Deal disclosure mandates drive demand for transparent emissions tracking on distributed systems.
Industry Challenges
- Distributed systems engineering talent scarcity:Cryptography and consensus protocol expertise remains concentrated among specialists with academic research backgrounds.
- Multi-jurisdiction compliance orchestration:Simultaneous SEC, CFTC, and GDPR obligations require complex node topology configurations that fragment network architectures.
- Smart contract security auditing:Formal verification methodologies for complex financial instruments demand specialized tooling that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise-Grade DLT Market |
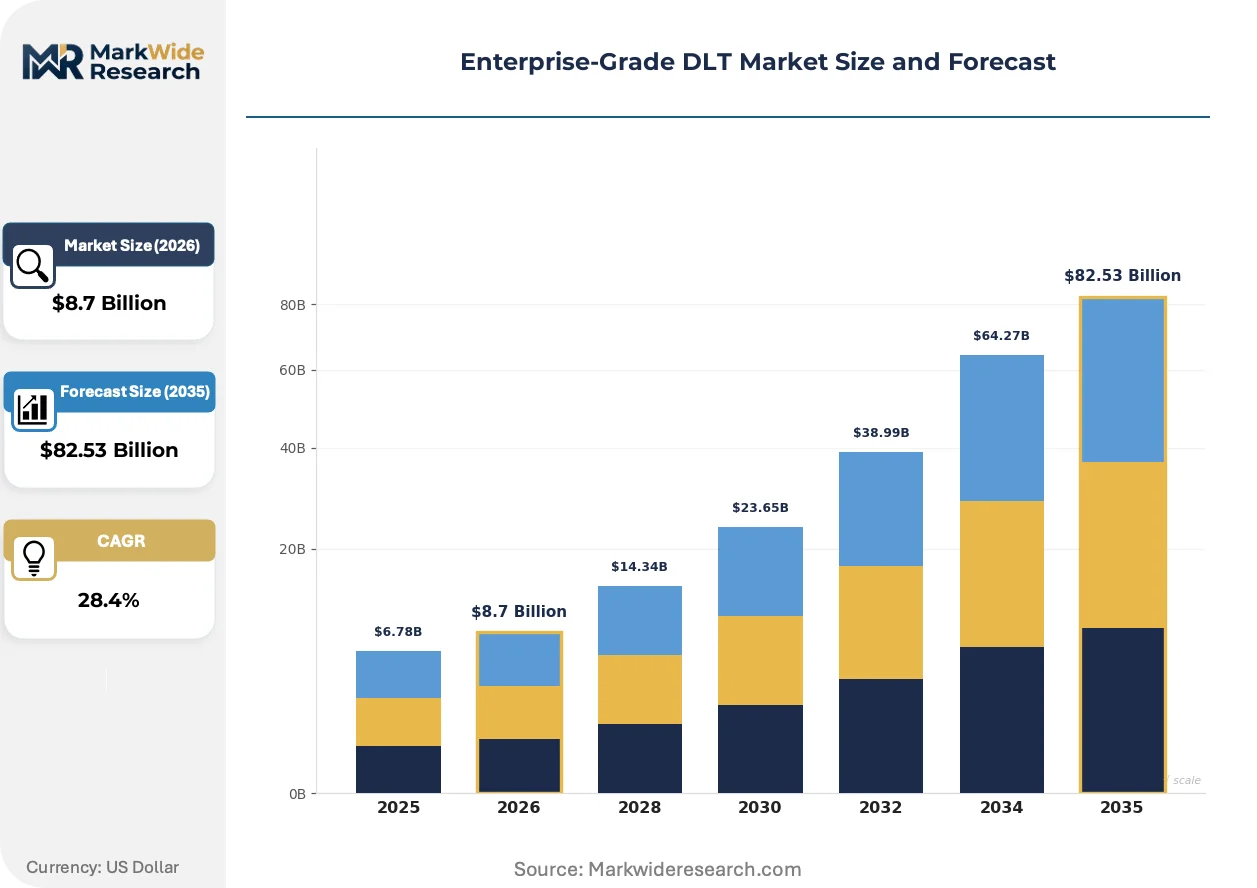
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Financial Services, Supply Chain, Healthcare, Telecommunications Technology: Smart Contracts, Permissioned Blockchain, Consortium Blockchain, Tokenization Application: Identity Verification, Secure Transactions, Data Sharing, Auditing |
| Companies Covered | Hyperledger Experts, PixelPlex, ConsenSys, Wildnet Edge, Innowise Group, LeewayHertz, Altoros, HashCash Consultants, Kaleido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise-Grade DLT Market Shifts & Advancements
Enterprise distributed ledger architectures are converging with privacy-enhancing technologies and cloud-native deployment models, reshaping how regulated entities approach multi-party data coordination without surrendering cryptographic key custody.
Confidential computing enclaves are miniaturizing the trusted execution environment footprint required for secure key management, enabling financial services firms to deploy validator nodes on commodity cloud infrastructure without hardware security module dependencies. Major payment processors are adopting these architectures for cross-border remittance corridors. This compression of hardware requirements is miniaturizing the capital barrier for mid-tier banks seeking network participation.
The EU AI Act imposes algorithmic accountability requirements on automated decision systems, directly shaping how smart contract oracles integrate with permissioned ledgers for credit scoring and trade finance workflows. Financial institutions must now document training data provenance and model drift monitoring. German and Singaporean banking regulators are issuing supplementary guidance on machine learning auditability standards.
Enterprise buyers are consolidating vendor relationships around full-stack platform providers capable of delivering smart contract development, node operations, and regulatory reporting from unified service agreements. Systems integrators are displacing point-solution specialists in procurement evaluations. This concentration pattern is most visible among United States asset managers restructuring their digital asset custody technology stacks.
Enterprise-Grade DLT Market Segmentation
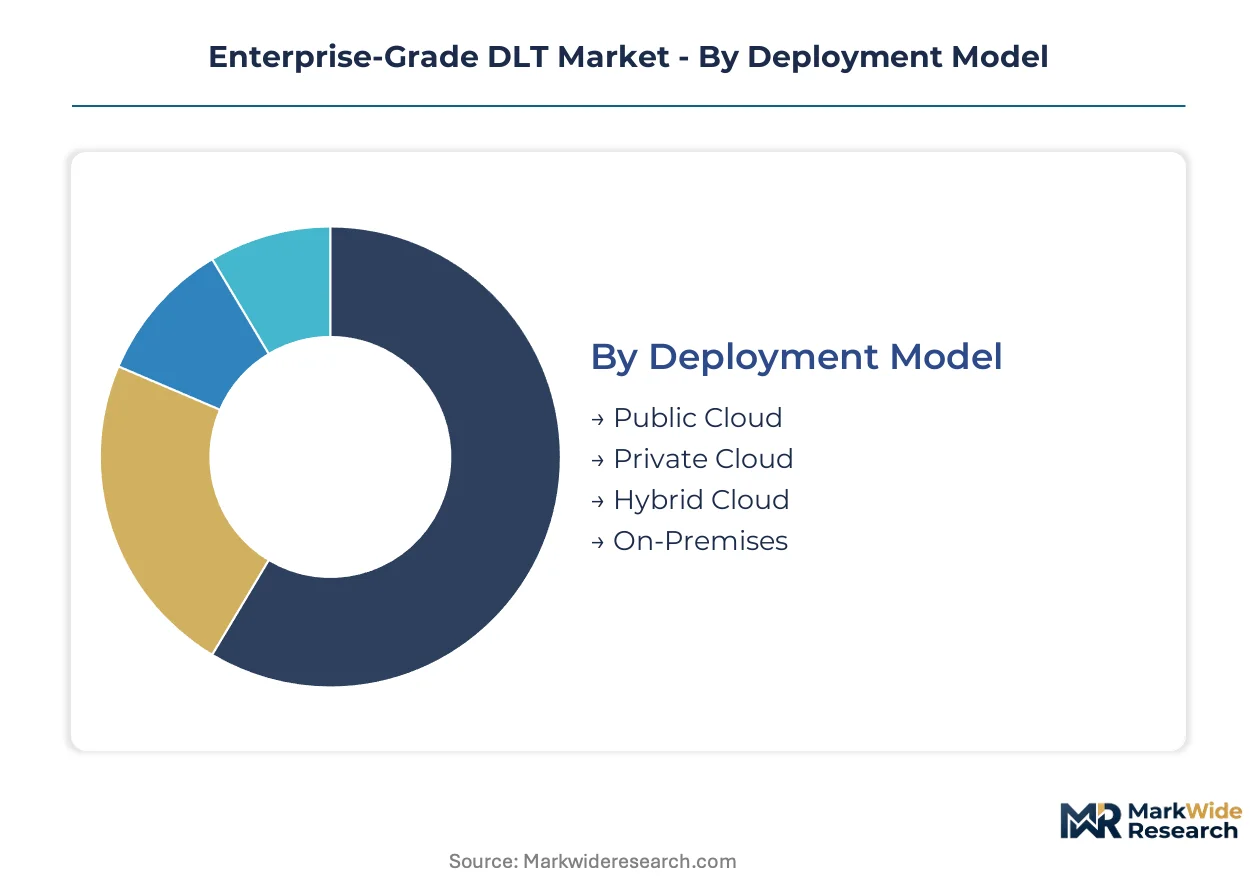
Enterprise-grade DLT procurement decisions hinge on deployment sovereignty, regulatory jurisdiction, and throughput requirements. Segmentation reveals where infrastructure investments concentrate versus where experimental budgets flow.
Deployment Model:
Private cloud configurations face acute substitution pressure from hybrid architectures as banks seek elasticity without surrendering key custody.
- Public Cloud:Validator nodes run on hyperscaler infrastructure with shared tenancy. Demand concentrates among fintech startups in Singapore seeking rapid network provisioning without capital expenditure.
- Private Cloud:Dedicated infrastructure isolates consensus traffic within single-tenant environments. German banking consortia prioritize this model to satisfy GDPR data residency mandates for cross-border settlement workflows.
- Hybrid Cloud:Sensitive cryptographic operations remain on-premises while compute-intensive validation leverages elastic cloud capacity. United States asset managers adopt this architecture to balance SEC audit trail requirements with infrastructure cost efficiency.
- On-Premises:Complete hardware ownership eliminates third-party access to signing keys. Central banks in wholesale CBDC pilots favor sovereign infrastructure for systemic payment rail prototypes.
Private cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
End User:
Technology maturity varies sharply across verticals, with financial services pulling ahead of healthcare by three to five years in production deployments.
- Financial Services:Permissioned ledgers automate correspondent banking reconciliation and trade finance documentation. United States and Singaporean institutions drive demand for atomic settlement rails eliminating multi-day clearing delays.
- Supply Chain:Immutable custody chains track pharmaceutical provenance and luxury goods authenticity. IoT sensor integration creates tamper-evident records from manufacturing through last-mile delivery.
- Healthcare:Patient consent management and clinical trial data integrity represent primary use cases. HIPAA compliance requirements slow deployment timelines relative to less regulated sectors.
- Telecommunications:Roaming settlement and spectrum license management emerge as early applications. Inter-carrier billing reconciliation benefits from cryptographic finality.
Financial services anchors the volume base while supply chain gains share at the steepest rate.
Technology:
Smart contract architectures face margin compression from no-code deployment tools lowering development barriers for mid-tier enterprises.
- Permissioned Blockchain:Validator membership requires cryptographic credentials issued by network governance bodies. Enterprise demand concentrates in United States and Germany for compliance with data sovereignty regulations.
- Tokenization:Asset digitization on distributed ledgers enables fractional ownership and programmable settlement. Regulatory sandboxes in Singapore and Germany permit pilot programs for securities tokenization.
- Smart Contracts:Self-executing code automates multi-party agreements without intermediary enforcement. Formal verification methodologies extend development cycles for complex financial instruments.
- Consortium Blockchain:Pre-selected node operators share infrastructure costs and governance responsibilities. Asian banking consortia dominate cross-border remittance implementations.
Permissioned blockchain anchors the volume base while tokenization gains share at the steepest rate.
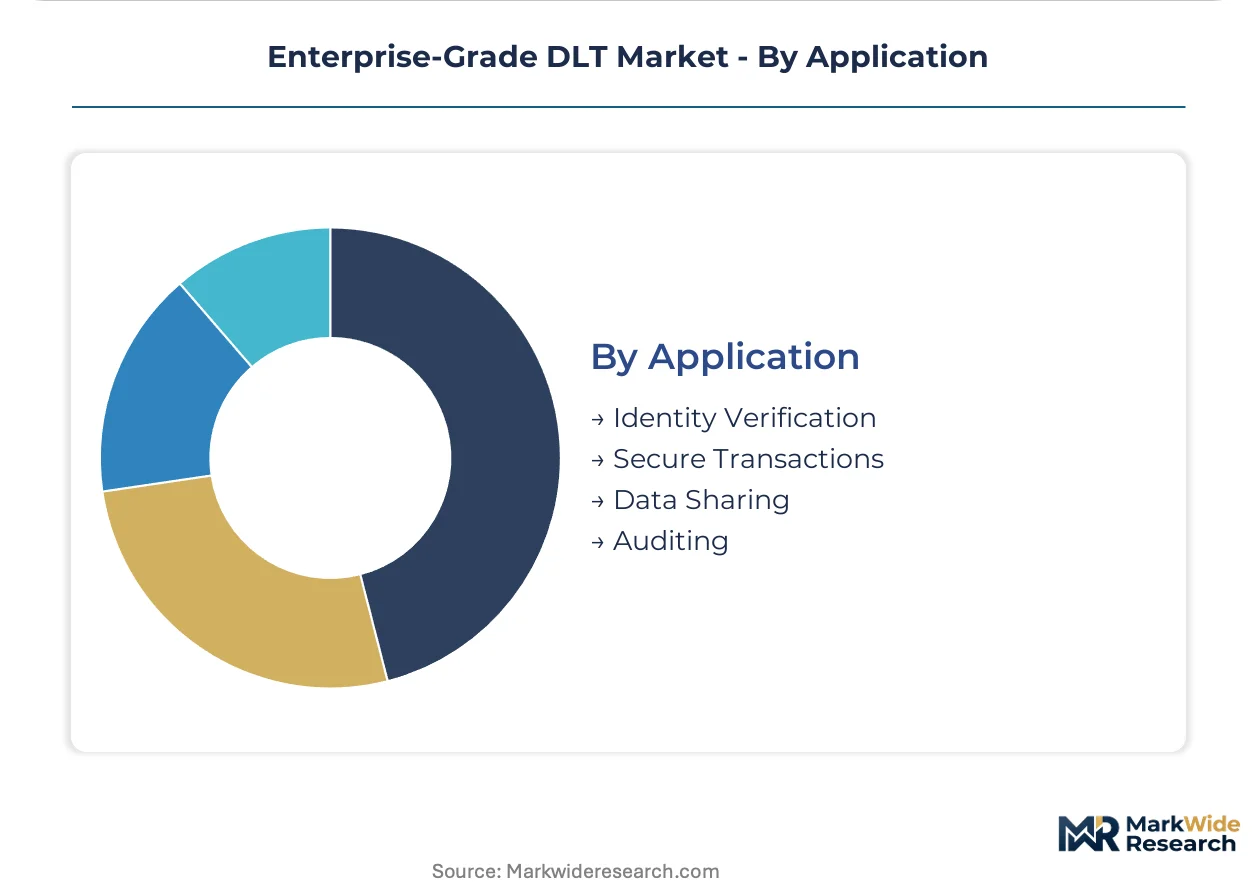
Application:
Identity verification commands premium pricing due to regulatory mandates, while data sharing applications struggle with interoperability standardization.
- Secure Transactions:Cryptographic finality eliminates settlement risk in high-value transfers. Wholesale CBDC pilots across Asian banking networks generate demand for atomic settlement capabilities.
- Identity Verification:Self-sovereign credential architectures reduce Know-Your-Customer duplication across financial institutions. EU GDPR and emerging digital identity frameworks shape technical specifications.
- Data Sharing:Zero-knowledge proof integration enables selective disclosure without exposing underlying records. Pharmaceutical supply chains leverage this capability for competitive confidentiality.
- Auditing:Immutable transaction trails satisfy SEC and CFTC examination requirements. Automated compliance reporting reduces manual reconciliation overhead.
Secure transactions anchors the volume base while identity verification gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German banking consortia export permissioned ledger infrastructure to Singaporean wholesale CBDC pilots, creating a trans-Eurasian corridor for atomic settlement technology.
United States
SEC examination requirements and CFTC digital asset jurisdiction drive demand for auditable consensus mechanisms. The IRA's clean energy provisions indirectly shape data center location decisions for validator networks. New York and Chicago financial centers host the densest concentration of enterprise DLT deployments for cross-border settlement automation.
Germany
German banking consortia prioritize GDPR-compliant data residency for cross-border settlement workflows. The EU AI Act imposes algorithmic accountability requirements on automated decision systems integrated with permissioned ledgers. Frankfurt's financial infrastructure cluster anchors wholesale CBDC pilot programs testing atomic settlement rails.
Singapore
Wholesale CBDC interoperability programs generate demand for atomic settlement infrastructure across Asian banking networks. The Monetary Authority of Singapore's regulatory sandbox permits securities tokenization pilots on permissioned infrastructure. Singapore's fintech corridor attracts rapid network provisioning demand from capital-light startups seeking validator nodes without hardware expenditure.
China
MEE dual carbon goals and emissions disclosure mandates drive transparent tracking systems for supply chain provenance. SAMR standardization efforts shape technical specifications for consortium blockchain deployments in trade finance. The Yangtze River Delta industrial cluster concentrates pilot programs for pharmaceutical custody chain verification.
Switzerland
Swiss banking secrecy traditions converge with cryptographic privacy techniques for institutional-grade asset custody. FINMA guidance on digital asset classification creates compliance-driven demand for immutable transaction trails. Zurich and Geneva financial centers host specialized engineering talent for formal verification methodologies in smart contract security.
Enterprise-Grade DLT Market Competitive Landscape
Listed technology conglomerates compete with private specialists across infrastructure tooling and full-stack service delivery. The vendor base organizes into three tiers: hyperscale cloud providers offering validator hosting, specialized consultancies delivering end-to-end deployment, and open-source foundations governing protocol standards. Strategic differentiation concentrates on M&A activity absorbing point-solution providers and geographic expansion into regulatory sandbox jurisdictions.
Within the Ethereum-compatible tooling tier, ConsenSys and LeewayHertz exemplify divergent positioning strategies. ConsenSys occupies a position anchored in protocol-layer infrastructure for permissioned network deployment. LeewayHertz sits within the full-stack implementation archetype spanning smart contract architecture through operational node management. HashCash Consultants represents the cross-border remittance specialization cluster dominating Asian banking consortium implementations.
| Leading Market Players |
|---|
| Hyperledger Experts |
| PixelPlex |
| ConsenSys |
| Wildnet Edge |
| Innowise Group |
| LeewayHertz |
| Altoros |
| HashCash Consultants |
| Kaleido |
| Others |
Supply & Pricing Matrix
Confidential computing enclaves replacing hardware security modules as the preferred key custody architecture simultaneously shift validator node supply toward commodity cloud regions and compress infrastructure pricing tiers for mid-tier banking participants.
Pricing Analysis
Next-generation zero-knowledge proof implementations command substantial premiums over current-generation permissioned ledger deployments, while legacy Byzantine fault-tolerant configurations face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates formally verified smart contract architectures from template-based deployments and open-source tooling. Cost compression in standard-tier node operations is intensifying because hyperscaler validator hosting commoditizes consensus infrastructure. Fintech startups in Singapore exhibit highest price sensitivity due to capital constraints, while German banking consortia prioritize certification-grade deployments regardless of cost.
Supply Chain Analysis
Inventory lead times for specialized cryptographic hardware extend deployment schedules as demand outpaces trusted execution environment manufacturing capacity. Validator node supply concentrates in the United States, Singapore, and Germany where hyperscaler infrastructure and regulatory clarity converge. Consensus protocol development draws from academic cryptography research, open-source foundation governance, and enterprise systems integration talent pools. Single-source vulnerability in cloud infrastructure dependencies creates systemic resilience exposure for cross-border settlement networks. Distribution runs through systems integrators consolidating vendor relationships around full-stack platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise-grade DLT procurement is approaching a platform-economics inflection as wholesale CBDC interoperability standards determine which ledger infrastructures achieve systemic payment rail status.
For Market Incumbents: Fortify market position through formal verification tooling investments that address smart contract security auditing bottlenecks. Acquire specialized cryptography talent pools concentrated in Swiss and German academic clusters. Defend against systems integrators displacing point-solution specialists by embedding regulatory reporting capabilities directly into protocol-layer infrastructure.
For New Entrants and Emerging Players: Differentiate on carbon credit verification workflows where MEE dual carbon goals and EU Green Deal mandates create compliance-driven demand with limited incumbent specialization. Target supply chain provenance implementations for pharmaceutical verticals in China where IoT sensor integration requirements outstrip current vendor capabilities. Pursue regulatory sandbox admission in Singapore as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Capital is best deployed toward full-stack implementation specialists with demonstrated production deployments across multiple consensus mechanisms. Long-term viability over the coming decade hinges on CBDC interoperability certification rather than isolated network scale. Monitor central bank pilot program vendor selections as the critical inflection signal for infrastructure consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Integration | GDPR-compliant data sharing enables pharmaceutical supply chain confidentiality without exposing competitive records. |
| Hybrid Cloud Node Deployment | Elastic compute capacity balances SEC audit trail requirements with infrastructure cost efficiency for asset managers. |
| Formal Verification Tooling Investment | Smart contract security auditing compression accelerates development cycles for complex financial instruments. |
| Wholesale CBDC Interoperability Certification | Atomic settlement rail status determines which ledger infrastructures achieve systemic payment rail adoption. |
| Regulatory Sandbox Market Entry | MAS and BaFin pilot programs provide controlled environments for securities tokenization proof-of-concept validation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with distributed systems engineers, regulatory compliance officers at financial institutions, smart contract auditors, and cloud infrastructure procurement leads. Secondary validation drew from SEC examination guidelines, EU AI Act implementation drafts, MAS regulatory sandbox disclosures, and ISO standardization committee proceedings. Bottom-up deployment counts across permissioned networks were triangulated against top-down infrastructure spending estimates from hyperscaler capex disclosures.
Across the analysis window, the forecasting framework modeled deployment value by technology segment, end-user vertical, and geographic regulatory cluster. Segmentation dimensions included consensus mechanism architecture, data residency compliance tier, and CBDC interoperability readiness. CAGRs were derived from slope-intercept modeling of historical adoption curves adjusted for regulatory mandate acceleration effects. Forecast inputs incorporated validator node geographic concentration indices and smart contract formal verification tooling availability.
The analysis sits within stated boundaries; outcomes outside wholesale CBDC pilot program expansion trajectories or MiCA enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory sandbox admission rates and cryptographic talent supply elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain in Sports Market