
 China Two Wheeler Market | 2026-2036
China Two Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
China Two Wheeler Market Outlook
Skilled battery-system engineering talent is rotating toward Zhejiang and Jiangsu provinces, tightening labor availability for incumbents elsewhere. Yadea Technology Group leverages its vertical cell-pack integration to dominate premium e-bike output. Zongshen Industrial Group anchors gasoline motorcycle production through its Chongqing manufacturing base. Jiangsu Xinri E-Vehicle Co. Ltd. specializes in fleet-optimized models for delivery contractors.
Two-wheelers encompass motorized and electric personal transport vehicles with curb weights below 400 kg, typically powered by internal combustion engines from 50cc to 500cc or lithium-ion battery packs from 48V to 72V, designed for urban commuting and last-mile logistics. The e-bike segment leads unit volume as municipal authorities restrict gasoline motorcycle registration in tier-one cities. Scooters command margin concentration in the 126-250cc engine capacity band where Wuyang-Honda Motors competes. Delivery services as an end user category is displacing personal use as the fastest-growing demand pool.
MIIT production qualification rules and GB/T electric vehicle safety standards shape product certification timelines and battery thermal management requirements. The national dual carbon goals from MEE accelerate provincial subsidy phase-outs for lead-acid models. Stakeholders must monitor NMPA-equivalent conformity assessment shifts as local governments tighten market access for non-compliant imports.
Market Dynamics
MIIT production qualification rules and GB/T electric vehicle safety standards are compressing certification timelines while provincial dual carbon mandates from MEE accelerate subsidy phase-outs for lead-acid models, forcing manufacturers toward lithium-ion architectures and integrated battery-pack engineering.
Growth Catalysts
- Delivery fleet electrification:Last-mile logistics operators are expanding procurement of fleet-optimized e-bikes as municipal authorities in tier-one cities restrict gasoline motorcycle registration, creating sustained demand pull from courier and food-delivery contractors.
- GB standards compliance:Tightening GB/T electric vehicle safety thresholds are raising barriers for non-compliant imports, protecting domestic manufacturers who have already invested in thermal management and battery system certification.
- Jiangsu-Zhejiang manufacturing concentration:Skilled battery-system engineering talent is rotating toward these coastal provinces, deepening technical capabilities and supplier density for electrified two-wheeler production.
Market Restraints
- Lithium-ion cell cost volatility:Raw material input fluctuations for cathode and electrolyte components compress margin predictability for e-bike assemblers lacking captive cell supply.
- Provincial subsidy phase-out:MEE dual carbon goals are eliminating purchase incentives for lead-acid models faster than lithium-ion cost curves can compensate, stranding price-sensitive consumer segments.
- Gasoline motorcycle registration bans:Tier-one city restrictions on ICE two-wheeler licensing are eliminating a revenue stream for manufacturers without parallel e-bike certification, forcing portfolio reconfiguration.
Strategic Opportunities
- Battery-swapping infrastructure:Delivery contractors in dense urban corridors are adopting subscription-based energy models that reduce upfront vehicle costs and extend fleet utilization rates.
- 126-250cc scooter premiumization:Wuyang-Honda Motors and competitors can defend margin concentration in this displacement band where personal mobility users seek performance differentiation from restricted e-bike alternatives.
- Vertical cell-pack integration:Manufacturers with backward integration into lithium-ion cell production capture thermal management IP and procurement cost advantages as GB standards tighten.
Industry Challenges
- Battery-system engineering talent scarcity:Electrochemical and thermal management specialists are concentrating in Jiangsu and Zhejiang, forcing inland competitors to relocate R&D functions or accept recruitment premiums.
- MIIT certification timeline compression:Production qualification rules are reducing time-to-market windows for new model introductions, requiring parallel rather than sequential testing protocols.
- Legacy lead-acid supply chain reconfiguration:Manufacturers must unwind established supplier relationships and retool assembly lines for lithium-ion architectures while managing stranded component inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Two Wheeler Market |
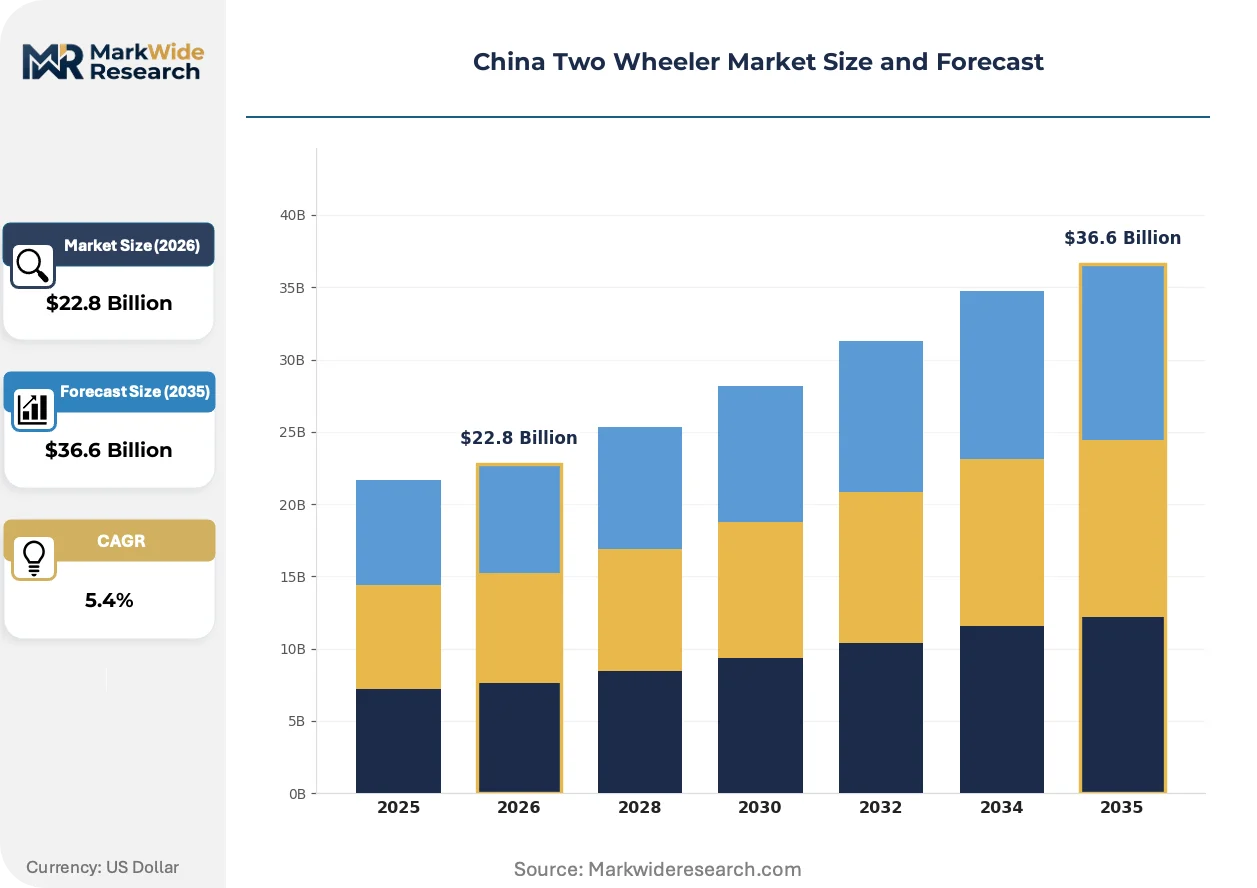
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorcycles, Scooters, E-bikes, Mopeds End User: Personal Use, Delivery Services, Shared Mobility, Taxi Services Engine Capacity: Less than 125cc, 126-250cc, 251-500cc, Above 500cc Distribution Channel: Online Retail, Dealerships, Direct Sales, Marketplaces |
| Companies Covered | Jiangmen Grand River Group Co. Ltd., Jiangsu Xinri E-Vehicle Co. Ltd., Loncin Motor Co. Ltd., Luoyang Northern Enterprises Group Co. Ltd., Wuyang-Honda Motors (Guangzhou) Co. Ltd., Sundiro Honda Motorcycle Co. Ltd., Zongshen Industrial Group Co. Ltd., Yadea Technology Group, Zhejiang Luyuan Electric Vehicle Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Two Wheeler Market Strategic Shifts
Electrification architectures are fragmenting across voltage classes and thermal management approaches as delivery fleets and personal users diverge in performance requirements and total-cost priorities.
Modular battery pack designs are decomposing traditional fixed-cell configurations into swappable, serviceable sub-assemblies. Delivery contractors in Shanghai and Shenzhen are adopting 48V-72V standardized formats at scale. This architecture is decomposing manufacturer control over after-sales revenue streams as third-party swapping networks capture energy-service margins.
MIIT production qualification rules and GB/T electric vehicle safety standards are mandating cell-level thermal runaway containment and system-level abuse testing. These requirements are extending development cycles by six to twelve months for non-integrated assemblers. The 126-250cc scooter segment faces the steepest compliance burden as manufacturers dual-certify ICE and electric variants.
Courier and food-delivery platforms are consolidating vehicle procurement through direct manufacturer partnerships rather than dealer networks. Meituan and Ele.me are specifying fleet-optimized models with reinforced frames and extended-range battery configurations. This channel consolidation is most visible in Hangzhou and Chengdu where municipal authorities coordinate fleet electrification targets with platform compliance incentives.
China Two Wheeler Market Segmentation
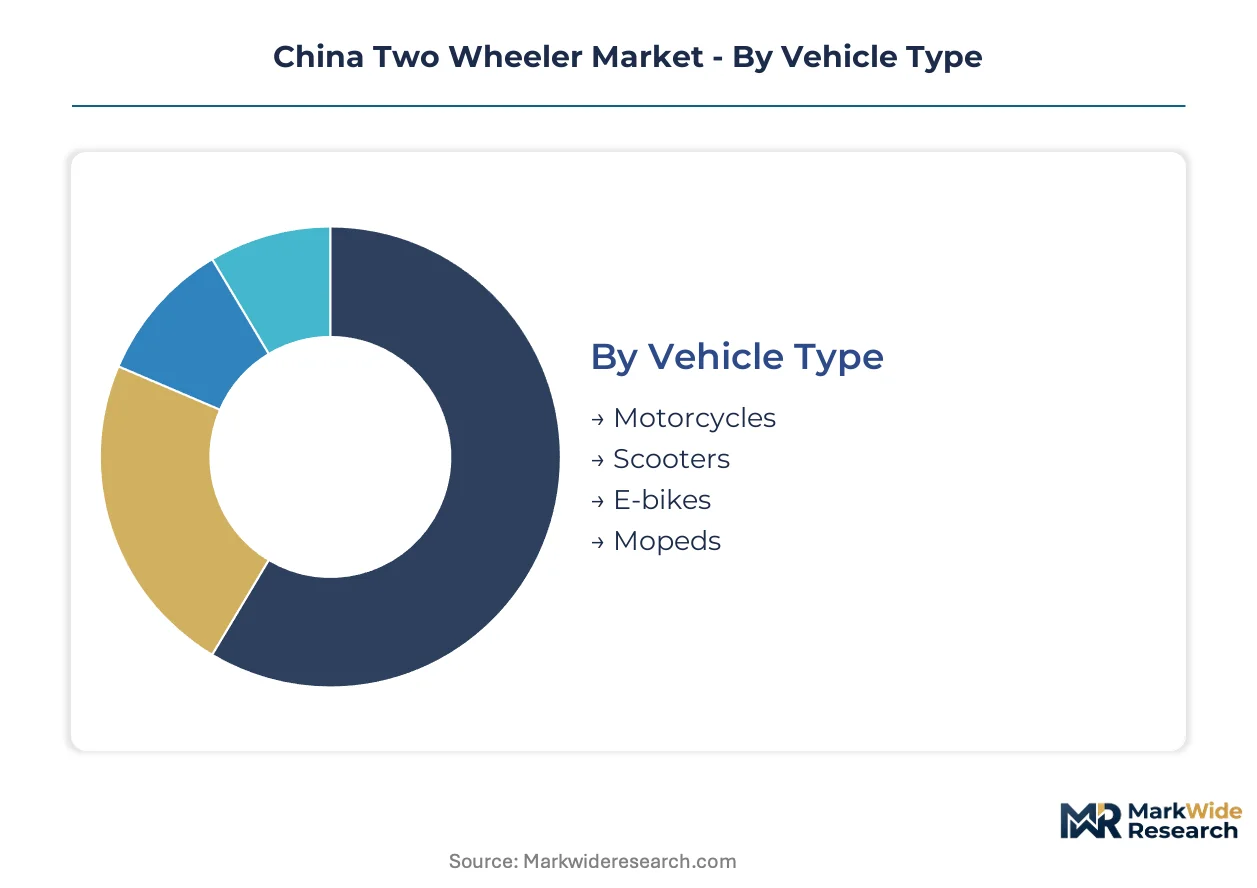
Segmentation in the China two-wheeler market reveals how electrification mandates and delivery fleet procurement are reshaping volume distribution across vehicle architectures. Understanding these splits exposes where MIIT certification investments concentrate and which channels are capturing fleet purchasing power.
Vehicle Type:
E-bikes and gasoline motorcycles diverge sharply in geographic concentration, with electrified models dominating Jiangsu-Zhejiang domestic output while ICE variants serve export markets and inland provinces.
- Motorcycles:Internal combustion platforms from 50cc to 500cc power these vehicles, with Chongqing manufacturers anchoring production for western China and Southeast Asian export corridors. Demand is compressing in tier-one cities as municipal registration bans eliminate personal-use licensing, forcing portfolio pivots toward rural and export markets.
- E-bikes:Lithium-ion and lead-acid configurations from 48V to 72V define this segment, capturing the bulk of replacement demand in Beijing, Shanghai, and Shenzhen where gasoline motorcycle restrictions are strictest. Fleet procurement from Meituan and Ele.me is displacing personal-use volume as the primary demand driver.
- Scooters:Step-through architectures span both ICE and electric powertrains, serving urban commuters seeking weather protection and storage capacity.
- Mopeds:Low-speed electric and gasoline variants under 50cc address price-sensitive riders and secondary-city mobility needs.
Motorcycles command the established base. The steepest expansion runs through E-bikes.
End User:
Cost tier differentiation separates fleet purchasers seeking total-cost optimization from individual buyers prioritizing upfront affordability.
- Delivery Services:Courier and food-delivery contractors operate fleet-optimized vehicles with reinforced frames, extended-range battery packs, and modular swapping compatibility. Platform procurement consolidation through direct manufacturer partnerships is bypassing traditional dealer networks in Hangzhou and Chengdu.
- Personal Use:Individual commuters and households purchase through retail channels, with demand fragmenting across premium lithium-ion models and price-driven lead-acid alternatives.
- Shared Mobility:Dockless and station-based rental operators deploy durable, connected vehicles with telematics integration for asset tracking.
- Taxi Services:Motorcycle taxi and three-wheeler operators in lower-tier cities utilize high-utilization ICE platforms for extended daily range requirements.
Personal Use anchors volume historically. Delivery Services is gaining share fastest.
Engine Capacity:
Margin concentration varies across displacement bands, with mid-capacity scooters defending profitability while electric architectures disrupt volume distribution.
- 126-250cc:Single-cylinder and parallel-twin gasoline engines in this band deliver performance differentiation for personal mobility users restricted from registering larger motorcycles in urban centers. Wuyang-Honda Motors and domestic competitors defend margin concentration here as tier-one city riders seek alternatives to speed-limited e-bikes.
- Less than 125cc:Small-displacement commuter motorcycles and mopeds serve rural markets and price-sensitive urban segments where e-bike range limitations constrain adoption.
- 251-500cc:Mid-size motorcycles target enthusiast riders and regional export markets with higher performance requirements.
- Above 500cc:Large-displacement premium motorcycles serve recreational and touring segments with limited domestic volume but strong export orientation.
Less than 125cc retains the broadest installed base. The 126-250cc band is climbing the fastest on value terms.
Distribution Channel:
Supply concentration in manufacturing clusters shapes channel efficiency, with proximity to Jiangsu-Zhejiang production centers favoring direct and marketplace models.
- Direct Sales:Fleet operators and shared mobility providers negotiate volume contracts directly with manufacturers, capturing pricing advantages and custom specification capabilities unavailable through retail channels.
- Dealerships:Physical retail networks handle personal-use sales, after-sales service, and battery maintenance for individual consumers.
- Online Retail:E-commerce platforms facilitate comparison shopping and configuration selection, with delivery logistics managed through manufacturer partnerships.
- Marketplaces:Third-party platforms aggregate inventory from multiple brands, serving price-sensitive buyers in lower-tier cities with limited dealer penetration.
Dealerships maintain the deepest geographic coverage. Direct Sales is expanding most quickly as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT production qualification rules and GB standards anchor the regulatory framework across Chinese provinces, creating differentiated compliance burdens that reshape manufacturing concentration and fleet procurement patterns.
Yangtze River Delta
Jiangsu and Zhejiang provinces concentrate battery-system engineering talent and electrified two-wheeler output. Municipal authorities in Hangzhou and Nanjing enforce strict gasoline motorcycle registration bans, accelerating fleet electrification for Meituan and Ele.me contractors. Yadea Technology Group leverages vertical cell-pack integration from its Zhejiang base to dominate premium e-bike production.
Pearl River Delta
Guangdong province hosts Wuyang-Honda Motors and Sundiro Honda Motorcycle joint ventures serving domestic and Southeast Asian export corridors. Shenzhen and Guangzhou municipal governments coordinate delivery fleet electrification targets with platform compliance incentives. The region balances ICE scooter production for personal mobility users seeking alternatives to speed-limited e-bikes.
Sichuan-Chongqing
Chongqing anchors gasoline motorcycle manufacturing through Zongshen Industrial Group's western China production base. Inland provinces maintain less restrictive ICE registration policies, preserving demand for rural and export-oriented output. The municipality's automotive supplier ecosystem feeds component flows to two-wheeler assemblers.
Beijing-Tianjin-Hebei
The capital region enforces the strictest gasoline motorcycle registration prohibitions among tier-one city clusters. Delivery contractors operate exclusively electrified fleets under municipal fleet electrification mandates. Procurement consolidation through direct manufacturer partnerships bypasses traditional dealer networks.
Shandong Peninsula
Qingdao and Jinan manufacturing bases serve northern China replacement demand with cost-optimized lead-acid and entry lithium-ion configurations. Provincial dual carbon mandates from MEE accelerate subsidy phase-outs faster than coastal provinces, stranding price-sensitive consumer segments.
China Two Wheeler Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated cell producers commanding thermal management IP while scale assemblers compete on procurement efficiency. The vendor base stratifies across three tiers: premium integrated manufacturers, mid-market fleet specialists, and price-driven commodity assemblers. Dominant competitive moves include backward integration into lithium-ion cell production and direct platform partnerships that disintermediate dealer networks.
Among Jiangsu-based electrified specialists, Jiangsu Xinri E-Vehicle Co. Ltd. occupies a position within the fleet-optimized tier, while Zhejiang Luyuan Electric Vehicle Co. Ltd. exemplifies the coastal manufacturing concentration. Zongshen Industrial Group anchors the gasoline motorcycle archetype from its Chongqing base. These three represent the structural divergence between electrified and ICE-dependent positioning.
| Leading Market Players |
|---|
| Jiangmen Grand River Group Co. Ltd. |
| Jiangsu Xinri E-Vehicle Co. Ltd. |
| Loncin Motor Co. Ltd. |
| Luoyang Northern Enterprises Group Co. Ltd. |
| Wuyang-Honda Motors (Guangzhou) Co. Ltd. |
| Sundiro Honda Motorcycle Co. Ltd. |
| Zongshen Industrial Group Co. Ltd. |
| Yadea Technology Group |
| Zhejiang Luyuan Electric Vehicle Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion cell substitution for lead-acid architectures is redrawing procurement geography toward Jiangsu-Zhejiang clusters while compressing margin structures for assemblers lacking captive cathode supply. MIIT production qualification rules and MEE dual carbon mandates simultaneously elevate certification costs and accelerate subsidy phase-outs, forcing price recalibration across battery chemistry tiers.
Pricing Analysis
Coastal Zhejiang commands price premiums over inland Chongqing production by fifteen to twenty percent on equivalent lithium-ion configurations. Three-tier pricing structure across premium integrated, mid-market fleet-optimized, and economy lead-acid levels separates Yadea's vertical cell-pack models from Xinri's fleet specialists and Shandong commodity assemblers. Pricing pressure stems from raw material volatility in cathode and electrolyte inputs that compresses assembler margins without upstream integration. Delivery contractors exhibit lowest price sensitivity due to total-cost optimization focus, while personal-use buyers in Shandong and northern provinces face stranding as provincial subsidies vanish faster than lithium-ion cost curves flatten.
Supply Chain Analysis
Inventory cycles for lithium carbonate and electrolyte salts now stretch lead times for non-integrated assemblers by six to eight weeks versus vertically integrated competitors. Cell production concentrates in China, South Korea, and Japan, with cathode precursor processing anchored in Jiangsu and Fujian provinces. Raw material dependencies on Chilean lithium, Indonesian nickel, and Australian spodumene expose assemblers to commodity volatility and maritime logistics chokepoints. Distribution runs through manufacturer-direct fleet contracts for Meituan and Ele.me procurement, bypassing traditional dealer networks in tier-one cities where municipal electrification mandates consolidate channel power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China two-wheeler market is recovering from lead-acid demand collapse as lithium-ion fleet procurement cycles and MIIT certification completion waves create replacement-driven volume expansion.
For Market Incumbents: Shield premium positioning by deepening backward integration into lithium-ion cell production and securing NMPA-equivalent conformity assessment ahead of GB/T safety standard tightening. Defend Jiangsu-Zhejiang manufacturing concentration against talent rotation premiums by co-locating R&D with supplier ecosystems. Prioritize direct platform partnerships with Meituan and Ele.me that disintermediate dealer networks and capture fleet-optimized specification control. For New Entrants and Emerging Players: Anchor in the 126-250cc scooter segment where Wuyang-Honda's dominance leaves white space for electric variants targeting tier-one city riders seeking performance differentiation from speed-limited e-bikes. Target Shandong and northern inland provinces where lead-acid subsidy phase-outs have stranded price-sensitive segments awaiting cost-competitive lithium-ion alternatives. Pursue battery-swapping infrastructure partnerships as the primary go-to-market angle, reducing upfront vehicle costs for delivery contractors through subscription-based energy models. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors vertically integrated cell-pack specialists with MIIT qualification and thermal management IP. Long-term viability over the next decade hinges on regulatory compliance depth rather than scale assembly efficiency. Acquisition targets should demonstrate captive lithium-ion supply, GB/T certification completion, and direct fleet procurement relationships. Monitor NMPA-equivalent conformity assessment timeline shifts as the critical inflection signal for import restriction intensity and domestic manufacturer protection levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Yadea's vertical cell-pack model captures thermal management IP and procurement cost advantages as GB standards tighten. |
| Direct Platform Partnership | Meituan and Ele.me fleet procurement consolidation bypasses dealer networks and locks in volume offtake commitments. |
| Battery-Swapping Infrastructure Deployment | Subscription-based energy models in Shanghai and Shenzhen reduce upfront costs and extend fleet utilization for delivery contractors. |
| MIIT Qualification Acceleration | Parallel testing protocols compress certification timelines as production qualification rules reduce new model introduction windows. |
| Regional Manufacturing Relocation | Jiangsu-Zhejiang talent concentration forces inland competitors to accept recruitment premiums or relocate R&D functions. |
Study Parameters
Initial hypotheses were tested against primary input from battery-system engineering directors, MIIT certification consultants, fleet procurement managers at delivery platforms, and thermal management specialists, then refined against secondary validation from MIIT production qualification filings, GB/T standard revision drafts, MEE provincial subsidy phase-out announcements, and customs trade data on lithium-ion cell imports. Bottom-up vehicle production estimates from Jiangsu and Zhejiang manufacturing clusters were triangulated against top-down demand projections from delivery fleet electrification targets.
Variance decomposition across vehicle type, end-user category, engine capacity band, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume forecasts weighted by lithium-ion cost curve trajectories and MIIT certification completion rates. Key inputs included municipal fleet electrification mandates, provincial dual carbon implementation timelines, and platform procurement consolidation patterns.
Decision-makers should treat outputs as directional under assumptions of continued MIIT qualification tightening and lithium-ion cost parity achievement; material deviation in cathode material pricing or GB standard enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market