
 Child Bike Seats Market | 2026-2036
Child Bike Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Child Bike Seats Market Outlook
Parental engineering talent and pediatric safety expertise is bifurcating the competitive landscape into premium innovators and value-oriented assemblers. Thule Group leverages its Scandinavian design heritage and automotive-grade testing protocols to sustain premium positioning across European and North American channels. Hamax AS anchors its market presence through Norwegian-origin safety credentials and deep rear-mount specialization. Polisport competes on manufacturing scale, drawing from Portuguese plastics molding expertise to occupy mid-tier retail shelves across Southern Europe.
A child bike seat is a rigid or semi-rigid carrier assembly designed for attachment to a bicycle frame, typically incorporating a harness system, lateral impact protection, and weather-resistant shell construction rated for dynamic loads during transit. Its primary commercial purpose is to enable safe family mobility for children aged approximately nine months to five years. Rear mount configurations dominate volume due to universal frame compatibility and superior crash-test performance, while cargo variants represent the fastest-growing structural category as urban parents replace second vehicles with electric-assisted family bicycles. Plastic shell construction leads material share for cost efficiency, though aluminum subframes gain traction in premium tiers where weight reduction commands margin premiums.
EN 14344 governs European child carrier safety requirements, mandating dynamic strength testing and harness retention criteria that filter non-compliant imports from Asian contract manufacturers. The United States CPSC maintains parallel but less prescriptive guidelines, creating a dual-certification burden for brands serving transatlantic distribution. ISO 8098 bicycle frame standards indirectly influence seat mounting geometry, compelling designers to accommodate expanding bottom-bracket and seat-tube dimensional variation. Stakeholders must monitor evolving e-bike weight classifications, as motor-assisted bicycle categories in Germany and the Netherlands are rewriting load-rating assumptions that underpin existing safety margins.
Market Dynamics
Urban millennial parents in car-congested metropolitan areas are forcing manufacturers to redesign load-rating assumptions around electric-assisted family bicycles, compressing development cycles for cargo-compatible seat architectures.
Growth Catalysts
- EN 14344 Certification Mandate:European dynamic strength testing and harness retention criteria filter non-compliant imports, elevating safety-grade manufacturers who maintain in-house crash-test facilities.
- E-bike Weight Classification Rewrite:German and Dutch motor-assisted bicycle categories are expanding permissible payload thresholds, enabling multi-child cargo configurations previously excluded from street-legal operation.
- Plastics Molding Scale Concentration:Portuguese and Southern European injection molding clusters supply cost-efficient shell production to mid-tier retail channels across Iberia and Italy.
Market Restraints
- Dual-Certification Burden:Transatlantic brands face parallel EN 14344 and CPSC guideline compliance costs, compressing margins for sub-scale manufacturers lacking dedicated regulatory affairs teams.
- Aluminum Subframe Input Volatility:Premium tier weight-reduction strategies expose producers to London Metal Exchange aluminum price swings and aerospace-grade alloy supply prioritization.
- Fixed-Rear-Rack Substitution:Frame-integrated child carrier solutions from cargo bicycle OEMs eliminate aftermarket seat demand among electric cargo bike purchasers.
Strategic Opportunities
- Underpenetrated Southern European Cycling Infrastructure:Spanish and Italian municipalities are accelerating protected lane construction, creating first-time family cycling demand in markets historically dominated by recreational sport riding.
- Weather-Resistant Material Convergence:Advanced polymer-ceramic coatings from automotive glazing applications are migrating into shell construction, enabling year-round Nordic and Alpine market penetration.
- Direct-to-Consumer Channel Expansion:Subscription-based fit-assessment services with home installation support bypass traditional brick-and-mortar retail markups in Netherlands and Denmark.
Industry Challenges
- Pediatric Biomechanics Talent Scarcity:Harness system designers with crash-dummy calibration expertise command premium compensation, constraining R&D throughput at mid-cap assemblers.
- E-bike Mounting Geometry Fragmentation:Expanding bottom-bracket and seat-tube dimensional variation under ISO 8098 compels SKU proliferation for frame-attachment hardware.
- Certification Timeline Compression:Evolving CPSC guideline drafts require pre-compliance testing before final rule publication, straining quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Bike Seats Market |
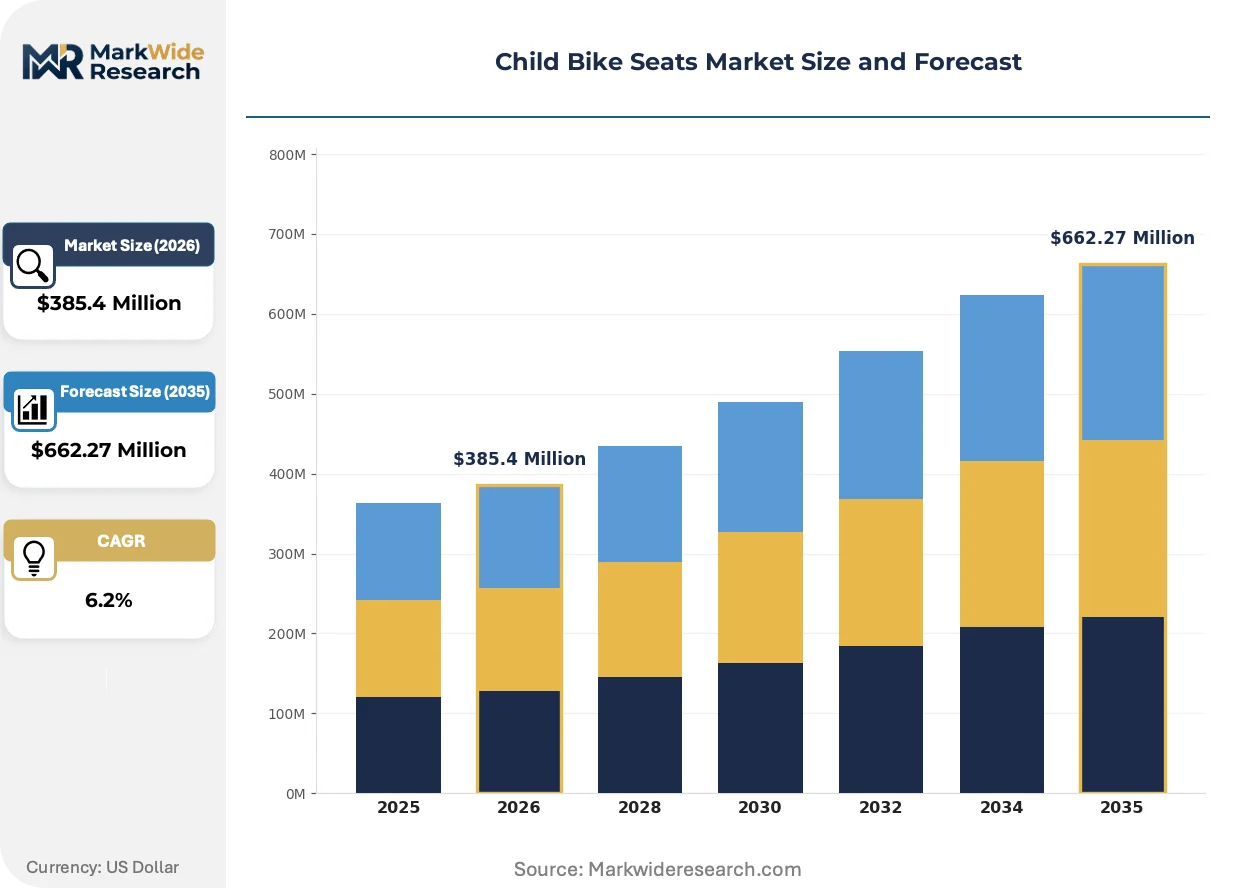
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear Mount, Front Mount, Hybrid, Cargo Material: Plastic, Aluminum, Steel, Fabric Safety Features: Harness System, Padding, Reflective Strips, Safety Belts Weight Capacity: 15 kg, 22 kg, 30 kg, Others |
| Companies Covered | Thule Group, Hamax AS, Polisport, WeeRide, Burley Design, Bellelli, Topeak, BoBike, REI Coop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Bike Seats Market Strategic Shifts
Scandinavian automotive-grade testing protocols are migrating into family mobility products, compressing the performance gap between industrial safety equipment and consumer child carriers.
Aluminum subframe construction is supplanting steel tubing in premium rear-mount configurations. Urban parents operating electric-assisted cargo bicycles specify sub-2.5 kilogram seat weights to preserve handling balance. This materials transition is compressing supplier margins for stamped-steel hardware specialists concentrated in Eastern European tier-two manufacturing.
REACH chemical restrictions on phthalate plasticizers are compelling Portuguese and Spanish molders to reformulate shell polymers ahead of 2025 enforcement windows. Manufacturers with pre-validated bio-based alternatives capture shelf space at German and Dutch specialty retailers. Southern European contract producers lacking reformulation capital face exclusion from Northern European distribution.
Subscription-based seasonal rental programs are displacing outright purchase patterns among Amsterdam and Copenhagen dual-income households. Fleet operators provide certified installation, liability coverage, and end-of-season deep-cleaning services. This service-model pivot concentrates demand among urban parents who reject storage burden and obsolescence risk.
Child Bike Seats Market Segmentation
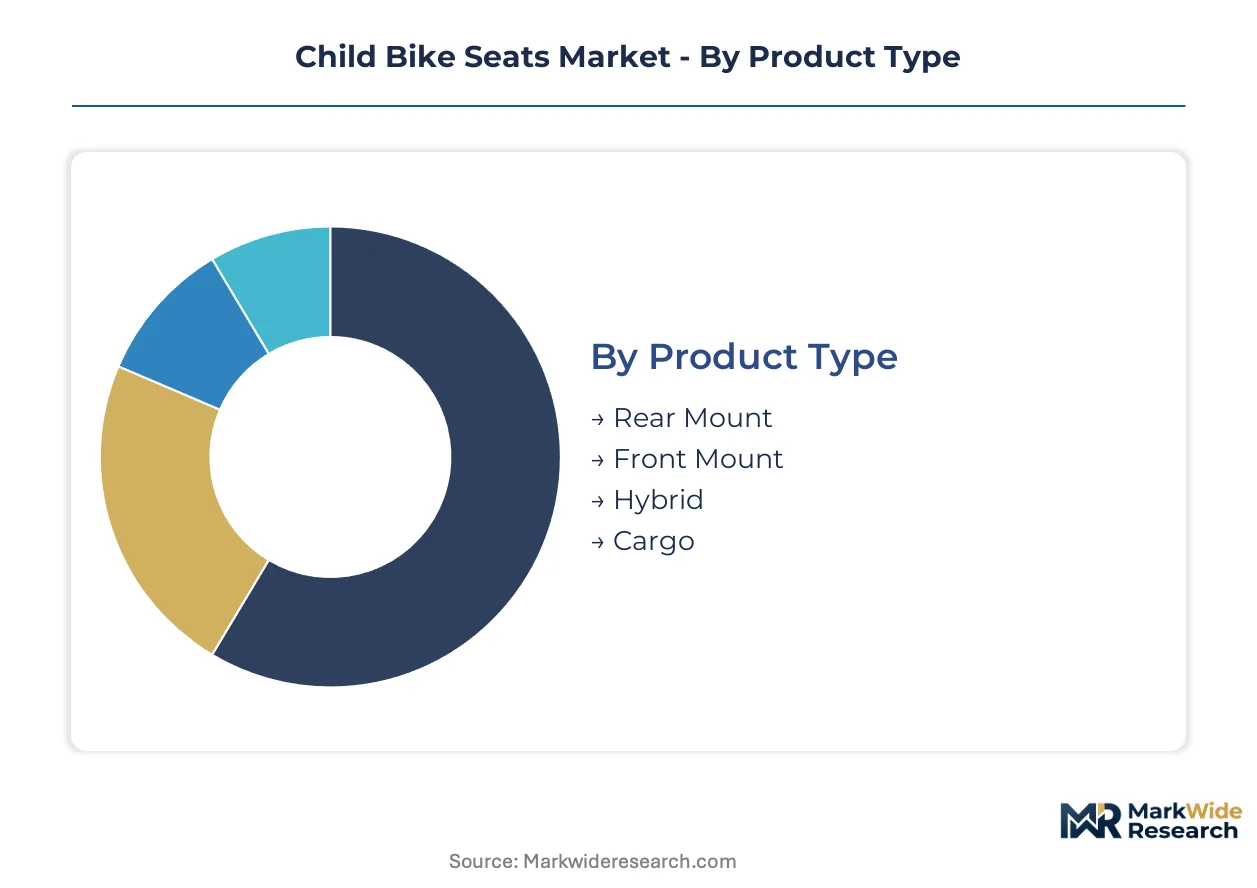
Child bike seat purchasing decisions cluster around mounting geometry, material durability, and safety certification tiers. Manufacturers configure production lines around these dimensions to capture urban family mobility demand across European cycling corridors.
Product Type:
German and Dutch channels drive export volumes for frame-integrated architectures, while domestic Southern European consumption favors universal-fit rear solutions.
- Rear Mount:Universal frame compatibility and superior EN 14344 crash-test performance anchor volume leadership. Demand concentrates in Netherlands and Germany where protected cycling infrastructure supports daily family commuting. Frame-attachment hardware accommodates expanding ISO 8098 bottom-bracket dimensional variation.
- Cargo:Electric-assisted family bicycles in Copenhagen and Amsterdam are rewriting payload assumptions for multi-child configurations. Street-legal operation thresholds under German motor-assisted bicycle categories enable previously excluded load ratings.
- Front Mount:Compact urban storage and parental visibility drive adoption in dense Italian and Spanish city centers.
- Hybrid:Convertible mounting systems capture seasonal recreational users in Alpine and Nordic markets.
Rear Mount commands the established base. The steepest expansion runs through Cargo.
Material:
Cost tier alignment separates premium aluminum subframe producers from volume plastic molders serving mid-tier retail.
- Plastic:Portuguese and Spanish injection molding clusters supply cost-efficient shell production across Iberia and Italy. REACH chemical restrictions on phthalate plasticizers are compelling reformulation ahead of enforcement windows.
- Aluminum:Sub-2.5 kilogram seat weights preserve handling balance on electric-assisted cargo bicycles. London Metal Exchange price volatility and aerospace-grade alloy supply prioritization constrain margin stability.
- Steel:Stamped-steel hardware specialists in Eastern European tier-two manufacturing face margin compression from materials substitution.
- Fabric:Weather-resistant polymer-ceramic coatings from automotive glazing applications enable year-round Nordic penetration.
Plastic dominates unit economics. Aluminum captures the fastest margin expansion.
Safety Features:
Certification grade determines channel access, with EN 14344 dynamic strength testing filtering non-compliant imports from Asian contract manufacturers.
- Harness System:Five-point retention designs with crash-dummy calibrated biomechanics command premium positioning. Pediatric safety expertise scarcity constrains R&D throughput at mid-cap assemblers.
- Padding:Energy-absorbing foam configurations differentiate premium tiers in German specialty retail.
- Reflective Strips:Visibility standards under Dutch street-legal requirements drive specification in Northern European distribution.
- Safety Belts:Simplified two-point systems occupy economy shelves in price-sensitive Southern European markets.
Harness System anchors premium positioning. Padding shows the steepest specification upgrade trajectory.
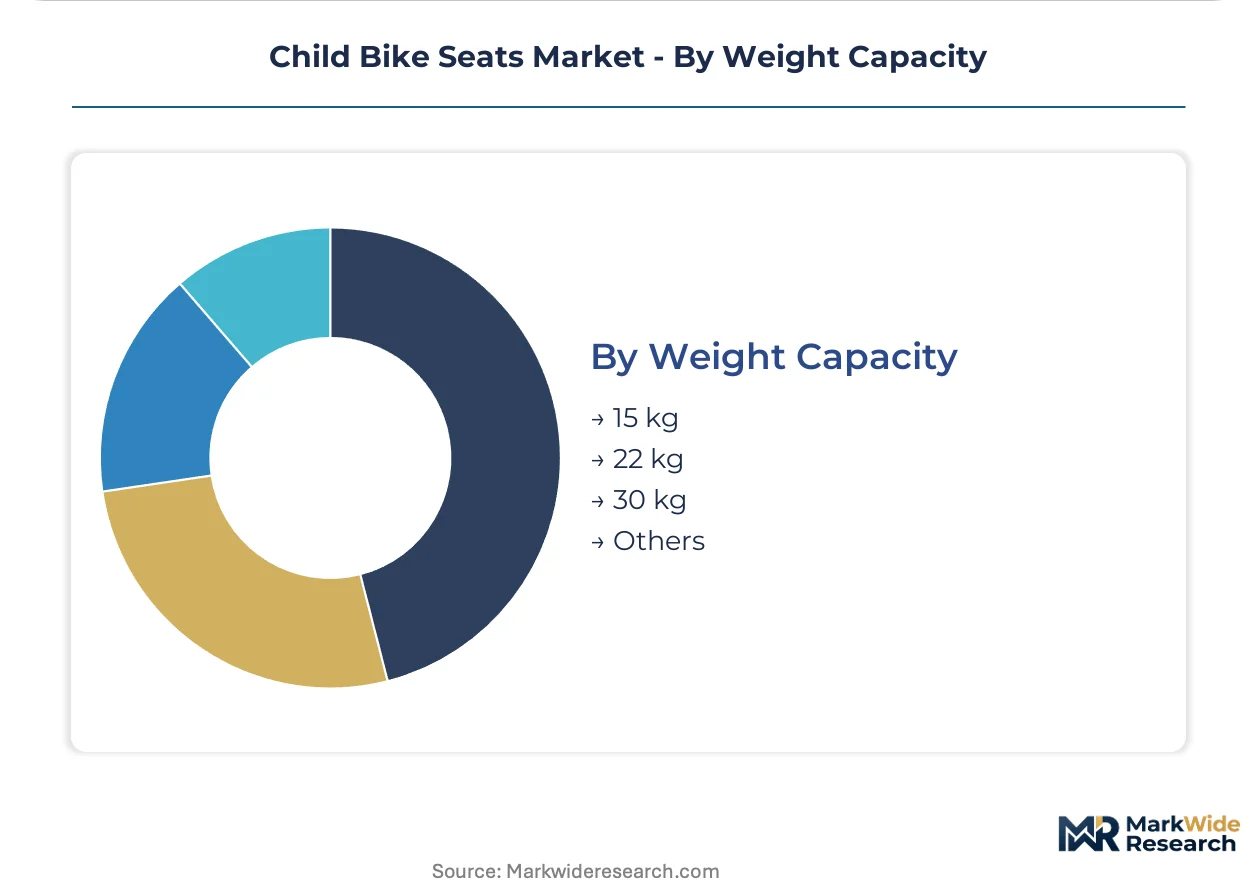
Weight Capacity:
Load-rating assumptions are compressing around electric-assisted bicycle payload thresholds in German and Dutch regulatory frameworks.
- 22 kg:Standard toddler-to-preschool transition rating dominates volume production for nine-month to five-year age windows. Frame-integrated solutions from cargo bicycle OEMs are displacing aftermarket demand at this threshold.
- 30 kg:Multi-child and extended-age configurations align with expanding e-bike permissible payload classifications. Copenhagen and Amsterdam fleet operators specify this rating for subscription-based seasonal rental programs.
- 15 kg:Infant-specific compact designs serve first-time parent segments in dense urban cores.
- Others:Custom commercial and disability-accessible configurations address institutional procurement in Scandinavian municipal fleets.
22 kg maintains the volume base. 30 kg climbs the fastest as family cargo cycling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch parents treat child bike seats as daily transport infrastructure, while Italian and Spanish buyers view them as seasonal recreational equipment. This consumption-mix differential concentrates premium innovation in Northern European cycling corridors and cost-optimized production in Southern European molding clusters.
Germany
Urban millennial parents in Berlin and Munich drive demand for EN 14344-certified rear-mount configurations compatible with electric-assisted cargo bicycles. The KBA motor-assisted bicycle classification system permits expanded payload thresholds for multi-child transport. Manufacturing concentrates in Baden-Württemberg, where automotive-grade testing protocols from Stuttgart's supplier ecosystem migrate into family mobility products.
Netherlands
Amsterdam and Copenhagen fleet operators specify 30 kg load-rated seats for subscription-based seasonal rental programs. Dutch street-legal visibility requirements mandate reflective strip integration across all distribution channels. The Randstad logistics corridor supports direct-to-consumer fit-assessment services with home installation support, bypassing traditional retail markups.
Italy
Dense Milan and Rome city centers favor compact front-mount designs prioritizing parental visibility over crash-test performance. The country's national consumer protection regulator enforces parallel safety marking requirements alongside CE compliance. Injection molding capacity clusters in Veneto supply cost-efficient shell production for price-sensitive domestic consumption and Iberian export.
Spain
Barcelona and Madrid municipalities accelerate protected lane construction, creating first-time family cycling demand in markets historically dominated by recreational sport riding. REACH chemical restrictions on phthalate plasticizers compel Catalan molders to reformulate shell polymers ahead of enforcement windows. Valencia's plastics engineering base captures mid-tier retail shelf space across Southern European distribution.
United States
Coastal metropolitan parents in Seattle and Portland adopt cargo-compatible architectures as electric bicycle adoption accelerates. The CPSC maintains less prescriptive guidelines than EN 14344, creating dual-certification burdens for transatlantic brands. Assembly operations concentrate near West Coast ports to manage inbound component flows from Asian contract manufacturers.
Child Bike Seats Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Scandinavian design houses commanding premium positioning through automotive-grade testing protocols while Portuguese and Spanish molders occupy mid-tier retail through manufacturing scale. The market structures around three archetypes: premium innovators with in-house crash-test facilities, value-oriented assemblers sourcing from contract manufacturers, and fleet-service operators managing subscription-based seasonal rental programs. Competitive moves concentrate on certification pre-positioning ahead of evolving CPSC guideline drafts and backward integration into aluminum subframe production to secure aerospace-grade alloy supply.
Among Scandinavian-heritage specialists, Thule Group and Hamax AS exemplify the premium innovator archetype through Norwegian-origin safety credentials and deep rear-mount specialization. Polisport occupies a position within the manufacturing-scale tier, drawing from Portuguese plastics molding expertise to serve mid-tier retail channels across Southern Europe. These three anchors demonstrate how geographic origin and production configuration stratify competitive positioning across certification-grade and price-point vectors.
| Leading Market Players |
|---|
| Thule Group |
| Hamax AS |
| Polisport |
| WeeRide |
| Burley Design |
| Bellelli |
| Topeak |
| BoBike |
| REI Coop |
| Others |
Value Chain & Pricing Dynamics
Ninety-day injection molding lead times from Portuguese and Spanish clusters compress inventory carrying costs for mid-tier producers while amplifying pricing power for EN 14344-certified manufacturers with captive crash-test facilities. This temporal asymmetry rewards backward integration into aluminum subframe production and penalizes assemblers dependent on spot-market polymer sourcing.
Pricing Analysis
Long-term offtake agreements between Dutch fleet operators and certified manufacturers dominate volume transactions, while spot purchasing persists in Southern European retail channels. Price differentiation hinges on EN 14344 certification tier and harness system biomechanics sophistication, with five-point retention designs commanding substantial premiums over two-point economy configurations. Cost compression in plastic shell tiers is intensifying because REACH-mandated phthalate reformulation strains molders lacking pre-validated bio-based alternatives. Municipal procurement offices in Germany and the Netherlands exhibit lowest price sensitivity due to liability coverage requirements, whereas Spanish and Italian independent retailers face acute margin pressure from Asian import competition.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for component assemblers sourcing hardware from Asian contract manufacturers. Manufacturing gravity centers on Portugal, Spain, and Germany, with Portuguese and Spanish injection molding clusters feeding shell production and Baden-Württemberg automotive suppliers migrating testing protocols into family mobility products. Raw material dependencies encompass aerospace-grade aluminum alloys, phthalate-free polymer formulations, and energy-absorbing foam compounds. Single-source vulnerability concentrates in pediatric biomechanics talent pools for harness system design. Distribution runs through specialty cycling retailers in Northern Europe and mass-market sporting goods channels in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Child bike seat markets are transitioning toward service-attach models faster than hardware growth alone would predict, with subscription-based seasonal rental programs in Amsterdam and Copenhagen expanding recurring revenue pools beyond traditional unit sales economics.
For Market Incumbents: Consolidate certification pre-positioning ahead of evolving CPSC guideline drafts to defend against regulatory arbitrage from Asian contract manufacturers. Deepen backward integration into aluminum subframe production to secure aerospace-grade alloy supply and escape London Metal Exchange price volatility squeezing premium tier margins.
For New Entrants and Emerging Players: Lead with direct-to-consumer fit-assessment services targeting Spanish and Italian first-time family cyclists in municipalities accelerating protected lane construction. The underpenetrated Southern European cycling infrastructure presents the most penetrable white space, with Valencia and Barcelona logistics corridors enabling home installation support models bypassing traditional retail markups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cargo-compatible seat architectures as electric-assisted bicycle payload rewrites demand multi-child configurations with 30 kg load ratings. Acquisition targets should display in-house crash-test facilities and EN 14344 pre-certification status. The signal to watch is KBA motor-assisted bicycle classification expansion enabling previously excluded street-legal operation thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | EN 14344 and evolving CPSC compliance filters non-compliant imports, securing channel access. |
| Backward Integration into Aluminum Subframes | Aerospace-grade alloy supply prioritization threatens stamped-steel dependent assemblers. |
| Subscription-Based Rental Program Launch | Amsterdam and Copenhagen fleet operators demonstrate liability-coverage bundling attracts dual-income households. |
| Direct-to-Consumer Fit-Assessment Services | Randstad logistics corridor enables home installation support bypassing retail markups. |
| Phthalate-Free Polymer Reformulation | REACH enforcement windows compel Catalan and Portuguese molders to capture German shelf space. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with product development directors at Scandinavian design houses, regulatory affairs leads navigating dual-certification burdens, Portuguese molding plant managers, and Dutch fleet operators managing subscription programs; alongside secondary validation through EN 14344 certification databases, KBA motor-assisted bicycle classification filings, customs records tracking Portuguese and Spanish injection molding exports, and REACH chemical restriction enforcement timelines. Bottom-up channel checks across specialty retailers and mass-market distributors triangulated against top-down production capacity assessments at Baden-Württemberg testing facilities.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, material tier, safety certification grade, weight capacity threshold, and regional regulatory cluster. CAGRs derived from segment-level growth rate synthesis incorporating e-bike adoption curves, infrastructure investment pipelines, and family formation demographics. Key inputs encompassed ISO 8098 frame geometry evolution and evolving German payload classification thresholds.
Forecasts assume regulatory continuity in EN 14344 enforcement and KBA classification regimes; material policy shifts would require re-modeling load-rating assumptions and certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Motorcycle Accessories Market