
 E-Mountain Bike Market | 2026-2036
E-Mountain Bike Market Size, Share, and Industry Trends Forecast 2026-2036
E-Mountain Bike Market Analysis
The EU F-Gas Regulation is realigning battery thermal management costs for manufacturers targeting European distribution. Trek Bicycle Corporation leverages in-house carbon fiber frame production to sustain margin control across premium hardtail lines. Specialized Bicycle Components anchors its competitive position through proprietary motor integration technology developed at its California engineering center. Giant Manufacturing dominates high-volume aluminum frame output from its Taiwan production base, competing on scale against European specialists.
An e-mountain bike combines a pedal-assist electric drivetrain with off-road suspension geometry, typically integrating a mid-drive motor delivering 250-750W nominal output and a lithium-ion battery pack mounted on the downtube. Full-suspension configurations command the largest revenue share as trail complexity intensifies across lift-served bike parks in the Alps and Rockies. Carbon fiber frame material leads average selling prices despite aluminum retaining volume dominance in entry and mid-tier segments. The 500 Wh battery capacity tier captures the broadest rider base, balancing weight distribution against range requirements for backcountry loops.
FCC certification governs wireless connectivity modules in US-sold units, while CE marking mandates electromagnetic compatibility across European imports. EPA guidelines on lithium battery recycling influence end-of-life cost structures for brands with direct-to-consumer channels. Japan's METI energy-efficiency benchmarks for power-assisted cycles create a template that South Korea's MFDS and Australia's TGA increasingly reference for domestic type-approval. Stakeholders must track how divergent national speed-limit thresholds for pedal-assist cutoff reshape product platform strategies across export markets.
Market Dynamics
The EU F-Gas Regulation is restructuring battery thermal management costs for manufacturers distributing across Europe, forcing redesigns of refrigerant-based cooling systems while trail access expansions in Germany and the Pacific Northwest pull recreational riders into the category.
Growth Catalysts
- Trail network densification:Lift-served bike parks in the Austrian Alps and Colorado Rockies are adding dedicated e-mountain bike trails, reducing access friction for new entrants.
- F-Gas Regulation compliance:The EU mandate on refrigerant standards is accelerating adoption of phase-change thermal management materials in battery packs destined for European markets.
- Mid-drive motor refinement:Torque-sensor integration with 85 Nm output ratings is expanding the addressable rider base to steeper terrain previously dominated by conventional mountain bikes.
Market Restraints
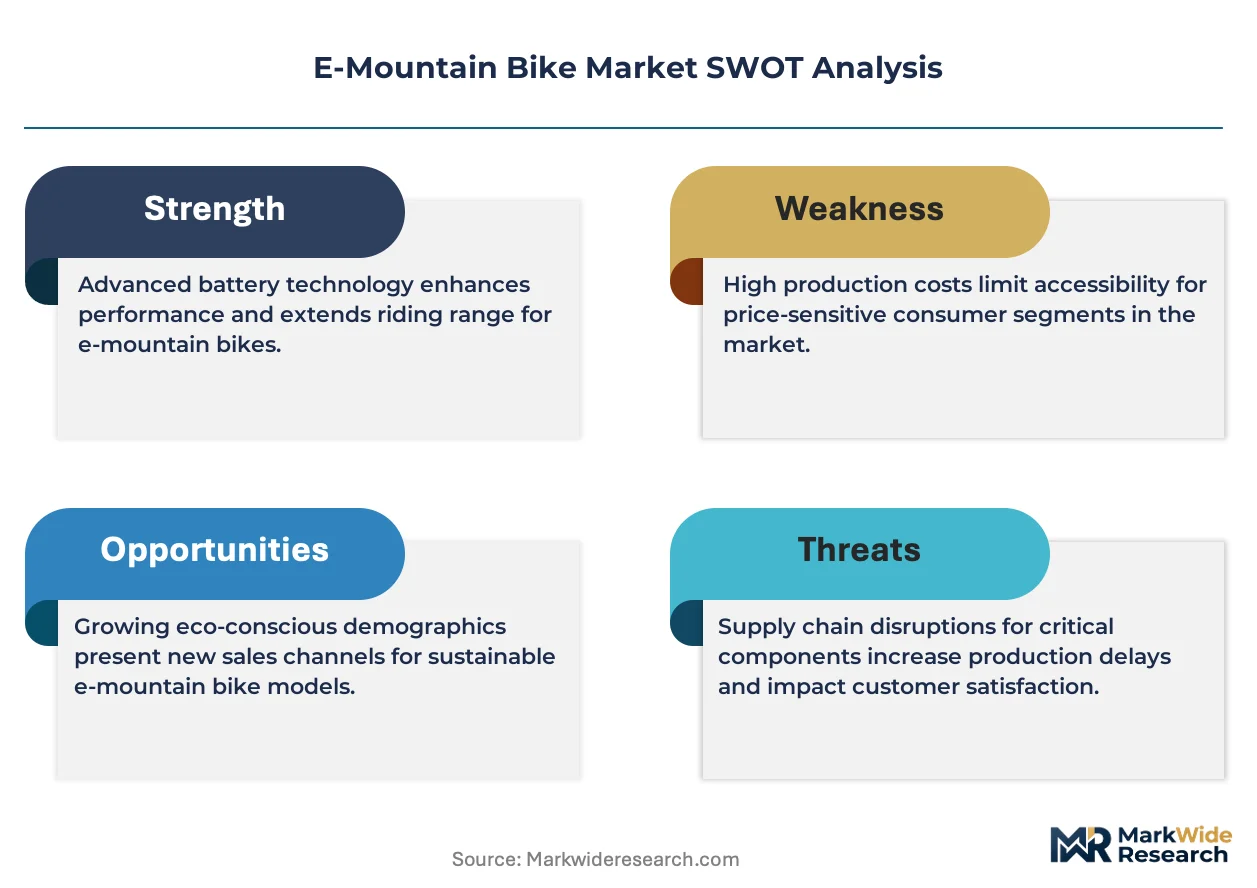
- Lithium carbonate volatility:Battery cell input costs fluctuate with spot-market pricing for cathode materials, compressing margin predictability for mid-tier assemblers.
- Taiwan frame concentration:High-volume aluminum production clusters around Taichung, creating single-source exposure for brands without captive carbon fiber capacity.
- Speed-limit fragmentation:Divergent pedal-assist cutoff thresholds between the United States, EU member states, and Japan force platform fragmentation and inventory complexity.
Strategic Opportunities
- Battery leasing models:Subscription-based battery programs reduce upfront purchase barriers for price-sensitive riders in the United Kingdom and Benelux markets.
- Dual-sport trail systems:Mixed-use paths accommodating both hiking and e-mountain biking are opening access in previously restricted US Forest Service jurisdictions.
- Solid-state thermal interface:Convergence of phase-change materials with graphene heat spreaders enables slimmer downtube profiles without sacrificing thermal runaway protection.
Industry Challenges
- Power electronics calibration:Tuning torque curves for varied terrain requires specialized firmware engineers, creating hiring bottlenecks at mid-size manufacturers.
- CE marking timelines:Electromagnetic compatibility certification for European imports extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Mountain Bike Market |
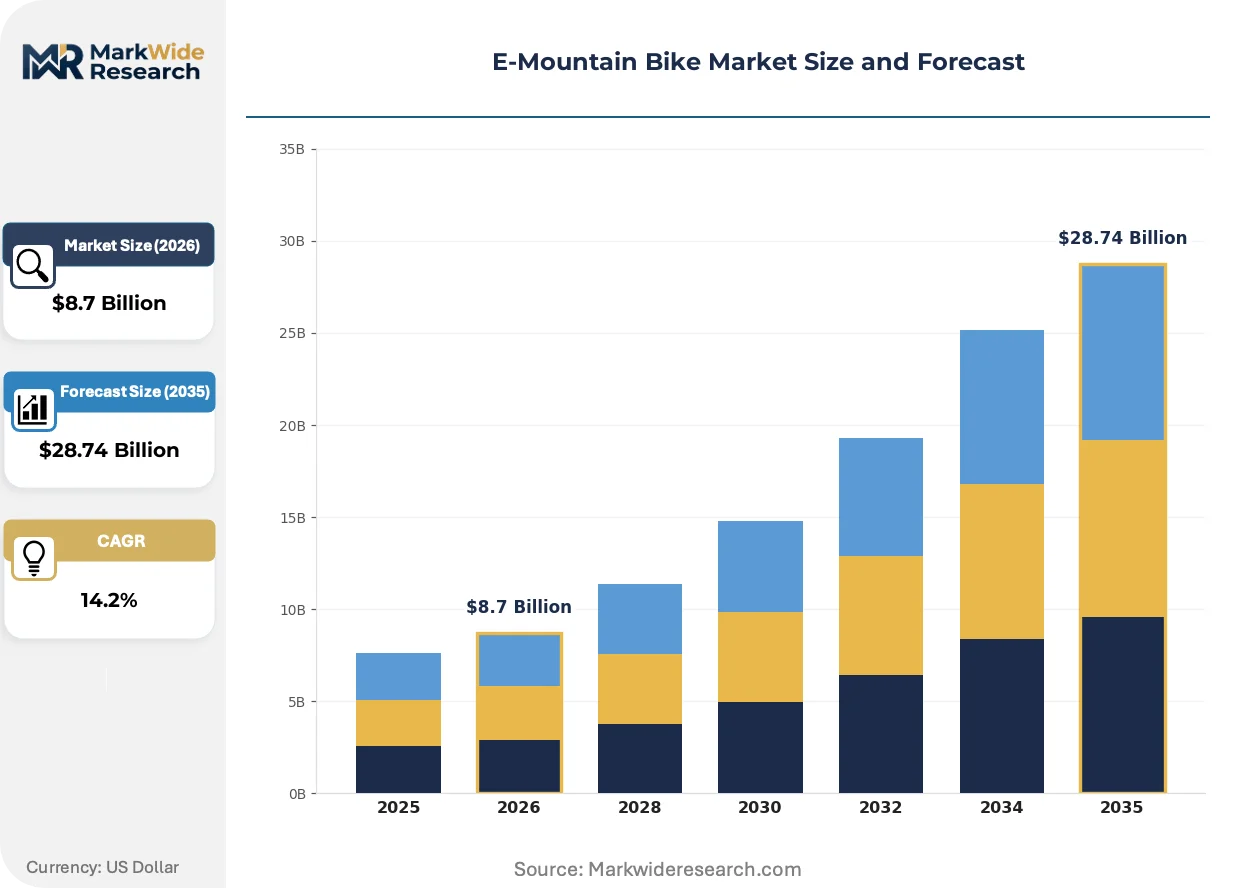
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Suspension, Hardtail, Fat Tire, Compact End User: Recreational Riders, Professional Cyclists, Trail Enthusiasts, Commuters Battery Capacity: 250 Wh, 500 Wh, 750 Wh, 1000 Wh Frame Material: Aluminum, Carbon Fiber, Steel, Titanium |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co. Ltd, Specialized Bicycle Components, Inc., Scott Sports SA, Accell Group, Yamaha Motor Co. Ltd, CUBE GmbH & Co. KG, Haibike, Merida Industry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Mountain Bike Market Emerging Trajectories
Active thermal management, wireless connectivity protocols, and modular battery architectures are converging to redefine product differentiation in premium e-mountain bike segments.
Phase-change material cooling is integrating into high-discharge battery packs to maintain cell temperature stability during sustained alpine descents. Premium hardtail buyers in Germany and Switzerland are specifying these systems at accelerating rates. This thermal architecture is integrating with smart battery management systems that predict thermal load based on GPS elevation profiles, compressing the performance gap between air-cooled and liquid-cooled alternatives.
REACH substance restrictions are tightening compliance requirements for adhesives and coatings used in frame construction, particularly for carbon fiber layup resins. Manufacturers exporting to EU markets are reformulating supply chains to exclude SVHC-classified compounds. The full-suspension segment bears the highest reformulation burden due to complex multi-material junctions requiring specialized bonding agents.
Direct-to-consumer channel expansion is fragmenting the traditional dealer-service model that dominated mountain bike retail for decades. Riders in urban-adjacent markets are accepting remote diagnostics and mail-in service protocols previously rejected by this category. This behavioral shift concentrates in the United States Pacific Northwest and Netherlands urban corridors where trailhead proximity reduces dependency on shop-based maintenance relationships.
E-Mountain Bike Market Segmentation
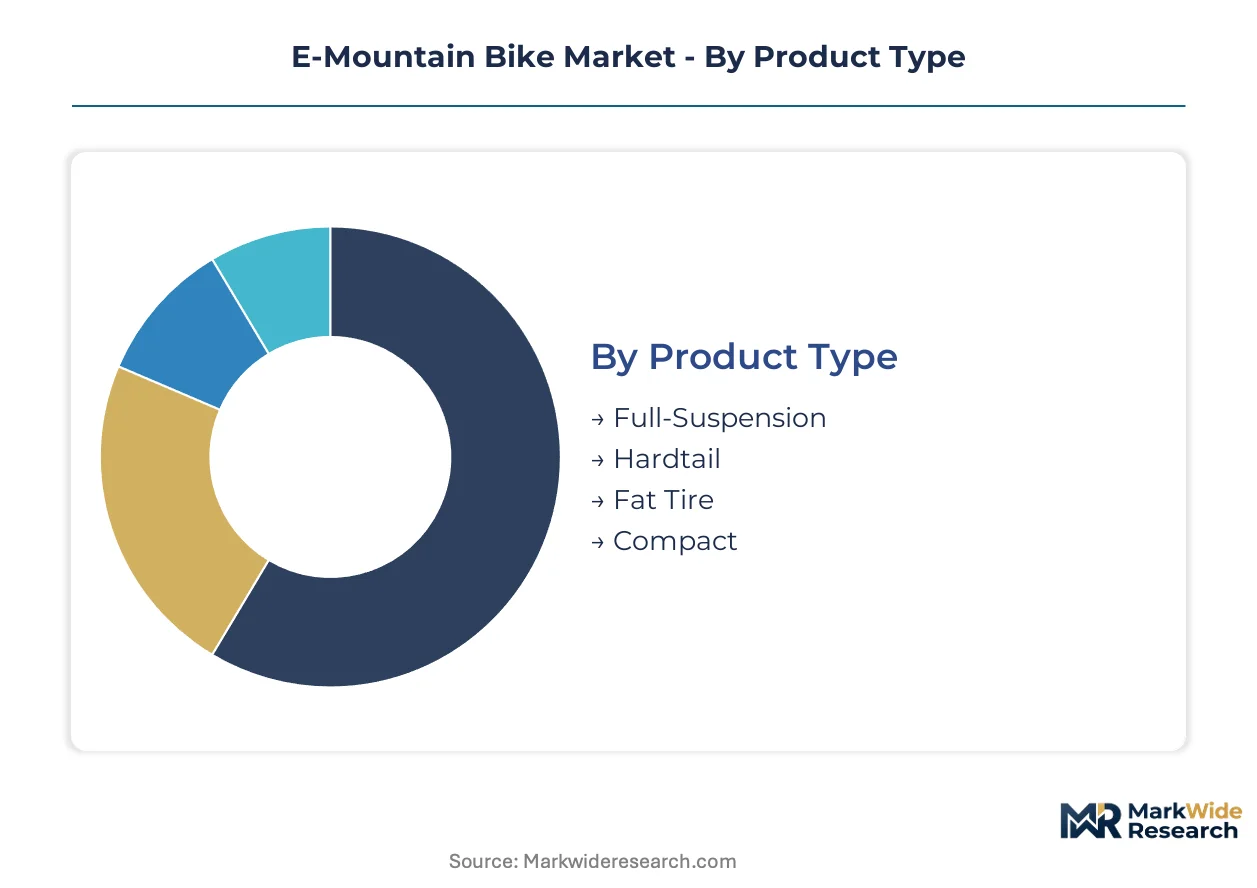
E-mountain bike purchasing decisions hinge on terrain specificity, thermal performance requirements, and frame manufacturing economics. Manufacturers configure product platforms around these segmentation axes to balance development costs against regional regulatory compliance.
Product Type:
Trail geometry and suspension travel separate riders by technical ambition and lift-access infrastructure.
- Full-Suspension:Dual-link rear suspension with 140-170mm travel dominates lift-served bike parks in the Austrian Alps and Colorado Rockies. Trail network densification across these regions pulls recreational riders toward platforms that absorb high-speed chatter and drop landings without pedal bob.
- Hardtail:Front-fork-only suspension reduces weight and maintenance complexity for cross-country loop riders. Germany's Alpine regions concentrate demand here, where climbing efficiency outweighs descent capability on multi-use trail systems.
- Fat Tire:4.0-inch plus tires float over sand and snow surfaces inaccessible to standard widths. Beach access trails in Oregon and winter groomed routes in Minnesota anchor this niche.
- Compact:Foldable frame geometries with 20-inch wheels address urban-adjacent storage constraints. Netherlands urban corridors and Tokyo apartment dwellers drive specification for multi-modal commuting integration.
Full-Suspension leads volumes today; Compact is gaining share fastest.
End User:
Skill progression curves and maintenance relationships shape how each buyer type engages distribution channels.
- Recreational Riders:Weekend warriors with limited mechanical literacy depend on dealer networks for suspension tuning and brake bleeding. Pacific Northwest trail access expansions concentrate this segment where shop-based service relationships remain sticky.
- Professional Cyclists:Sponsored athletes and race competitors demand prototype access and rapid component replacement. Their specification influence cascades through enthusiast communities despite small absolute numbers.
- Trail Enthusiasts:Self-sufficient riders with workshop competency accept direct-to-consumer channels and remote diagnostics. This behavioral shift fragments traditional retail most aggressively in United States markets.
- Commuters:Utility-focused buyers prioritize integrated lighting, fender compatibility, and theft-resistant battery locks over suspension performance. Benelux cycling infrastructure investments expand this application.
Recreational Riders anchor current shipment volumes; Trail Enthusiasts are climbing the fastest.
Battery Capacity:
Range anxiety intersects with frame packaging constraints and thermal runaway protection requirements.
- 500 Wh:The broadest rider base balances weight distribution against backcountry loop requirements. This tier captures alpine descent riders who need sustained output without excessive downtube bulk.
- 750 Wh:Extended-range packs with phase-change thermal management address multi-day hut-to-hut touring in Switzerland and Tyrol. F-Gas Regulation compliance costs concentrate development investment here.
- 250 Wh:Minimalist configurations prioritize frame handling purity for technical singletrack purists. Japan's METI efficiency benchmarks influence these lightweight specifications.
- 1000 Wh:Dual-battery or oversized single-cell arrays serve expedition riders and commercial tour operators. Weight penalties restrict adoption to specialized applications.
500 Wh dominates unit economics; 750 Wh shows steepest expansion trajectory.
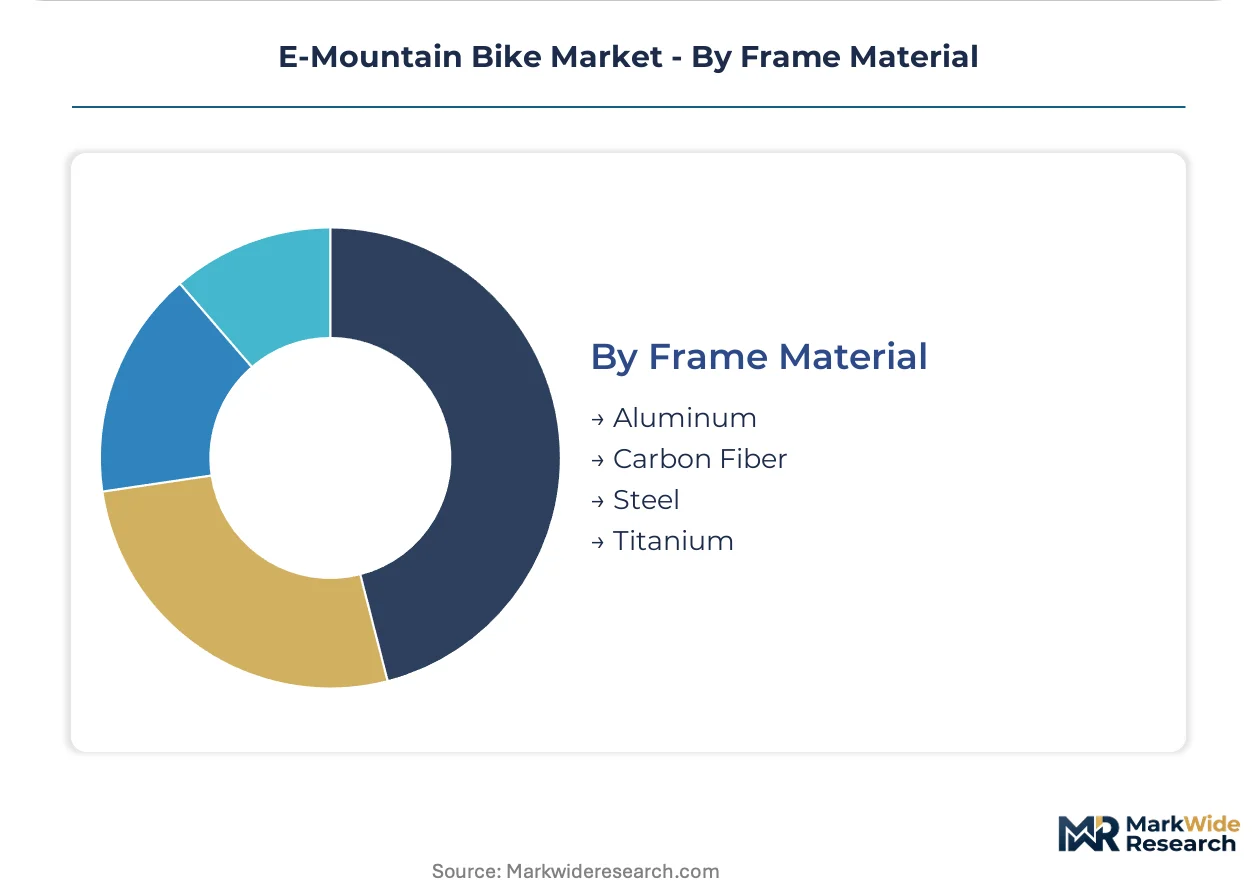
Frame Material:
Manufacturing geography and labor intensity separate cost structures across supply bases.
- Aluminum:High-volume hydroformed tubing from Taichung production clusters delivers price-accessible entry and mid-tier platforms. Giant Manufacturing's scale advantages here compress margins for European specialists without captive capacity.
- Carbon Fiber:Layup-intensive construction with tunable stiffness profiles commands premium positioning. REACH substance restrictions on SVHC-classified resins force supply chain reformulation for EU-bound units.
- Steel:Chromoly and stainless variants appeal to custom frame builders and repairability advocates. Small-batch production resists Asian manufacturing consolidation.
- Titanium:Aerospace-grade tubing delivers fatigue resistance and corrosion immunity for lifetime purchase intentions. Limited weld-qualified fabricators constrain volume expansion.
Aluminum leads volumes today; Carbon Fiber is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Taichung, and Boulder anchor the industry's technical development. Manufacturing clusters concentrate around carbon fiber layup specialists in Taiwan and aluminum hydroforming operations in Germany. Trail network investments across four continents pull recreational riders into the category.
United States
Lift-served bike parks in Colorado and the Pacific Northwest are adding dedicated e-mountain bike trails. The EPA's lithium battery recycling guidelines shape end-of-life cost structures for direct-to-consumer brands. Boulder, Colorado hosts firmware engineering clusters where torque-sensor calibration specialists concentrate.
Germany
Alpine regions in Bavaria and Baden-Württemberg concentrate recreational rider demand on multi-use trail systems. The EU F-Gas Regulation forces refrigerant redesigns in battery thermal management for European-bound units. Stuttgart's engineering base anchors mid-drive motor refinement work for premium hardtail lines.
Switzerland
Hut-to-hut touring routes in the Alps drive specification for extended-range battery packs with phase-change cooling. Swissmedic-type approval timelines for electromagnetic compatibility create four-to-six month launch delays. The Zürich-Geneva corridor concentrates high-net-worth buyer demand for carbon fiber full-suspension platforms.
Japan
METI energy-efficiency benchmarks for power-assisted cycles establish technical templates referenced across Asia-Pacific. The Kansai region's precision manufacturing base supplies torque-sensor components to global assemblers. Osaka-area engineering centers focus on lightweight 250 Wh configurations for technical singletrack purists.
Taiwan
Taichung's aluminum frame production clusters deliver high-volume hydroformed tubing to mid-tier brands worldwide. GB standards alignment with EU technical regulations streamlines export certification for European distribution. The central Taiwan manufacturing belt concentrates Giant Manufacturing's scale advantages in entry-level platform output.
E-Mountain Bike Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive carbon fiber capacity. Tier-one assemblers compete on motor integration proprietary technology while mid-tier players source frames from concentrated Taiwanese supply bases. Three archetypes dominate: European premium specialists with in-house engineering, Asian scale manufacturers with aluminum volume advantages, and component suppliers backward-integrating into complete bike assembly. M&A activity targets firmware engineering teams, while capacity expansion concentrates in carbon fiber layup facilities.
Among Taiwan-based scale manufacturers, Giant Manufacturing Co. Ltd exemplifies volume-driven aluminum platform dominance. Trek Bicycle Corporation and Specialized Bicycle Components occupy positions as vertically integrated premium-tier specialists with captive carbon fiber production and proprietary motor development. These three anchors represent the structural tension between Asian manufacturing scale and European-North American engineering premiumization.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. Ltd |
| Specialized Bicycle Components, Inc. |
| Scott Sports SA |
| Accell Group |
| Yamaha Motor Co. Ltd |
| CUBE GmbH & Co. KG |
| Haibike |
| Merida Industry Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Austria maintain pricing discipline through captive carbon fiber layup facilities that insulate premium hardtail lines from Taiwanese aluminum cost cycles. Their ownership structure enables long-term supplier relationships without quarterly margin pressure, concentrating investment in F-Gas Regulation-compliant thermal management systems that European distributors now require.
Pricing Analysis
Bundled battery leasing programs separate hardware acquisition from energy service costs across United Kingdom and Benelux markets, while unbundled frame-only purchases persist among self-sufficient trail enthusiasts. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales service intensity. Cost compression in entry-level aluminum frames is intensifying because Giant Manufacturing's Taichung scale advantages compress margins for European specialists without captive capacity. Recreational riders in the Pacific Northwest exhibit highest price sensitivity due to dealer dependency, while carbon fiber full-suspension buyers in Switzerland show least.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion battery packs are creating secondary refurbishment channels in Germany and the Netherlands, with end-of-life collection networks governed by EPA guidelines in the United States. Frame manufacturing draws from Taiwan, Germany, and China, while torque-sensor components source from Japan's Kansai precision manufacturing base. Single-source vulnerability concentrates in Taichung aluminum hydroforming clusters. Distribution runs through direct-to-consumer channels that fragment traditional dealer-service relationships in urban-adjacent United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Mountain Bike Market reads as a late-cycle quality story where recreational rider demand is shifting toward full-suspension platforms with integrated thermal management, rewarding manufacturers with in-house engineering depth.
For Market Incumbents: Anticipate firmware engineering talent scarcity by acquiring specialized calibration teams in Boulder and Stuttgart before mid-tier competitors consolidate remaining pools. Defend margin position through backward integration into carbon fiber layup capacity that REACH substance restrictions now favor for EU-bound units. Channel control through exclusive dealer networks in the Pacific Northwest remains sticky against direct-to-consumer fragmentation.
For New Entrants and Emerging Players: Direct-to-consumer digital channels with remote diagnostics capability offer the most penetrable route into United States trail enthusiast segments where workshop competency reduces service dependency. Target battery leasing subscription models in United Kingdom and Benelux markets where upfront purchase barriers concentrate price-sensitive demand. White-space exists in compact foldable geometries for Netherlands urban corridors and Tokyo apartment dwellers seeking multi-modal integration.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier aluminum assemblers without captive carbon fiber capacity or proprietary motor integration technology. Long-term viability favors vertically integrated specialists with in-house engineering in Stuttgart or Boulder and established European distribution compliant with F-Gas Regulation mandates. Monitor phase-change thermal management adoption rates in 750 Wh battery packs as inflection indicator for premium segment profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Phase-Change Thermal Management Integration | F-Gas Regulation compliance in European markets now requires refrigerant-free battery cooling systems with graphene heat spreaders. |
| Direct-to-Consumer Channel Expansion | Remote diagnostics and mail-in service protocols are fragmenting traditional dealer relationships in United States Pacific Northwest markets. |
| Battery Leasing Program Launch | Subscription-based energy services reduce upfront barriers for price-sensitive recreational riders in United Kingdom and Benelux corridors. |
| Carbon Fiber Layup Capacity Addition | REACH substance restrictions on SVHC-classified resins favor in-house formulation control for EU-bound premium full-suspension platforms. |
| Firmware Engineering Team Acquisition | Torque-sensor calibration specialists in Boulder and Stuttgart face hiring bottlenecks that mid-size manufacturers cannot resolve organically. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with frame manufacturing plant managers, OEM procurement leads at motor suppliers, dealer network operators, and trail access advocacy coordinators. Secondary validation draws from EPA lithium battery recycling guidelines, EU F-Gas Regulation filings, METI energy-efficiency benchmark publications, and customs trade data for aluminum and carbon fiber imports. Bottom-up assembly cost modeling triangulates against top-down demand segmentation across product type, battery capacity, and frame material tiers.
Rate-of-change decomposition separates volume expansion from average selling price evolution across the projection horizon. Segmentation dimensions modeled include suspension configuration, battery capacity tier, frame material grade, and regional regulatory cluster. CAGRs derive from rider population growth in lift-served bike park jurisdictions, trail network densification rates, and thermal management system adoption curves. Industry-specific inputs incorporate torque-sensor refinement timelines and phase-change material cost reduction trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state thermal interface materials would alter the outlook if graphene heat spreader costs decline faster than projected. Forecasts reflect assumptions about F-Gas Regulation enforcement consistency and lithium carbonate spot price volatility. Practitioners should monitor CE marking timeline extensions and speed-limit regulatory fragmentation for early signals of platform strategy disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market