
 UAE Electric Bike Market | 2026-2036
UAE Electric Bike Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Electric Bike Market Insights
Aftermarket service revenue is narrowing as manufacturers bundle extended warranties and mobile maintenance into initial purchase contracts. NIU Technologies leverages its cloud-connected diagnostics platform to lock in recurring service income across Dubai's delivery fleet accounts. Giant Bicycles anchors its position through dealer-trained technician networks that handle battery swaps and firmware updates in Abu Dhabi and Sharjah. Sulmi competes on rapid-turnaround repair commitments that appeal to time-sensitive courier operators.
An electric bike integrates a rechargeable battery pack, hub or mid-drive motor, and pedal-assist or throttle-based control system into a bicycle frame, delivering motorized propulsion up to manufacturer-specified speeds for urban transport and light commercial duty. City bikes and cargo bikes dominate unit volumes as Dubai's delivery services prioritize load capacity and step-through accessibility for rider turnover reduction. Lithium-ion battery configurations command the replacement and upgrade cycle as fleet operators phase out lead acid units to cut weight and extend daily range per charge.
MOHAP and the UAE's central standardization body govern product safety certifications and battery transport regulations that determine which models clear customs and retail licensing. Dubai's Roads and Transport Authority and Abu Dhabi's Department of Municipalities set operating permissions, lane access rules, and helmet mandates that directly shape fleet procurement specifications. Stakeholders must track how emirate-level enforcement consistency evolves, since divergent rider licensing requirements between Dubai and northern emirates would fragment fleet deployment economics.
Market Dynamics
Fleet electrification mandates from Dubai's Roads and Transport Authority and Abu Dhabi's Department of Municipalities are compressing replacement cycles for petrol-powered delivery scooters, forcing operators to standardize on connected electric two-wheelers with telematics compliance.
Growth Catalysts
- Dubai's Green Mobility Strategy:Municipal sustainability targets require last-mile logistics operators to convert 30% of fleets to electric powertrains by defined interim deadlines, creating guaranteed demand visibility.
- Lithium-ion chemistry improvements:Energy density gains in NMC and LFP cell configurations extend daily range per charge, enabling courier operators to complete full delivery routes without mid-shift battery swaps.
- Petrol scooter operating cost inflation:Fuel price volatility and maintenance burden for internal combustion engines in high-utilization commercial duty cycles push fleet managers toward total-cost-of-ownership calculations favoring electrification.
Market Restraints
- Charging infrastructure asymmetry:Northern emirates lack the DC fast-charging corridor density of Dubai and Abu Dhabi, fragmenting fleet deployment economics across the federation.
- Battery cell supply concentration:Lithium-ion pack production concentrates in East Asian manufacturing hubs, exposing UAE assemblers to shipping cost volatility and customs clearance delays.
- Hub motor thermal limitations:Sustained high-load operation in summer ambient temperatures degrades motor efficiency and accelerates bearing wear, compressing maintenance intervals.
Strategic Opportunities
- Sharjah and Ras Al Khaimah logistics corridors:These northern emirates currently show minimal electric two-wheeler penetration but host expanding e-commerce fulfillment centers requiring last-mile connectivity.
- Solar-integrated charging depots:Warehouse operators with rooftop photovoltaic installations can offer fleet customers bundled clean energy contracts that offset grid electricity costs during peak demand windows.
- Battery-as-a-service models:Decoupling vehicle purchase from energy storage ownership reduces upfront capital requirements for small courier operators and locks in recurring revenue streams for infrastructure providers.
Industry Challenges
- Telematics integration complexity:Fleet management platforms must reconcile data protocols from multiple motor controller manufacturers to deliver unified route optimization and rider safety monitoring.
- MOHAP certification timelines:Product safety documentation and battery transport compliance reviews create 8-14 week customs clearance delays for new model introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Electric Bike Market |
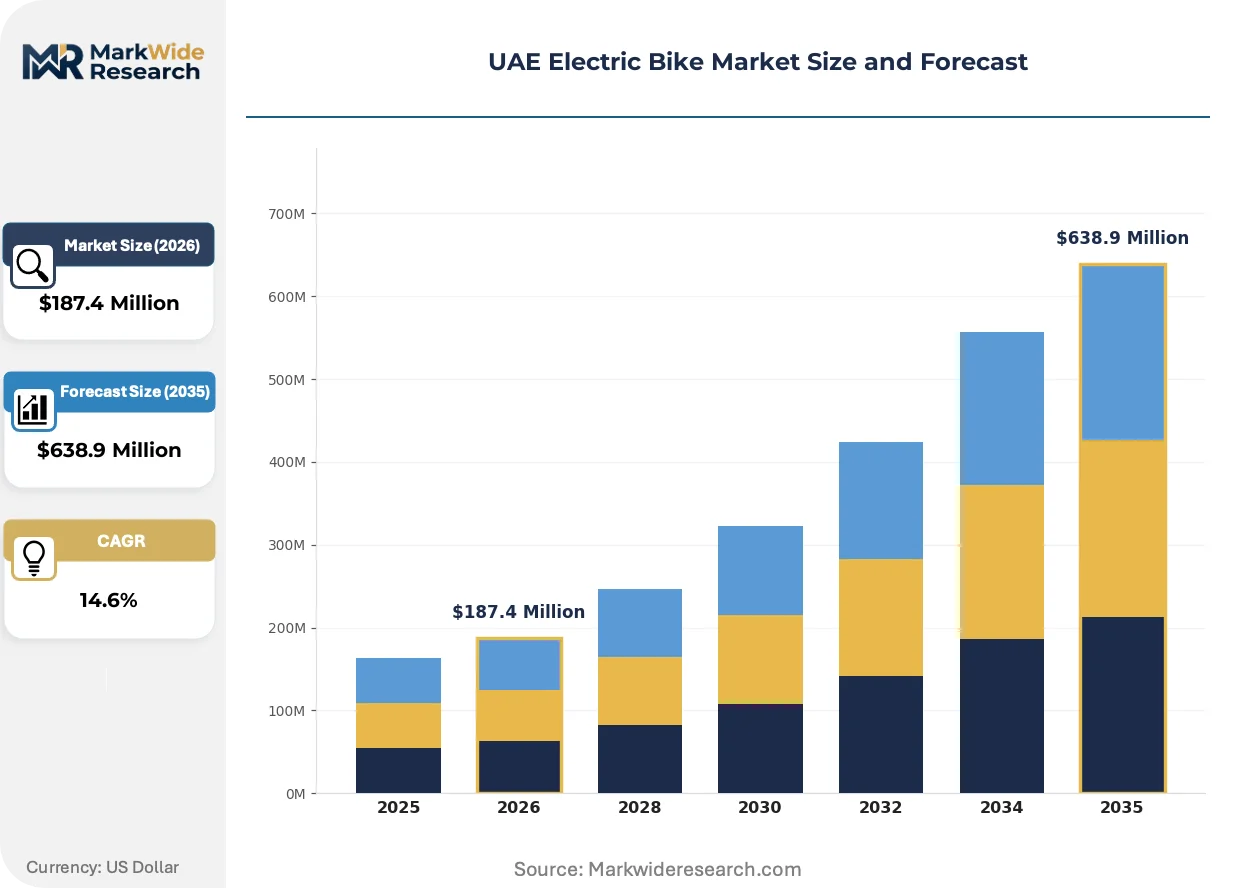
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bikes, Mountain Bikes, Folding Bikes, Cargo Bikes Battery Type: Lithium-ion, Lead Acid, Nickel Metal Hydride, Lithium Polymer End User: Commuters, Delivery Services, Recreational Users, Fleet Operators Weight Capacity: Standard, Heavy-duty, Lightweight, Ultra-lightweight |
| Companies Covered | SuperC Motors / Surron Dubai, Al Asala Bicycles Trading L.L.C, accet.ae, MiniMotors Middle East, Sulmi, ONE MOTO Technologies, EMX Motors, NIU Technologies, Giant Bicycles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Electric Bike Market Trends and Innovations
Connected diagnostics and over-the-air firmware management are redefining how fleet operators maintain electric two-wheelers, shifting value capture from reactive repair toward predictive intervention models.
Mid-drive motor architectures are migrating from premium consumer segments into commercial cargo bike configurations. Dubai-based delivery fleets are specifying torque-sensor pedal assist systems for hill-climb performance in Deira and Bur Dubai districts. The technology is migrating from European cycling markets into UAE commercial specifications as load ratings and thermal management improve.
MOHAP and the UAE's central standardization body are tightening lithium-ion battery transport and storage regulations to align with evolving international safety frameworks. These rules now require UN38.3 test certification for all imported battery packs and mandate thermal runaway containment in warehouse charging facilities. Fleet operators in Abu Dhabi's island communities are responding by consolidating charging operations into purpose-built depots rather than dispersed residential locations.
Service bundling is displacing transactional aftermarket relationships across Dubai's delivery fleet accounts. NIU Technologies and Giant Bicycles now embed multi-year maintenance contracts and mobile technician dispatch into initial vehicle procurement agreements. This consolidation is most visible among time-sensitive courier operators who cannot tolerate unscheduled downtime during peak delivery windows.
UAE Electric Bike Market Segmentation
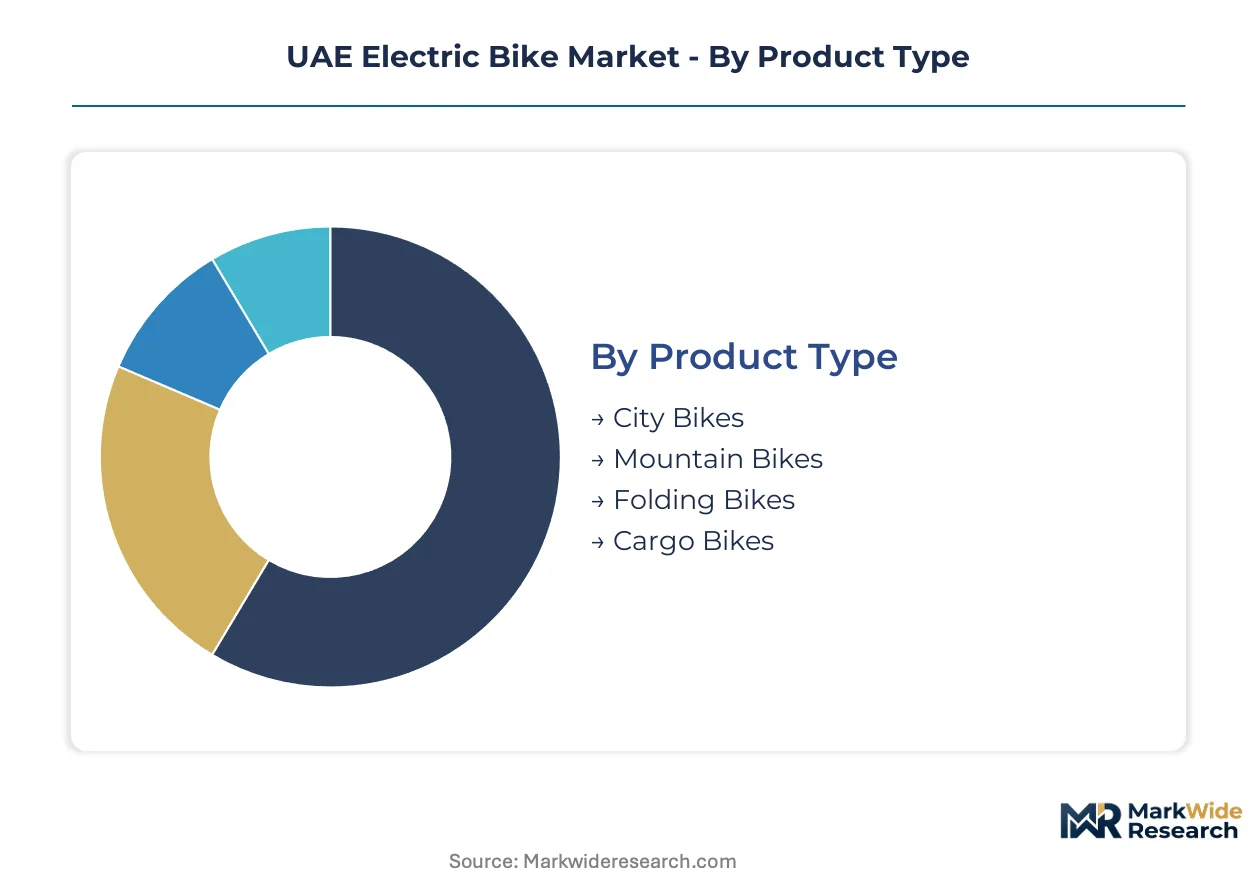
Segmentation in the UAE electric bike market reveals how procurement priorities diverge between commercial fleet operators and individual consumers. Understanding these splits helps vendors align product specifications with the distinct durability, range, and service requirements of Dubai's logistics corridors versus Abu Dhabi's recreational cycling communities.
Product Type:
Replacement cycles vary sharply across product categories, with commercial workhorses turning over every 18-24 months while recreational units persist for 5-7 years.
- Cargo Bikes:Reinforced frames with extended wheelbases accommodate 150-200kg payloads for last-mile delivery operators. Dubai's logistics fleets specify these units for e-commerce fulfillment routes where load capacity directly determines revenue per rider hour.
- City Bikes:Step-through frames and upright riding positions dominate Abu Dhabi's island communities where short-distance commuting meets high humidity tolerance requirements. Step-through accessibility reduces rider training time for fleet operators managing high turnover.
- Folding Bikes:Compact storage dimensions appeal to multi-modal commuters connecting with Dubai Metro and tram networks.
- Mountain Bikes:Suspension systems and knobby tire configurations serve Hatta and Jebel Jais recreational trail users seeking off-pavement capability.
Cargo bikes dominate installed base value. City bikes are where expansion concentrates most quickly.
Battery Type:
Cost tier alignment determines procurement patterns, with premium chemistry commanding fleet contracts and economy options persisting in price-sensitive consumer segments.
- Lithium-ion:NMC and LFP cell configurations deliver 500-1000 charge cycles with energy densities above 250 Wh/kg. Dubai's delivery services mandate these packs for thermal stability during summer ambient temperatures exceeding 45°C.
- Lithium Polymer:Flexible form factors and reduced weight suit folding bike designs where frame integration constraints limit pack dimensions. Sharjah's recreational distributors stock these for premium consumer segments.
- Lead Acid:Lower upfront costs persist in northern emirate price-sensitive markets despite 3-4x weight penalties.
- Nickel Metal Hydride:Moderate energy density and reduced memory effect appeal to legacy fleet operators transitioning from lead acid infrastructure.
Lithium-ion dominates installed base. Lithium polymer is gaining share fastest among premium consumer segments.
End User:
Volume concentration splits between high-unit fleet deployments and fragmented individual purchases with divergent service expectations.
- Delivery Services:High-utilization operators in Dubai's logistics corridors specify telematics-integrated units with route optimization compatibility. These accounts generate 60-70% of commercial revenue through multi-year service contracts.
- Fleet Operators:Centralized procurement for corporate mobility programs and rental schemes across Abu Dhabi's business districts. Standardized specifications reduce maintenance complexity and spare parts inventory requirements.
- Commuters:Individual purchasers prioritizing reliability and theft deterrence for daily Dubai Metro connections.
- Recreational Users:Weekend cyclists and fitness enthusiasts in Al Ain and Ras Al Khaimah seeking pedal-assist for trail exploration.
Delivery services anchor commercial revenue. Fleet operators represent the steepest expansion trajectory as corporate sustainability mandates proliferate.
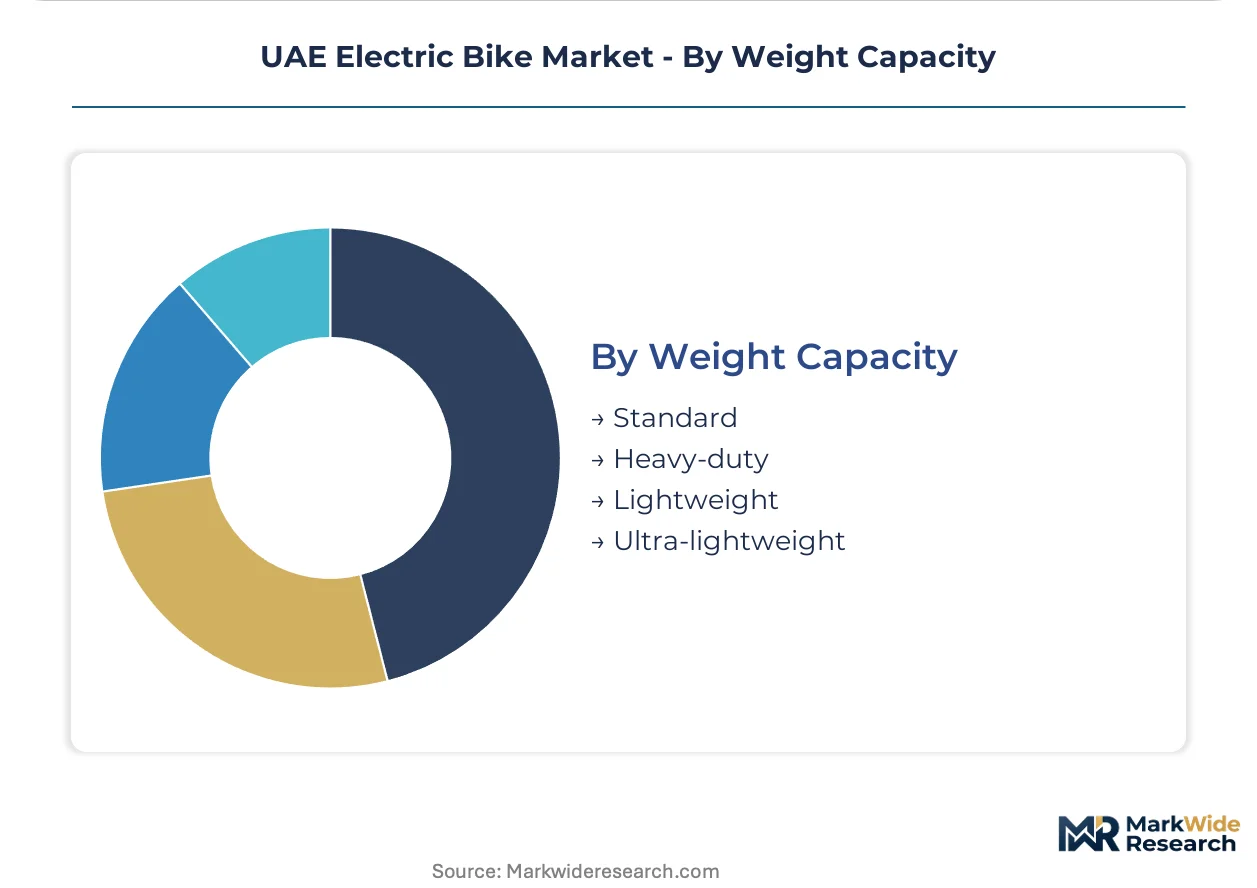
Weight Capacity:
Application requirements drive specification splits, with commercial duty cycles demanding reinforced construction versus consumer preference for maneuverability.
- Heavy-duty:Reinforced frames and upgraded hub motors accommodate 120kg+ payloads plus cargo for Dubai's grocery and pharmaceutical delivery specialists. These units specify upgraded brake systems for loaded deceleration safety margins.
- Standard:100-120kg ratings serve typical commuter and light delivery applications across Abu Dhabi's mixed-use developments. This specification balances component cost with adequate durability for moderate daily distances.
- Lightweight:Aluminum and carbon fiber frame materials reduce total vehicle weight below 20kg for multi-modal commuters.
- Ultra-lightweight:Premium materials and compact motors target enthusiast segments where portability exceeds payload priority.
Heavy-duty dominates fleet procurement value. Standard capacity is where consumer volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai concentrates commercial fleet deployment while Abu Dhabi dominates premium consumer adoption, with northern emirates lagging in charging density and regulatory harmonization.
Dubai
Last-mile logistics corridors along Sheikh Zayed Road and Al Quoz industrial zones drive heavy-duty cargo bike procurement for e-commerce fulfillment. Dubai's Roads and Transport Authority enforces fleet electrification timelines through its Green Mobility Strategy mandates. Jebel Ali logistics clusters host the highest density of telematics-integrated electric two-wheeler depots.
Abu Dhabi
Island communities on Saadiyat and Yas Islands prioritize step-through city bikes for short-distance commuting in high-humidity conditions. The Department of Municipalities coordinates lane access permissions with federal sustainability frameworks. Khalifa Industrial Zone Abu Dhabi anchors corporate mobility program deployments for standardized fleet specifications.
Sharjah
E-commerce fulfillment center expansion creates latent demand for delivery fleet electrification without matching charging infrastructure investment. The emirate's municipal transport authority tracks Dubai's regulatory templates for future adoption alignment. Industrial zones near Sharjah International Airport show emerging courier operator interest in battery-swap capable configurations.
Northern Emirates
Ras Al Khaimah and Fujairah present minimal current penetration but host tourism and light logistics applications requiring ruggedized frame specifications. Federal MOHAP certification requirements apply uniformly, though local enforcement capacity varies. Mountain trail networks near Jebel Jais attract recreational mountain bike interest from weekend fitness segments.
UAE Electric Bike Market Competitive Landscape
Capability concentration sits with telematics-integrated specialists; scale advantage sits with established bicycle manufacturers with dealer networks. The vendor base splits between cloud-connected fleet solution providers and traditional distributors with maintenance infrastructure. Two strategic archetypes dominate: technology-integrated platform vendors and service-bundled dealer networks. Competitive moves center on multi-year service contract bundling and rapid-turnaround repair commitments.
Among technology-integrated specialists, NIU Technologies exemplifies the connected-diagnostics archetype through cloud-based fleet management platforms. Giant Bicycles anchors the dealer-network tier with technician-trained service infrastructure. Sulmi occupies a position emphasizing rapid repair turnaround for time-sensitive courier operators.
| Leading Market Players |
|---|
| SuperC Motors / Surron Dubai |
| Al Asala Bicycles Trading L.L.C |
| accet.ae |
| MiniMotors Middle East |
| Sulmi |
| ONE MOTO Technologies |
| EMX Motors |
| NIU Technologies |
| Giant Bicycles |
| Others |
Pricing and Supply Chain Analysis
Dongguan's lithium-ion cell manufacturing clusters feed directly into UAE fleet procurement negotiations, with capacity allocation decisions at Chinese gigafactories translating into pricing leverage for Dubai's delivery operators during annual contract renewals.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement, with Dubai's logistics operators locking in 24-36 month battery supply contracts to insulate against spot market volatility. Price differentiation rests on telematics integration depth and MOHAP certification tier, with connected-diagnostics platforms commanding premium positioning. Cost compression in entry-level hub motor configurations is intensifying because lead acid replacement demand from northern emirates constrains margin expansion. Small courier operators exhibit highest price sensitivity, while integrated fleet managers prioritize total-cost-of-ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from Chinese cell manufacturers are reshaping working capital requirements for UAE assemblers, with 90-120 day supplier financing becoming standard for NMC and LFP pack procurement. Geographic supply concentration centers on China, South Korea, and Japan for lithium-ion cells, with Taiwan and Vietnam contributing motor controller assemblies. Raw material dependencies include cobalt sulfate, lithium carbonate, and rare-earth permanent magnets. Single-source vulnerability around cathode active material suppliers exposes assemblers to export license disruptions. Distribution runs through Jebel Ali bonded warehousing facilities before final assembly in Dubai and Abu Dhabi industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE electric bike market sits in early-cycle expansion, with Dubai's Green Mobility Strategy fleet electrification mandates guaranteeing demand visibility through defined interim compliance deadlines.
For Market Incumbents: Harden telematics platform differentiation against emerging hardware-commoditization pressure from white-label motor controller suppliers. Secure backward integration into battery pack assembly within UAE free zones to compress MOHAP certification timelines and lock in service revenue through captive maintenance networks. For New Entrants and Emerging Players: Establish a beachhead in Sharjah's e-commerce fulfillment corridor, where charging infrastructure gaps have delayed incumbent fleet deployment. Battery-swap capable configurations offer the most penetrable entry angle, with rapid-turnaround repair commitments differentiating against established dealer-network incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-connected fleet management platform providers with multi-year service contract penetration above sixty percent of installed base. Long-term viability favors vendors with UAE-based assembly capacity and MOHAP pre-certification pipelines. Watch for northern emirate regulatory harmonization with Dubai's RTA frameworks as the key inflection signal for geographic expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | NIU Technologies and Giant Bicycles embed cloud diagnostics to capture recurring service revenue from Dubai delivery fleets. |
| Battery-as-a-Service Model Launch | Decouples energy storage ownership from vehicle purchase, reducing upfront capital barriers for small courier operators. |
| Solar-Integrated Charging Depot Buildout | Warehouse operators with rooftop photovoltaic offer bundled clean energy contracts offsetting grid electricity costs. |
| Mid-Drive Motor Architecture Migration | Torque-sensor pedal assist systems from European cycling markets enter UAE commercial cargo specifications. |
| MOHAP Pre-Certification Pipeline Investment | UAE-based assembly capacity compresses customs clearance delays for new model introductions. |
Research Methodology
Desk research of UAE federal regulatory filings, Dubai RTA policy circulars, and customs trade databases preceded structured interviews with fleet procurement managers, MOHAP certification specialists, lithium-ion cell distributors, and dealer network operators. Primary fieldwork across Dubai's Jebel Ali logistics clusters and Abu Dhabi's Khalifa Industrial Zone validated secondary demand estimates. Bottom-up unit deployment counts from telematics providers were triangulated against top-down market value projections.
Assumptions held Dubai's Green Mobility Strategy electrification timelines and MOHAP battery transport regulations fixed across the projection horizon, while lithium cell chemistry cost curves and northern emirate charging infrastructure investment schedules were varied. Segmentation modeling spanned product type, battery chemistry, end-user category, and weight capacity tier, with regional adoption patterns as an additional dimension. CAGRs were derived from logistic penetration curves fitted to fleet replacement cycle data and consumer purchase intention surveys.
Sensitivities concentrate around northern emirate regulatory harmonization velocity and East Asian cell export license availability. Forecasts reflect these documented assumptions; deviation in federal EV policy enforcement consistency or lithium carbonate supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Electric Cargo Bikes Market