
 Low Voltage Drives Market | 2026-2036
Low Voltage Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage Drives Market Analysis
Water treatment utilities is redrawing procurement patterns across the Low Voltage Drives landscape as municipal infrastructure upgrades accelerate. ABB leverages its integrated automation portfolio to anchor large-scale European water projects. Siemens competes through digital twin integration with its drive systems. Danfoss specializes in decentralized drive architectures for pumping applications.
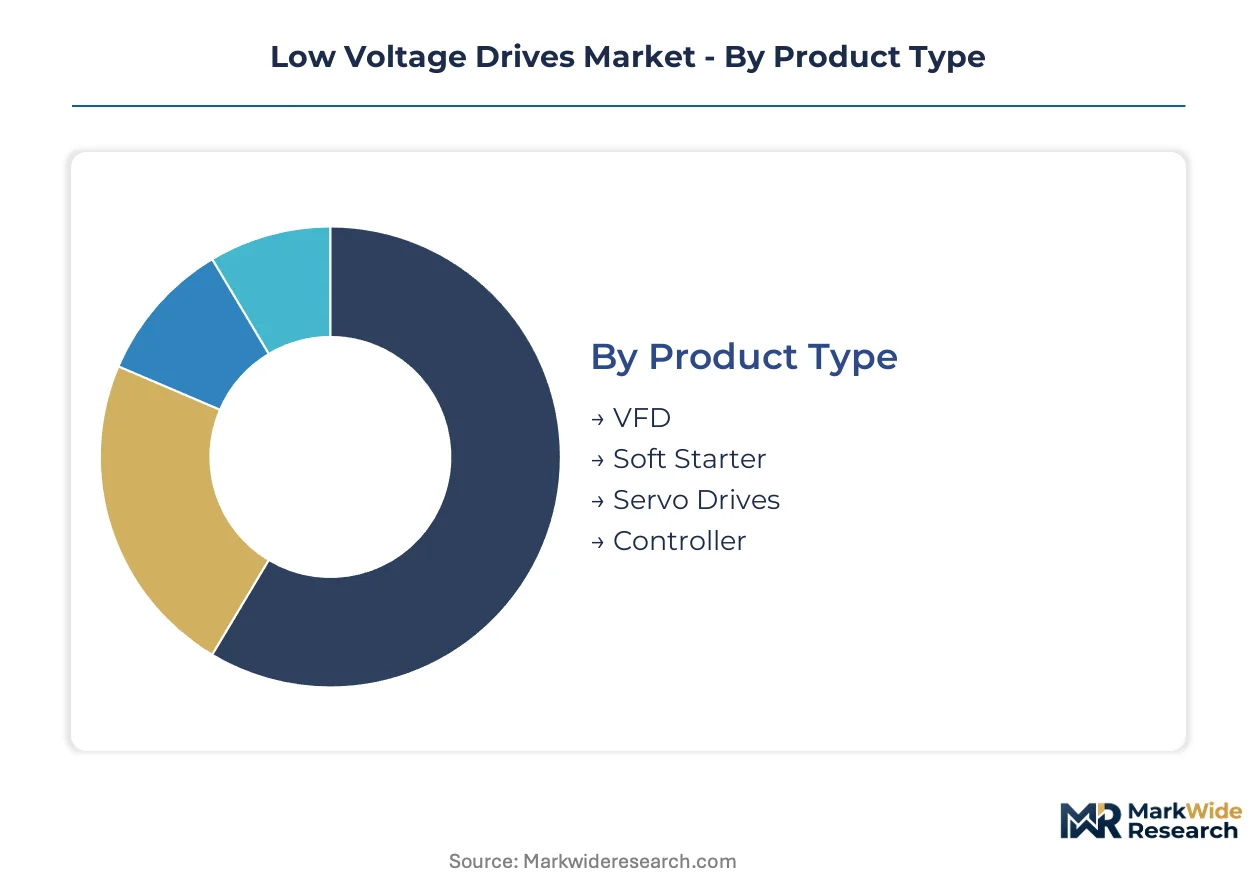
Low voltage drives are power conversion devices operating below 1000V that modulate motor speed and torque through variable frequency control, typically employing insulated-gate bipolar transistor switching at 2-16 kHz carrier frequencies to optimize energy consumption in rotating equipment. Their primary purpose is reducing electricity draw in motor-intensive processes by matching output to variable load conditions. VFD deployments dominate installed base value across manufacturing and water treatment end users where fan and pump modulation delivers the steepest efficiency gains. Servo drives represent the fastest-expanding product category as precision motion control penetrates packaging and material handling lines. Soft starters retain defensive margin pools in mining conveyors where mechanical stress reduction outweighs full variable-speed benefits.
EU Ecodesign Directive efficiency tiers, IEC 61800-9 system standards, and China's GB 30253 motor efficiency mandates collectively tighten minimum performance thresholds for drive-motor combinations sold into regulated channels. EPA energy efficiency guidelines and OSHA electrical safety standards shape compliance costs for US industrial buyers integrating retrofit drive packages. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring product portfolios for cross-border deployment.
Market Dynamics
Municipal water infrastructure retrofits are compressing procurement cycles as EU Ecodesign Directive tiers force simultaneous motor and drive replacements across aging treatment plants.
Growth Catalysts
- IE3/IE4 Motor Mandates:China's GB 30253 efficiency standards and India's BIS regulations compel integrated drive-motor upgrades in process industries, expanding addressable equipment bases.
- Pump Station Modernization:Water treatment utilities across Germany, the United States, and China accelerate VFD deployments to meet energy efficiency mandates and reduce operational expenditure.
- Servo Drive Penetration:Packaging and material handling lines adopt precision motion control for higher throughput, displacing mechanical transmission systems in high-speed applications.
Market Restraints
- IGBT Supply Concentration:Power semiconductor fabrication concentrates in East Asian foundries, exposing drive manufacturers to input volatility and extended lead times.
- Copper and Rare Earth Magnet Costs:Motor core materials face commodity price swings that compress margins on integrated drive-motor packages.
- Legacy System Inertia:Mining and heavy process facilities retain soft starters and direct-on-line starters where mechanical stress reduction outweighs variable-speed efficiency gains.
Strategic Opportunities
- Decentralized Drive Architectures:Pumping applications in distributed water networks adopt motor-mounted drives, eliminating control cabinet infrastructure and reducing installation labor.
- Digital Twin Integration:Predictive maintenance platforms converge with drive systems to enable condition-based service models in continuous process industries.
- India Industrial Retrofit Wave:Bureau of Energy Efficiency Perform Achieve and Trade scheme creates compliance-driven demand for efficiency-class drive installations in textile and cement plants.
Industry Challenges
- IEC 61800-9-2 Certification Timelines:Extended type-testing protocols for system-level efficiency ratings delay product launches and fragment regional variant portfolios.
- Power Electronics Talent Scarcity:Shortage of engineers proficient in electromagnetic compatibility design and thermal management constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage Drives Market |
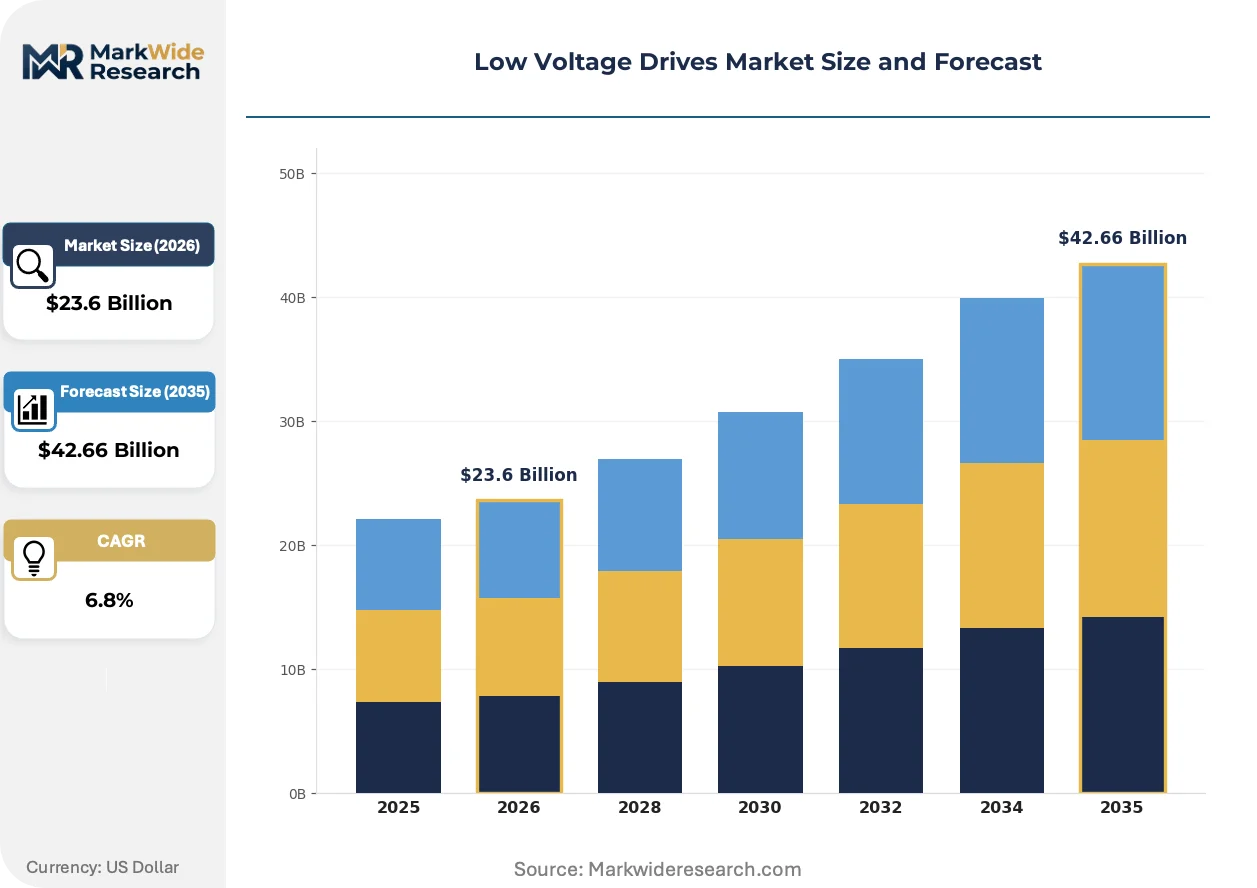
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VFD, Soft Starter, Servo Drives, Controller End User: Manufacturing, Oil & Gas, Mining, Water Treatment Technology: Analog, Digital, Microcontroller, PLC Application: Pumps, Fans, Conveyors, Compressors |
| Companies Covered | ABB, Siemens, Schneider Electric, Danfoss, Yaskawa Electric, Rockwell Automation, Mitsubishi Electric, WEG, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage Drives Market Emerging Trajectories
Silicon carbide power semiconductors and edge-native control platforms are redrawing performance benchmarks and procurement criteria across industrial drive applications.
Silicon carbide MOSFETs enable higher switching frequencies and reduced thermal losses in compact drive packages. Packaging machinery OEMs in Germany and Japan adopt these devices for servo systems requiring sub-millisecond response. The technology is fragmenting established IGBT supply relationships as device sourcing shifts to specialized wide-bandgap foundries.
The EU Ecodesign Directive's 2023 tier expansion mandates IE4-equivalent system efficiency for motors above 0.75kW. Drive manufacturers must recalibrate control algorithms and thermal designs to maintain compliance margins. Water treatment procurement in France and the Netherlands now specifies system-level efficiency certificates, filtering supplier pools.
After-sales service unbundling accelerates as end-users separate hardware procurement from maintenance contracts. Large manufacturing groups in the United States negotiate multi-site drive monitoring agreements independent of original equipment purchases. This pattern concentrates in automotive and food processing verticals with standardized asset bases.
Low Voltage Drives Market Segmentation
Low voltage drives serve heterogeneous load profiles across industrial infrastructure, requiring granular segmentation to match control architectures with torque demands, duty cycles, and regulatory compliance tiers. Procurement specifications diver sharply between municipal water utilities seeking IE4-equivalent system efficiency and mining operators prioritizing mechanical stress mitigation over variable-speed returns.
Product Type:
EU Ecodesign Directive tiers and China's GB 30253 standards impose divergent efficiency certification burdens across drive architectures, fragmenting platform standardization economics.
- VFD:Variable frequency drives modulate motor speed through IGBT-based power conversion at 2-16 kHz carrier frequencies, optimizing energy draw in fan and pump applications. Water treatment utilities in Germany and the United States deploy these units to meet tightening efficiency mandates while reducing operational expenditure.
- Servo Drives:Precision motion control systems deliver sub-millisecond response for positioning applications through closed-loop feedback architectures. Packaging machinery OEMs in Germany and Japan adopt silicon carbide-enabled variants for higher switching frequencies and compact thermal footprints.
- Soft Starter:Reduced-voltage starting devices limit mechanical stress and inrush current without full variable-speed capability.
- Controller:Integrated control platforms combine drive logic with process automation interfaces.
VFD handles the majority of throughput; servo drives are gaining share fastest on precision automation demand.
End User:
Capital intensity and retrofit cycles vary dramatically across verticals, with process industries facing accelerated replacement timelines under efficiency regulations.
- Water Treatment:Municipal infrastructure retrofits across France, the Netherlands, and the United States compress procurement cycles as IE4-equivalent system mandates force simultaneous motor and drive replacements. Procurement specifications now require system-level efficiency certificates, filtering supplier pools.
- Manufacturing:Discrete production lines deploy drives across material handling, machining, and assembly operations with varying duty cycle requirements.
- Mining:Heavy conveyors and crushers retain soft starters where mechanical stress reduction outweighs variable-speed efficiency gains.
- Oil & Gas:Upstream and midstream pumping applications face hazardous area certification requirements and extended asset lifecycles.
Water treatment commands the steepest near-term volume expansion; manufacturing offers the broadest installed base for aftermarket conversion.
Technology:
Control platform selection trades off deterministic response against integration complexity and legacy system compatibility.
- Digital:Microprocessor-based architectures enable parameter-driven configuration and network connectivity for Industry 4.0 integration.
- Microcontroller:Embedded control systems balance cost and functionality for standardized pump and fan applications.
- PLC:Programmable logic controller integration suits complex multi-axis coordination in material handling lines.
- Analog:Legacy voltage and current signal interfaces persist in retrofit installations where digital infrastructure remains absent.
Digital platforms anchor new specification activity; microcontroller solutions dominate volume shipments on cost optimization.
Application:
Load characteristics dictate drive sizing, thermal design, and control algorithm selection across rotating equipment categories.
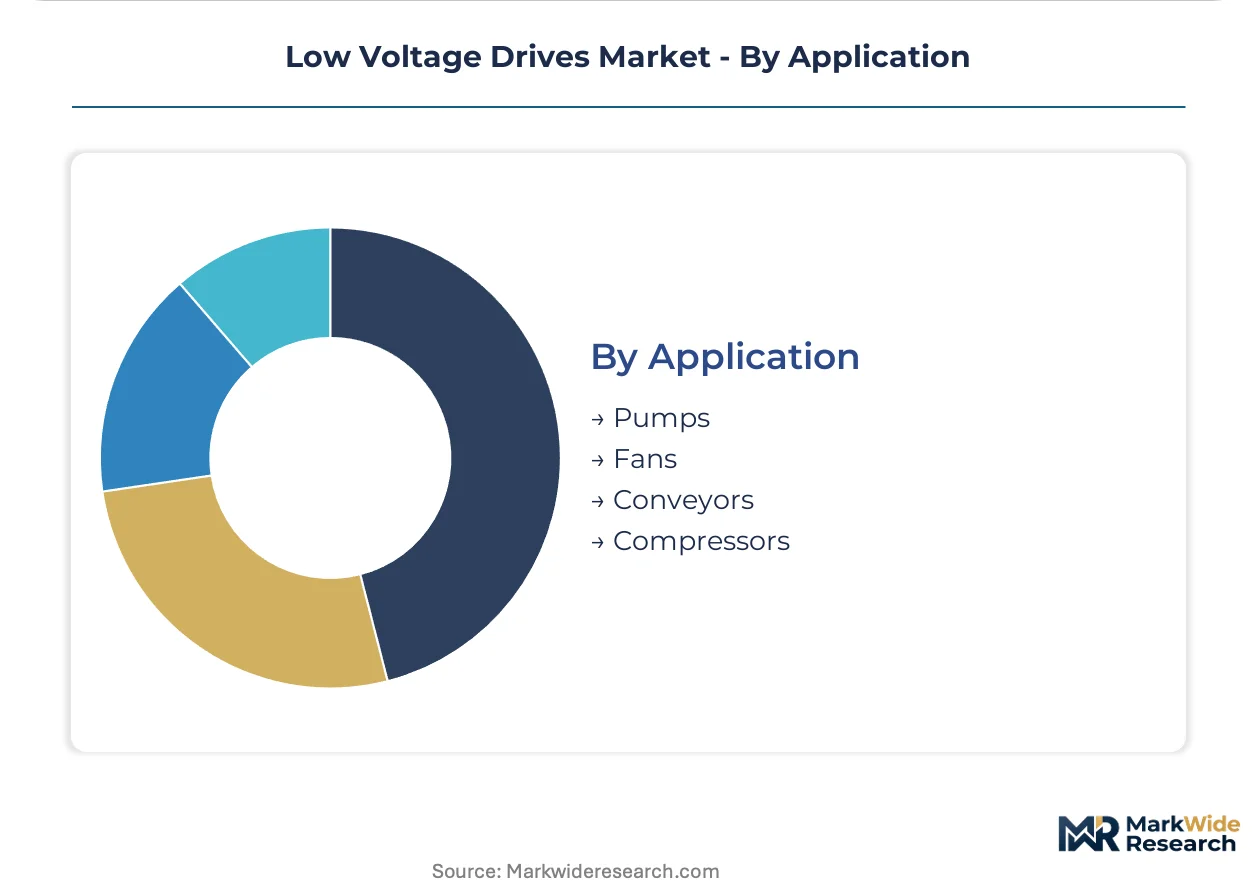
- Pumps:Centrifugal and positive displacement pumping in water distribution and process industries constitutes the largest addressable load category. Decentralized motor-mounted architectures eliminate control cabinet infrastructure in distributed networks.
- Fans:HVAC and industrial ventilation systems present quadratic torque curves optimized for variable-frequency modulation.
- Conveyors:Constant torque demands with high starting current requirements favor soft starters or heavy-duty VFD configurations.
- Compressors:Rotary and reciprocating compression equipment requires specialized control for surge protection and load sharing.
Pump applications generate the dominant revenue share; compressor deployments show the most rapid specification upgrading on energy audit prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Chinese manufacturers dominate export flows into United States municipal water infrastructure and Southeast Asian manufacturing hubs. Trade corridors channel high-efficiency drive systems toward regulated markets while cost-optimized variants serve emerging industrial clusters.
United States
EPA energy efficiency guidelines and OSHA electrical safety standards accelerate municipal water treatment retrofits in California and Texas. The Bureau of Reclamation's infrastructure modernization programs compress procurement timelines for IE4-equivalent drive-motor systems. Chicago's metropolitan water reclamation district deploys decentralized architectures across aging pump stations.
Germany
EU Ecodesign Directive tier expansions force simultaneous motor and drive replacements across Bavarian and North Rhine-Westphalian process industries. KBA consultation on industrial equipment efficiency filters supplier pools through system-level certification requirements. Stuttgart's automotive manufacturing corridor adopts silicon carbide-enabled servo systems for precision assembly lines.
China
GB 30253 motor efficiency mandates and MIIT industrial upgrading directives compel integrated drive-motor deployments in Yangtze River Delta textile plants. The country's dual carbon goals tighten operational expenditure pressures on energy-intensive sectors. Shandong Province's cement and chemical clusters retrofit aging fixed-speed infrastructure with variable frequency control.
India
Bureau of Energy Efficiency Perform Achieve and Trade scheme creates compliance-driven demand in Gujarat and Maharashtra textile operations. BIS efficiency regulations align with state-level industrial policy incentives for equipment modernization. Tamil Nadu's automotive component suppliers adopt precision motion control for export-oriented production lines.
Japan
METI energy conservation standards and JIS certification requirements shape premium-tier procurement in Kansai region packaging machinery. The country's semiconductor equipment sector drives sub-millisecond response specifications for servo drive architectures. Nagoya's industrial automation cluster integrates edge-native control platforms with legacy manufacturing infrastructure.
Low Voltage Drives Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base concentrates around integrated automation conglomerates and power electronics specialists with divergent route-to-market strategies. Three archetypes dominate: diversified industrial technology groups, dedicated motion control specialists, and regional electromechanical fabricators. Competitive moves center on digital twin integration partnerships and silicon carbide supply chain anchoring.
Among Swiss-Swedish and German industrial technology groups, ABB and Siemens occupy positions exemplifying integrated automation portfolio breadth. Danfoss represents the dedicated power electronics specialist archetype with focused pumping application expertise. These three entities anchor tiered competitive positioning across municipal infrastructure and discrete manufacturing verticals.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Danfoss |
| Yaskawa Electric |
| Rockwell Automation |
| Mitsubishi Electric |
| WEG |
| Nidec Corporation |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign Directive certification tiers gate both supplier qualification and price differentiation simultaneously, forcing drive manufacturers to recalibrate thermal designs and control algorithms to maintain compliance margins while water treatment utilities filter procurement pools through system-level efficiency certificates.
Pricing Analysis
IGBT-based variable frequency drives, silicon carbide-enabled servo systems, and legacy analog control platforms occupy distinct pricing strata based on switching frequency performance and thermal efficiency ratings. Pricing stratifies across premium, standard, and economy tiers where IEC 61800-9-2 system certification and GB 30253 compliance grade anchor differentiation. Cost compression in standard-tier VFDs is intensifying because East Asian foundry concentration extends lead times and input volatility. Municipal water utilities in Germany and France exhibit the highest price sensitivity due to budget-constrained retrofit cycles, while semiconductor equipment OEMs in Japan tolerate premium positioning for sub-millisecond response specifications.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes compound inbound logistics costs for power semiconductor modules and rare earth magnet shipments. Power electronics fabrication concentrates in China, Taiwan, and South Korea, while copper winding materials and insulated-gate bipolar transistor substrates draw from Chilean mining operations and Japanese metallurgical processing. Single-source vulnerability in wide-bandgap silicon carbide wafer supply exposes drive manufacturers to allocation constraints as packaging machinery OEMs accelerate adoption. Distribution runs through authorized industrial automation distributors and direct OEM procurement channels, with aftermarket service contracts increasingly unbundled from hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large manufacturing groups negotiating multi-site monitoring agreements, fragmenting supplier pricing leverage as end-users separate hardware procurement from maintenance contracts.
For Market Incumbents: Compound defensive positioning through backward integration into silicon carbide wafer sourcing and captive IGBT module production to offset East Asian foundry concentration risks. Anchor certification investment in IEC 61800-9-2 system-level efficiency ratings to defend margin pools against emerging power electronics specialists attacking standard-tier VFD segments. For New Entrants and Emerging Players: Predictive maintenance platform integration represents a service-layer gap where incumbents under-serve continuous process industries with legacy asset bases. Target decentralized motor-mounted drive architectures in distributed water networks where installation labor reduction outweighs brand preference. Pursue digital twin partnerships with municipal infrastructure operators as a go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide-enabled servo drive manufacturing as wide-bandgap foundry capacity constraints tighten equipment procurement cycles. Acquisition targets should emphasize power electronics specialists with electromagnetic compatibility design capabilities and existing pumping application expertise. Monitor Bureau of Energy Efficiency enforcement intensity in Indian textile and cement clusters as an inflection indicator for compliance-driven retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Anchoring | Long-term wafer supply agreements with Taiwanese foundries secure switching frequency leadership in servo systems. |
| Digital Twin Integration Partnership | Predictive maintenance platforms with German automotive OEMs enable condition-based service revenue streams. |
| Decentralized Drive Architecture Development | Motor-mounted control eliminates cabinet infrastructure for French and Dutch water distribution networks. |
| IEC 61800-9-2 Certification Investment | System-level efficiency testing capabilities filter competitor pools in EU municipal procurement. |
| India Industrial Retrofit Channel Buildout | Perform Achieve and Trade scheme compliance creates textile and cement plant specification access. |
Methodological Framework
Desk research of trade association technical publications, customs shipment records, and regulatory filing databases preceded structured interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and water utility engineering managers. Primary fieldwork across German process industries, Chinese Yangtze River Delta manufacturing clusters, and United States municipal infrastructure operators combined with secondary validation from SEC 10-K filings, IEC standard documentation, and Bureau of Energy Efficiency program disclosures. Bottom-up equipment shipment analysis and top-down energy efficiency mandate impact modeling were triangulated to derive market estimates.
Variance decomposition across product type, end-use vertical, control technology, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segment-level CAGRs were derived from retrofit cycle compression rates, efficiency mandate phase-in schedules, and power semiconductor adoption curves. Forecast inputs incorporated pump station modernization program announcements, MIIT industrial upgrading directive enforcement patterns, and servo drive penetration rates in packaging machinery OEM specifications.
Forecasts assume regulatory continuity in EU Ecodesign Directive tier expansions, China's GB 30253 efficiency mandates, and India's Perform Achieve and Trade scheme; material policy shifts would require re-modeling. Commodity price volatility in copper and rare earth magnets, alongside wide-bandgap semiconductor supply disruptions, represent specific risk factors that could revise outlooks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Modular Inverter Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Battery Equalizer Market
Power Systems
South America DC Distribution Network Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Voltage Stabilizer System Market