
 Asia-Pacific Gamma Butyrolactone Market | 2026-2036
Asia-Pacific Gamma Butyrolactone Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gamma Butyrolactone Market Outlook
Buyer concentration among pharmaceutical companies is rebalancing as mid-size API manufacturers in India and Southeast Asia diversify their solvent suppliers away from dominant Chinese producers. Mitsubishi Chemical Group Corporation anchors high-purity pharmaceutical grade supply through integrated acetylene-based production in Japan. Dairen Chemical Corporation leverages its Taiwanese manufacturing base to serve electronics solvent demand across the region. Zhejiang Realsun Chemical Co., Ltd. competes on industrial grade volume, sustaining cost leadership through captive butanediol feedstock.
Gamma butyrolactone is a hygroscopic cyclic ester with a boiling point of 204°C, synthesized primarily via dehydrogenation of 1,4-butanediol over copper-chromite catalysts, serving as a versatile protic solvent and chemical intermediate across polymer, pharmaceutical, and electronics manufacturing. Industrial grade GBL dominates volume flows, though pharmaceutical grade commands premium pricing due to stringent residual impurity limits and CDSCO or NMPA certification requirements. Solvent applications lead absolute consumption, while intermediate use for N-methylpyrrolidone and pyrrolidone derivatives represents the fastest-expanding segment as lithium-ion battery manufacturing scales across South Korea and China.
China's MEE enforces wastewater discharge and VOC emission thresholds that constrain smaller GBL producers, while India's CDSCO mandates impurity profiling for pharmaceutical grade imports under its Drugs and Cosmetics Act. Japan's METI classifies GBL as a designated substance, requiring transaction records that shape cross-border trade documentation. Stakeholders must monitor how divergent national chemical control regimes affect inventory positioning and contract structuring across the region.
Market Dynamics
China's dual carbon goals and MEE environmental enforcement are compressing petrochemical-derived solvent production permits, forcing capacity consolidation around Shanghai and Ningbo while rerouting procurement flows toward acetylene-based and bio-based alternatives.
Growth Catalysts
- Lithium-ion battery manufacturing:N-methylpyrrolidone demand from South Korean and Chinese cell producers is pulling GBL intermediate consumption upward as gigafactory construction accelerates.
- CDSCO pharmaceutical grade certification:Indian API manufacturers are expanding GBL procurement for active pharmaceutical ingredient synthesis under stricter impurity profiling mandates.
- Acetylene-based production:Japanese integrated chemical producers are capturing premium pharmaceutical grade share through cleaner feedstock chemistry that satisfies residual solvent limits.
Market Restraints
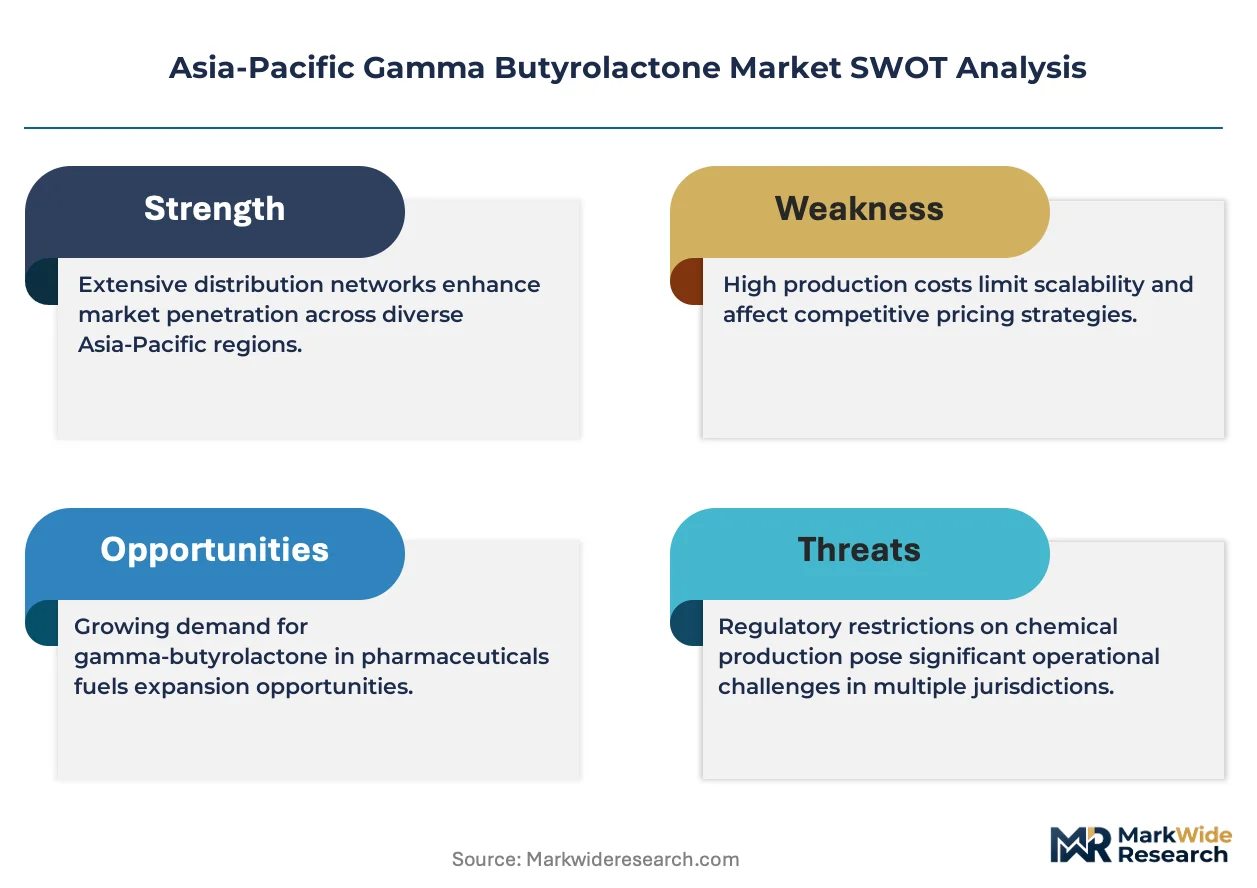
- 1,4-butanediol feedstock volatility:Petrochemical route dependency exposes producers to naphtha and propylene price swings that compress margin visibility.
- Shanghai-Ningbo supply concentration:Eastern China's chemical manufacturing clusters concentrate 60-plus percent of regional capacity, creating single-point vulnerability to MEE enforcement actions.
- Biobased solvent substitution:Electronics manufacturers are piloting 2-methyltetrahydrofuran and other renewable alternatives for precision cleaning applications.
Strategic Opportunities
- Southeast Asia API manufacturing:Vietnam and Indonesia pharmaceutical sectors remain underpenetrated for pharmaceutical grade GBL, offering first-mover positioning as CDSCO-aligned facilities relocate.
- MEE carbon intensity benchmarking:China's dual carbon goals create regulatory tailwind for producers with verified low-emission acetylene or bio-based process routes.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume pharmaceutical and electronics solvent buyers.
Industry Challenges
- CDSCO-NMPA certification timeline compression:Pharmaceutical grade qualification requires 18-24 month impurity profiling cycles that delay revenue recognition for new market entrants.
- Catalyst regeneration capex:Copper-chromite dehydrogenation catalyst replacement and spent catalyst hazardous waste handling require continuous capital deployment that strains smaller producers.
- Cross-border documentation complexity:Japan's METI designated substance transaction records create compliance friction for inventory positioning across multi-country supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gamma Butyrolactone Market |
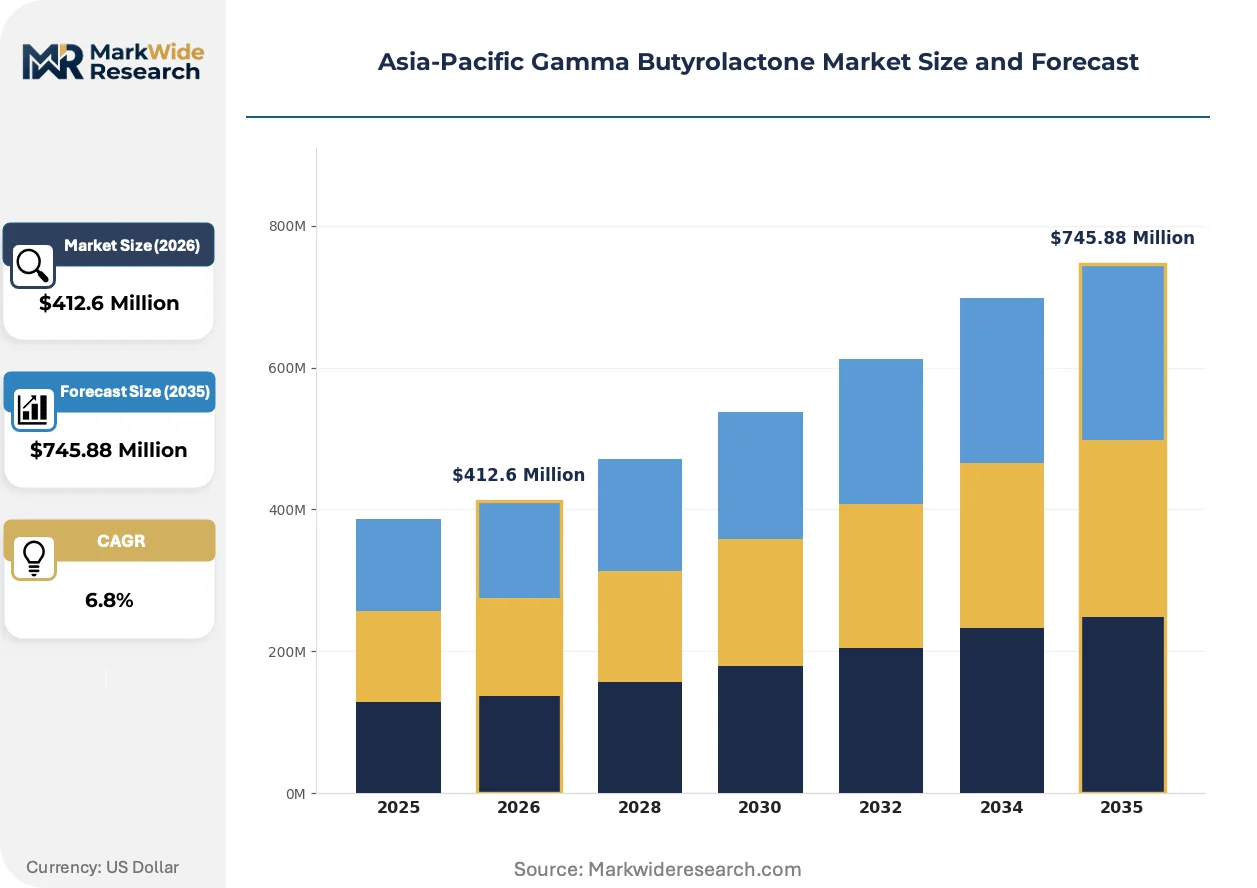
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Food Grade Application: Solvent, Intermediate, Chemical Reagent, Plasticizer End User: Chemical Industry, Pharmaceutical Companies, Cosmetics Manufacturers, Food Processing Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Zhejiang Realsun Chemical Co., Ltd., Boai NKY Pharmaceuticals Ltd., Taj Pharmaceuticals Limited, Chengda Pharmaceuticals, Changxin Chemical Science-Tech Co., Ltd., Mitsubishi Chemical Group Corporation, Dairen Chemical Corporation, BALAJI AMINES, Panax Etec Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gamma Butyrolactone Market Strategic Shifts
Electrification of chemical process heating and solvent recovery systems is reshaping production economics, while regulatory carbon accounting and buyer certification requirements are rewriting qualification protocols across the Asia-Pacific region.
Membrane-based solvent recovery technology is electrifying energy-intensive distillation operations in GBL purification stages. South Korean electronics solvent users are adopting ceramic membrane systems at pilot scale, cutting steam consumption by half while meeting SEMI residual purity specifications. This electrification is compressing the cost gap between virgin and recycled pharmaceutical grade material.
China's MEE is enforcing wastewater discharge and VOC emission thresholds that constrain smaller dehydrogenation unit operators. The industrial consequence is permit non-renewal for facilities lacking closed-loop catalyst regeneration or vapor recovery systems. Pharmaceutical grade producers with verified environmental management systems are capturing contract volume from formulators facing ESG audit pressure.
Certificate-of-analysis-driven supplier selection is displacing price-first procurement in Indian and Southeast Asian API manufacturing. Formulators are unbundling solvent supply from traditional full-service distributors, instead contracting directly with producers holding CDSCO or NMPA pharmaceutical grade certifications. This behavioral shift is most visible in Hyderabad and Ahmedabad clusters where multinational pharmaceutical quality audits have intensified.
Asia-Pacific Gamma Butyrolactone Market Segmentation
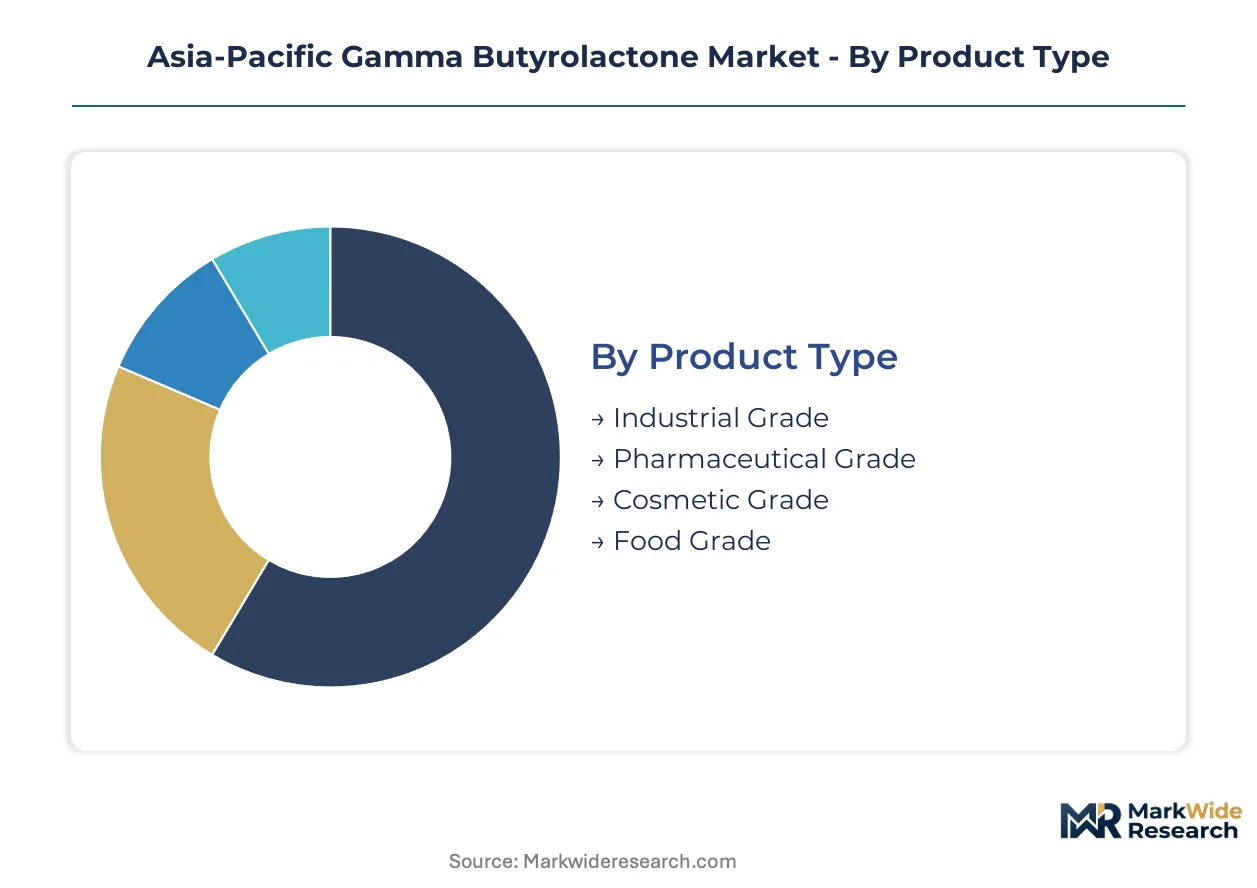
Gamma butyrolactone procurement patterns diverge sharply across purity grades and end-use specifications, with pharmaceutical certification requirements and battery manufacturing purity thresholds creating distinct commercial lanes. Segmentation clarity enables suppliers to align catalyst selection, impurity profiling investment, and distribution infrastructure with buyer technical requirements.
Product Type:
Standardization dominates at the industrial end of the spectrum, while pharmaceutical and food grades demand batch-level customization and regulatory documentation.
- Industrial Grade:Copper-chromite dehydrogenation yields material with higher residual aldehyde and moisture content, acceptable for polymer synthesis and general solvent applications. Chemical manufacturers around Shanghai and Ningbo absorb the majority of regional volume, though MEE wastewater enforcement is compressing smaller producer margins.
- Pharmaceutical Grade:Stringent residual solvent limits under CDSCO and NMPA guidelines necessitate dedicated distillation trains and certificate-of-analysis documentation for every lot. Indian API manufacturers in Hyderabad and Ahmedabad clusters are expanding procurement as multinational quality audits intensify impurity profiling requirements.
- Cosmetic Grade:Intermediate purity tier serving personal care formulators with controlled heavy metal specifications.
- Food Grade:Smallest volume category requiring compliance with national food safety regulator standards for flavor and fragrance applications.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Volume concentration versus value capture splits this category, with intermediate applications commanding technical premiums while solvent uses drive absolute tonnage.
- Solvent:Protic solvent properties support polymer dissolution, paint stripping, and electronics cleaning across industrial manufacturing. South Korean and Chinese electronics fabs represent concentrated demand as semiconductor and display panel production scales.
- Intermediate:Dehydrogenation to N-methylpyrrolidone for lithium-ion battery electrode manufacturing is pulling GBL consumption upward. South Korean cell producers and Chinese gigafactory construction are expanding NMP demand fastest.
- Chemical Reagent:Laboratory and specialized synthesis applications requiring high purity and consistent lot-to-lot behavior.
- Plasticizer:Minor application in polymer flexibility modification, facing substitution pressure from phthalate-free alternatives.
Solvent applications anchor current volume. Intermediate use is climbing the fastest as battery manufacturing scales.
End User:
Buyer sophistication and certification requirements stratify this category, from commodity chemical procurement to audited pharmaceutical supply chains.
- Chemical Industry:Broad-base consumption across polymer, coating, and adhesive manufacturing with price-sensitive procurement patterns.
- Pharmaceutical Companies:CDSCO-mandated impurity profiling and 18-24 month qualification cycles create high switching costs. Indian API manufacturers are diversifying supplier bases away from dominant Chinese producers.
- Cosmetics Manufacturers:Formulators seeking residual solvent documentation for personal care product safety assessments.
- Food Processing:Niche flavor and extraction applications with national food safety regulator compliance requirements.
Chemical Industry channels the majority of current offtake. Pharmaceutical Companies are gaining share fastest as API manufacturing relocates to India and Southeast Asia.
Distribution Channel:
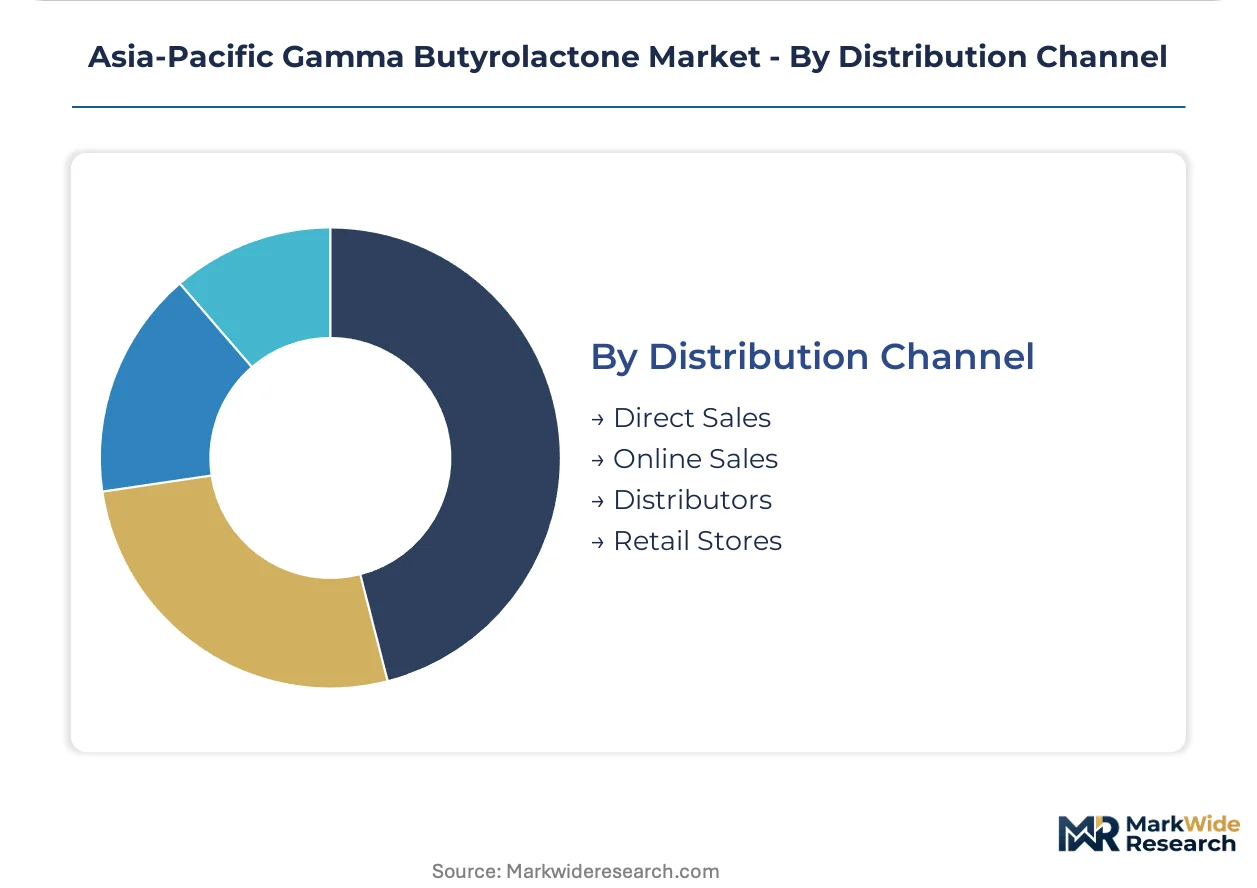
Relationship intensity and technical service requirements shape channel selection, with certified grades demanding direct producer engagement.
- Direct Sales:Pharmaceutical and electronics grade buyers contract directly with producers holding CDSCO, NMPA, or SEMI certifications, bypassing traditional distributor markups. Certificate-of-analysis documentation and audit trails favor this channel for regulated applications.
- Distributors:Industrial grade volume moves through regional chemical distributors with stocking positions in Shanghai, Mumbai, and Singapore. Consolidation among distributors is reducing supplier optionality for mid-size buyers.
- Online Sales:Emerging channel for standardized industrial grades and small-lot reagent sales, with specialty chemical platforms disintermediating traditional networks.
- Retail Stores:Minimal presence, limited to laboratory supply outlets for reagent-grade small packaging.
Direct Sales commands the highest value flows. Online Sales is expanding most quickly as digital procurement platforms penetrate mid-volume buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and process technicians concentrate in eastern China's manufacturing corridors, anchoring regional production capacity for dehydrogenation-based GBL synthesis across the Asia-Pacific.
China
Lithium-ion battery gigafactory construction and N-methylpyrrolidone intermediate demand are pulling GBL consumption upward in Jiangsu and Zhejiang provinces. MEE enforcement of wastewater discharge thresholds is compressing smaller dehydrogenation unit operators. Chemical manufacturing clusters around Shanghai and Ningbo concentrate over sixty percent of national capacity as permit non-renewal forces consolidation.
Japan
Pharmaceutical grade GBL production serves domestic API manufacturers and export markets through acetylene-based feedstock chemistry. METI designated substance transaction record requirements shape cross-border trade documentation and inventory positioning. Integrated chemical producers in the Kanto region around Tokyo maintain high-purity supply chains for residual-sensitive applications.
India
API manufacturing expansion in Hyderabad and Ahmedabad clusters is expanding pharmaceutical grade GBL procurement under CDSCO-mandated impurity profiling. Multinational pharmaceutical quality audits are intensifying certificate-of-analysis requirements for solvent suppliers. Domestic producers and importers are diversifying supply bases away from dominant Chinese sources.
South Korea
Electronics solvent demand from semiconductor and display panel fabs anchors industrial grade consumption in the Seoul Capital Area and Busan-Ulsan corridor. Lithium-ion battery cell producers are scaling N-methylpyrrolidone intermediate demand as domestic gigafactory construction accelerates. Ceramic membrane solvent recovery pilot installations are cutting steam consumption in purification operations.
Taiwan
Electronics manufacturing precision cleaning applications drive pharmaceutical grade solvent procurement from domestic and Japanese suppliers. Dairen Chemical Corporation anchors regional supply through integrated manufacturing serving display panel and semiconductor fabricators. The island's chemical sector is positioning for battery material intermediate demand as regional cell production scales.
Asia-Pacific Gamma Butyrolactone Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific GBL market, creating a tiered structure where scale-driven industrial grade producers coexist with certification-heavy pharmaceutical grade suppliers. Japanese integrated chemical groups and Chinese petrochemical operators anchor opposite ends of the purity spectrum. Three archetypes dominate: acetylene-based premium producers, BDO-integrated volume players, and regional distributors with stocking positions. Capacity consolidation and direct-to-formulator channel expansion represent the dominant competitive moves as environmental enforcement tightens.
Among Japanese-based integrated producers, Mitsubishi Chemical Group Corporation exemplifies the acetylene-based pharmaceutical grade archetype through cleaner feedstock chemistry satisfying residual solvent limits. Zhejiang Realsun Chemical Co., Ltd. occupies a position within the BDO-integrated volume tier, sustaining cost leadership through captive butanediol feedstock access. Dairen Chemical Corporation represents the Taiwan-based electronics solvent specialist, leveraging geographic proximity to semiconductor and display manufacturing clusters across the region.
| Leading Market Players |
|---|
| Zhejiang Realsun Chemical Co., Ltd. |
| Boai NKY Pharmaceuticals Ltd. |
| Taj Pharmaceuticals Limited |
| Chengda Pharmaceuticals |
| Changxin Chemical Science-Tech Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Dairen Chemical Corporation |
| BALAJI AMINES |
| Panax Etec Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap producers across eastern China anchor regional supply discipline through captive 1,4-butanediol feedstock access, translating upstream cost control into pricing power over industrial grade spot buyers while pharmaceutical grade premiums reflect certification investment recovery timelines.
Pricing Analysis
Bundled technical service contracts dominate pharmaceutical grade procurement, while unbundled spot transactions govern industrial grade flows. Three-tier pricing structure across pharmaceutical, industrial, and reagent grades reflects residual impurity limits and CDSCO documentation requirements. Pricing pressure stems from MEE permit non-renewals compressing smaller producer margins. Industrial grade buyers in polymer manufacturing exhibit highest price sensitivity, while pharmaceutical formulators absorb premiums for certified supply security.
Supply Chain Analysis
Single-source vulnerability sits with eastern China's Shanghai-Ningbo corridor, where MEE enforcement actions risk concentrated disruption. Manufacturing draws from China, Japan, and India, with 1,4-butanediol feedstock, copper-chromite catalysts, and acetylene feedstock anchoring input dependencies. Tariff exposure on cross-border pharmaceutical grade flows compounds regulatory documentation friction from Japan's METI transaction records. Distribution runs through direct producer relationships for certified grades and regional chemical distributors for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Gamma Butyrolactone Market functions as a stable compounder, with lithium-ion battery manufacturing scaling N-methylpyrrolidone intermediate demand through successive capacity cycles.
For Market Incumbents: Deploy acetylene-based process certification to capture pharmaceutical grade premiums as CDSCO impurity profiling mandates intensify. Deepen captive butanediol integration to defend margin position against naphtha price volatility. Consolidate around Shanghai-Ningbo clusters ahead of MEE permit renewal deadlines.
For New Entrants and Emerging Players: Launch via direct-to-formulator digital channels targeting mid-volume pharmaceutical buyers in Hyderabad and Ahmedabad. Vietnam and Indonesia API manufacturing relocation offers first-mover positioning for CDSCO-aligned facilities. Bio-based process routes attract ESG-audited contract volume.
For Investors and Strategic Acquirers: Japanese integrated chemical groups are the most active acquirer in this space, seeking pharmaceutical grade capacity with verified environmental management systems. Target producers with acetylene-based feedstock flexibility and existing NMPA or CDSCO certifications. Watch ceramic membrane solvent recovery adoption rates as electrification inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 1,4-Butanediol | Captive feedstock access insulates margin from naphtha volatility in Shanghai-Ningbo clusters. |
| Pharmaceutical Grade Certification Investment | CDSCO-aligned impurity profiling opens contract volume from multinational API quality audits. |
| Ceramic Membrane Solvent Recovery Installation | Electrified purification cuts steam consumption for South Korean electronics solvent users. |
| Direct-to-Formulator Digital Channel Launch | Specialty chemical platforms disintermediate distributor markups for mid-volume pharmaceutical buyers. |
| Acetylene-Based Process Route Conversion | Cleaner feedstock chemistry satisfies residual solvent limits for premium pharmaceutical grade supply. |
Study Parameters
Coverage spans China, Japan, India, South Korea, and Taiwan, with primary inputs from each market through structured interviews with plant managers at dehydrogenation facilities, procurement leads at downstream API manufacturers, distribution channel partners in Mumbai and Singapore, and technical R&D directors at integrated chemical groups. Secondary validation draws from MEE discharge filings, CDSCO import certifications, SEC 10-K disclosures by listed chemical producers, and customs trade data. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Granularity-level modeling distinguishes pharmaceutical, industrial, cosmetic, and food grades by purity threshold, while application-level splits track solvent, intermediate, reagent, and plasticizer end-uses across the projection horizon. End-user segmentation captures chemical industry, pharmaceutical companies, cosmetics manufacturers, and food processing buyers. CAGRs derive from weighted capacity expansion announcements, battery gigafactory construction timelines, and API manufacturing relocation patterns. Forecast inputs include catalyst regeneration cycle economics and membrane technology adoption curves.
Several conditions sit outside the modeled scope, including abrupt MEE regulatory reversals, biobased solvent substitution breakthroughs, and pharmaceutical manufacturing relocation delays. Forecasts reflect documented assumptions about permit renewal trajectories and carbon intensity benchmarking implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fluoroboric Acid Market
Chemicals
Iscotrizinol Market
Chemicals
De-Icing Agents Market
Chemicals
Global Bleaching Agents Market
Chemicals
Selenium Sulfide Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Periodic Acid Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Sodium Methoxide Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Tromethamine Market
Chemicals
North America Tartaric Acid Market
Chemicals
Hydrogen Fluoride Pyridine Market