
 Smart Home Hub Market | 2026-2036
Smart Home Hub Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Hub Market Outlook
Matter-certified interoperability is redrawing competitive boundaries in connected living infrastructure. Samsung Electronics leverages its SmartThings ecosystem to anchor hardware-software integration across appliance categories. Amazon.com competes through Alexa's voice-first architecture, while Apple differentiates via privacy-centric HomeKit protocols that control premium segment positioning.
A smart home hub functions as a centralized gateway device aggregating command protocols across disparate IoT endpoints, typically integrating Zigbee, Z-Wave, Thread, or Wi-Fi radios with processor cores managing local automation logic. Voice-assistant hubs currently lead volume shipments as natural-language interfaces lower adoption friction for mainstream consumers. Energy-management applications represent the fastest-expanding use case as utility time-of-use tariffs incentivize automated load shifting.
The Connectivity Standards Alliance administers Matter certification requirements that reshape hardware compatibility mandates across the US, EU, and China. In Europe, GDPR and the EU Cybersecurity Act impose data-localization and encryption standards that elevate compliance costs for cloud-dependent hub architectures. Stakeholders must now decide whether to prioritize open-ecosystem interoperability investments or defend proprietary platform margins as regulatory pressure intensifies on cross-border data flows.
Market Dynamics
The Matter protocol standardization by the Connectivity Standards Alliance is dissolving ecosystem lock-in and forcing hardware vendors to abandon proprietary radio stacks in favor of interoperable Thread and Wi-Fi implementations.
Growth Catalysts
- GDPR and EU Cybersecurity Act:European data-localization mandates elevate compliance costs for cloud-dependent architectures, creating openings for edge-computing hub designs that process automation logic locally.
- Utility time-of-use tariffs:Energy-management applications expand as residential consumers automate load shifting to avoid peak pricing, driving hub adoption for HVAC and EV charger coordination.
- China ecosystem bundling:Mass-market penetration accelerates where smartphone and appliance vendors pre-integrate hub functionality into existing device purchases.
Market Restraints
- Silicon supply concentration:Thread radio chipset availability constrains hub production timelines when foundry capacity tightens for sub-40nm process nodes.
- Legacy Z-Wave stranded assets:Existing installed bases of proprietary mesh networks resist migration to Matter-compatible hardware, delaying replacement cycles.
- Cross-border data friction:China's GB standards for data residency conflict with cloud architectures optimized for US or EU hosting, complicating multinational product strategies.
Strategic Opportunities
- India smart city deployments:Municipal infrastructure projects in Bengaluru and Hyderabad seek centralized building automation platforms that aggregate residential and commercial endpoints.
- Healthcare aging-in-place:Fall detection and medication adherence sensors require hub-based local processing to meet HIPAA requirements for protected health information handling.
- Thread and energy-harvesting sensor convergence:Battery-free environmental monitors eliminate maintenance visits, enabling hub networks in remote vacation properties and agricultural outbuildings.
Industry Challenges
- Matter certification backlog:Testing laboratory capacity constraints delay product launches by four to eight months, compressing selling seasons for holiday-dependent consumer electronics.
- Embedded systems security expertise:Firmware vulnerability remediation requires specialized talent scarce outside semiconductor design hubs in Taiwan and Israel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Hub Market |
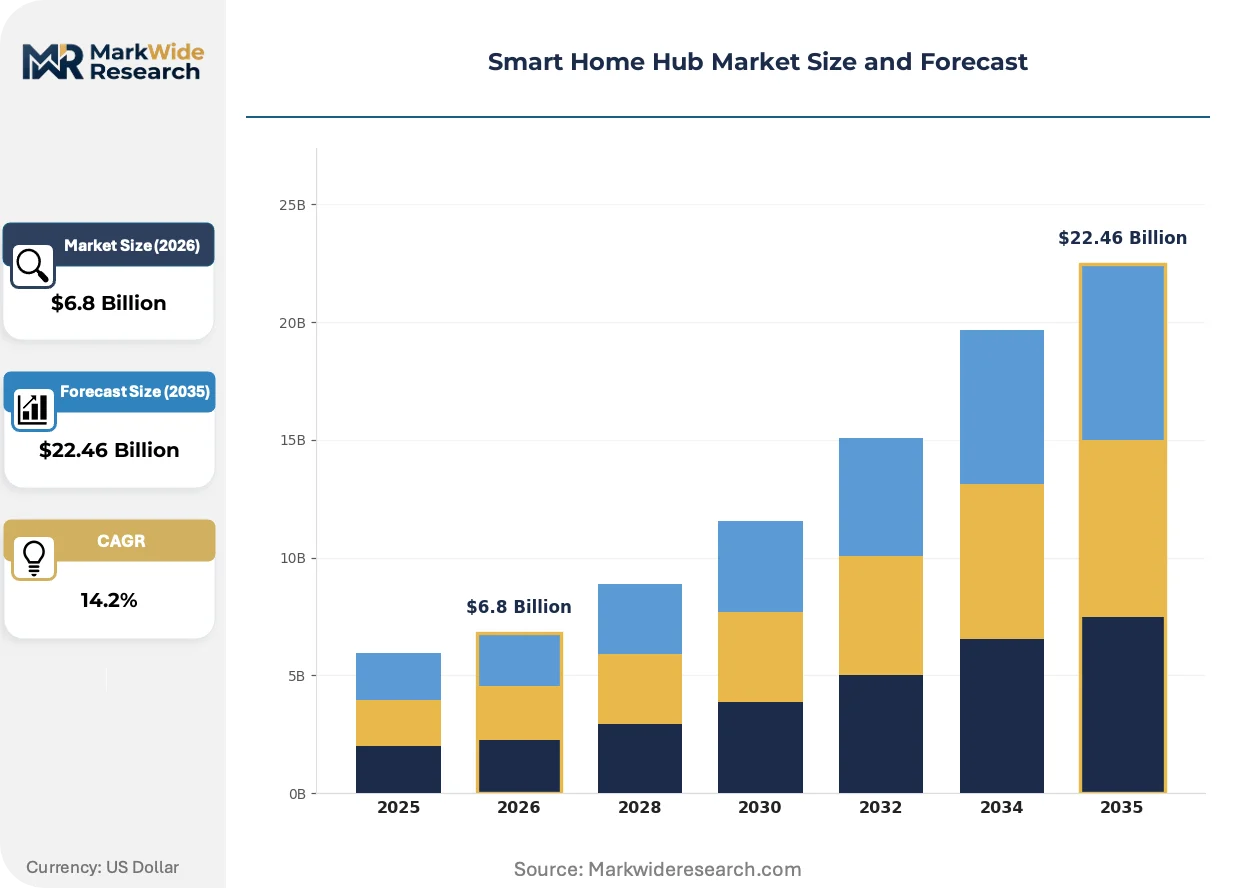
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Displays, Voice Assistants, Central Controllers, Smart Plugs Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential Users, Builders, Contractors, Property Managers Application: Home Automation, Energy Management, Security Monitoring, Entertainment Control |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., Amazon.com, Inc., Vivint LLC, Logitech International S.A., Google LLC, Xiaomi Corporation, Snap One LLC, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Hub Market Strategic Shifts
Voice-first interface architecture is ceding ground to multimodal control as gesture recognition and predictive automation reduce interaction friction for mainstream households.
Edge AI inference engines are bifurcating hub hardware tiers. Premium devices now ship with neural processing units capable of local voice recognition and anomaly detection, while mass-market SKUs offload computation to cloud services. Residential property developers specify NPU-equipped hubs for luxury installations, whereas rental and entry-level housing accepts latency trade-offs for lower hardware costs. This performance gap is compressing mid-tier vendor margins as buyers polarize toward capability extremes.
REACH substance restrictions and F-Gas Regulation in Europe are reshaping thermal design requirements. Hub enclosures must eliminate specific flame retardants and refrigerant-based cooling systems, pushing vendors toward passive heat dissipation architectures. High-density markets in Germany and the Netherlands face the steepest compliance deadlines, accelerating adoption of aluminum unibody construction over plastic assemblies.
Buyer expectations now favor unbundled after-sales service models. Consumers reject mandatory subscription tiers for remote access and firmware updates, pressuring vendors to monetize through hardware margins and optional feature unlocks rather than recurring cloud fees. This shift is most visible in North American direct-to-consumer channels where Amazon and Best Buy return policies amplify switching flexibility.
Smart Home Hub Market Segmentation
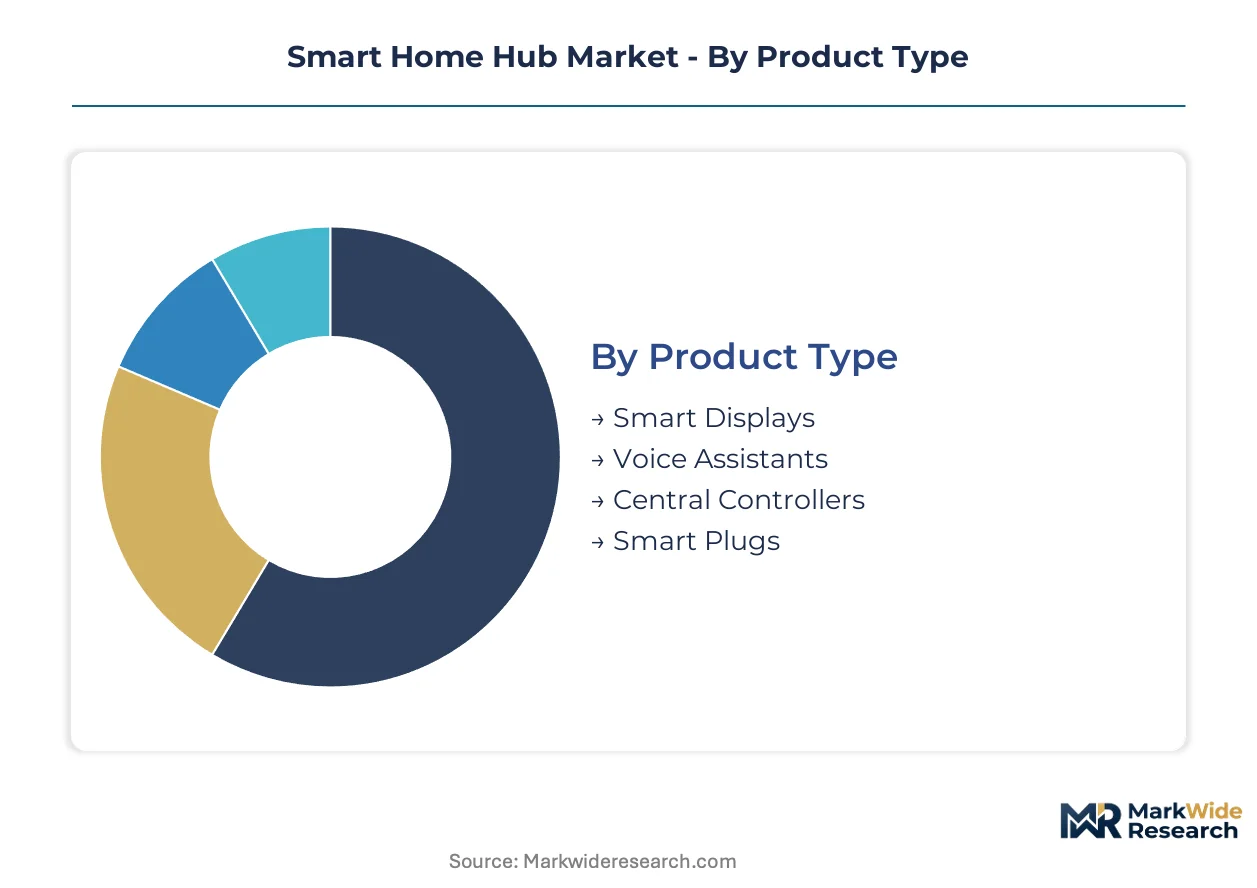
Smart home hub segmentation reveals how hardware specifications, connectivity protocols, and buyer types reshape distribution economics. Channel strategy differs sharply between consumer-direct voice assistants and specification-driven central controllers sold through professional integrators.
Product Type:
Channel mix varies dramatically: voice assistants and smart displays dominate retail and e-commerce, while central controllers flow through professional installation networks and builder specification channels.
- Smart Displays:Touchscreen-enabled hubs combining visual interfaces with voice control, typically featuring 7-10 inch panels running Android or proprietary OS stacks. Demand concentrates in North American and European households where kitchen countertop placement drives replacement of standalone voice speakers. GDPR-compliant local processing variants command specification preference in German and French markets where cloud-averse consumers dominate premium tiers.
- Voice Assistants:Speaker-integrated hubs prioritizing natural-language processing over visual feedback, leveraging far-field microphone arrays for whole-room capture. Mass-market penetration accelerates through Amazon and Google retail bundling, though privacy-conscious segments in California and Washington state increasingly specify edge-only voice processing that eliminates cloud audio transmission.
- Central Controllers:Rack-mounted or in-wall automation processors managing whole-home device orchestration through wired and wireless backbones. Professional integrators in Florida and Texas specify these for luxury residential deployments exceeding 200 connected endpoints.
- Smart Plugs:Outlet-integrated mini-hubs providing single-point control for legacy appliances without native connectivity. Entry-level demand clusters in Chinese urban apartments where renters seek non-permanent automation solutions.
By volume, voice assistants lead. By growth pace, smart displays are expanding most quickly as visual feedback reduces user error in multi-device households.
Technology:
Cost tier separation is pronounced: Wi-Fi and Bluetooth anchor sub-$50 mass-market SKUs, while Zigbee and Z-Wave command 3-4x hardware premiums in professional channels.
- Wi-Fi:Ubiquitous radio protocol leveraging existing home infrastructure, eliminating dedicated gateway requirements for cloud-dependent devices. Ubiquitous deployment in Indian and Brazilian markets where smartphone penetration exceeds dedicated smart home adoption, though 2.4GHz congestion in dense urban clusters drives 5GHz and 6GHz migration in Tokyo and Seoul apartment towers.
- Zigbee:Mesh networking protocol operating in 2.4GHz spectrum with sub-100mW power consumption, enabling battery-powered sensor networks. European energy-management deployments favor Zigbee 3.0 for utility-grade demand response, with E.ON and Enel specifying certified stacks for tariff-responsive load control in German and Italian smart meter rollouts.
- Z-Wave:Sub-GHz proprietary mesh protocol optimized for wall penetration and interference immunity in multi-story construction. Legacy installed bases in US suburban markets resist Matter migration, delaying replacement cycles where 700-series chipsets already deployed.
- Bluetooth:Point-to-point protocol dominating direct-to-device commissioning and temporary guest access scenarios. Matter-over-Bluetooth commissioning flows now standard for initial hub setup, though sustained operation shifts to Thread or Wi-Fi backhaul.
Wi-Fi dominates unit shipments. Zigbee captures the steepest expansion trajectory as utility time-of-use tariffs spread across EU member states.
End User:
Volume concentration sits with residential direct purchasers, though margin pools concentrate in builder and property manager channels where specification lock-in extends replacement cycles.
- Residential Users:Individual consumers purchasing through retail, e-commerce, or carrier channels for self-installation. North American big-box retail drives seasonal volume spikes tied to holiday gifting periods.
- Builders:Production and custom home developers pre-installing hub infrastructure during construction to meet buyer expectations for integrated living. Toll Brothers and Lennar in Arizona and Colorado now specify Matter-certified central controllers as standard in homes above $800,000.
- Contractors:Professional integrators and electricians installing hub systems in retrofit and renovation scenarios. CEDIA-certified firms in Georgia and North Carolina specialize in whole-home automation exceeding 500 endpoints.
- Property Managers:Multi-family housing operators deploying hub networks for centralized building automation and tenant amenity differentiation. Greystar and AvalonBay pilot hub-based energy submetering in Texas and Virginia Class-A assets to recover utility costs.
Residential users generate the highest unit volumes. Builders are gaining share fastest as pre-installation becomes standard in new construction above median price points.
Application:
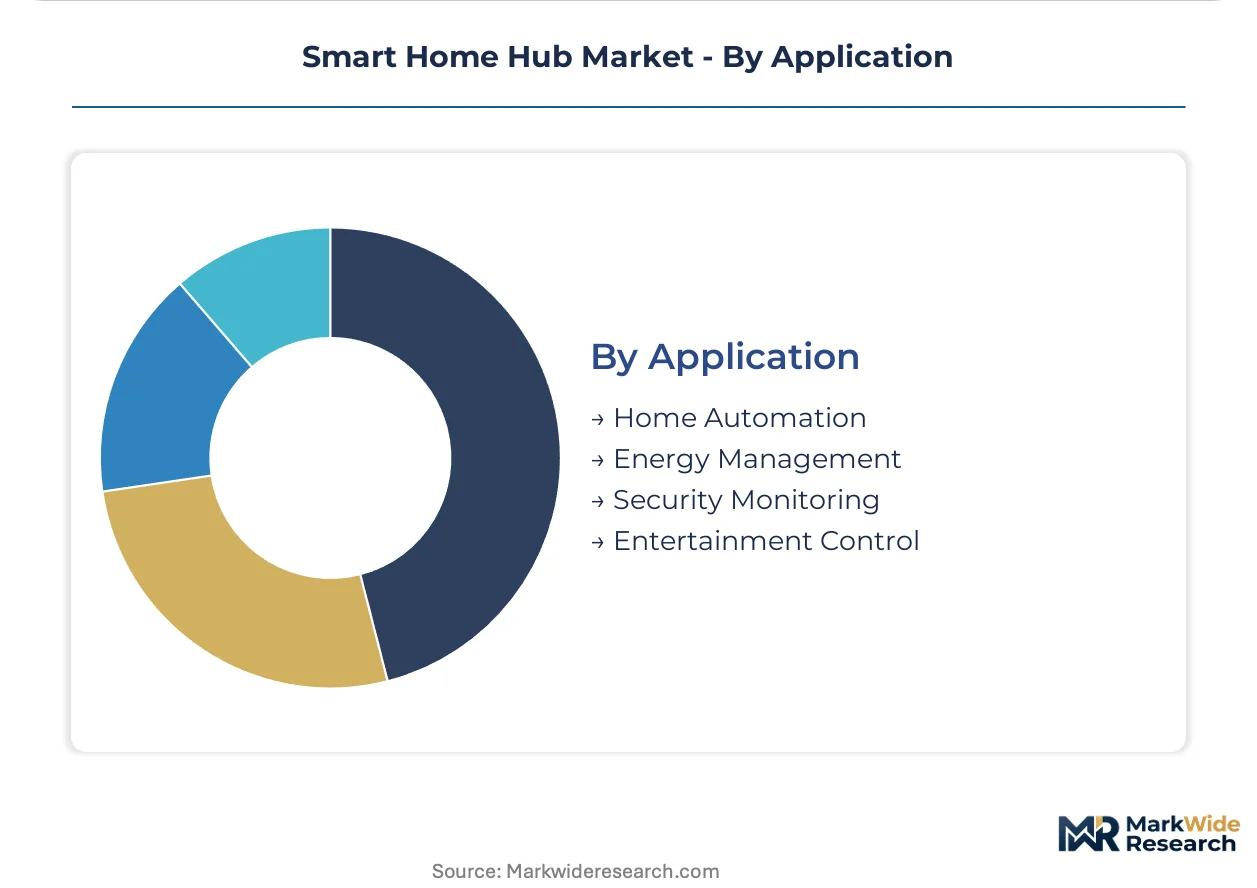
Customer type shapes application prioritization: security monitoring dominates professional installer specifications, while entertainment control drives retail impulse purchases.
- Home Automation:Coordinated control of lighting, climate, and motorized systems through scene-based programming. Whole-home automation demand clusters in affluent suburban markets where integration complexity justifies professional installation.
- Energy Management:Automated load shifting and consumption optimization responding to utility tariffs and grid signals. California PG&E and Texas ERCOT territory deployments accelerate as time-of-use rate structures penalize peak consumption.
- Security Monitoring:Hub-integrated intrusion detection, video verification, and environmental hazard alerting. ADT and Vivint specifications in Florida and Ohio prioritize local processing to reduce false alarm dispatch fees.
- Entertainment Control:Unified command of streaming devices, audio distribution, and gaming systems through single interfaces. Younger demographic demand in urban UK and Australian markets favors voice-first control over traditional remote proliferation.
Home automation leads by installed base. Energy management is climbing the fastest as electrification of heating and transport expands addressable load under utility control programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in smart home hub hardware tilt toward net-import positions in Europe and North America, while China and South Korea maintain component export surpluses. Foundry capacity allocation for Thread radio chipsets shapes regional production timelines.
United States
Utility time-of-use tariffs from PG&E and ERCOT drive hub adoption for automated load shifting in California and Texas. FCC Part 15 regulations govern unlicensed spectrum use for Zigbee and Thread deployments. Greater Boston hosts edge-AI startups developing local voice processing chips that bypass cloud transmission.
Germany
GDPR and the EU Cybersecurity Act mandate data-localization for cloud-dependent architectures, elevating demand for edge-computing hub designs. REACH substance restrictions and F-Gas Regulation reshape thermal design toward passive aluminum unibody construction. E.ON specifies Zigbee 3.0 stacks for demand response in smart meter rollouts across North Rhine-Westphalia.
China
MIIT-administered GB standards for data residency conflict with multinational cloud architectures, complicating product strategies for foreign vendors. Xiaomi and Huawei ecosystem bundling accelerates mass-market penetration through smartphone and appliance pre-integration. Shenzhen hardware clusters concentrate Thread radio module production for export markets.
Japan
METI promotes energy-management hub adoption through utility-led demand response programs targeting HVAC and EV charger coordination. JIS standards govern electromagnetic compatibility for residential IoT deployments. Tokyo apartment towers migrate to 5GHz and 6GHz Wi-Fi backhaul to relieve 2.4GHz congestion in dense urban clusters.
India
Smart city deployments in Bengaluru and Hyderabad seek centralized building automation platforms aggregating residential and commercial endpoints. BIS certification requirements delay product launches for imported hub hardware. Maharashtra and Telangana state programs subsidize edge-computing infrastructure for municipal energy management.
Smart Home Hub Market Competitive Environment
Concentration sits with consumer electronics conglomerates that leverage existing appliance ecosystems to anchor hub adoption. The vendor base spans three tiers: platform-integrated hardware giants, voice-first technology specialists, and professional installation channel suppliers. Strategic moves center on Matter certification acceleration and edge-AI silicon integration rather than proprietary protocol defense.
Within the platform-integrated tier, Samsung Electronics Co., Ltd. and Apple Inc. exemplify divergent positioning—Samsung through open-ecosystem SmartThings hardware-software integration, Apple via privacy-centric HomeKit protocols that control premium segment access. Amazon.com, Inc. occupies a distinct voice-first archetype that competes through Alexa's natural-language interface ubiquity. Xiaomi Corporation anchors mass-market penetration in Asia through ecosystem bundling strategies that pre-integrate hub functionality into smartphone and appliance purchases.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Amazon.com, Inc. |
| Vivint LLC |
| Logitech International S.A. |
| Google LLC |
| Xiaomi Corporation |
| Snap One LLC |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
Matter protocol migration from proprietary Z-Wave stacks to Thread and Wi-Fi implementations simultaneously relocates foundry demand toward sub-40nm capacity in Taiwan and compresses hardware premiums for interoperability-certified SKUs. This substitution dynamic concentrates bargaining power with semiconductor fabricators while eroding margins for hub vendors locked into legacy chipset inventories.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing for central controller installations, whereas retail channels favor per-unit transactional models for voice assistants and smart displays. Three-tier pricing structure across premium, standard, and economy levels separates NPU-equipped edge-AI devices from cloud-dependent mass-market SKUs and basic smart plugs. Pricing pressure stems from consumer rejection of mandatory subscription tiers for remote access, forcing vendors toward hardware-margin dependence. Property managers exhibit highest price sensitivity due to multi-unit procurement scale, while luxury home builders show lowest sensitivity when specifying pre-installed infrastructure.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for Thread radio chipsets and neural processing units, while Shenzhen hardware clusters concentrate final assembly and Matter certification testing. The supply chain draws from silicon wafers, RF front-end modules, and aluminum unibody enclosures as core inputs. Single-source vulnerability concentrates in sub-40nm foundry capacity allocation, where automotive and smartphone demand competes for smart home hub silicon. Distribution runs through professional integrator networks for central controllers and big-box retail for consumer-direct voice assistants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Matter certification dissolves ecosystem lock-in, creating niches for specialized edge-AI vendors and regional compliance-focused players alongside platform giants.
For Market Incumbents: Secure Matter certification acceleration through testing laboratory partnerships to compress four-to-eight month approval delays that threaten holiday selling seasons. Defend proprietary platform margins by investing in NPU-equipped premium tiers where residential developers specify hardware-software integration, while accelerating backward integration into Thread radio module sourcing to reduce foundry allocation dependency. For New Entrants and Emerging Players: Matter certification fast-track through CSA-authorized third-party labs enables rapid market entry before incumbent product refresh cycles. White-space targets concentrate in India smart city deployments and healthcare aging-in-place segments requiring HIPAA-compliant local processing. Penetrable geography sits with German and French markets where GDPR-compliant edge-computing variants command specification preference among cloud-averse premium consumers. For Investors and Strategic Acquirers: Capital is best deployed toward edge-AI silicon specialists with embedded systems security expertise, scarce outside Taiwan and Israel, over cloud-dependent platform aggregators facing data-localization compliance cost escalation. Long-term viability favors vendors with in-house NPU architecture and Matter-native protocol stacks rather than legacy Z-Wave retrofit plays. Signal to watch: Thread radio chipset lead times and foundry capacity allocation announcements indicating supply constraint intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Acceleration | CSA testing laboratory partnerships compress approval timelines for holiday-dependent consumer electronics launches. |
| Edge-AI Silicon Integration | NPU-equipped hub designs capture specification preference from Toll Brothers and Lennar in luxury residential deployments. |
| Backward Integration into Thread Modules | In-house radio chipset sourcing reduces dependency on Shenzhen hardware cluster foundry allocation cycles. |
| Healthcare Privacy Compliance Positioning | HIPAA-aligned local processing architectures address fall detection and medication adherence sensor integration requirements. |
| Professional Integrator Channel Control | CEDIA-certified firm partnerships lock in whole-home automation specifications exceeding 500 connected endpoints. |
Study Parameters
Operator-level perspectives from smart home platform engineers, professional integrators, residential property developers, and semiconductor procurement managers anchored the qualitative base. Primary interviews combined with secondary validation from Connectivity Standards Alliance certification databases, FCC Part 15 filings, E.ON and Enel utility demand response specifications, and customs trade data for Thread radio module flows. Bottom-up hub shipment modeling and top-down smart home infrastructure spending estimates provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against Thread chipset availability scenarios and Matter adoption pace variations. Segmentation dimensions modeled include product type, connectivity protocol, end-user category, and application use case across the projection horizon. CAGRs derived from logistic diffusion curves for protocol standardization and price elasticity functions for subscription rejection trends. Industry-specific inputs incorporated utility time-of-use tariff rollout schedules and REACH substance restriction compliance deadlines.
Decision-makers should treat outputs as directional under base assumptions of sustained Matter protocol adoption and stable foundry capacity allocation; material deviation would warrant model refresh. Specific risk factors include silicon supply concentration tightening, cross-border data friction escalation, and Matter certification backlog persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Home Use Anti-Aging Beauty Device Market
Consumer Goods
Refurbished Sneaker Market
Consumer Goods
Japan Heated Tobacco Products Market
Consumer Goods
West Africa Cigarettes Market
Consumer Goods
Deodorant Products Market
Consumer Goods
Household Cleaners Market
Consumer Goods
Dishwashing Detergent Market
Consumer Goods
Europe Cosmetics Market
Consumer Goods
Cat Massage Comb Market
Consumer Goods
Europe Heated Mattress Pads Market
Consumer Goods
North America Smoking Pipe Market
Consumer Goods
Sun Protection Spray Market
Consumer Goods
Hair Wig Market
Consumer Goods
Luxury Kitchen Appliances Market
Consumer Goods
Household Coffee Machine Market
Consumer Goods
Picnic Coolers Market