
 Dog Dental Chews Market | 2026-2036
Dog Dental Chews Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Dental Chews Market Insights
Pet specialty retail purchasing is pivoting toward fewer, larger distributors with direct manufacturer relationships. Mars, Incorporated leverages its vertical integration into rawhide sourcing to secure supply consistency for high-volume retail contracts. Nestlé Purina PetCare competes through R&D intensity in enzymatic coating technologies that extend chew efficacy claims. Virbac anchors the veterinary channel with prescription-positioned dental chews that require clinic endorsement.
Dog dental chews are extruded or molded edible products formulated with abrasive textures, enzymatic additives, or mechanical designs intended to reduce plaque and calculus accumulation during mastication. Manufacturing employs twin-screw extrusion at controlled moisture levels to achieve density gradients that balance chew duration against fracture risk for specific breed sizes. Rawhide and vegetable-based product types dominate volume, though vegetable-based formulations are capturing faster growth as grain-free positioning aligns with clean-label pet food migration. The plaque control application leads clinical positioning, while breath freshening occupies the highest margin pool through impulse and subscription channels.
The FDA Center for Veterinary Medicine regulates manufacturing claims and ingredient safety for edible pet products in the United States, while the Association of American Feed Control Officials establishes labeling standards that manufacturers must navigate for interstate commerce. The EU's Feed Hygiene Regulation imposes HACCP-based manufacturing requirements that constrain market access for non-compliant exporters. Stakeholders must monitor evolving veterinary dental health claim substantiation standards and decide whether to pursue prescription positioning or maintain over-the-counter accessibility as regulatory scrutiny intensifies.
Market Dynamics
Pet specialty retail consolidation across the United States concentrates purchasing power into fewer distributors, forcing manufacturers to secure direct supply agreements and backward-integrate into rawhide sourcing to maintain contract eligibility.
Growth Catalysts
- Veterinary Endorsement Programs:Clinic-based recommendation systems in the United States create pull-through demand that mass-market channels cannot replicate, locking in premium positioning for clinically validated formulations.
- REACH Compliance Arbitrage:European manufacturers meeting ECHA feed hygiene standards gain preferential access to cross-border distribution networks that exclude non-compliant exporters from shelf placement.
- Enzymatic Coating R&D:Patent-protected bioactive surface treatments extend efficacy claims from mechanical abrasion to biochemical plaque disruption, justifying subscription pricing models.
Market Restraints
- Rawhide Input Volatility:Cattle hide supply fluctuations in Brazil and Argentina transmit price shocks through the supply chain, compressing margins for non-integrated producers.
- FDA Claim Substantiation:The Center for Veterinary Medicine's evolving standards for dental health efficacy claims require costly clinical trials that freeze smaller competitors out of prescription positioning.
- Vegetable-Based Texture Limitations:Starch and cellulose formulations struggle to replicate the chew duration density of rawhide, limiting clinical efficacy perception among veterinary gatekeepers.
Strategic Opportunities
- Subscription Channel Penetration:Direct-to-consumer platforms in the United States bypass retail margin stacking while capturing recurring revenue through automated replenishment of breath-freshening SKUs.
- Grain-Free Certification Tailwinds:AAFCO-compliant limited-ingredient positioning aligns with clean-label migration in human food, opening shelf space in premium pet specialty doors.
- Telemedicine Integration:Virtual veterinary platforms create new prescription pathways for clinic-endorsed dental chews without physical clinic inventory requirements.
Industry Challenges
- Twin-Screw Extrusion Expertise Gap:Moisture-controlled density gradient manufacturing requires specialized process engineering talent that concentrates at legacy pet food equipment suppliers.
- EU Feed Hygiene Reconfiguration:HACCP-based manufacturing line upgrades for European market access demand capital deployment that conflicts with near-term margin targets for North American-focused producers.
- Patent Thicket Navigation:Enzymatic additive intellectual property portfolios held by human oral care companies create licensing friction for pet product adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Dental Chews Market |
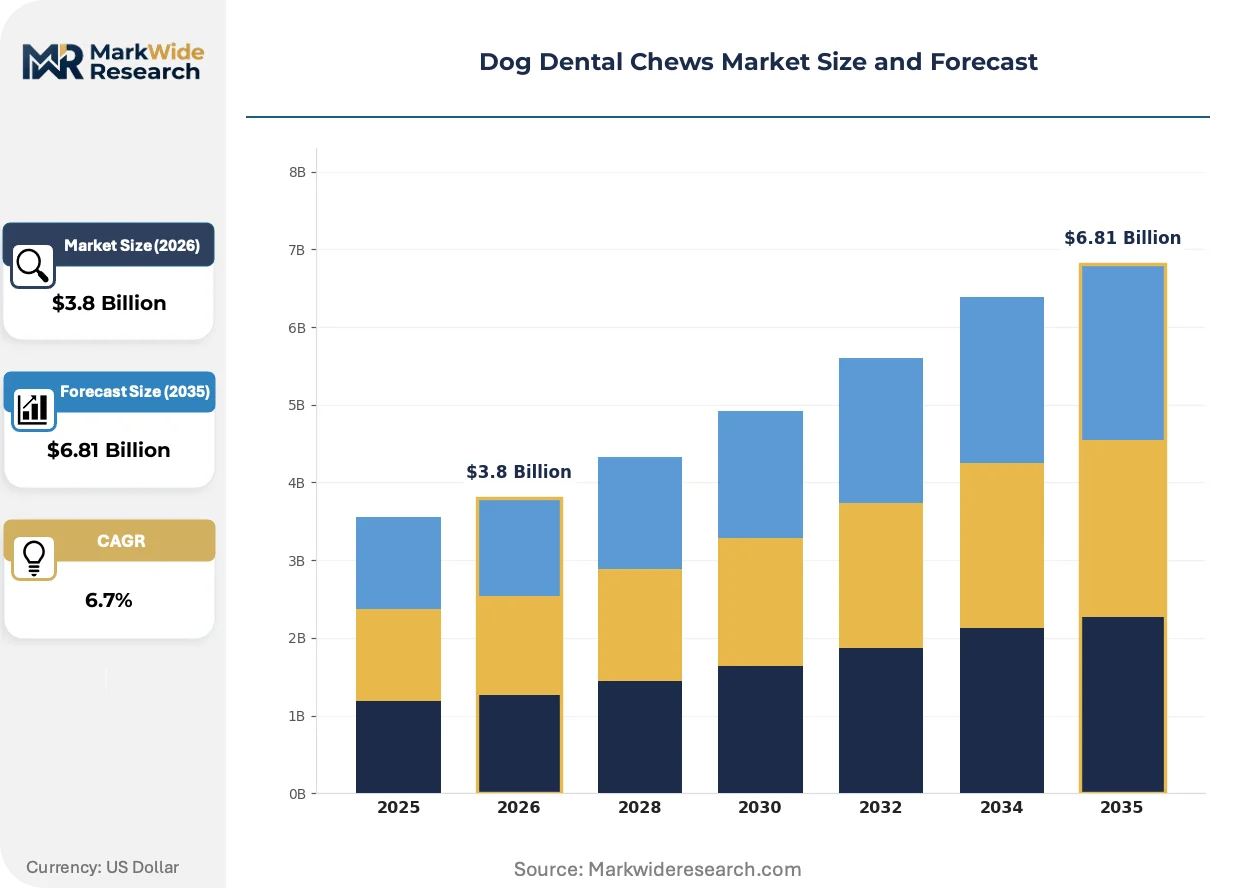
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rawhide, Vegetable-Based, Chew Sticks, Edible Bones, Dental Biscuits Application: Plaque Control, Breath Freshening, Tartar Removal, Gum Health, Teeth Whitening End User: Pet Owners, Veterinary Clinics, Animal Shelters, Grooming Centers, Pet Retailers Packaging Type: Resealable Pouches, Blister Packs, Bulk Bags, Boxes, Vacuum Sealed Packs |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, Colgate-Palmolive Company, Virbac, General Mills, The J.M. Smucker Company, Spectrum Brands Holdings, Central Garden & Pet, PetIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Dental Chews Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how dental efficacy is proven, priced, and purchased. Manufacturers now compete on biochemical validation rather than mechanical design alone.
Enzymatic coating technology is rewriting competitive positioning in the premium segment. Bioactive surface treatments that release glucose oxidase and lactoperoxidase during mastication now dominate R&D pipelines at major manufacturers. Pet specialty retailers in the United States are prioritizing SKUs with documented salivary antimicrobial activity, compressing shelf space for purely mechanical abrasion products.
The EU Feed Hygiene Regulation's HACCP mandates are forcing manufacturing line segregation that smaller exporters cannot afford. European distributors now require third-party certification of pathogen control protocols as a condition of contract negotiation. North American producers seeking European market access must either partner with EU-based toll manufacturers or absorb seven-figure facility upgrade costs.
Subscription-based replenishment models are displacing impulse purchasing in the breath-freshening category. Amazon's Subscribe and Save and Chewy's Autoship programs now capture the majority of volume in high-margin SKUs. This channel shift concentrates demand forecasting risk with manufacturers while reducing retail slotting fee exposure.
Dog Dental Chews Market Segmentation
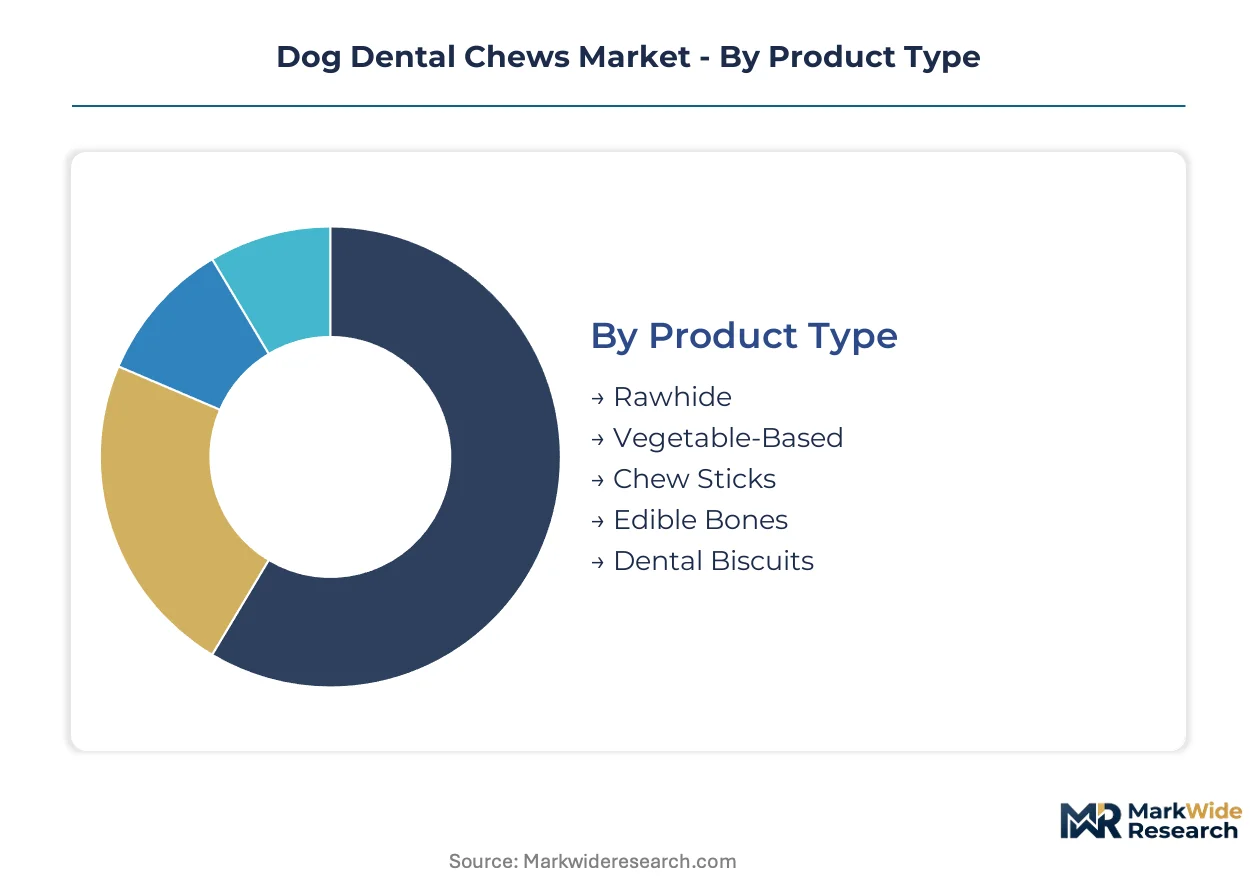
Segmentation in dog dental chews determines manufacturing investment profiles and channel access requirements. Each dimension—product chemistry, clinical positioning, buyer type, and packaging format—creates distinct margin structures and regulatory exposure.
Product Type:
Capital intensity varies sharply across product types, with rawhide requiring hide-processing infrastructure and vegetable-based formulations demanding precision extrusion systems.
- Rawhide:Cattle hide processing involves brining, liming, and controlled drying operations that tie up working capital in hide inventories and wastewater treatment. Brazilian and Argentinian hide supply fluctuations transmit directly through this segment, compressing margins for non-integrated producers.
- Vegetable-Based:Twin-screw extrusion at controlled moisture levels achieves density gradients that balance chew duration against fracture risk. Grain-free positioning aligns with clean-label migration, opening shelf space in premium pet specialty doors.
- Chew Sticks:Molded starch or cellulose formulations with abrasive surface textures target impulse purchase occasions.
- Edible Bones:Compressed vegetable protein or collagen matrices shaped to mimic natural bone structure.
- Dental Biscuits:Baked formulations with enzymatic additives, typically positioned as training rewards with secondary dental benefits.
Rawhide absorbs the bulk of installed capacity; vegetable-based is expanding most quickly.
Application:
Application segmentation maps directly to pricing power, with clinical claims commanding subscription premiums and cosmetic benefits driving impulse velocity.
- Plaque Control:Enzymatic coating technologies release glucose oxidase and lactoperoxidase during mastication to disrupt biofilm formation. Veterinary endorsement programs in the United States create pull-through demand that mass-market channels cannot replicate.
- Breath Freshening:High-margin positioning through mint, parsley, or chlorophyll additives targets owner-perceptible outcomes. Amazon's Subscribe and Save and Chewy's Autoship programs now capture the majority of volume in this category.
- Tartar Removal:Abrasive mechanical action claims require substantiation documentation for regulatory compliance.
- Gum Health:Anti-inflammatory additive positioning, often with omega fatty acid or antioxidant supplementation.
- Teeth Whitening:Peroxide-free optical brightening agents for cosmetic positioning in premium channels.
Plaque control commands the highest clinical pricing; breath freshening posts the steepest volume expansion trajectory.
End User:
Buyer type determines regulatory pathway and margin stacking, with veterinary channels requiring prescription infrastructure and direct-to-consumer bypassing retail fees.
- Pet Owners:Direct purchasing through e-commerce platforms and mass retail, with subscription models displacing impulse buying.
- Veterinary Clinics:Prescription-positioned dental chews requiring FDA Center for Veterinary Medicine claim substantiation and clinic inventory systems. Virbac anchors this channel with endorsement-dependent distribution.
- Animal Shelters:Bulk procurement with cost-minimization priorities and simplified formulation requirements.
- Grooming Centers:Point-of-sale placement targeting service-occasion add-on purchases.
- Pet Retailers:Consolidating pet specialty doors with direct manufacturer relationship requirements and slotting fee negotiations.
Pet retailers absorb the bulk of volume throughput; veterinary clinics are climbing the fastest on a value basis.
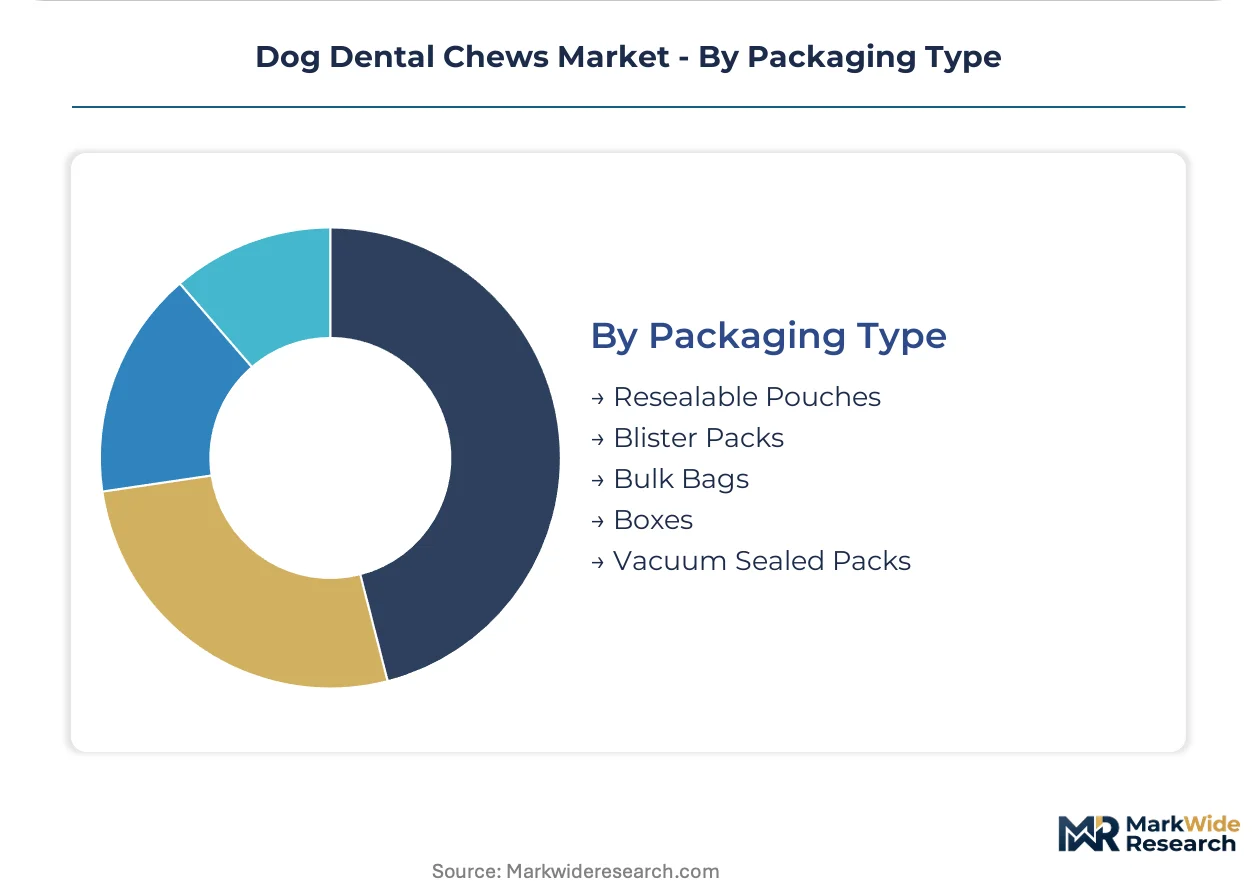
Packaging Type:
Packaging format selection reflects channel economics and shelf-life engineering, with convenience features justifying premium price tiers.
- Resealable Pouches:Flexible film structures with zipper closures for moisture retention and portion control in repeat-purchase households.
- Blister Packs:Individual unit visibility for veterinary sample distribution and premium positioning.
- Bulk Bags:Multi-kilogram formats for shelter, breeder, and multi-dog household economies.
- Boxes:Rigid secondary packaging for gift occasions and retail shelf presence.
- Vacuum Sealed Packs:Extended shelf-life preservation for export logistics and preservative-free formulation claims.
Resealable pouches dominate unit volume; vacuum sealed packs are gaining share fastest in export-oriented production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian and Argentinian cattle hide supply chains anchor raw material sourcing for rawhide-based dental chew production, with manufacturing capacity clustering near North American pet specialty retail distribution hubs.
United States
Veterinary endorsement programs and premium pet humanization trends concentrate demand in coastal metropolitan markets. The FDA Center for Veterinary Medicine regulates manufacturing claims and ingredient safety for edible pet products. Kansas and Nebraska host extrusion manufacturing clusters serving direct-to-consumer subscription channels.
Germany
REACH compliance arbitrage creates preferential access for manufacturers meeting ECHA feed hygiene standards. The EU Feed Hygiene Regulation imposes HACCP-based manufacturing requirements that constrain market access. Bavaria-based toll manufacturers process contract production for North American brands seeking European shelf placement.
United Kingdom
Pet specialty retail consolidation drives demand for AAFCO-compliant limited-ingredient positioning aligned with clean-label migration. The Veterinary Medicines Directorate oversees efficacy claim substantiation for prescription-positioned products. Greater London distribution hubs coordinate cross-border fulfillment to EU markets post-Brexit.
China
Domestic pet humanization trends accelerate vegetable-based formulation adoption among urban middle-class households. The Ministry of Agriculture and Rural Affairs regulates feed safety standards for imported and domestically produced pet edibles. Yangtze River Delta manufacturing zones supply private-label production for North American mass-market retailers.
Brazil
Cattle hide supply fluctuations transmit price volatility through rawhide-dependent supply chains. The Ministry of Agriculture, Livestock and Food Supply oversees export certification for hide-derived pet products. São Paulo state tanning clusters feed integrated processors with captive hide sourcing arrangements.
Dog Dental Chews Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic coating specialization and veterinary channel positioning. The market structures around three tiers: integrated multinationals with captive rawhide supply, R&D-intensive specialists with patent-protected bioactive technologies, and regional private-label manufacturers serving consolidated pet specialty retailers. Strategic archetypes include backward-integrated commodity suppliers, enzymatic coating technology licensors, and prescription-positioned veterinary channel anchors. Competitive moves concentrate on manufacturing line HACCP upgrades for EU market access and direct-to-consumer subscription platform development.
Within the integrated multinational tier, Mars, Incorporated and Nestlé Purina PetCare exemplify scale-driven archetypes with diversified pet nutrition portfolios. Virbac occupies a distinct position as a veterinary channel specialist requiring clinic endorsement infrastructure. These three anchors represent contrasting strategic postures: commodity supply security, consumer packaged goods R&D intensity, and prescription regulatory pathway navigation.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| Colgate-Palmolive Company |
| Virbac |
| General Mills |
| The J.M. Smucker Company |
| Spectrum Brands Holdings |
| Central Garden & Pet |
| PetIQ |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up pet specialty retailers concentrate purchasing power across North America, forcing manufacturers into direct supply agreements that compress margin stacking while rewarding backward-integrated producers with contract eligibility and pricing discipline.
Pricing Analysis
High-volume rawhide SKUs trade on thin margins through mass-market channels, while enzymatic-coated premium lines capture subscription premiums via Chewy Autoship and Amazon Subscribe and Save. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed prescription products from grain-free specialty positioning and commodity rawhide alternatives. Cost compression in the rawhide tier is intensifying because Brazilian cattle hide supply volatility transmits directly through non-integrated producers. Animal shelters and bulk procurement buyers exhibit the highest price sensitivity; veterinary clinics and direct-to-consumer subscribers show the least.
Supply Chain Analysis
Reverse-logistics flows are minimal in edible pet products due to food safety regulations, though expired inventory returns from retail consolidation create disposal cost burdens for manufacturers without reprocessing agreements. Rawhide supply concentrates in Brazil and Argentina for cattle hide sourcing, with twin-screw extrusion equipment anchored in the United States and Germany for vegetable-based production. Manufacturing draws from cattle hides, enzymatic additives, and starch-cellulose matrices as primary inputs. Single-source vulnerability in Brazilian hide supply chains threatens margin stability for non-integrated processors. Distribution runs through consolidating pet specialty retailers with direct manufacturer relationship requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog dental chews sector is transitioning from mechanical abrasion claims to biochemical efficacy validation, with enzymatic coating technologies displacing legacy rawhide formulations in premium positioning.
For Market Incumbents: Lock in captive rawhide supply through Brazilian tanning cluster partnerships or vertical integration to defend against price volatility from Argentinian supply disruptions. Prioritize HACCP manufacturing line upgrades to maintain EU Feed Hygiene Regulation compliance and cross-border distribution access. For New Entrants and Emerging Players: The price-point gap between prescription-positioned veterinary products and mass-market rawhide alternatives offers white-space opportunity for mid-tier grain-free formulations with AAFCO-compliant limited-ingredient positioning. Target telemedicine-integrated veterinary platforms for prescription pathway access without physical clinic infrastructure investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor enzymatic coating technology specialists with patent-protected bioactive surface treatments in the United States and Germany. Long-term viability hinges on subscription channel capture and regulatory pathway navigation. Watch FDA Center for Veterinary Medicine claim substantiation standards as the inflection indicator for prescription positioning economics.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Coating R&D Investment | Patent-protected bioactive surface treatments extend efficacy claims from mechanical abrasion to biochemical plaque disruption. |
| EU Feed Hygiene HACCP Compliance | Manufacturing line segregation upgrades unlock cross-border distribution networks that exclude non-compliant exporters. |
| Direct-to-Consumer Subscription Launch | Chewy Autoship and Amazon Subscribe and Save bypass retail margin stacking while capturing recurring revenue pools. |
| Brazilian Hide Supply Integration | Captive sourcing from São Paulo tanning clusters insulates margins from cattle hide price volatility. |
| Telemedicine Platform Partnership | Virtual veterinary channels create prescription pathways without physical clinic inventory requirements. |
Research Methodology
Trade publications, veterinary clinical journals, and AAFCO regulatory filings formed the secondary backbone, supplemented by customs records and pet specialty retail audit data. Primary interviews with veterinary clinic procurement managers, pet food R&D directors, and distribution channel partners validated demand patterns and pricing dynamics. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down market sizing from manufacturer capacity assessments.
Historical trendline analysis of rawhide input costs and enzymatic additive pricing informed projection assumptions across the analysis window. The forecast framework modeled segmentation dimensions including product chemistry, clinical positioning, buyer type, and packaging format. CAGRs were derived from regression analysis of volume trajectories and value expansion patterns. Twin-screw extrusion capacity utilization and veterinary endorsement program penetration served as industry-specific forecast inputs.
Inputs from veterinary procurement databases and pet specialty retail point-of-sale systems were available through the study window; gaps in real-time subscription channel transaction data introduce uncertainty bands around direct-to-consumer growth assumptions. Forecasts reflect documented assumptions regarding regulatory claim substantiation timelines and rawhide supply stability. Material deviation in FDA Center for Veterinary Medicine enforcement posture or Brazilian cattle hide export certification warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Pet Toys Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Cat Collar Market
Pet Care Products
Dry Pet Food Market
Pet Care Products
PET Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Dog Vest Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Pet Supplement Market
Pet Care Products
UK Pet Diet Market