
 Asia-Pacific Athletic Footwear Market | 2026-2036
Asia-Pacific Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Athletic Footwear Market Outlook
Premium cushioning specifications and carbon-plate performance tiers is collapsing the gap between elite marathon products and mass-market running lines. Nike Inc leverages its proprietary foam formulations and athlete endorsement networks to sustain pricing power across Greater China. ASICS Corporation anchors its regional position through Japan-centric technical running heritage and specialized distribution in Tokyo and Osaka. Li-Ning Company Ltd competes on domestic manufacturing scale and patriotic brand positioning within mainland China's sportswear sector.
Asia-Pacific athletic footwear encompasses engineered shoes designed for sport-specific biomechanical performance, typically incorporating ethylene-vinyl acetate midsoles, thermoplastic polyurethane stability plates, and knitted polyester uppers manufactured through automated lasting and direct-injection molding processes. These products serve competitive athletes, fitness enthusiasts, and casual consumers requiring impact absorption, motion control, and durability across varied training surfaces. Running shoes dominate volume flows across the region's e-commerce channels, while the athletes end-user segment commands the highest per-unit margins through technical customization and professional-grade specifications. Specialty stores retain outsized influence in Japan and South Korea, where in-store gait analysis and fitting services differentiate the offline retail channel from discount-driven online alternatives.
China's SAMR enforces GB standards for footwear physical safety and chemical content, while India's BIS mandates product certification for imported athletic shoes entering domestic distribution. Japan's METI promotes technical textile innovation through JIS standards that influence regional supplier qualification requirements. Stakeholders must monitor evolving recycled-content mandates and cross-border e-commerce duty structures as these regulatory instruments reshape both cost structures and market access pathways across the region.
Market Dynamics
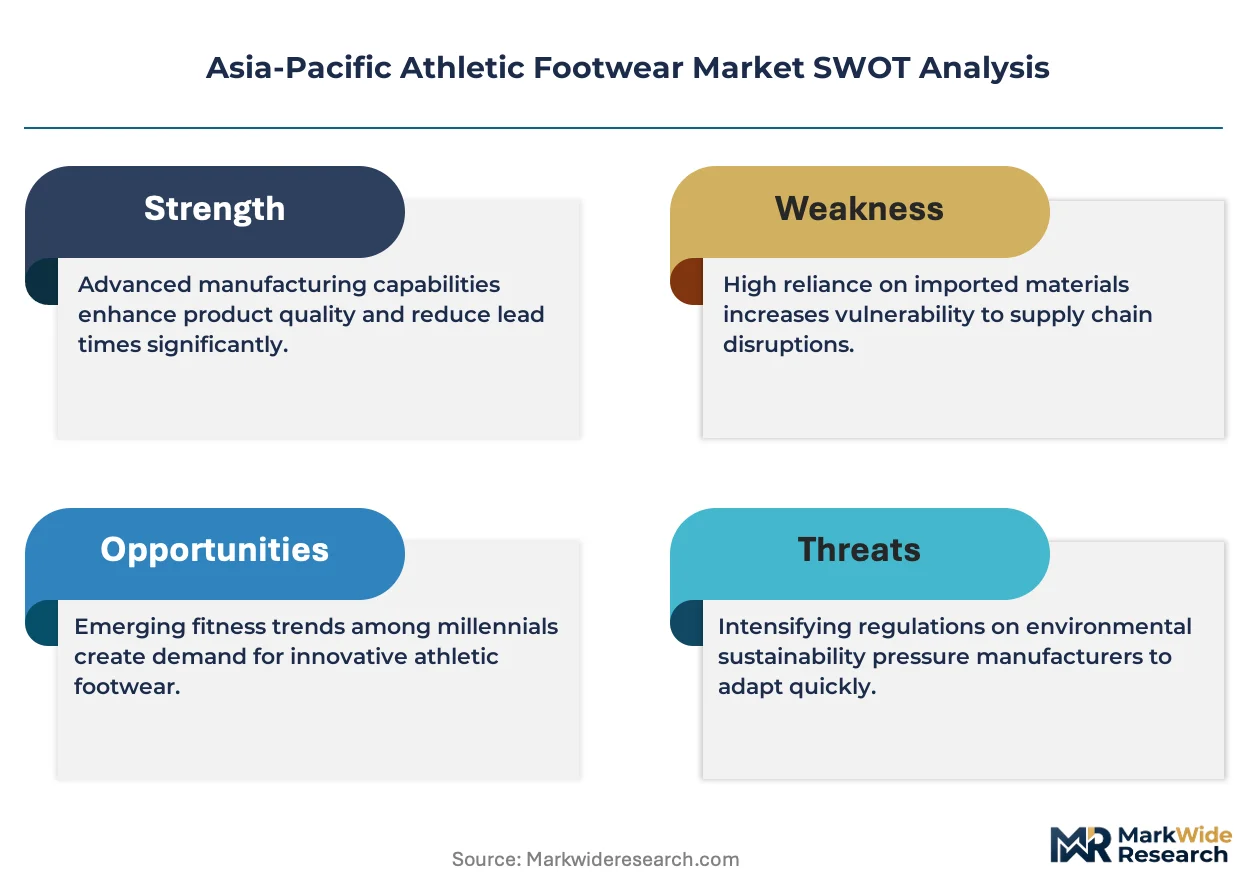
China's GB standards for footwear safety and recycled content mandates are forcing manufacturers to reconfigure material sourcing and production workflows across the Asia-Pacific supply base.
Growth Catalysts
- Marathon participation surge:Amateur running clubs in China and India are expanding the consumer base for performance running shoes with carbon-plate specifications.
- GB standards compliance:China's SAMR enforcement of physical safety and chemical content rules is accelerating investment in certified manufacturing infrastructure.
- Fitness culture maturation:Tier-one Chinese cities and Indian metropolitan corridors such as Mumbai and Delhi are exhibiting rising disposable incomes directed toward technical athletic footwear.
Market Restraints
- Ethylene-vinyl acetate price volatility:Midsole foam input costs fluctuate with petrochemical feedstock markets, compressing margin stability for mass-market producers.
- Specialty store concentration:Japan and South Korea retain outsized offline retail influence through gait analysis services, limiting pure e-commerce penetration.
- Thermoplastic polyurethane supply bottlenecks:Stability plate manufacturing depends on specialized polymer suppliers concentrated in East Asian industrial clusters.
Strategic Opportunities
- India's BIS certification pathway:Product certification mandates for imported athletic shoes create first-mover advantage for compliant regional manufacturers.
- Direct-injection molding automation:Automated lasting processes enable mass customization at scale for performance-tier specifications.
- Recycled polyester uppers:Knitted upper production using post-consumer waste streams aligns with emerging circular economy incentives across the region.
Industry Challenges
- Biomechanical engineering talent scarcity:Sport-specific design expertise for motion control systems remains concentrated in Japanese and South Korean technical institutes.
- Cross-border e-commerce duty complexity:Evolving tariff structures for direct-to-consumer shipments create compliance overhead for multi-market distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Athletic Footwear Market |
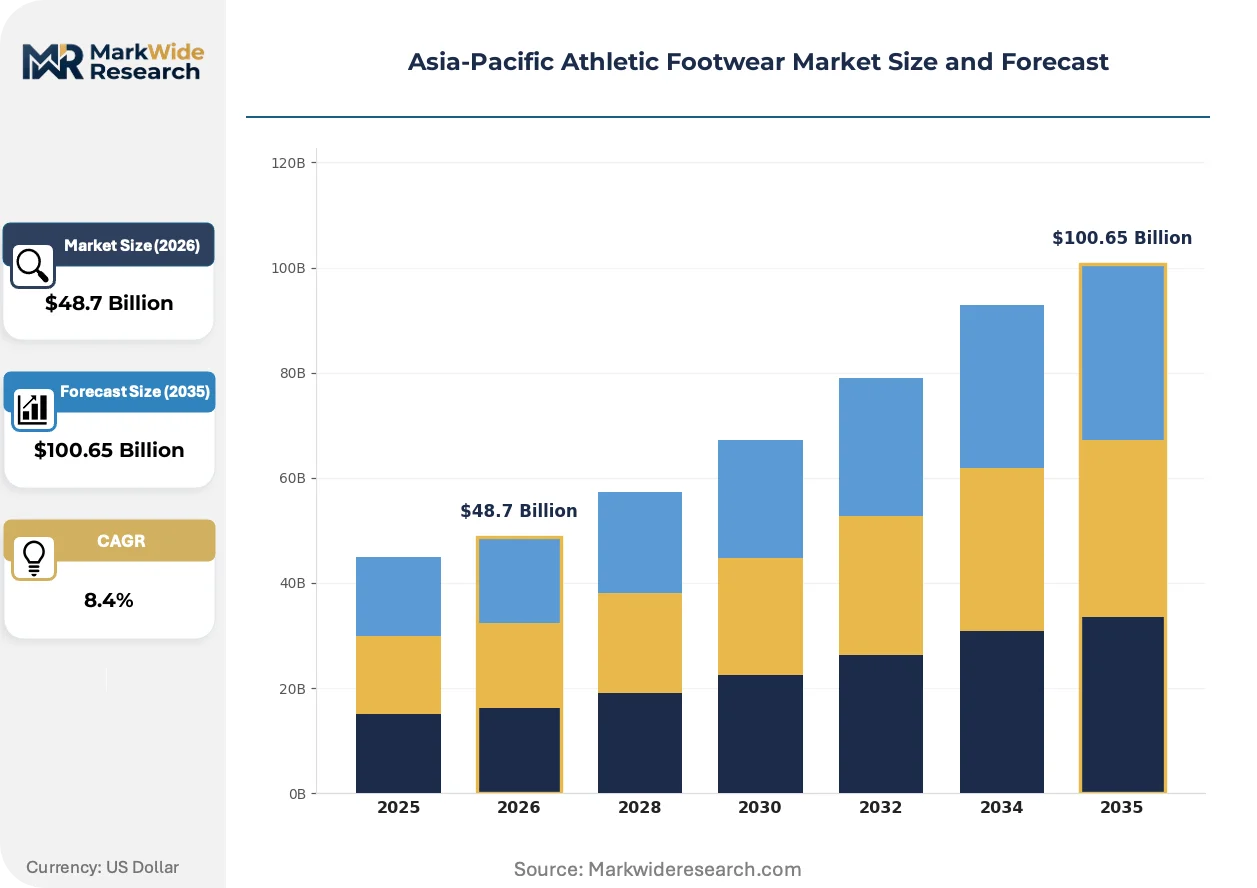
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Training Shoes, Walking Shoes, Cross-Training Shoes End User: Men, Women, Children, Athletes Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Discount Stores Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Nike Inc, Adidas AG, Puma SE, ASICS Corporation, Under Armour Inc, Li-Ning Company Ltd, ANTA Sports Products Ltd, Skechers USA Inc, New Balance Athletics Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Athletic Footwear Market Strategic Shifts
Material science breakthroughs and regulatory pressure on chemical content are compressing development cycles and reshaping competitive differentiation across the Asia-Pacific athletic footwear sector.
Carbon-fiber plate integration is decomposing the traditional boundary between elite marathon products and accessible performance tiers. Recreational runners in China's tier-one cities are adopting carbon-plate specifications previously reserved for professional athletes. This diffusion is compressing average selling price premiums and forcing brands to differentiate through proprietary foam formulations rather than plate presence alone.
China's SAMR recycled-content mandates are requiring manufacturers to document post-consumer material percentages in knitted polyester uppers and ethylene-vinyl acetate midsoles. Suppliers must requalify under revised GB standards verification protocols. Japanese manufacturers leveraging METI technical textile programs are accelerating JIS-compliant recycled fiber development to maintain regional supplier status.
Specialty retail channels in Tokyo and Osaka are unbundling gait analysis from product purchase, selling biomechanical assessment as a standalone service. This model is displacing pure transaction-based retail in South Korea's premium segments. Digital fitting tools are capturing share in India's metropolitan corridors where offline technical service infrastructure remains underdeveloped.
Asia-Pacific Athletic Footwear Market Segmentation
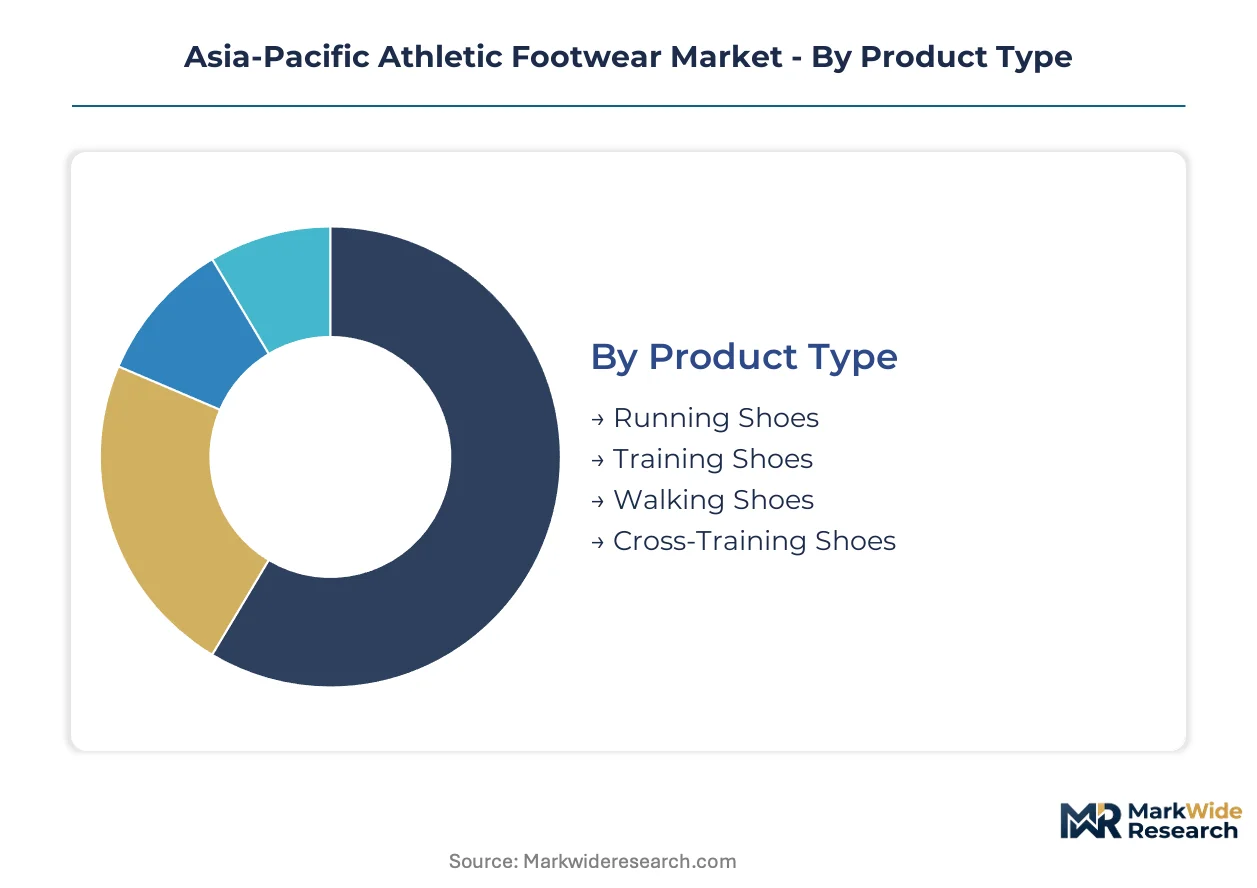
Segmentation in Asia-Pacific athletic footwear reveals how carbon-plate technology, recycled-content mandates, and channel-specific service models are fragmenting demand across performance tiers. Manufacturers must align product architecture with distinct biomechanical requirements and regulatory compliance pathways in each slice.
Product Type:
Channel mix varies sharply by sport-specific engineering intensity, with carbon-plate running shoes concentrating in specialty retail while cross-training volumes flow through discount channels.
- Running Shoes:Engineered with ethylene-vinyl acetate midsoles and thermoplastic polyurethane stability plates for impact absorption across marathon distances. Demand concentrates in China's tier-one cities and Mumbai, where amateur running clubs are adopting carbon-plate specifications previously limited to elite athletes. This segment dominates installed base.
- Training Shoes:Multi-directional support structures accommodate gym-based resistance and agility protocols. India's metropolitan corridors exhibit steepest expansion trajectory as fitness culture maturation drives technical footwear adoption beyond pure running use cases.
- Walking Shoes:Moderate cushioning densities target daily step-count consumers with durability-focused outsole compounds.
- Cross-Training Shoes:Lateral stability features serve hybrid workout formats; volumes concentrate in mass-market e-commerce channels.
Running shoes dominate installed base. Training shoes are where expansion concentrates.
End User:
Cost tier stratification separates professional-grade customization from mass-market specifications, with athletes commanding per-unit premiums that subsidize development amortization across consumer segments.
- Men:Largest volume segment with established size-run distribution across all channels.
- Women:Narrower heel-last engineering and colorway differentiation drive specialty store attachment rates in Tokyo and Osaka.
- Children:Growth-containment features and rapid replacement cycles concentrate in budget-tier offline retail.
- Athletes:Biomechanical customization and professional-grade specifications generate highest margins; demand clusters around China's GB-certified manufacturing infrastructure and Japan's technical textile institutes. Athletes dominate margin contribution. Children represent volume expansion opportunity.
Distribution Channel:
Geographic maturity determines channel viability, with gait-analysis service infrastructure limiting pure e-commerce penetration in Japan and South Korea while India's underdeveloped offline technical services accelerate digital adoption.
- Online Retail:Direct-to-consumer platforms capture share in India's metropolitan corridors where offline technical infrastructure remains underdeveloped. Cross-border e-commerce duty complexity creates compliance overhead for multi-market distribution.
- Offline Retail:Mass-market department stores and sporting goods chains serve price-sensitive consumers with limited fitting service expectations.
- Specialty Stores:In-store gait analysis and biomechanical assessment differentiate premium positioning in Tokyo, Osaka, and Seoul; unbundled service models are displacing pure transaction-based retail. Specialty stores dominate margin capture. Online retail is where volume expansion concentrates.
- Discount Stores:Volume-driven clearance channels for prior-season inventory and private-label alternatives.
Price Tier:
Supply concentration in certified manufacturing clusters creates cost-structure differentiation between compliance-heavy premium tiers and price-elastic budget positioning.
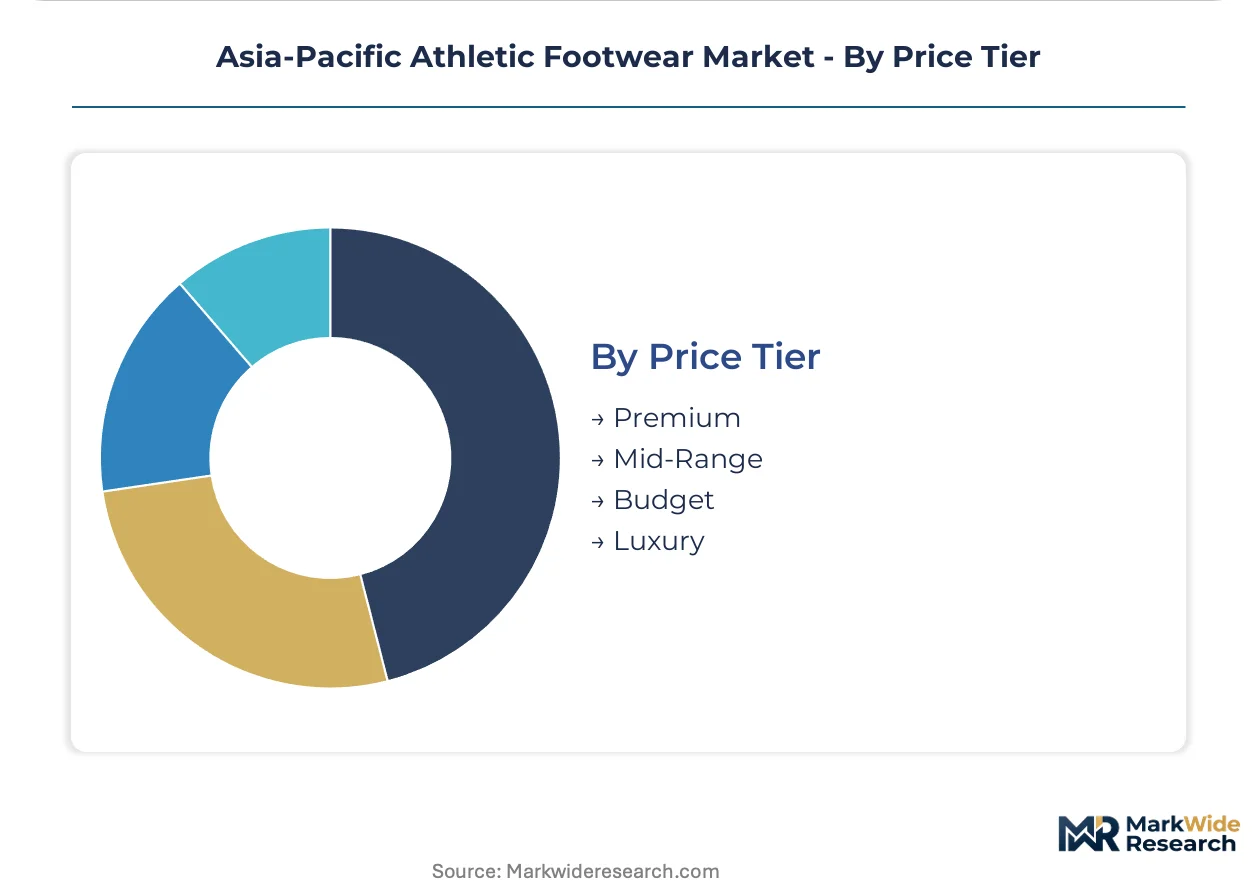
- Premium:Proprietary foam formulations and carbon-plate integration target China's tier-one cities with GB standards-compliant construction; recycled-content mandates add documentation overhead.
- Mid-Range:Standardized ethylene-vinyl acetate midsoles serve India's rising disposable income segments with performance-adjacent specifications at accessible price points. Premium dominates technology investment recovery. Mid-range is where volume expansion concentrates.
- Budget:Simplified construction and domestic manufacturing scale serve mass-market replacement demand.
- Luxury:Limited-edition collaborations and material exclusivity target collector segments with negligible volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific athletic footwear trade flows reflect a pronounced import dependency in India and Australia against China's export-manufacturing dominance. Regional supply chains route ethylene-vinyl acetate compounds and thermoplastic polyurethane stability plates through specialized East Asian industrial clusters before final assembly.
China
Marathon participation in Beijing and Shanghai drives carbon-plate specification adoption among amateur runners. SAMR enforces GB standards for footwear physical safety and recycled content documentation across manufacturing facilities. Dongguan and Wenzhou industrial corridors concentrate automated lasting and direct-injection molding capacity for regional export supply.
India
Mumbai and Delhi metropolitan corridors exhibit rising disposable incomes directed toward technical running shoes with performance-adjacent specifications. BIS mandates product certification for imported athletic shoes entering domestic distribution channels. Tamil Nadu and Gujarat manufacturing zones are expanding certified production infrastructure to capture import substitution opportunities.
Japan
Specialty retail channels in Tokyo and Osaka sustain premium positioning through unbundled gait analysis services sold separately from product purchase. METI promotes technical textile innovation through JIS standards influencing regional supplier qualification requirements. Kansai industrial clusters anchor thermoplastic polyurethane stability plate fabrication for domestic and export markets.
South Korea
Seoul Capital Area consumers demand biomechanical assessment integration in offline retail experiences, limiting pure e-commerce penetration. MFDS-equivalent consumer product safety frameworks align with regional chemical content restrictions. Busan-Ulsan manufacturing zones supply knitted polyester upper components to regional footwear assemblers.
Australia
Sydney and Melbourne fitness culture maturation drives demand for marathon-distance running specifications with proprietary foam formulations. TGA-aligned product safety standards govern imported athletic footwear chemical content thresholds. Limited domestic manufacturing capacity creates import dependency on Chinese and Vietnamese production sources.
Asia-Pacific Athletic Footwear Market Competitive Environment
Concentration sits with diversified sportswear conglomerates controlling proprietary foam formulations and athlete endorsement networks. Mid-tier domestic manufacturers compete on patriotic brand positioning and certified compliance with recycled-content mandates. Strategic archetypes separate technology licensors, scale-driven assemblers, and heritage-anchored technical specialists. Competitive moves center on backward integration into ethylene-vinyl acetate compound production and geographic expansion through cross-border e-commerce duty optimization.
Among diversified sportswear conglomerates, Nike Inc and Adidas AG exemplify technology-licensing archetypes with proprietary material science investments, while ASICS Corporation occupies a position within heritage-anchored technical specialists emphasizing biomechanical engineering depth. Li-Ning Company Ltd represents domestic scale-driven assemblers leveraging patriotic positioning within mainland China's sportswear sector. These three anchors illustrate how competitive positioning fragments across technology ownership, manufacturing scale, and cultural brand equity rather than converging on uniform strategies.
| Leading Market Players |
|---|
| Nike Inc |
| Adidas AG |
| Puma SE |
| ASICS Corporation |
| Under Armour Inc |
| Li-Ning Company Ltd |
| ANTA Sports Products Ltd |
| Skechers USA Inc |
| New Balance Athletics Inc |
| Others |
Value Chain & Pricing Dynamics
China's SAMR enforcement of GB standards for footwear physical safety and recycled content documentation simultaneously gates supplier qualification and stratifies price tiers across the Asia-Pacific athletic footwear market. Manufacturers must absorb certification overhead to access premium positioning while budget-tier assemblers face exclusion from performance-tier supply chains.
Pricing Analysis
Recreational runners in China's tier-one cities anchor the three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from carbon-plate integration density and proprietary foam formulation exclusivity. Cost compression in the mid-range tier is intensifying because ethylene-vinyl acetate feedstock volatility transfers directly to contract negotiations. Mass-market e-commerce buyers exhibit highest price sensitivity; professional athletes and specialty store patrons demonstrate lowest elasticity due to biomechanical customization requirements.
Supply Chain Analysis
China and Vietnam anchor ethylene-vinyl acetate midsole production and automated lasting capacity for regional export supply. Thermoplastic polyurethane stability plates draw from specialized polymer suppliers concentrated in Japan's Kansai industrial clusters and South Korea's Busan-Ulsan zones. Single-source vulnerability sits with carbon-fiber plate fabricators limited to qualified East Asian facilities. Distribution runs through specialty retail channels in Tokyo and Osaka, direct-to-consumer platforms in India's metropolitan corridors, and mass-market e-commerce across Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. GB standards compliance and JIS certification pathways create switching costs that lock qualified suppliers into long-term OEM relationships.
For Market Incumbents: Compound proprietary foam formulation advantages through backward integration into ethylene-vinyl acetate compound production. Expand certified manufacturing infrastructure in Tamil Nadu and Gujarat to capture India's BIS-mandated import substitution opportunity. Defend against emerging domestic Chinese assemblers by deepening athlete endorsement network exclusivity in marathon-tier events. For New Entrants and Emerging Players: Anchor in India's underdeveloped offline technical service infrastructure by deploying digital fitting tools targeting Mumbai and Delhi fitness enthusiasts. Target the mid-range training shoe segment where performance-adjacent specifications meet accessible price points. Pursue white-label manufacturing partnerships with established recycled-content certified facilities to bypass GB standards documentation barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across direct-injection molding automation and carbon-plate fabrication capacity. Long-term viability favors acquisition targets with captive supply of thermoplastic polyurethane stability plates and proven SAMR audit histories. Monitor India's BIS certification backlog as an inflection signal for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVA Compound Production | Captive supply of midsole foam buffers petrochemical feedstock volatility for premium-tier manufacturers. |
| GB Standards Certification Investment | SAMR-compliant documentation unlocks China's tier-one city distribution and carbon-plate specification access. |
| Specialty Store Service Unbundling | Standalone gait analysis revenue in Tokyo and Osaka displaces pure transaction-based retail economics. |
| Recycled Polyester Upper Transition | Post-consumer waste stream integration aligns with emerging circular economy mandates across the region. |
| Digital Fitting Platform Deployment | Biomechanical assessment tools capture share in India's metropolitan corridors lacking offline technical infrastructure. |
Study Parameters
A spread of perspectives from brand product managers, specialty retail buyers, manufacturing facility directors, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, industrial cluster production databases, and SAMR certification registries. Bottom-up volume triangulation across ethylene-vinyl acetate midsole output and top-down value estimation from tiered price positioning were cross-referenced for convergence.
Segmentation dimensions modeled include product type, end user archetype, distribution channel, and price tier across the projection horizon. CAGRs were derived from fitted growth curves anchored to marathon participation trajectories and fitness culture maturation indicators. Industry-specific forecast inputs encompass carbon-plate specification diffusion rates and recycled-content mandate compliance timelines.
Underlying assumptions cover sustained petrochemical feedstock availability and stable enforcement of BIS import certification pathways, with deviation risk concentrated in cross-border e-commerce duty restructuring and thermoplastic polyurethane supply disruptions. Recalibration cycles align with material shifts in China's GB standards verification protocols and India's manufacturing infrastructure buildout momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Equestrian Footwear Market
Footwear
Europe Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Womens Footwear Market
Footwear
E-Commerce Footwear Market
Footwear
Global Recovery Footwear Market
Footwear
Dance Shoes Market
Footwear
Protective Footwear Market
Footwear
Sustainable Footwear Market
Footwear
Casual Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Hiking Footwear Market
Footwear
Global Men Leather Shoes Market
Footwear
Football Shoes Market
Footwear
Platform Boots Market
Footwear
Shoe Insoles Market