
 Drone for Kids Market | 2026-2036
Drone for Kids Market Size, Share, and Industry Trends Forecast 2026-2036
Drone for Kids Market Insights
Polycarbonate is restructuring product economics in the Drone for Kids Market as it displaces ABS in rotor housings and impact frames, cutting unit weight while improving crash resilience. DJI leverages its Shenzhen manufacturing base to control component costs across the mini drone tier. Holy Stone differentiates through gesture-control firmware optimized for the 6-8 Years age bracket. Spin Master anchors North American shelf presence through exclusive retail partnerships with big-box toy chains.
A drone for kids constitutes a lightweight unmanned aerial vehicle with enclosed rotors, altitude hold sensors, and maximum flight speeds capped below regulatory thresholds, designed primarily for recreational flight and introductory STEM learning. Camera Drones occupy the highest margin pool as parents prioritize photo-capture features for the Teens segment, while Educational Drones represent the fastest-growing product type as schools integrate UAV modules into science curricula. The 9-12 Years age bracket dominates unit volume, though the 3-5 Years category is expanding through simplified one-button controls and foam-encased designs that reduce parental safety concerns.
The FAA's Remote ID mandate and the EU's CE marking under the Toy Safety Directive constrain firmware architecture and transmitter power for devices sold in the United States and European member states. China's GB standards for electronic toys, administered by SAMR, set baseline electrical safety and battery enclosure requirements that most Shenzhen-based manufacturers treat as the default design floor. Stakeholders must monitor how evolving aviation authority classifications for sub-250-gram devices reshape the addressable market for entry-level models.
Market Dynamics
STEM curriculum mandates in primary education systems are pulling educational drone kits into institutional procurement channels, rewiring how manufacturers allocate R&D between consumer toy features and classroom durability specifications.
Growth Catalysts
- GB Standards Compliance:China's SAMR-administered electronic toy safety baselines have streamlined export certification for Shenzhen manufacturers, reducing time-to-market for child-safe battery enclosures and altitude-hold sensors.
- Polycarbonate Material Shift:Rotor housing fabrication is migrating from ABS to polycarbonate resins, cutting unit weight while improving crash resilience for repeated indoor use by younger operators.
- FAA Remote ID Rule:The United States aviation authority's unmanned aircraft identification mandate is forcing firmware architecture upgrades that incidentally improve parental oversight features through integrated geofencing.
Market Restraints
- Lithium Polymer Cost Volatility:Battery cell price swings constrain margin stability for entry-level models where power-to-weight ratios determine flight time competitiveness.
- Shenzhen Supply Concentration:Component sourcing clusters within a single Chinese manufacturing hub create geopolitical exposure and tariff vulnerability for brands without diversified assembly footprints.
- CE Marking Friction:The European Union's Toy Safety Directive compliance timelines delay product launches by 4-6 months versus domestic Chinese certification, compressing seasonal sales windows.
Strategic Opportunities
- Gesture Control Convergence:Hand-motion firmware originally developed for premium consumer drones is migrating downward into sub-$100 units, opening differentiation space for the 6-8 Years age bracket.
- Institutional Procurement Channels:School district bulk purchasing represents an underpenetrated volume pool distinct from holiday retail cycles, with multi-year curriculum adoption creating predictable replacement demand.
- Sub-250-Gram Regulatory Category:Aviation authority weight thresholds for simplified registration are incentivizing industrial design optimization around 249-gram platforms that bypass operator licensing requirements.
Industry Challenges
- Firmware Talent Scarcity:Embedded systems engineers with aviation sensor integration experience command premium compensation, constraining mid-tier manufacturers' in-house development capacity.
- Multi-Jurisdiction Certification Overhead:Simultaneous compliance with FAA Remote ID, EU CE marking, and China's GB standards requires parallel testing tracks that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone for Kids Market |
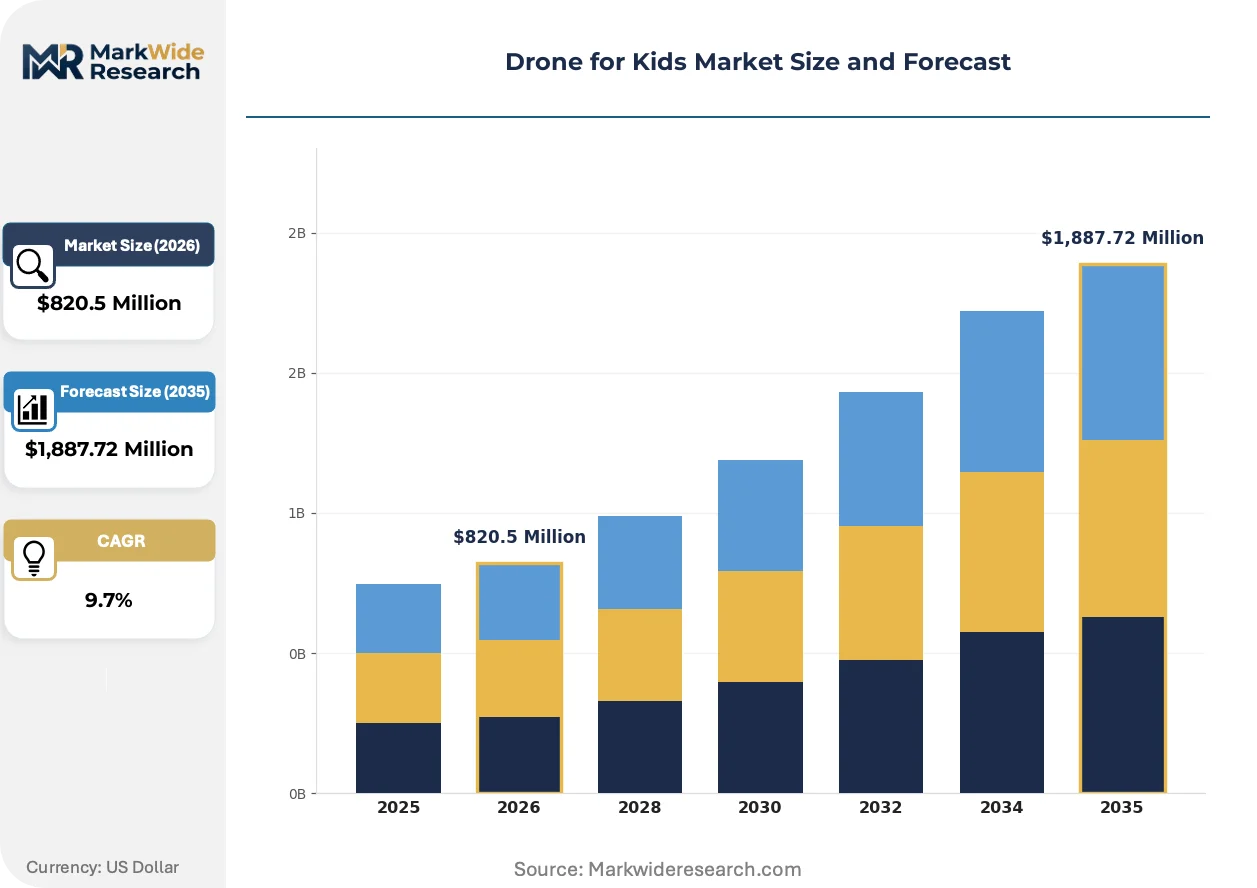
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,887.72 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Drones, Camera Drones, Racing Drones, Educational Drones Age Group: 3-5 Years, 6-8 Years, 9-12 Years, Teens Control Type: Remote Control, Smartphone Control, Gesture Control, Voice Control Sales Channel: Online Retailers, Specialty Toy Stores, Department Stores, Educational Supply Stores |
| Companies Covered | DJI, Parrot, Hubsan Technology, Syma Toys, Holy Stone, Horizon Hobby, Guangdong Cheerson Hobby Technology, Hasbro, Spin Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone for Kids Market Trends and Innovations
Active sensor miniaturization and regulatory pressure on traceability are compressing development cycles, forcing manufacturers to integrate aviation-grade components into toy-price platforms.
Computer vision modules for obstacle avoidance are converging with altitude-hold sensors in sub-$150 units. Primary schools adopting UAV science modules are specifying these features as baseline requirements. The technology convergence is collapsing the feature gap between recreational toys and entry-level prosumer devices, pressuring mid-tier pricing structures.
The EU's CE marking under the Toy Safety Directive is tightening electrical enclosure standards for lithium polymer battery compartments. Manufacturers targeting European member states must redesign housing geometries to accommodate additional thermal shielding. The Teens segment camera drones face the steepest compliance cost increases due to higher power densities in imaging subsystems.
Parental purchasing for educational outcomes is displacing impulse toy buying in the 9-12 Years bracket. School supply retailers are capturing shelf space previously held by big-box toy chains, altering cooperative advertising fund flows. This channel rotation is most visible in the United States, where district-level STEM grant programs concentrate volume through approved educational vendors rather than seasonal retail promotions.
Drone for Kids Market Segmentation
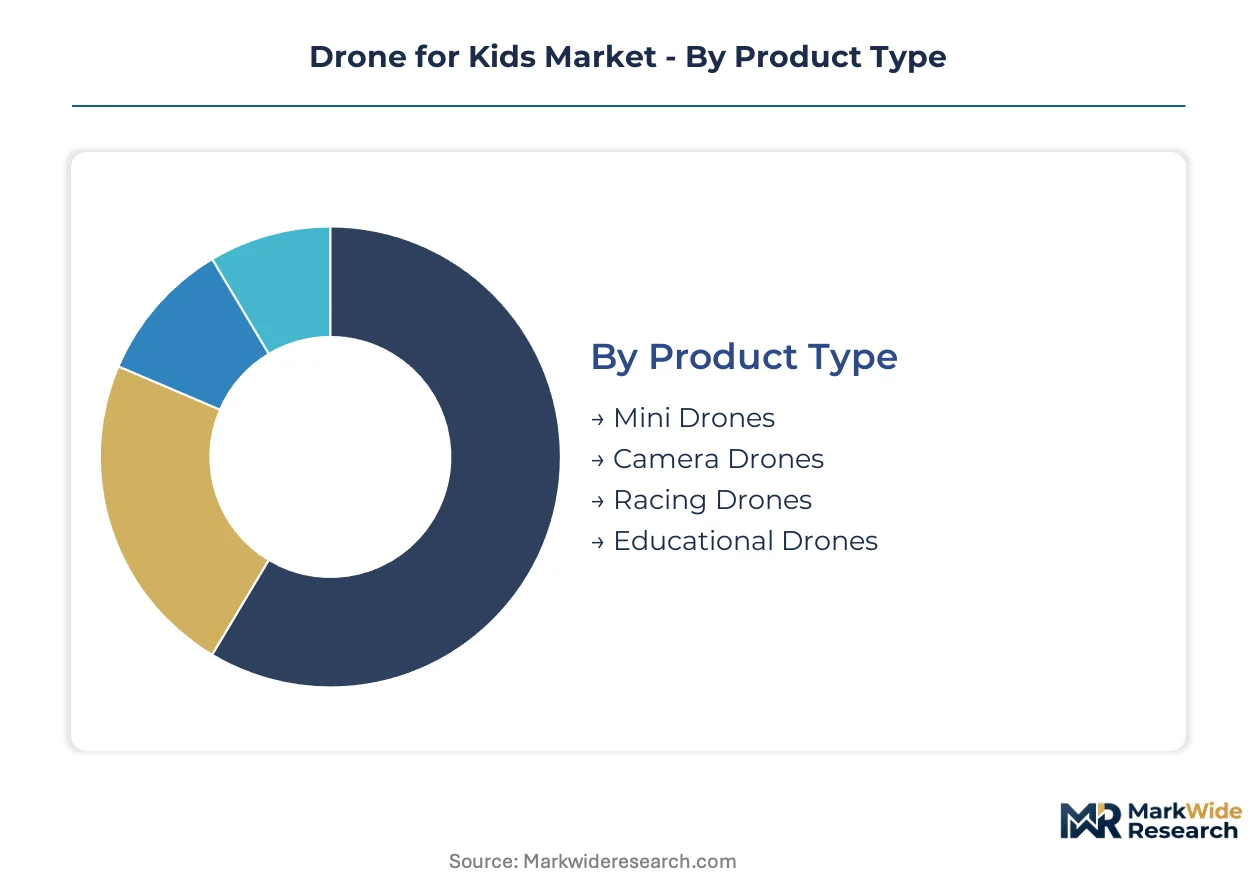
Segmentation in the Drone for Kids Market reveals how parental purchasing logic splits between recreational entertainment and structured learning outcomes. Manufacturers must align firmware capabilities and safety certifications with distinct age-based motor skill development stages rather than treating the category as a monolithic toy segment.
Product Type:
Parents weigh durability against feature density when selecting across product tiers, with educational outcomes commanding premium positioning.
- Mini Drones:Lightweight platforms under 100 grams with enclosed rotors and simplified altitude-hold sensors dominate entry-level procurement. Shenzhen manufacturers concentrate volume here for the 6-8 Years bracket where crash frequency demands polycarbonate resilience.
- Camera Drones:Imaging capabilities with 720p-1080p resolution and electronic image stabilization capture the highest margin pool as Teens segment parents prioritize photo-capture features for social sharing. FAA Remote ID compliance adds firmware cost layers that compress margins on sub-$150 units.
- Racing Drones:First-person-view headsets and manual flight mode overrides target adolescent operators with prior RC experience. Demand clusters in hobbyist communities rather than mainstream retail channels.
- Educational Drones:Programmable flight paths and block-coding interfaces align with primary school STEM curricula requirements. School district bulk purchasing in the United States is expanding most quickly as district-level grant programs fund UAV science modules.
Mini Drones lead on scale; Educational Drones lead on momentum.
Age Group:
Neurodevelopmental milestones dictate control interface complexity and parental safety oversight requirements across the childhood spectrum.
- 3-5 Years:One-button takeoff and foam-encased rotor guards accommodate limited fine motor control and high crash tolerance. Simplified controls reduce parental supervision burden in indoor environments.
- 6-8 Years:Gesture-control firmware adoption is climbing the fastest as hand-motion interfaces bypass joystick coordination barriers. Holy Stone and similar brands optimize UX for this bracket's spatial reasoning development stage.
- 9-12 Years:Dominates absolute unit volume through combined recreational and educational purchasing. School supply retailers capture shelf space from big-box toy chains as STEM outcomes displace impulse buying.
- Teens:Camera resolution and manual flight mode access become primary selection criteria. Social media content creation drives feature prioritization distinct from younger brackets.
The 9-12 Years bracket anchors volume concentration; the 6-8 Years bracket shows steepest expansion trajectory.
Control Type:
Interface modality selection tracks operator age, parental trust thresholds, and regulatory transmitter power constraints.
- Remote Control:Physical joysticks with 2.4GHz transmitter protocols remain the baseline for 9-12 Years operators developing fine motor precision. FCC Part 15 compliance requirements add certification overhead for US-bound shipments.
- Smartphone Control:Wi-Fi direct connection and touchscreen tilt-steering appeal to Teens segment digital natives. Latency limitations constrain adoption for precision flight applications.
- Gesture Control:Computer vision modules interpreting hand motion commands migrate from premium consumer tiers into sub-$100 units. Firmware development costs concentrate capability among Shenzhen-based engineering teams.
- Voice Control:Limited vocabulary recognition for basic commands targets the 3-5 Years bracket where manual coordination lags verbal capability. Microphone integration raises CE marking compliance complexity for European markets.
Remote Control retains installed base dominance; Gesture Control gains share fastest through technology convergence.
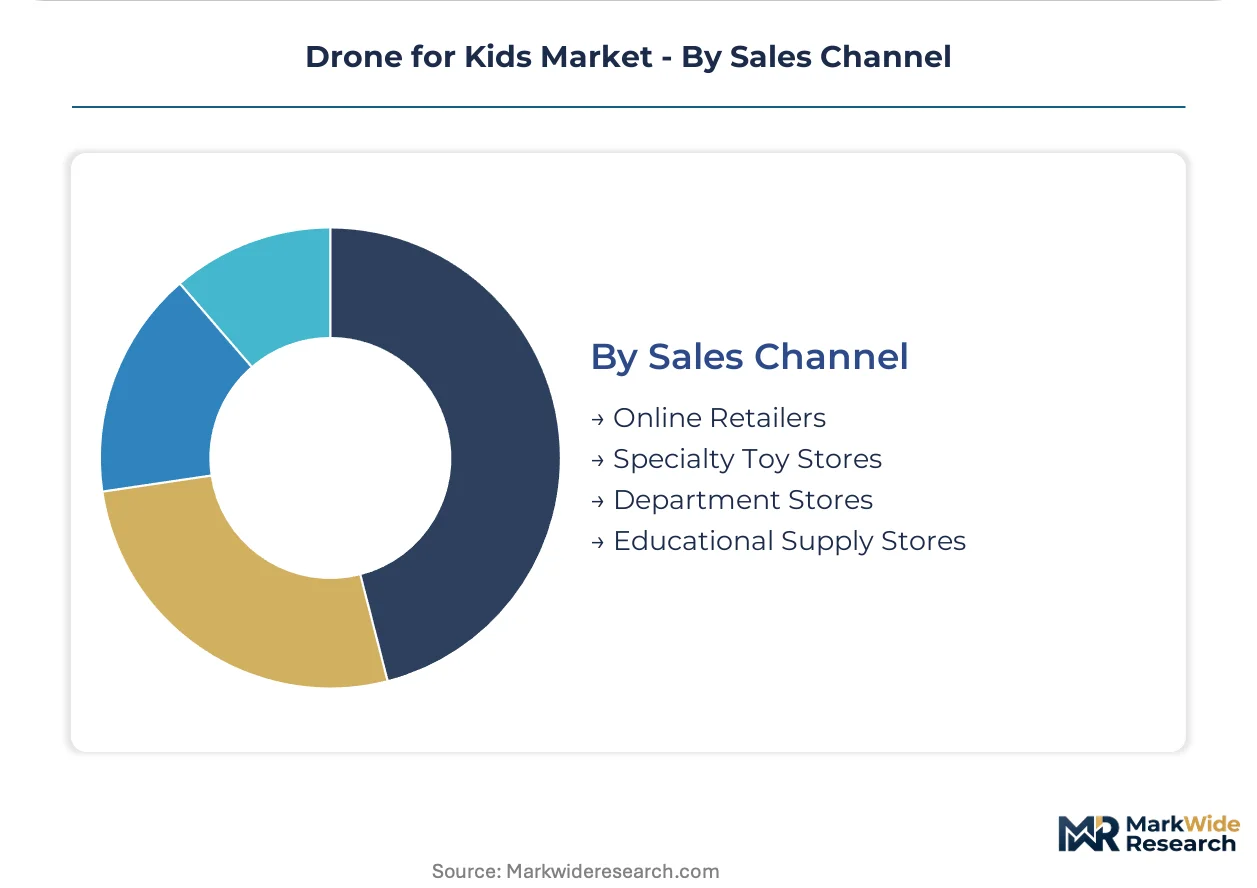
Sales Channel:
Channel selection reflects purchasing occasion timing and the educational versus recreational positioning of specific product configurations.
- Online Retailers:Amazon and direct-to-consumer platforms capture Teens segment camera drone volume through review-driven discovery and specification comparison tools. Return logistics complexity constrains entry-level mini drone economics.
- Specialty Toy Stores:Curated assortments and staff expertise support 6-8 Years parental decision-making where safety certification verification matters. Geographic concentration in suburban retail corridors aligns with family demographics.
- Department Stores:Seasonal promotional cycles and gift registry integration target holiday purchasing for the 3-5 Years bracket. Shelf space compression favors established brands with cooperative advertising funds.
- Educational Supply Stores:School district procurement portals and curriculum alignment certification open institutional volume distinct from consumer retail cycles. Multi-year adoption agreements create predictable replacement demand in the United States.
Online Retailers lead on transaction scale; Educational Supply Stores lead on contract predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing cluster anchors global production capacity for child-safe drone platforms, with component sourcing and firmware development concentrating in China's Pearl River Delta. Regulatory divergence across major demand markets is fragmenting certification requirements and reshaping export logistics for manufacturers.
United States
School district STEM grant programs are accelerating educational drone procurement through approved vendor channels. The FAA's Remote ID mandate for unmanned aircraft is forcing firmware architecture upgrades that improve parental oversight through integrated geofencing. California and Texas school systems lead institutional adoption volume.
China
Domestic demand for introductory STEM learning tools is expanding alongside export manufacturing. SAMR-administered GB standards for electronic toys set baseline electrical safety and battery enclosure requirements that Shenzhen manufacturers treat as the default design floor. The Pearl River Delta cluster enables rapid prototyping and cost-competitive production.
Germany
Parental prioritization of educational outcomes is shifting purchasing toward curriculum-aligned products. CE marking under the EU Toy Safety Directive constrains transmitter power and firmware architecture for devices entering European member states. Bavaria's technical universities support regional STEM program integration.
Japan
Precision manufacturing heritage is influencing demand for quality-differentiated platforms in the 9-12 Years bracket. METI guidelines on consumer electronics safety intersect with aviation authority classifications for sub-250-gram devices. The Kanto region around Tokyo concentrates retail distribution and educational procurement.
United Kingdom
Primary school science curriculum revisions are creating institutional volume distinct from seasonal retail cycles. The Civil Aviation Authority's weight-based registration thresholds incentivize industrial design optimization around 249-gram platforms. London and Southeast England anchor educational supply chain distribution.
Drone for Kids Market Competitive Landscape
Technology licensing dominates the current landscape as gesture-control firmware migrates from premium consumer tiers into sub-$100 units. The vendor base fragments between Shenzhen-based original equipment manufacturers controlling component costs and Western brands anchoring retail shelf presence through exclusive distribution agreements. Three archetypes define competitive positioning: vertically integrated electronics conglomerates, specialty toy brands with firmware optimization capabilities, and contract manufacturers serving institutional procurement channels. Portfolio diversification into educational modules and strategic partnerships with school district vendors represent the dominant competitive moves.
Among China-based original equipment manufacturers, DJI and Hubsan Technology exemplify scale-driven production archetypes leveraging Shenzhen manufacturing density. Holy Stone occupies a position within the specialty firmware tier, while Spin Master anchors North American retail presence through big-box toy chain partnerships. Guangdong Cheerson Hobby Technology represents the contract manufacturing segment serving institutional procurement channels.
| Leading Market Players |
|---|
| DJI |
| Parrot |
| Hubsan Technology |
| Syma Toys |
| Holy Stone |
| Horizon Hobby |
| Guangdong Cheerson Hobby Technology |
| Hasbro |
| Spin Master |
| Others |
Pricing and Supply Chain Analysis
School district STEM procurement mandates in the United States are compressing seasonal sales windows and forcing manufacturers to hold inventory across non-holiday quarters, eroding margin stability for entry-level mini drone tiers. This demand-side institutionalization rewards Shenzhen-based producers with flexible assembly footprints while penalizing brands locked into big-box toy chain promotional calendars.
Pricing Analysis
Polycarbonate resin cost pass-through from rotor housing suppliers is intensifying margin pressure in the sub-$100 mini drone tier where flight-time competitiveness hinges on power-to-weight optimization. Three-tier pricing structure across premium camera drones, standard educational kits, and economy mini units stratifies by certification grade and firmware capability. Pricing softness reflects lithium polymer cell volatility and the 4-6 month CE marking delay for European-bound shipments. The 3-5 Years bracket exhibits highest price sensitivity as parents treat foam-encased units as disposable trial purchases, while Teens segment camera drones command brand premiums for social-sharing features.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale component demand from Shenzhen assembly clusters, with polycarbonate resin distributors and altitude-hold sensor foundries feeding just-in-time production lines. Manufacturing gravity centers on China, with South Korea and Japan supplying precision gyroscope modules and image sensors. Raw material dependencies span lithium polymer cells from CATL and LG Chem supply chains, polycarbonate resin from SABIC and Covestro, and 2.4GHz transmitter chipsets from Nordic Semiconductor. Single-source vulnerability concentrates in Shenzhen firmware engineering talent pools. Distribution runs through educational supply portals, Amazon fulfillment centers, and big-box toy chain direct import programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drone for Kids Market functions as a geographic-arbitrage play where Shenzhen manufacturing cost structures undercut Western assembly by margins that absorb trans-Pacific logistics and tariff exposure. The FAA's Remote ID compliance burden in the United States creates a regulatory moat that favors incumbents with embedded systems engineering depth over pure contract manufacturers.
For Market Incumbents: To counter firmware talent scarcity in Shenzhen engineering clusters, anchor defensive positioning through backward integration into altitude-hold sensor calibration facilities and captive supply of polycarbonate rotor housings. Secure multi-year curriculum adoption agreements with U.S. school district procurement portals to insulate volume from holiday retail cyclicality. For New Entrants and Emerging Players: Enter via institutional procurement channels in the United Kingdom and Germany where CE marking compliance timelines have already filtered out undercapitalized competitors, leaving white space for curriculum-aligned educational drone kits with block-coding interfaces. Target Bavaria and Southeast England school systems with direct sales teams bypassing retail margin stacks. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated OEMs controlling both Shenzhen assembly capacity and Western educational supply chain relationships, positioned to capture margin expansion as FAA Remote ID compliance raises firmware development barriers. The inflection signal to watch is district-level STEM grant program consolidation in Texas and California shifting from pilot procurement to multi-year replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Architecture Upgrade | FAA Remote ID compliance opens premium positioning in U.S. institutional channels. |
| Educational Curriculum Partnership | District-level STEM grant alignment secures predictable replacement demand cycles. |
| Polycarbonate Material Transition | Crash resilience improvement supports indoor use positioning for younger brackets. |
| Gesture Control Integration | Computer vision module cost curves enable sub-$100 differentiation for 6-8 Years segment. |
| Sub-250-Gram Design Optimization | Aviation authority weight thresholds bypass operator licensing in EU and UK markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with firmware engineering directors at Shenzhen OEMs, procurement leads at U.S. school district vendors, category buyers at big-box toy chains, and regulatory affairs specialists navigating FAA Remote ID implementation. Secondary validation drew from FAA unmanned aircraft registry disclosures, EU CE marking notification databases, SAMR GB standards filings, and customs trade data on lithium polymer cell imports. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across age brackets and control types.
Segment-weighting approaches distributed volume and value projections across product type, age group, control interface, and sales channel dimensions throughout the forecast period. CAGRs derived from polynomial trend fitting to historical shipment trajectories, adjusted for regulatory inflection points including FAA Remote ID phase-in schedules and EU Toy Safety Directive enclosure standard revisions. Industry-specific forecast inputs incorporated school district STEM grant appropriation cycles and polycarbonate resin price indices from Asian petrochemical exchanges.
The model holds under stable lithium polymer supply conditions and continued district-level STEM funding authorization; deviation in battery cell trade policy or aviation authority weight threshold reclassification would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Construction Toys Market
Toys and Games
Pre-School Games and Toys Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Wooden Toys Market
Toys and Games
Sustainable Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Global Educational Toy Market
Toys and Games
Blind Box Toys Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Glow Sticks Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Bubble Blower Market