
 Self-Lacing Shoes Market | 2026-2036
Self-Lacing Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Lacing Shoes Market Outlook
Aftermarket battery replacement and firmware upgrade revenue is narrowing as manufacturers embed longer-life power cells and over-the-air update capabilities into first-generation units. Nike leverages vertical integration across electromechanical component design to control core tightening mechanisms. Puma anchors its position through selective partnerships with European football clubs that demand precise fit customization. Digitsole competes on sensor-density configurations that track gait metrics alongside lacing automation.
Self-lacing shoes incorporate motorized tightening systems, pressure sensors, and rechargeable power modules to deliver automated fit adjustment without manual lace manipulation. These systems typically operate through electromechanical actuators that respond to foot expansion during activity, serving commercial purposes in athletic performance optimization and accessibility applications for users with limited dexterity. Athletic shoes dominate current volume as professional sports leagues integrate wearables into training regimens, while sensor-based technology commands premium positioning through real-time biomechanical feedback. Smart shoes represent the fastest-growing product category as health-conscious consumers seek gait analysis alongside convenience features.
FCC certification requirements in the United States govern wireless transmission protocols for Bluetooth-enabled lacing systems, while EU REACH compliance constrains battery chemistry and synthetic material composition for European market access. China's SAMR enforces GB standards for electronic component safety in consumer wearables, creating multi-jurisdictional testing burdens for brands pursuing cross-border distribution. Stakeholders must monitor evolving e-waste directives that could mandate replaceable battery architectures and reshape hardware design roadmaps.
Market Dynamics
Miniaturized motor systems and electromechanical actuators are compressing component footprints while elevating unit economics, forcing manufacturers to redesign supply chains around precision electromechanical sourcing rather than traditional footwear materials.
Growth Catalysts
- Professional Sports Integration:Athletic leagues embed wearables into training protocols, creating institutional procurement pipelines for sensor-enabled footwear. Teams demand real-time biomechanical feedback during competition.
- REACH Compliance Maturation:EU battery chemistry standards now provide predictable certification pathways, reducing time-to-market for European distribution. Manufacturers align synthetic material selection with ECHA substance restrictions.
- Dexterity Accessibility Mandates:Aging populations and rehabilitation centers drive adoption among users with limited hand mobility. Medical device distributors now stock automated lacing systems alongside orthotic footwear.
Market Restraints
- Lithium-Ion Supply Concentration:Power cell sourcing clusters in East Asian refining operations, exposing brands to geopolitical disruption in battery mineral processing.
- FCC Certification Burden:Bluetooth-enabled lacing systems require multi-month wireless protocol testing in the United States, delaying product launches for cross-border entrants.
- Mechanical Durability Thresholds:Electromechanical actuators face accelerated wear in high-moisture environments, limiting warranty terms and increasing service cost reserves.
Strategic Opportunities
- India PLI Scheme Alignment:Electronics manufacturing incentives attract component assembly operations for price-sensitive Asian markets. Local production reduces import duty exposure.
- Healthcare Reimbursement Pathways:German statutory health insurers evaluate automated footwear for prescription coverage among diabetic foot care patients. Medical certification unlocks institutional volume.
- OTA Firmware Convergence:Over-the-air update capabilities merge with gait analytics platforms, enabling subscription revenue models alongside hardware sales. Software-defined functionality extends product lifecycles.
Industry Challenges
- Mechatronics Talent Scarcity:Footwear manufacturers compete with automotive and robotics sectors for electromechanical engineers capable of integrating motor systems into flexible substrates.
- Multi-Jurisdictional Testing Overhead:Simultaneous FCC, REACH, and SAMR compliance requires parallel certification tracks, straining quality assurance bandwidth and capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Lacing Shoes Market |
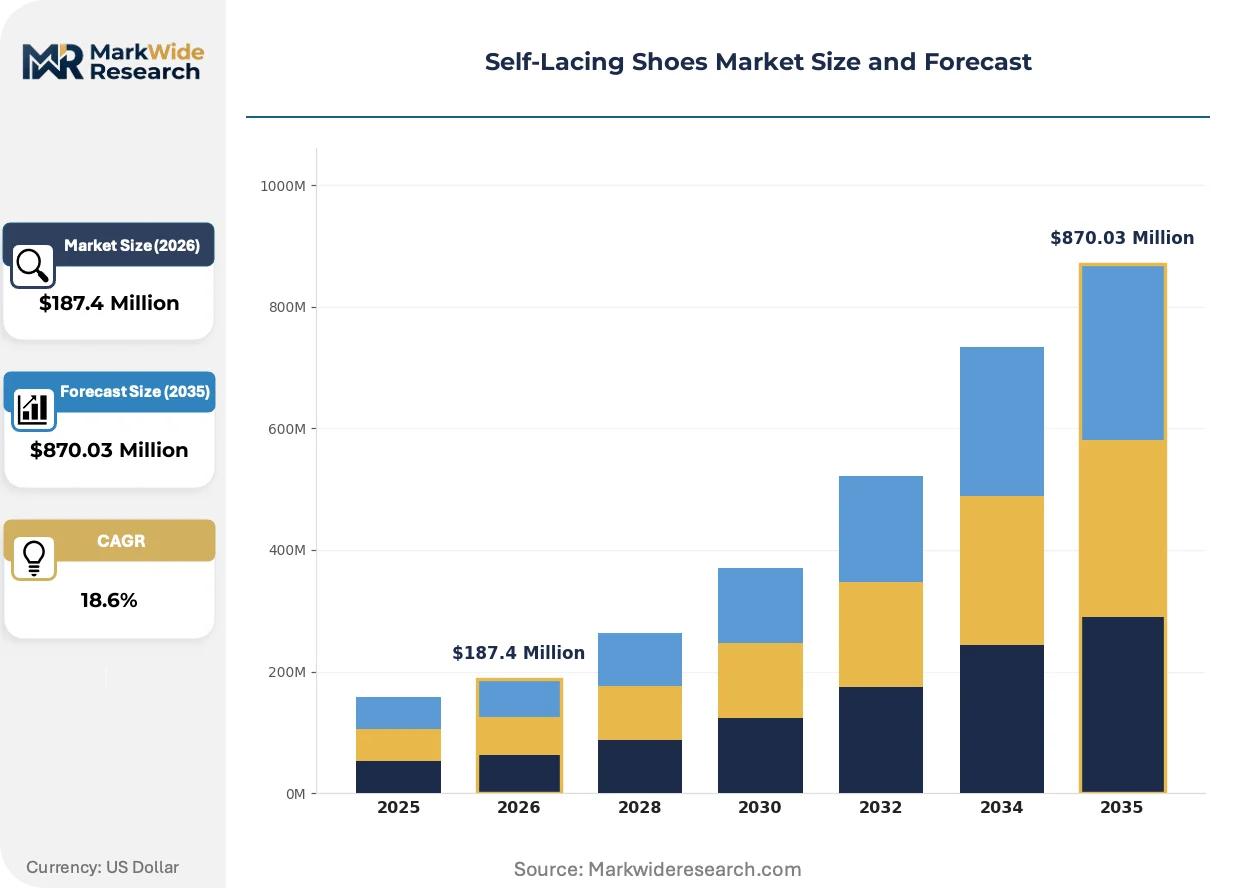
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Shoes, Athletic Shoes, Casual Shoes, Safety Shoes Technology: Electromechanical, Bluetooth, Sensor-Based, Power-Assisted End User: Adults, Kids, Athletes, Professionals Distribution Channel: Online Retail, Specialty Stores, Department Stores, Brand Outlets |
| Companies Covered | Nike, Puma, Adidas, Digitsole, Powerlace Technology, Power Laces, LLC, Under Armour, ASICS, New Balance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Lacing Shoes Market Strategic Shifts
Electromechanical architectures are displacing passive lacing systems across premium athletic segments, while regulatory pressure on battery chemistry and wireless transmission protocols reshapes hardware design priorities.
Solid-state battery cells are collapsing the volume requirements for power modules in automated footwear, enabling thinner midsole profiles without sacrificing charge cycles. Marathon runners and professional cyclists now specify energy density metrics in procurement tenders. This compression of power architecture is eliminating the heel-bulge aesthetic that constrained early-generation designs.
EU REACH substance restrictions are tightening disclosure requirements for synthetic polymers in wearable electronics, compelling manufacturers to reformulate housing materials ahead of sunset dates. ECHA candidate list updates now capture specific phthalates common in flexible cable sheathing. German and French distributors are prioritizing suppliers with pre-certified material declarations to avoid customs detention.
Direct-to-consumer gait analysis is displacing retail fitting sessions as primary purchase triggers, with mobile app ecosystems capturing biometric data ahead of transaction completion. Specialty running stores in the United States and China now function as experience showrooms rather than inventory fulfillment points. This channel compression is visible most acutely in urban markets where same-day delivery infrastructure supports try-before-commit models.
Self-Lacing Shoes Market Segmentation
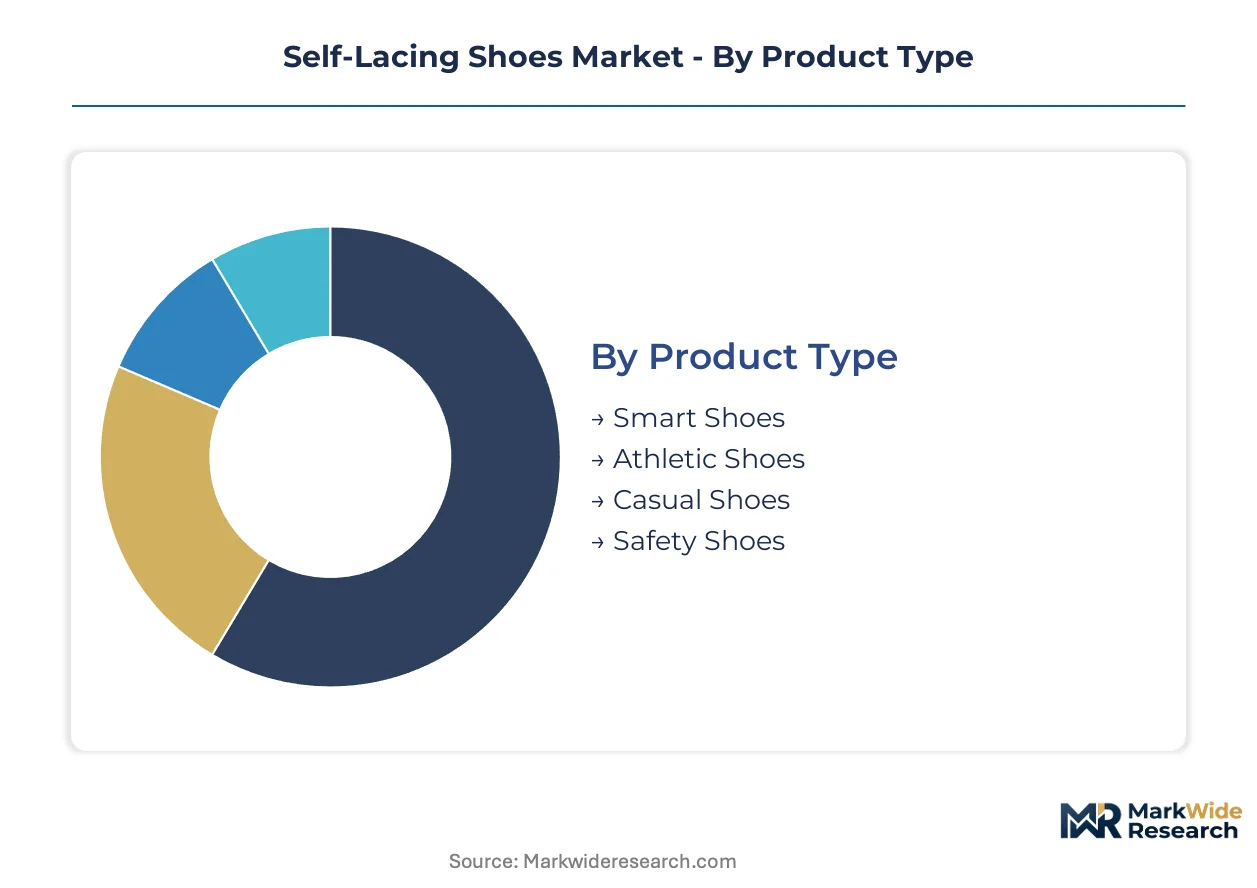
Segmentation in self-lacing footwear reveals divergent replacement cycles across use cases. Athletic applications demand annual refresh rates driven by biomechanical wear, while casual segments stretch toward three-year cycles. Understanding these velocity differences shapes inventory planning and warranty reserve calculations.
Product Type:
Athletic units turn over fastest at 12-18 month cycles, while safety and casual categories extend toward 36 months through durable construction mandates.
- Smart Shoes:Dense sensor arrays capture gait metrics, ground contact time, and pronation angles for health-conscious consumers. Demand clusters in urban China and Germany where digital health integration commands premium positioning. Firmware update capabilities extend functional lifespan beyond physical wear.
- Athletic Shoes:Electromechanical tightening systems respond to foot expansion during high-intensity activity, serving professional training regimens and competitive events. Professional sports teams in the United States and football clubs in Germany drive institutional procurement volume with specifications for real-time fit adjustment.
- Casual Shoes:Simplified motor configurations prioritize convenience over biometric tracking for everyday urban mobility.
- Safety Shoes:Reinforced housings and sealed actuator systems meet industrial workplace standards for moisture and impact resistance.
Athletic Shoes dominate installed base. Smart Shoes is where expansion concentrates.
Technology:
Cost tiers separate patent-protected electromechanical architectures from commodity Bluetooth connectivity modules.
- Electromechanical:Miniaturized motor systems and precision actuators deliver automated tension adjustment through mechanical linkages. Nike's vertical integration across component design and Puma's selective club partnerships anchor competitive positioning in this premium tier.
- Bluetooth:Wireless protocol stacks enable smartphone-controlled fit adjustment and activity logging. FCC certification requirements in the United States and SAMR GB standards in China create multi-jurisdictional testing burdens that filter out smaller entrants.
- Sensor-Based:Pressure and motion arrays trigger autonomous tightening responses without manual input.
- Power-Assisted:Hybrid architectures combine manual initiation with motorized completion for accessibility-focused applications.
Electromechanical systems command margin concentration. Bluetooth configurations are climbing the fastest through price-accessible consumer penetration.
End User:
Volume concentrates in adult recreational segments, while margin extraction favors professional athlete specifications and medical accessibility applications.
- Adults:Health-conscious consumers aged 25-45 drive sensor-enabled procurement for fitness tracking and convenience. Direct-to-consumer gait analysis apps in the United States and China now capture biometric data ahead of purchase completion, compressing traditional retail channels.
- Athletes:Professional and amateur competitors demand real-time biomechanical feedback and competition-legal fit automation. German statutory health insurers evaluate automated footwear for prescription coverage among diabetic foot care patients, unlocking institutional volume.
- Kids:Growth-adjustable tension systems accommodate rapid foot size changes without replacement.
- Professionals:Workplace safety specifications and medical rehabilitation centers drive adoption among users with limited hand mobility.
Adults dominate installed base. Athletes is where expansion concentrates.
Distribution Channel:
Supply concentration in direct-to-consumer platforms is forcing specialty retail into experience-showroom positioning.
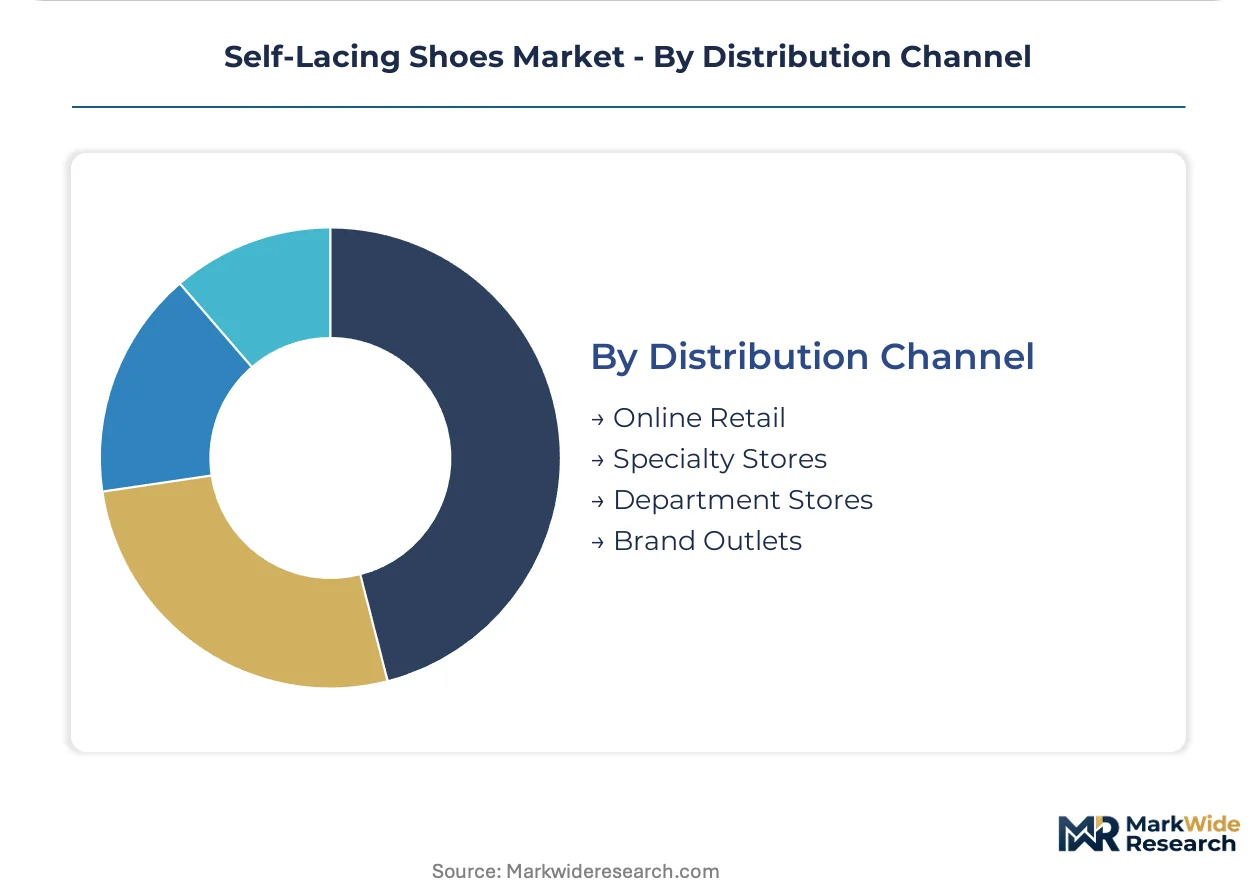
- Online Retail:Mobile app ecosystems and same-day delivery infrastructure support try-before-commit models in urban United States and Chinese markets. This channel captures the steepest expansion trajectory as digital-native consumers bypass physical fitting sessions.
- Specialty Stores:Running-focused retailers in the United States and Germany now function as biometric experience centers rather than inventory fulfillment points. Staff expertise in gait analysis justifies premium positioning against price-transparent online alternatives.
- Department Stores:Broad assortment strategies accommodate casual segment browsing with limited technical consultation.
- Brand Outlets:Direct manufacturer channels control pricing and warranty service for electromechanical systems requiring specialized support.
Specialty Stores dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Chinese consumers demand sub-premium Bluetooth configurations for mass-market penetration. German buyers absorb electromechanical premiums for medical-grade specifications. United States volume splits between athletic institutional procurement and accessibility-focused Medicare channels.
United States
Professional sports franchises and rehabilitation centers drive dual demand tracks. FCC certification timelines for Bluetooth-enabled lacing systems extend product launch cycles by four to six months. Boston and Los Angeles host concentrated specialty retail networks that function as biometric experience centers rather than inventory points.
Germany
Football club procurement specifications and statutory health insurance reimbursement pathways for diabetic foot care create institutional volume. ECHA REACH substance restrictions on synthetic polymers compel housing material reformulation ahead of 2026 sunset dates. Bavaria's industrial electronics corridor supplies precision actuator components to footwear assemblers.
China
SAMR GB standards enforcement for electronic component safety in consumer wearables creates compliance barriers for cross-border entrants. Yangtze River Delta manufacturing clusters produce miniaturized motor systems at scale for price-sensitive Asian distribution. Shanghai and Shenzhen direct-to-consumer platforms capture the steepest online retail expansion trajectory.
India
PLI scheme electronics manufacturing incentives attract component assembly operations for cost-optimized regional supply. BIS certification requirements for electronic consumer goods extend time-to-market for first-time entrants. Maharashtra and Karnataka host emerging specialty retail footprints in Mumbai and Bangalore urban corridors.
Japan
Aging demographic accessibility mandates and METI industrial standards for wearable electronics converge on medical-rehabilitation applications. JIS certification protocols for electronic component safety filter out smaller import competitors. Tokyo-Osaka corridor specialty retailers emphasize gait analysis integration for health-conscious consumer segments.
Self-Lacing Shoes Market Competitive Environment
Capability concentration sits with vertically integrated electromechanical designers; scale advantage sits with apparel conglomerates leveraging existing retail infrastructure. The market structures around three tiers: patent-protected mechanism specialists, sensor-density configurators, and brand-licensed assemblers. Dominant competitive moves include backward integration into motor system sourcing and selective partnership anchoring with professional sports institutions.
Within the integrated-design tier, Nike and Puma exemplify divergent pathway strategies. Digitsole occupies a position among sensor-density specialists competing on biomechanical data capture alongside lacing automation. These three anchors illustrate how competitive positioning separates mechanism control from data platform ownership.
| Leading Market Players |
|---|
| Nike |
| Puma |
| Adidas |
| Digitsole |
| Powerlace Technology |
| Power Laces, LLC |
| Under Armour |
| ASICS |
| New Balance |
| Others |
Value Chain & Pricing Dynamics
East Asian lithium-ion refining operations concentrate power cell sourcing for automated footwear, anchoring margin pools with electromechanical system designers who control tightening mechanism patents rather than brand licensors. This upstream battery chemistry concentration forces downstream pricing stratification across premium electromechanical tiers and accessible Bluetooth configurations.
Pricing Analysis
Aftermarket battery replacement and firmware upgrade revenue streams are narrowing as manufacturers embed longer-life power cells and over-the-air update capabilities into first-generation units. Three-tier pricing structure across premium electromechanical, standard sensor-based, and economy Bluetooth levels separates Nike's vertically integrated architectures from Digitsole's sensor-density configurations and mass-market alternatives. Pricing pressure stems from REACH compliance maturation reducing European certification friction and expanding competitor entry. Casual adult segments exhibit highest price sensitivity, while professional athlete specifications and German medical accessibility channels absorb premium positioning.
Supply Chain Analysis
Yangtze River Delta contract manufacturers hold dominant capacity for miniaturized motor system assembly, with Bavaria's industrial electronics corridor supplying precision actuator components. Lithium-ion cells, electromechanical actuators, and synthetic polymer housings constitute critical input dependencies. Single-source vulnerability clusters in East Asian battery mineral processing expose brands to geopolitical disruption. Distribution runs through direct-to-consumer platforms capturing steepest expansion, with specialty retail repositioning as biometric experience centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FCC, REACH, and SAMR certification burdens create multi-jurisdictional barriers that filter out capital-constrained entrants and protect incumbent positioning.
For Market Incumbents: Harden supply chain resilience through captive sourcing of electromechanical actuators from Bavaria's precision component corridor, insulating against East Asian battery mineral disruption. Deepen firmware platform ownership to capture subscription revenue from gait analytics services, defending against pure-play sensor specialists eroding hardware margins.
For New Entrants and Emerging Players: Establish a beachhead in India's price-sensitive segments leveraging PLI scheme electronics manufacturing incentives for cost-optimized regional assembly. Target accessibility-focused medical rehabilitation centers in Japan's aging demographic corridors, where METI standards convergence creates procurement pathways without direct competition from athletic brand incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mechanism specialists with patent-protected electromechanical architectures and established FCC certification track records. Long-term viability favors acquirers who can bridge five-to-ten year windows of healthcare reimbursement expansion. Monitor German statutory health insurer prescription coverage decisions for diabetic foot care as inflection signal for institutional volume unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor System Sourcing | Nike's captive supply of electromechanical actuators from Bavaria insulates against East Asian battery mineral disruption. |
| Healthcare Reimbursement Certification | German statutory health insurer evaluation of automated footwear for diabetic foot care unlocks institutional prescription volume. |
| OTA Firmware Platform Development | Subscription revenue from gait analytics services extends product lifecycles beyond physical wear cycles. |
| PLI Scheme Manufacturing Alignment | India's electronics manufacturing incentives enable cost-optimized component assembly for price-sensitive Asian distribution. |
| Selective Sports Institution Partnership | Puma's European football club anchoring creates procurement specifications that competitors cannot easily replicate. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with footwear brand product managers, electromechanical component engineers, specialty retail gait analysis specialists, and German statutory health insurer reimbursement evaluators. Secondary validation drew from FCC equipment authorization databases, ECHA REACH substance restriction updates, SAMR GB standard filings, and athletic league wearable procurement tenders. Bottom-up unit economics modeling triangulated against top-down market sizing from trade customs data and electronics component import records.
Calibration across the analysis window employed segmented growth rate derivation by product type, technology tier, end-user archetype, and distribution channel, with cross-reference to regional regulatory cluster adoption curves. CAGRs were computed from annualized shipment velocity and average selling price trajectories. Industry-specific forecast inputs included marathon runner energy density procurement specifications and professional cycling team biomechanical feedback integration timelines.
Sensitivities concentrate around lithium-ion supply disruption, REACH substance restriction sunset dates, and FCC certification timeline extensions. Forecasts reflect documented assumptions on battery chemistry stability and wireless protocol standardization. Quarterly review of German health insurer reimbursement decisions, SAMR enforcement intensity, and solid-state battery commercialization milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Mountain Bike Footwear and Socks Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
White Sneakers Market
Footwear
Kids Barefoot Shoes Market
Footwear
Duck Boots Market
Footwear
Slip on Shoes Market
Footwear
Custom Shoes Market
Footwear
Ankle Boots Market
Footwear
Driving Footwear Market
Footwear
Cowboy Boots Market
Footwear
Winter Footwear Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Waterproof Sneakers Market
Footwear
Protective Footwear Market
Footwear
Tactical Footwear Market
Footwear
UK Lifestyle Sneakers Market