
 Tattoo Stencil Printer Market | 2026-2036
Tattoo Stencil Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Stencil Printer Market Insights
Professional-grade thermal transfer resolution is rotating the market upward as studios abandon hand-traced stencils for digitally precise replication. Brother Group leverages its decades of thermal printing R&D to anchor supply relationships with high-volume studio chains across Japan and North America. Epson competes through pigment-ink durability patents that extend stencil longevity on complex skin surfaces. Shijiazhuang Dragonhawk Tattoo Supply Co., Ltd. dominates budget-tier export channels with vertically controlled manufacturing in Hebei Province.
A tattoo stencil printer is a dedicated peripheral that reproduces artwork onto transfer paper or synthetic film via thermal, inkjet, or laser deposition, typically achieving 300-600 dpi resolution to ensure line fidelity during skin application. The device serves commercial tattooing by eliminating hand-tracing errors and accelerating client throughput. Thermal printers lead unit shipments due to low consumable costs and compact studio footprints, while digital printing technology captures margin pools through software-integrated design workflows. End-user concentration among tattoo studios sustains premium pricing for networked fleet models, whereas freelance artists drive portable single-unit demand.
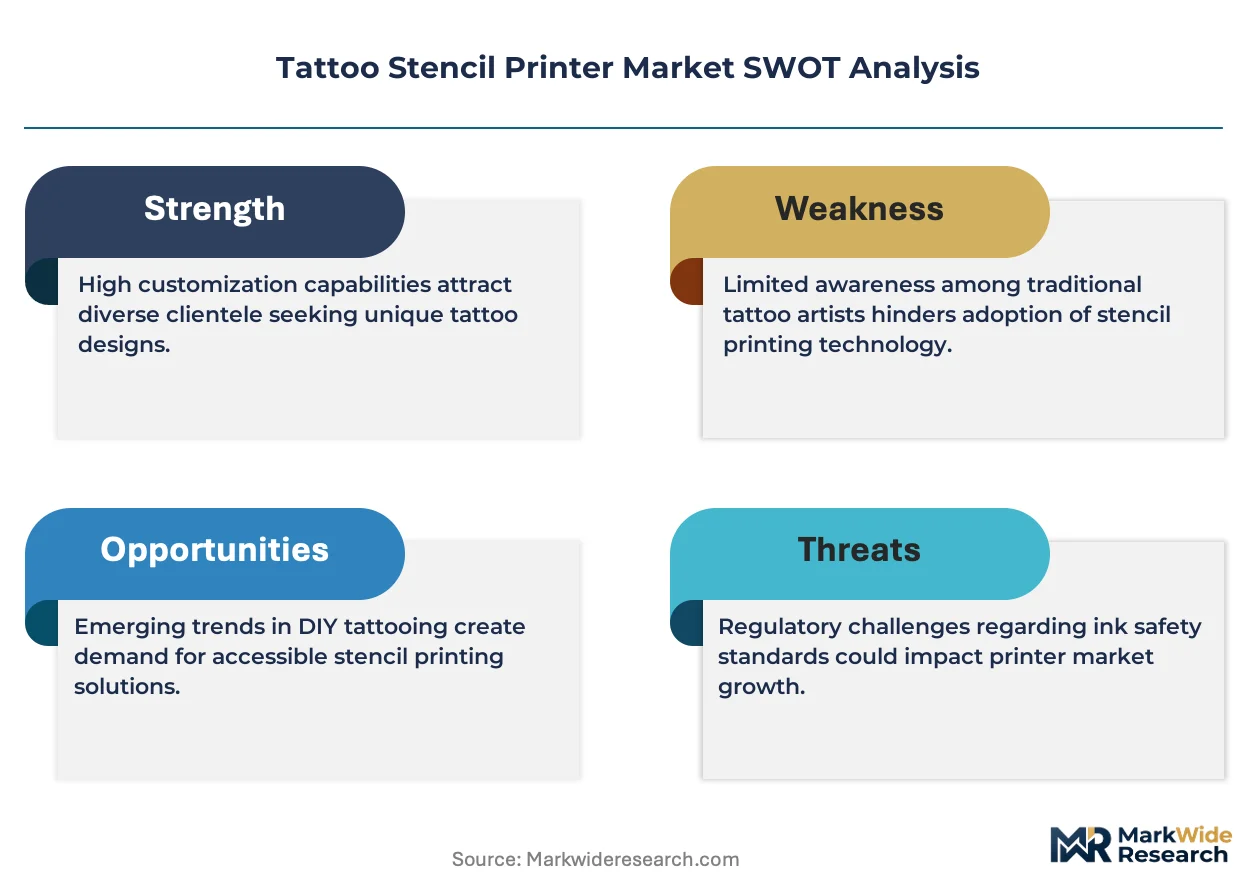
FDA Center for Devices and Radiological Health oversight of laser-emitting stencil systems shapes product certification pathways for US market entry. REACH compliance for thermal paper chemical coatings restricts European supply options and elevates testing expenditures for Asian exporters. EU MDR-aligned skin-contact material standards further constrain film substrate formulations. Stakeholders must monitor evolving state-level tattoo facility licensing rules that increasingly mandate documented sterilization protocols for reusable printer components.
Market Dynamics
Bluetooth-enabled thermal transfer units are consolidating studio procurement decisions as artists prioritize wireless design workflows over tethered legacy systems, compressing replacement cycles and elevating software-integrated equipment premiums.
Growth Catalysts
- EU MDR skin-contact standards:Tattoo studios in Germany and France now demand certified film substrates, pulling manufacturers toward compliant supply chains and widening premium equipment margins.
- Metropolitan studio clustering:Dense tattoo districts in Los Angeles, London, and Seoul generate concentrated equipment refresh demand as competitive pressure forces technology upgrades.
- Thermal transfer R&D spillover:Decades of receipt printer innovation from Japanese electronics conglomerates now transfer directly into compact, high-resolution stencil hardware.
Market Restraints
- REACH thermal paper compliance:ECHA restrictions on bisphenol-A coatings force European distributors to source alternative chemistries at elevated testing cost.
- Hebei Province supply concentration:Budget-tier export channels depend on vertically controlled manufacturing clusters vulnerable to regional logistics disruptions.
- Pigment-ink humidity sensitivity:Inkjet stencil systems suffer degraded output fidelity in high-moisture climates, limiting deployment in tropical studio environments.
Strategic Opportunities
- FDA laser device classification pathway:Emerging laser-emitting stencil systems face clarified 510(k) clearance routes, enabling first-mover positioning in precision dermatological marking.
- Portable single-unit freelance segment:Independent artists operating across multiple pop-up locations generate unmet demand for battery-powered compact thermal printers.
- Software-integrated design workflows:Convergence of tablet-based design applications with wireless printer protocols creates subscription revenue potential for equipment vendors.
Industry Challenges
- Artist certification compliance timelines:EU member states increasingly mandate documented sterilization protocols for reusable printer components, extending onboarding friction for new equipment vendors.
- Cross-platform design file compatibility:Proprietary raster formats from competing design software create integration complexity for universal printer drivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Stencil Printer Market |
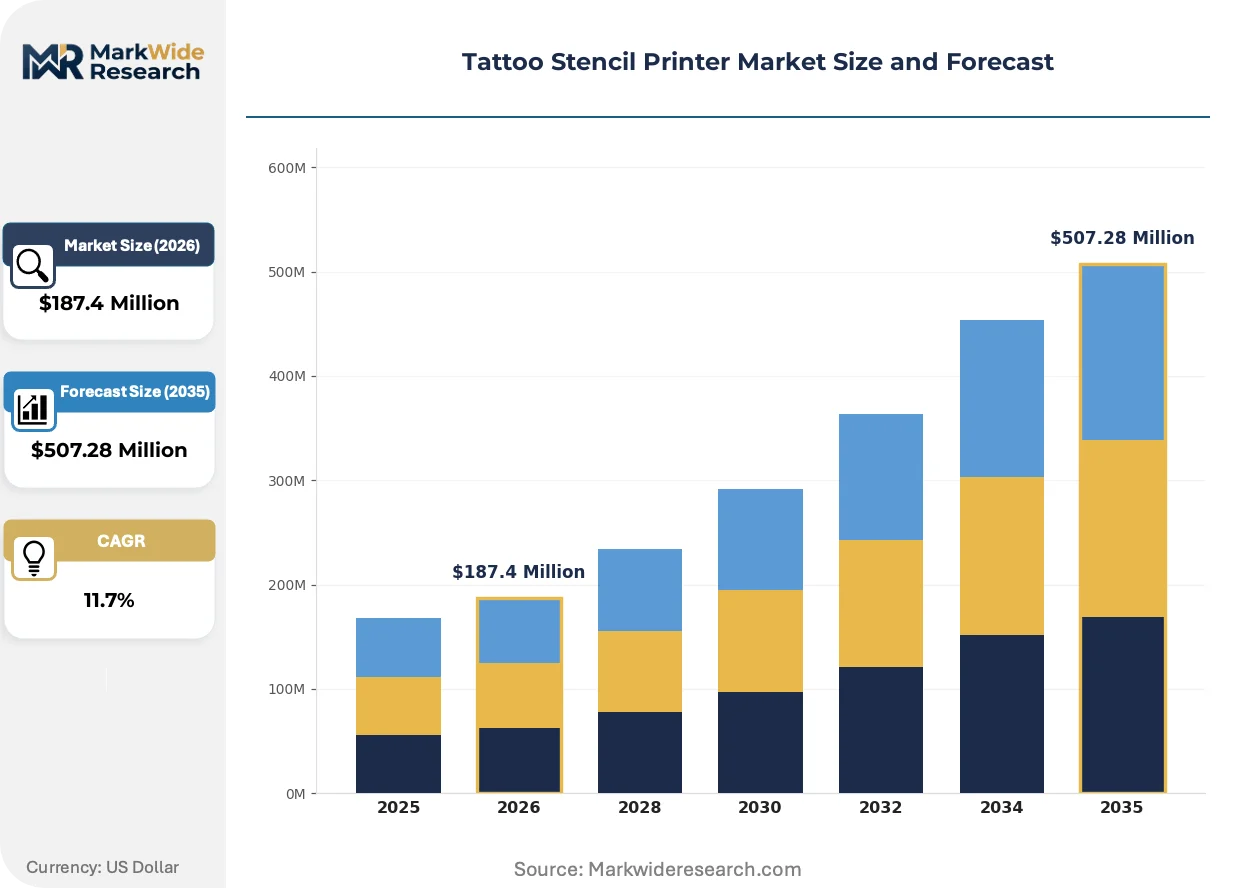
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Thermal Printers, Laser Printers, Rotary Printers End User: Tattoo Studios, Freelance Artists, Cosmetic Clinics, Schools Technology: Digital Printing, UV Printing, Sublimation, Heat Transfer Material: Paper, Vinyl, Film, Speciality Papers |
| Companies Covered | Brother Group, Epson, Shijiazhuang Dragonhawk Tattoo Supply Co., Ltd., Atomus, Phomemo, Prinker, Inkbox, Life Basis, Zinnor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Stencil Printer Market Trends and Innovations
Wireless connectivity protocols and cloud-based design repositories are dissolving the tether between artist workstations and output hardware, enabling mobile-first studio layouts and decentralized production workflows.
Thermal transfer deposition technology is supplanting hand-traced stencil preparation in high-volume studio chains across Japan and North America. These operators now deploy networked fleet models with centralized design libraries. The shift is compressing per-client preparation time from fifteen minutes to under ninety seconds while eliminating transcription errors.
REACH chemical safety frameworks are constraining thermal paper coating formulations across European supply channels. Manufacturers must reformulate bisphenol-free alternatives and submit extended toxicity dossiers to ECHA. German distributors have responded by consolidating supplier relationships with REACH-registered coating specialists in Switzerland and Austria.
Freelance artists are fragmenting procurement authority away from centralized studio equipment budgets toward personal hardware ownership. Individual practitioners now purchase portable units through direct-to-consumer channels rather than distributor networks. This pattern concentrates in South Korea's independent tattoo scene and Australia's mobile artist community.
Tattoo Stencil Printer Market Segmentation
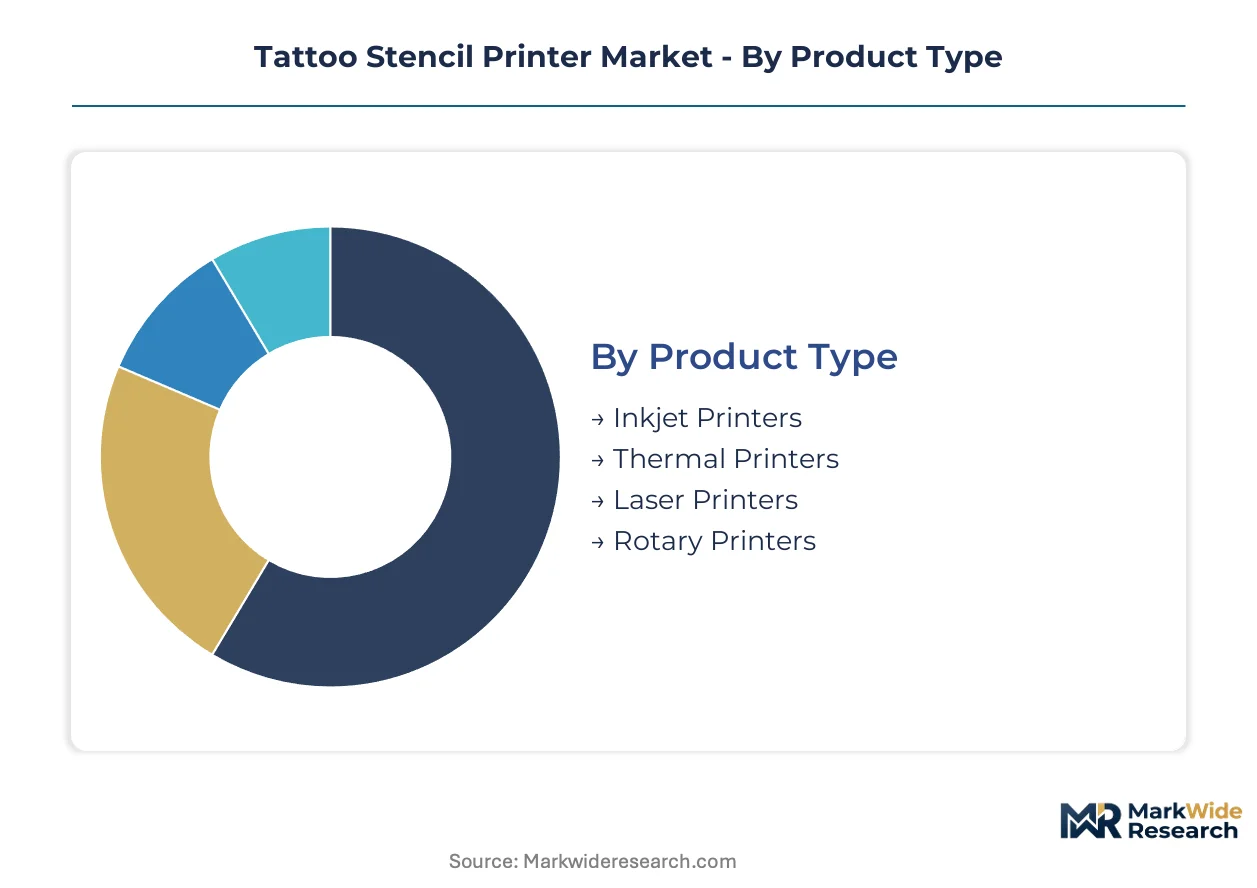
Tattoo stencil printer procurement splits sharply between high-volume studio chains seeking networked fleet deployment and independent operators prioritizing portability. Technology choices determine consumable economics, while end-user concentration shapes regional distribution strategies.
Product Type:
Margin pools concentrate in thermal printer hardware where Japanese electronics conglomerates leverage receipt printer R&D spillover into compact studio equipment.
- Thermal Printers:These units deposit wax-based ink through heated printheads onto transfer paper at 300-600 dpi resolution. Los Angeles studio clusters favor networked thermal fleets for their sub-ninety-second stencil preparation and minimal maintenance overhead. Bluetooth-enabled models command premium pricing as artists abandon tethered legacy systems.
- Inkjet Printers:Pigment-ink systems achieve superior color gradation for complex multi-tone designs. Epson's durability patents extend stencil longevity on challenging skin surfaces, though humidity sensitivity restricts deployment in tropical studio environments like Miami and Singapore.
- Laser Printers:Toner-based deposition offers archival-grade line precision for large-format back pieces. FDA Center for Devices and Radiological Health oversight of laser-emitting systems shapes 510(k) clearance pathways for US market entry.
- Rotary Printers:Mechanical embossing units serve budget-conscious entry-level artists in emerging markets. Hebei Province manufacturing clusters supply these through vertically controlled export channels vulnerable to regional logistics disruptions.
Thermal Printers hold installed capacity. Inkjet Printers are rotating up the share rankings.
End User:
Volume concentration tilts toward tattoo studios, though freelance artist fragmentation is redirecting procurement through direct-to-consumer channels.
- Tattoo Studios:High-volume operators in London's Shoreditch and Seoul's Hongdae districts deploy centralized design libraries with fleet-managed thermal units. Competitive pressure forces technology refresh cycles as studios compete on client throughput metrics.
- Freelance Artists:Independent practitioners operating pop-up locations generate unmet demand for battery-powered compact thermal printers. South Korea's independent tattoo scene and Australia's mobile artist community concentrate this procurement pattern.
- Cosmetic Clinics:Medical aesthetic facilities require REACH-compliant film substrates for semi-permanent makeup applications. EU MDR skin-contact standards pull these operators toward certified equipment margins.
- Schools:Tattoo training academies prioritize entry-level rotary and thermal units for student practice. Certification compliance timelines extend onboarding friction for equipment vendors supplying this segment.
Tattoo Studios dominate current shipments. Freelance Artists are expanding most quickly as personal hardware ownership displaces studio-provided equipment.
Technology:
Software-integrated workflows concentrate value capture in digital printing platforms with wireless protocol convergence.
- Digital Printing:Tablet-based design applications paired with wireless printer protocols enable subscription revenue models for equipment vendors. Cloud-based design repositories dissolve tether constraints between artist workstations and output hardware.
- Heat Transfer:Thermal wax deposition remains the workhorse for commercial tattooing due to low consumable costs and compact studio footprints. Decades of receipt printer innovation from Brother Group and compatriots transfer directly into stencil hardware.
- UV Printing:Ultraviolet-cured inks offer instant-dry operation for high-throughput environments. ECHA restrictions on photoinitiator chemicals elevate testing expenditures for European supply options.
- Sublimation:Dye-transfer technology achieves photographic reproduction quality for portrait work. Specialized substrate requirements limit adoption to premium studio tiers in Tokyo and New York.
Heat Transfer maintains volume leadership. Digital Printing is climbing the fastest as software-integrated workflows displace standalone hardware.
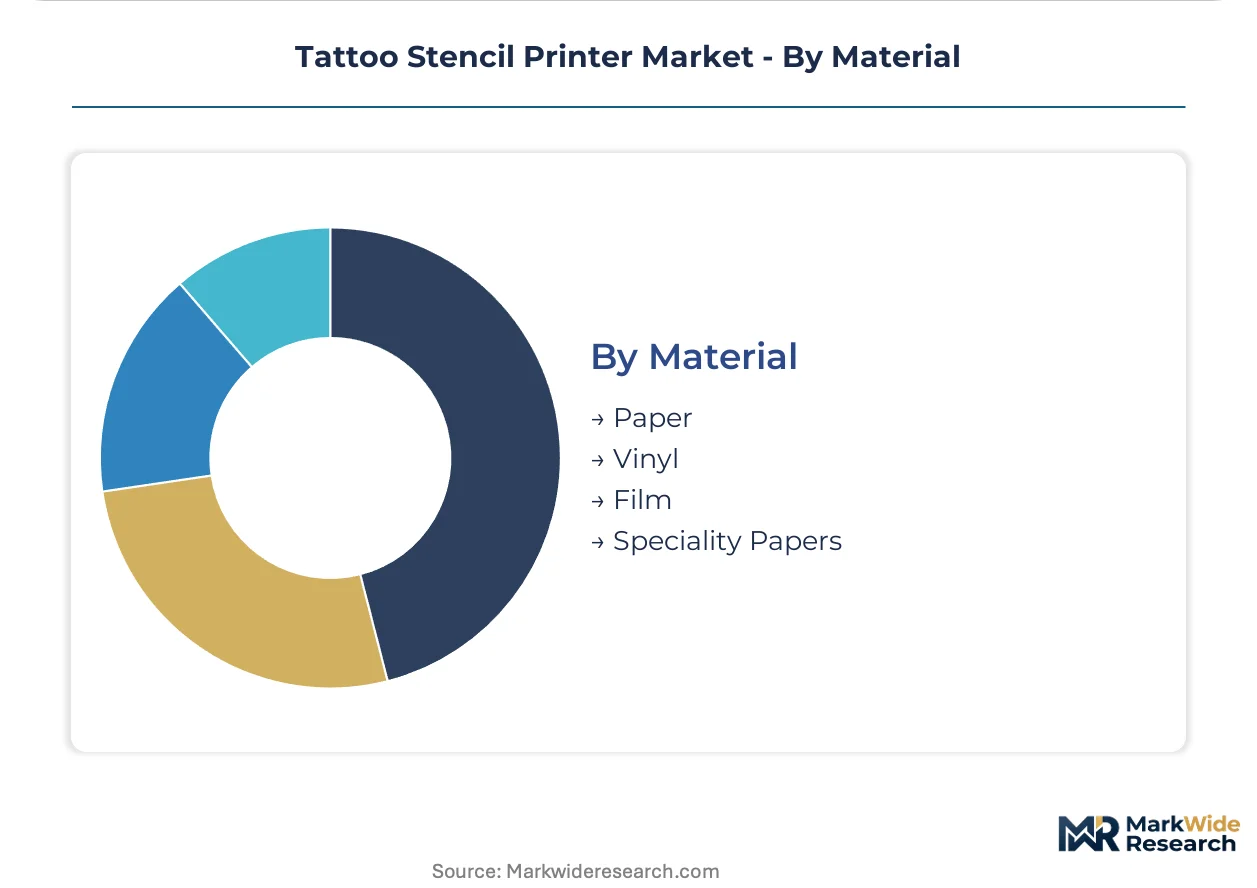
Material:
Film substrates command premium positioning under tightening EU MDR skin-contact standards, while paper remains the volume anchor.
- Film:Synthetic polymer substrates achieve superior line fidelity and moisture resistance during skin application. REACH compliance for thermal paper chemical coatings restricts European supply options and elevates testing expenditures for Asian exporters.
- Paper:Thermal transfer paper dominates unit economics through low per-sheet costs. Bisphenol-A coating restrictions force reformulation toward ECHA-registered alternative chemistries from Swiss and Austrian specialists.
- Vinyl:Flexible polymer backing suits curved body surfaces and extended wear testing. Cosmetic clinics in Germany and France specify medical-grade vinyl for regulatory compliance.
- Speciality Papers:Archival-grade cotton rag and synthetic blends serve collectors and museum-quality documentation. Limited volume concentrates in high-end Tokyo and Los Angeles ateliers.
Paper retains shipment volume leadership. Film is gaining share fastest as regulatory compliance premiums widen price differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Japanese and Chinese manufacturing hubs dominate international supply, while import demand concentrates in studio-dense metropolitan districts across North America and Europe. Regional regulatory divergence around skin-contact materials and laser device classifications fragments certification pathways and elevates compliance expenditures for cross-border vendors.
United States
FDA Center for Devices and Radiological Health oversight of laser-emitting stencil systems mandates 510(k) clearance for precision dermatological equipment entering the market. Los Angeles studio clusters drive premium equipment procurement as competitive pressure forces technology refresh cycles. State-level tattoo facility licensing rules in California and New York increasingly mandate documented sterilization protocols for reusable printer components.
Germany
EU MDR-aligned skin-contact material standards constrain film substrate formulations for tattoo studios in Berlin and Hamburg. ECHA REACH restrictions on bisphenol-A thermal paper coatings force distributors toward Swiss and Austrian registered alternative chemistry suppliers. Bavarian training academies extend equipment vendor onboarding friction through certification compliance timelines for sterilization documentation.
South Korea
MFDS medical device classification guidelines shape import pathways for cosmetic marking equipment serving Seoul's Hongdae tattoo district. Independent artists operating pop-up locations fragment procurement authority toward personal hardware ownership through direct-to-consumer channels. Busan-Ulsan manufacturing corridors supply compact thermal units leveraging decades of electronics conglomerate R&D spillover.
Japan
METI industrial standards for thermal printing equipment transfer directly into compact stencil hardware development by domestic electronics manufacturers. Tokyo's premium atelier tier concentrates demand for sublimation dye-transfer systems achieving photographic reproduction quality. Osaka-Kansai studio chains deploy networked fleet models with centralized design libraries to compress per-client preparation time.
United Kingdom
CE marking requirements under EU-UK Trade and Cooperation Agreement continuity provisions govern laser-emitting device market access for London Shoreditch studio operators. REACH-aligned chemical safety frameworks constrain thermal paper coating formulations across British supply channels. Manchester and Birmingham training schools prioritize entry-level rotary and thermal units for student practice equipment.
Tattoo Stencil Printer Market Competitive Landscape
Listed leaders compete with private specialists across certification tiering, with electronics conglomerates holding thermal printing patents against focused tattoo supply houses controlling budget export channels. The vendor base separates into three strategic archetypes: diversified technology conglomerates with receipt printer R&D heritage, vertically integrated Chinese manufacturing specialists, and design-software-integrated equipment vendors. Competitive moves concentrate on geographic expansion into studio-dense metropolitan clusters and technology licensing agreements to secure wireless protocol integration.
Within the diversified conglomerate tier, Brother Group and Epson exemplify players leveraging decades of thermal deposition and pigment-ink durability research into stencil hardware supply relationships. Among vertically integrated specialists, Shijiazhuang Dragonhawk Tattoo Supply Co., Ltd. occupies a position representing budget-tier export channel control through Hebei Province manufacturing concentration. These three anchors illustrate the competitive tension between premium branded equipment and cost-optimized supply chain dominance.
| Leading Market Players |
|---|
| Brother Group |
| Epson |
| Shijiazhuang Dragonhawk Tattoo Supply Co., Ltd. |
| Atomus |
| Phomemo |
| Prinker |
| Inkbox |
| Life Basis |
| Zinnor |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Hebei Province manufacturing clusters lock in thermal printhead supply access and stabilize unit cost visibility for distributors serving European REACH-compliant markets. These arrangements insulate procurement budgets from spot-market volatility in bisphenol-A-free coating chemistries while committing volume thresholds that shape pricing negotiations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA certification tier and volume scale, with networked fleet models commanding premiums over portable single units. Cost compression in the budget tier is intensifying because Hebei Province manufacturers are consolidating export channels. Freelance artists exhibit highest price sensitivity, while high-volume studio chains in Los Angeles and Seoul prioritize throughput metrics over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy as REACH-registered coating specialists in Switzerland and Austria face extended toxicity dossier timelines. Manufacturing concentrates in China, Japan, and South Korea. Raw material dependencies include thermal printheads, wax-based ink formulations, and synthetic film substrates. Single-source vulnerability runs through vertically controlled Hebei Province clusters. Distribution runs through tattoo supply distributors and direct-to-consumer channels serving freelance artists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in wireless protocol integration expertise and REACH-registered coating chemistry access is concentrating competitive advantage among vendors with established electronics conglomerate heritage. Firms lacking these capabilities face extended onboarding friction in EU and US markets.
For Market Incumbents: Shield premium positioning by deepening backward integration into thermal printhead supply and accelerating FDA 510(k) clearance investment for laser-emitting systems. Counter freelance artist fragmentation through subscription-based software-integrated workflow bundles that lock in recurring revenue and elevate switching costs. For New Entrants and Emerging Players: FDA laser device classification fast-tracks offer first-mover positioning in precision dermatological marking segments underserved by thermal transfer incumbents. Target battery-powered portable units for Australia's mobile artist community and South Korea's independent tattoo scene. Pursue direct-to-consumer channel entry with tablet-native design application integration. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive Hebei Province manufacturing and established REACH-compliant coating supply relationships. Long-term viability hinges on regulatory certification breadth across FDA, EU MDR, and MFDS frameworks. Watch freelance artist procurement fragmentation rates as inflection indicator for hardware ownership model shift.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA-registered alternative chemistries from Swiss specialists secure European market access against bisphenol-A restrictions. |
| FDA 510(k) Laser Device Clearance | Precision dermatological marking systems gain regulated pathway into Los Angeles studio clusters and cosmetic clinic segments. |
| Software-Integrated Workflow Launch | Tablet-based design applications with wireless printer protocols enable subscription revenue capture from high-volume operators. |
| Battery-Powered Portable Unit Development | Compact thermal hardware addresses unmet demand from South Korean and Australian freelance artists operating pop-up locations. |
| Hebei Manufacturing Footprint Expansion | Vertically controlled production clusters strengthen budget-tier export channel dominance against Japanese electronics conglomerates. |
Research Methodology
The analysis maps thermal transfer, inkjet, laser, and rotary printer sub-sectors, each validated through equipment procurement managers at studio chains, freelance artists, tattoo training academy directors, and cosmetic clinic operators. Primary interview findings triangulate against secondary sources including FDA 510(k) filings, ECHA REACH registration databases, MFDS medical device classifications, and customs trade records. Bottom-up unit shipment estimates reconcile with top-down market value assessments.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology type, end-user concentration, material compliance tier, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectory aggregation incorporating equipment replacement cycle compression, certification timeline extensions, and wireless protocol adoption curves.
Decision-makers should treat outputs as directional under stable REACH enforcement and FDA classification continuity assumptions; material deviation would warrant model refresh. Revision becomes warranted when bisphenol-A coating substitution costs or laser device clearance timelines cross thresholds that alter competitive positioning dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Tattoo Machine Market