
 Out Store Signage Market | 2026-2036
Out Store Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Out Store Signage Market Analytics
South Korea's display panel ecosystem is rewriting how out store signage supply chains organize around OLED and microLED sources. Samsung Electronics leverages captive semiconductor capacity to control digital sign module costs. LG Electronics anchors premium outdoor display lines through its commercial solutions division. Daktronics sustains North American sports and transit venue dominance with engineered LED cabinet systems.
Out store signage encompasses exterior visual communication structures deployed beyond building envelopes to attract pedestrian and vehicular traffic, typically engineered with weather-resistant substrates, UV-stabilized inks, and illumination systems rated for IP65 or higher environmental protection. These installations serve retail, food service, and entertainment operators seeking to convert passageway visibility into foot traffic and transaction volume. Vinyl substrates still occupy the largest material share due to cost scalability across temporary promotional campaigns, though acrylic and metal assemblies command margin pools in permanent branded installations. Digital signs represent the fastest-expanding sign type category as cloud content management and daylight-readable panels displace static printed formats in high-traffic zones.
The US Department of Energy enforces minimum efficacy requirements for illuminated exterior fixtures, while local jurisdictions apply International Sign Association code compliance for structural wind load and electrical safety. The EU F-Gas Regulation constrains refrigerant-based thermal management in outdoor digital enclosures, pushing manufacturers toward passive cooling architectures. Stakeholders must monitor how municipal digitization permits and energy benchmarking ordinances in key metropolitan areas reshape total cost of ownership calculations for networked signage deployments.
Market Dynamics
LED efficacy mandates from the US Department of Energy and local energy benchmarking ordinances are compressing procurement cycles for illuminated exterior fixtures, forcing operators to recalculate total cost of ownership around networked digital deployments.
Growth Catalysts
- Quick-service restaurant expansion:Chains are accelerating exterior menu board deployments to capture drive-through and pedestrian traffic in urban commercial corridors.
- Cloud content management:Remote update capabilities for digital signage are reducing operational friction for multi-location retail operators managing seasonal campaigns.
- South Korea display ecosystem:Captive OLED and microLED panel capacity is compressing module costs for premium outdoor digital installations.
Market Restraints
- Aluminum substrate volatility:Metal framing and enclosure input costs fluctuate with energy-intensive smelting economics, pressuring permanent branded installation margins.
- EU F-Gas Regulation constraints:Refrigerant-based thermal management in outdoor digital enclosures faces phase-down schedules, limiting active cooling options for high-brightness panels.
- Vinyl substitution pressure:Temporary promotional campaigns still favor cost-scalable printed substrates over digital alternatives in low-traffic zones.
Strategic Opportunities
- Passive cooling architectures:Thermal engineering innovations bypass F-Gas restrictions while extending LED module lifespan in extreme climate zones.
- Transit venue digitization:Sports arenas and transportation hubs present underpenetrated demand for engineered LED cabinet systems with structural wind load certification.
- IRA energy efficiency incentives:US commercial building operators can offset illuminated fixture upgrades through federal tax credits aligned with Department of Energy efficacy thresholds.
Industry Challenges
- IP65+ certification timelines:Environmental protection rating compliance for outdoor digital enclosures extends product development cycles and testing expenditures.
- Legacy static sign integration:Hybrid deployments combining printed substrates with digital elements require coordination across disparate supply chains and installation trades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out Store Signage Market |
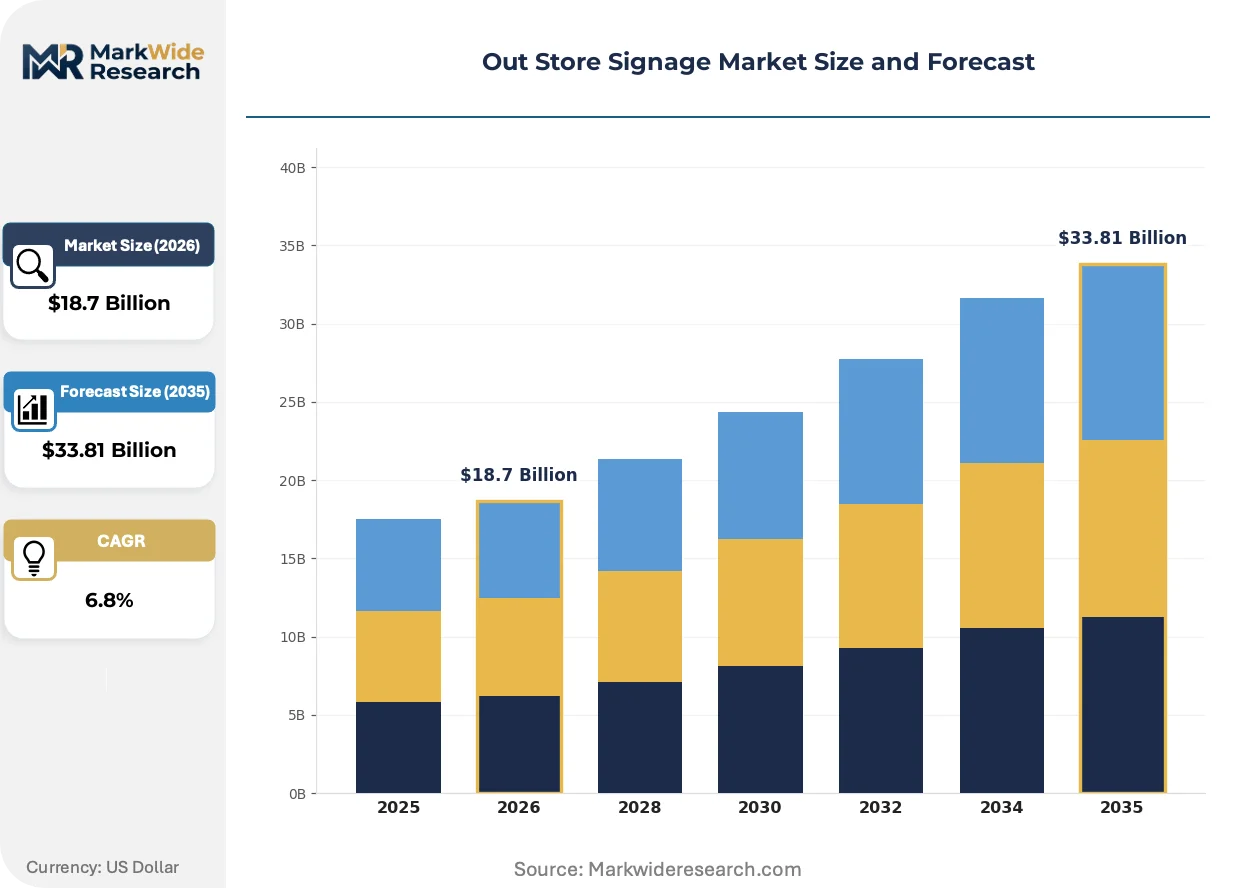
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sign Type: Billboards, A-Frame, Banners, Digital Signs Material: Vinyl, Acrylic, Metal, Wood Installation Method: Permanent, Temporary, Mounted, Freestanding End User: Retail Stores, Restaurants, Service Providers, Event Venues |
| Companies Covered | Samsung Electronics, LG Electronics, Daktronics, NEC Display Solutions, Panasonic Corporation, Sharp NEC Display Solutions, Planar Systems, Watchfire Signs, BrightSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out Store Signage Market Evolving Landscape
Content management platforms and thermal engineering are converging to redefine how exterior visual communication systems are specified, deployed, and monetized across retail and food service verticals.
MicroLED direct-view displays are migrating from indoor premium applications to high-brightness outdoor installations through advances in flip-chip bonding and ceramic substrate thermal conductivity. Stadium and transit operators in Germany and South Korea are piloting daylight-readable configurations that eliminate backlighting subsystems. This migration is compressing the performance gap between conventional LED modules and next-generation panel architectures.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are constraining material selection for outdoor digital enclosures across European procurement channels. Manufacturers are reformulating potting compounds and gasket materials to eliminate SVHC candidates while redesigning thermal management around passive heat sinks. German engineering consultancies are embedding these constraints into municipal digitization permit specifications.
Quick-service chains are consolidating vendor relationships around full-service signage contracts that bundle hardware, content management software, and preventive maintenance into single-source agreements. This procurement consolidation displaces the traditional model of separate creative agencies, sign fabricators, and electrical contractors. The shift is most visible in United States urban commercial corridors where franchise operators seek operational simplicity across dispersed locations.
Out Store Signage Market Segmentation
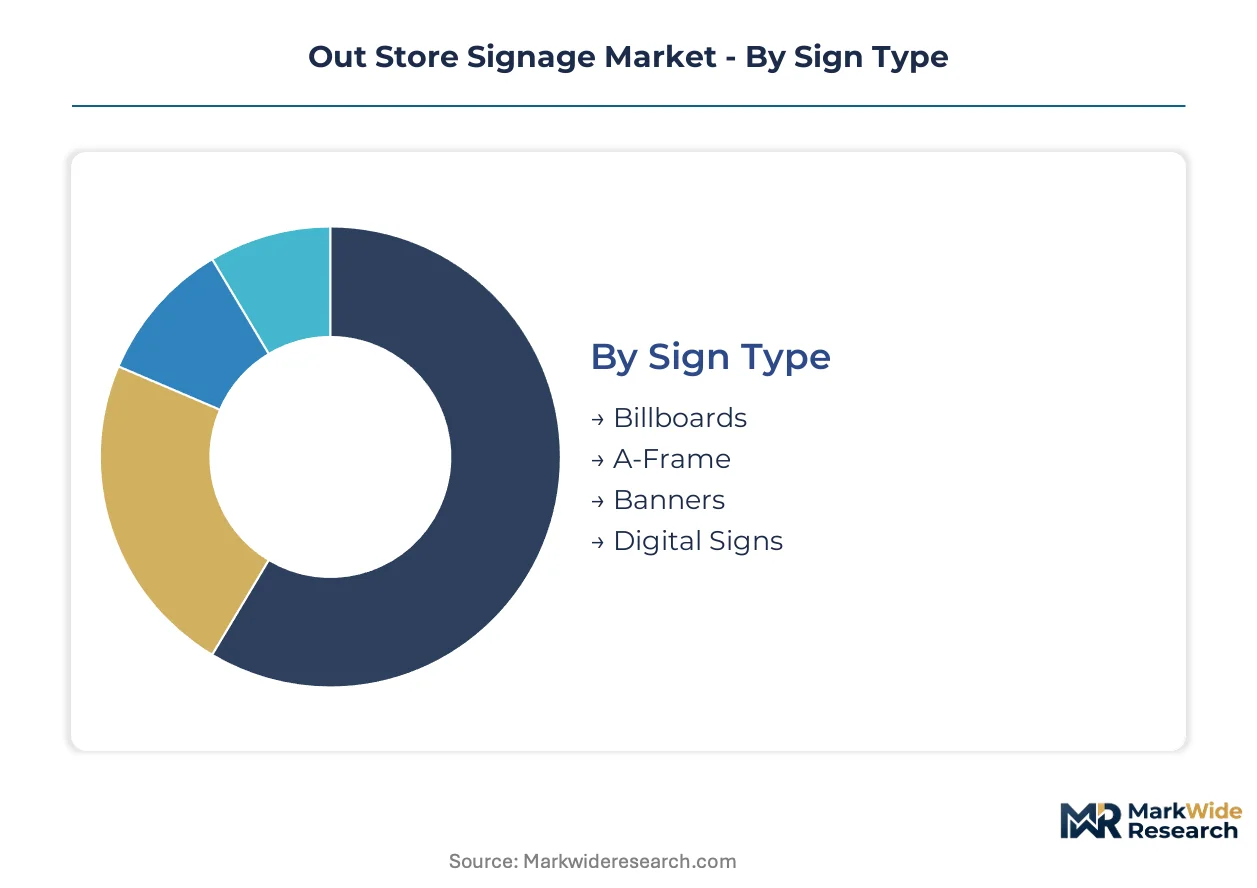
Signage procurement cycles vary dramatically by substrate durability and technology refresh rates. Operators must match segment selection to campaign duration, regulatory exposure, and total cost of ownership across urban commercial corridors.
Sign Type:
Replacement velocity separates static formats from digital infrastructure, with temporary printed deployments turning over in weeks versus networked systems persisting for years.
- Billboards:Large-format highway and arterial displays engineered for 500-foot viewing distances with weather-resistant vinyl or flex-face substrates. Demand clusters along interstate corridors in the United States and Germany where municipal height ordinances permit elevated structures. Operators face extended permitting timelines and structural wind load certification requirements.
- Digital Signs:Networked LED or LCD panels with cloud content management, daylight-readable brightness exceeding 5,000 nits, and IP65 environmental sealing. Quick-service restaurant chains in South Korea and the United States are accelerating drive-through menu board deployments to enable real-time pricing and promotional agility.
- A-Frame:Double-sided sidewalk displays with hinged or snap-frame substrate retention for rapid graphic swaps. Retail operators favor these for flash sales and directional messaging in high-foot-traffic pedestrian zones.
- Banners:Flexible vinyl or mesh substrates suspended from building facades, light poles, or temporary framing systems. Event venues and seasonal retailers deploy these for cost-scalable short-term visibility without structural permanence.
Billboards anchor the volume base while digital signs gain share at the steepest rate.
Material:
Cost tier and longevity trade-offs drive procurement decisions, with premium substrates commanding margin pools in branded permanent installations.
- Vinyl:PVC-based flexible substrates dominate temporary promotional campaigns through cost scalability and UV-stabilized ink compatibility. Quick-service chains and event venues in the United States specify 13-ounce scrim vinyl for exterior banners and billboards subject to seasonal replacement cycles.
- Metal:Aluminum and steel framing systems with powder-coated or anodized finishes for structural enclosures and permanent branded monuments. Fabricators face margin pressure from energy-intensive smelting economics and aluminum substrate price volatility.
- Acrylic:Cast or extruded thermoplastic sheets with optical clarity for illuminated channel letters and face-lit cabinet systems. Premium retail and hospitality operators specify these for dimensional branding in protected urban environments.
- Wood:Treated lumber or composite substrates for rustic aesthetic applications in specialty retail and entertainment districts. Limited deployment due to moisture degradation and fire code restrictions in dense commercial zones.
Vinyl captures the highest shipment volumes while metal assemblies extract premium pricing in permanent installation contracts.
Installation Method:
Structural commitment levels separate capital-intensive foundation work from portable deployments requiring no municipal permits.
- Permanent:Foundation-mounted or structurally attached installations with engineered anchoring systems rated for seismic and wind load conditions. Sports arenas and transit venues in Germany specify these for engineered LED cabinet systems with decade-long service life expectations.
- Mounted:Building-integrated or pole-attached configurations requiring facade penetration or bracket welding. Municipal sign codes in the United States regulate projection distances and clearance heights above sidewalks.
- Temporary:Ground-supported or weighted-base systems deployable without excavation or structural modification. Event venues and seasonal retailers favor these for compliance agility and rapid site turnover.
- Freestanding:Self-supporting structures including pylons, monuments, and A-frames with integrated ballast or foundation systems. Quick-service restaurants deploy these for drive-through menu boards and directional signage in parking lot environments.
Permanent installations lock in long-term revenue for fabricators while temporary methods expand addressable market reach to short-cycle operators.
End User:
Customer type determines specification complexity, with food service operators prioritizing rapid content refresh against retail emphasis on brand permanence.
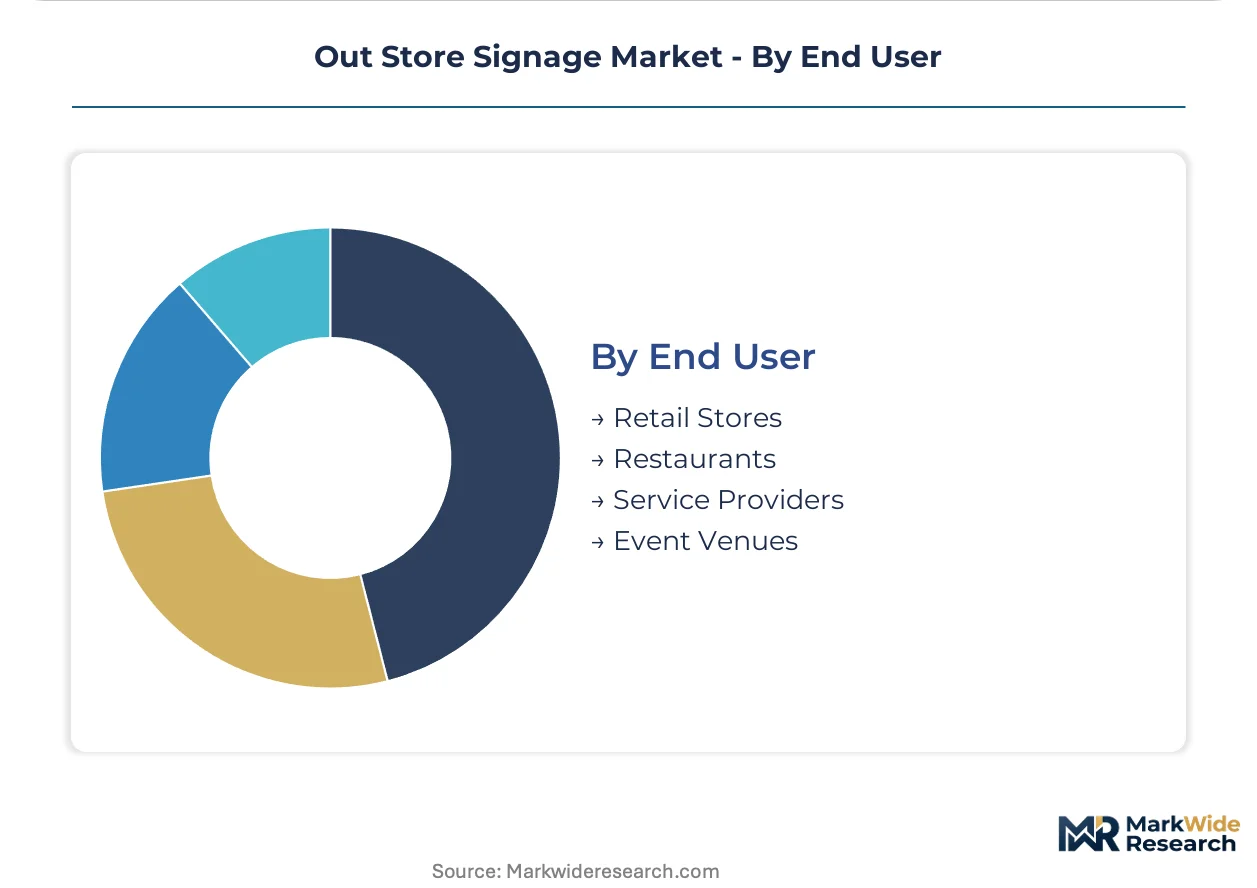
- Restaurants:Quick-service chains and fast-casual operators deploying exterior menu boards, drive-through displays, and promotional A-frames. Cloud content management and daylight-readable panels are displacing static printed formats in high-traffic urban corridors across the United States and South Korea.
- Retail Stores:Department stores, specialty merchants, and big-box operators specifying permanent branded monuments, window graphics, and sidewalk directional systems. Acrylic and metal assemblies command preference for dimensional channel letter installations.
- Event Venues:Stadiums, arenas, and exhibition centers requiring engineered LED cabinet systems with structural certification and passive cooling architectures. German transit operators are piloting microLED configurations for daylight-readable concourse displays.
- Service Providers:Banks, healthcare clinics, and professional services deploying wayfinding and identification signage with extended replacement cycles. These operators prioritize durability and code compliance over promotional agility.
Restaurants generate the most dynamic replacement demand while retail stores provide the stable installed base for permanent substrate suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel manufacturing concentrates in South Korea and China, while North American and European markets drive specification complexity through energy codes and municipal digitization permits.
United States
Quick-service restaurant chains deploy exterior menu boards across urban commercial corridors to capture drive-through traffic. The US Department of Energy enforces LED efficacy mandates for illuminated exterior fixtures. Dallas-Fort Worth and Atlanta anchor demand clusters where franchise operators consolidate vendor relationships around full-service signage contracts.
Germany
Transit venues and sports arenas pilot microLED configurations for daylight-readable concourse displays. The EU F-Gas Regulation constrains refrigerant-based thermal management in outdoor digital enclosures. Engineering consultancies in Munich and Hamburg embed passive cooling requirements into municipal digitization permit specifications.
South Korea
Samsung Electronics and LG Electronics leverage captive OLED and microLED capacity to compress module costs for premium outdoor installations. Local energy benchmarking ordinances reshape procurement criteria for networked deployments. Seoul Capital Area and Busan-Ulsan anchor the display panel ecosystem supplying global markets.
Japan
Commercial building operators specify engineered LED cabinet systems with extended service life expectations. METI efficiency standards influence procurement cycles for illuminated exterior fixtures. Tokyo and Osaka metropolitan areas concentrate demand for hybrid deployments combining printed substrates with digital elements.
United Kingdom
Retail operators in London and Southeast England prioritize permanent branded monuments with acrylic and metal assemblies. REACH substance restrictions constrain material selection for outdoor digital enclosures. Birmingham and Manchester emerge as secondary demand clusters for temporary promotional campaigns using vinyl substrates.
Out Store Signage Market Competitive Landscape
Display panel conglomerates and engineered systems specialists split the market into technology-driven and application-engineered segments. Samsung Electronics and LG Electronics anchor the former through captive semiconductor capacity, while Daktronics occupies the latter with structural certification expertise. Three archetypes dominate: vertically integrated electronics conglomerates, engineered LED cabinet specialists, and cloud content management platforms. Competitive moves center on thermal engineering partnerships and municipal permit specification capture.
Among South Korea-based conglomerates, Samsung Electronics and LG Electronics represent the technology-integrated archetype through display panel supply control. Daktronics anchors the engineered systems tier with North American sports and transit venue dominance. These three exemplify how supply chain positioning and application engineering credentials determine procurement access across quick-service restaurant and transit verticals.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Daktronics |
| NEC Display Solutions |
| Panasonic Corporation |
| Sharp NEC Display Solutions |
| Planar Systems |
| Watchfire Signs |
| BrightSign |
| Others |
Value Network & Pricing Analysis
Seoul Capital Area display panel capacity anchors global module pricing, with Samsung Electronics and LG Electronics leveraging captive semiconductor fabrication to compress costs for downstream signage integrators. This concentration grants Korean conglomerates pricing power over premium outdoor digital installations while forcing North American and European fabricators to absorb aluminum substrate volatility and EU thermal management compliance costs.
Pricing Analysis
The US Department of Energy LED efficacy mandates dictate the pricing tier structure across illuminated exterior fixtures. Three-tier pricing structure across premium, standard, and economy levels separates IP65-certified engineered cabinets from basic commercial-grade enclosures and temporary vinyl deployments. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from aluminum smelting energy costs pressuring permanent installation margins. Quick-service restaurant chains exhibit highest price sensitivity due to dispersed location footprints, while transit venue operators prioritize lifecycle durability over upfront capital expenditure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for metal framing and electronic components. Manufacturing concentrates in South Korea, China, and Germany. Raw material flows draw from aluminum smelters, OLED panel foundries, and UV-stabilized vinyl resin producers. Single-source vulnerability persists for microLED flip-chip bonding equipment. Distribution runs through full-service signage contractors consolidating hardware, software, and maintenance into single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around municipal digitization permits and IP65 certification timelines creates sustainable competitive barriers for established players.
For Market Incumbents: Build certification moats by accelerating IP65+ testing capacity and capturing municipal permit specification authorship in Dallas-Fort Worth and Atlanta corridors. Aluminum substrate volatility threatens margin stability; backward integration into thermal engineering partnerships with passive cooling specialists defends position. Channel control through full-service contract consolidation locks out fragmented creative agency competition. For New Entrants and Emerging Players: German transit venue microLED pilots represent the most penetrable white-space target, with engineering consultancies in Munich embedding passive cooling requirements into municipal specifications. Event venue temporary deployments in Birmingham and Manchester offer lower certification barriers for vinyl substrate specialists. Go-to-market execution should anchor on hybrid deployment expertise bridging printed substrates with digital element integration. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because cloud content management subscriptions and preventive maintenance contracts generate predictable cash flows across quick-service restaurant footprints. Acquisition targets should screen for engineered LED cabinet specialists with structural wind load certification and transit venue referenceability. Watch for IRA energy efficiency incentive uptake velocity as inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Engineering Partnership | Passive cooling architectures bypass EU F-Gas restrictions while extending LED module lifespan in extreme climates. |
| Municipal Permit Specification Capture | German engineering consultancies embed compliance requirements that lock preferred vendors into decade-long transit venue deployments. |
| Full-Service Contract Consolidation | Single-source agreements bundling hardware, software, and maintenance displace fragmented creative agency and electrical contractor models. |
| Cloud Content Management Platform Integration | Remote update capabilities reduce operational friction for multi-location quick-service operators managing seasonal campaigns. |
| IRA Energy Efficiency Incentive Monetization | Federal tax credits aligned with Department of Energy efficacy thresholds offset illuminated fixture upgrade costs for commercial building operators. |
Research Methodology
A spread of perspectives from signage fabricators, municipal permitting officers, quick-service restaurant franchise operators, and transit venue procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, customs trade data, Department of Energy efficacy standards, and International Sign Association code documentation. Bottom-up demand modeling across substrate types and installation methods triangulated against top-down market sizing.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include sign type, material substrate, installation method, and end-user vertical. CAGRs were derived from replacement velocity differentials between static and digital formats, overlaying regulatory compliance timelines and energy benchmarking ordinance adoption curves. Forecast inputs incorporated LED efficacy mandate phase-in schedules and aluminum price volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated display panel conglomerates or engineered systems specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Department Stores Market
Retailing
Out-Door Signage Market
Retailing
Philippines Retail Industry Market
Retailing
Thailand Retail Market
Retailing
United States Hardware Stores Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
Retail Display Racks Market
Retailing
In Store Signage Market
Retailing
China Retail Market
Retailing
Consumer Shopping Cart Market
Retailing
Consumer Products and Retail Market
Retailing
Gift Baskets Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Home Shopping Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Displays Market