
 Pet Hotels Market | 2026-2036
Pet Hotels Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Hotels Market Outlook
North American boutique pet lodging capacity is decoupling from traditional veterinary boarding infrastructure. Marriott International leverages its Bonvoy ecosystem to anchor premium pet-inclusive stays across resort portfolios. IHG through Kimpton sustains boutique differentiation with its longstanding pets-welcome policy and dedicated amenity programs. Best Western competes on mid-market accessibility with standardized pet protocols across franchise locations.
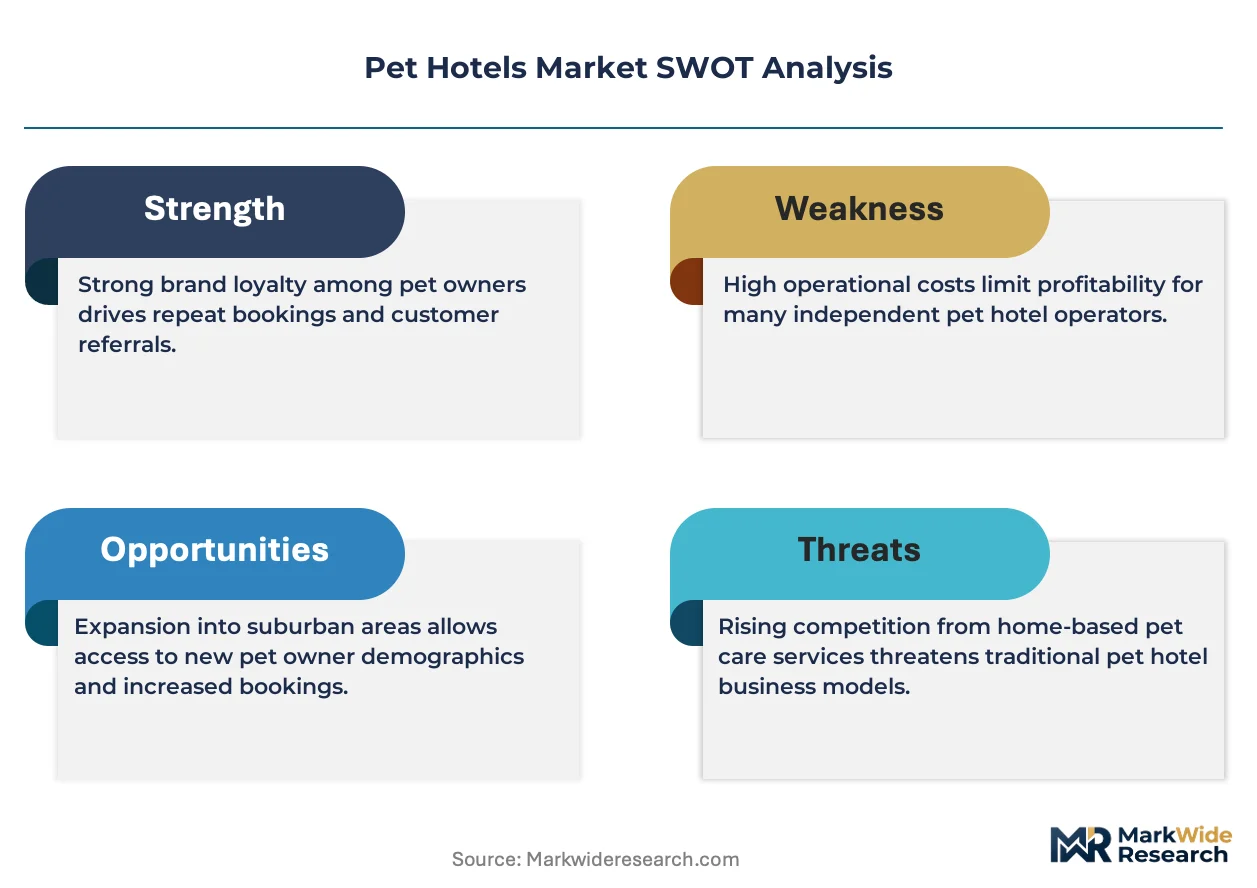
Pet hotels are commercial hospitality facilities engineered to provide supervised overnight accommodation, feeding, exercise, and medical monitoring for companion animals, typically featuring climate-controlled kennels, outdoor relief yards, and staff trained in animal behavior and emergency response. Their primary commercial purpose is to substitute domestic pet care during owner travel, business absence, or relocation transitions. Luxury hotels and combined indoor-outdoor facilities command the dominant margin pools as owners trade up from basic kennel services. Budget hotels and indoor-only facilities face structural pressure from gig-economy pet sitting platforms that undercut price points while offering home-environment alternatives.
USDA Animal Welfare Act standards, state-level Department of Agriculture kennel licensing regimes, and municipal zoning ordinances collectively govern facility construction, staffing ratios, and operational permits across the United States. These frameworks elevate compliance costs for new entrants while creating defensible positions for incumbents with established inspection records and bonded relationships with local regulators. Stakeholders must monitor evolving service animal versus pet distinctions in ADA interpretation and emerging municipal restrictions on breed-specific boarding capacity.
Market Dynamics
Urban millennial pet owners now treat companion animal boarding as hospitality rather than veterinary overflow, forcing facility operators to replicate hotel-grade service infrastructure and amenity programming previously absent from kennel economics.
Growth Catalysts
- USDA Animal Welfare Act standards:Federal inspection regimes elevate facility construction and staffing baselines, filtering out subscale operators and consolidating demand toward compliant incumbents with bonded regulator relationships.
- Remote-work pattern reversals:Return-to-office mandates in California and Texas metropolitan corridors compress owner absence windows and concentrate boarding demand into premium short-stay formats.
- Climate-controlled kennel specifications:HVAC and air-quality engineering investments unlock year-round operational capacity in extreme-weather states, expanding addressable geography for indoor-outdoor facility formats.
Market Restraints
- Municipal zoning ordinances:Local land-use restrictions on noise, odor, and traffic limit greenfield facility placement in dense metropolitan markets where demand concentrates most intensely.
- Veterinary technician labor scarcity:Licensed animal health professionals command wage premiums that compress margin structures for mid-market operators unable to pass through full cost recovery.
- Gig-economy pet sitting platforms:Rover and Wag undercut price points for basic overnight care by substituting home-environment alternatives that bypass facility capex entirely.
Strategic Opportunities
- Underserved secondary metros:Austin, Nashville, and Raleigh-Durham exhibit pet ownership rates approaching coastal levels with one-third the boutique lodging capacity per capita.
- Extended-stay relocation boarding:Corporate relocation pipelines generate 14-30 day median stays with lower per-diem sensitivity than vacation-driven demand.
- State-level kennel licensing reciprocity:Emerging interstate recognition frameworks reduce multi-state operator compliance duplication and accelerate geographic expansion timelines.
Industry Challenges
- Certified animal behavior specialist recruitment:Facility differentiation depends on staff credentials that require 2-4 year training pipelines with limited program throughput.
- Legacy property retrofit capex:Converting veterinary boarding infrastructure to hospitality-grade lodging demands $400-$800 per-square-foot renovation spend with 5-7 year payback horizons.
- ADA service animal versus pet distinction monitoring:Evolving federal interpretation creates operational ambiguity around accommodation obligations and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Hotels Market |
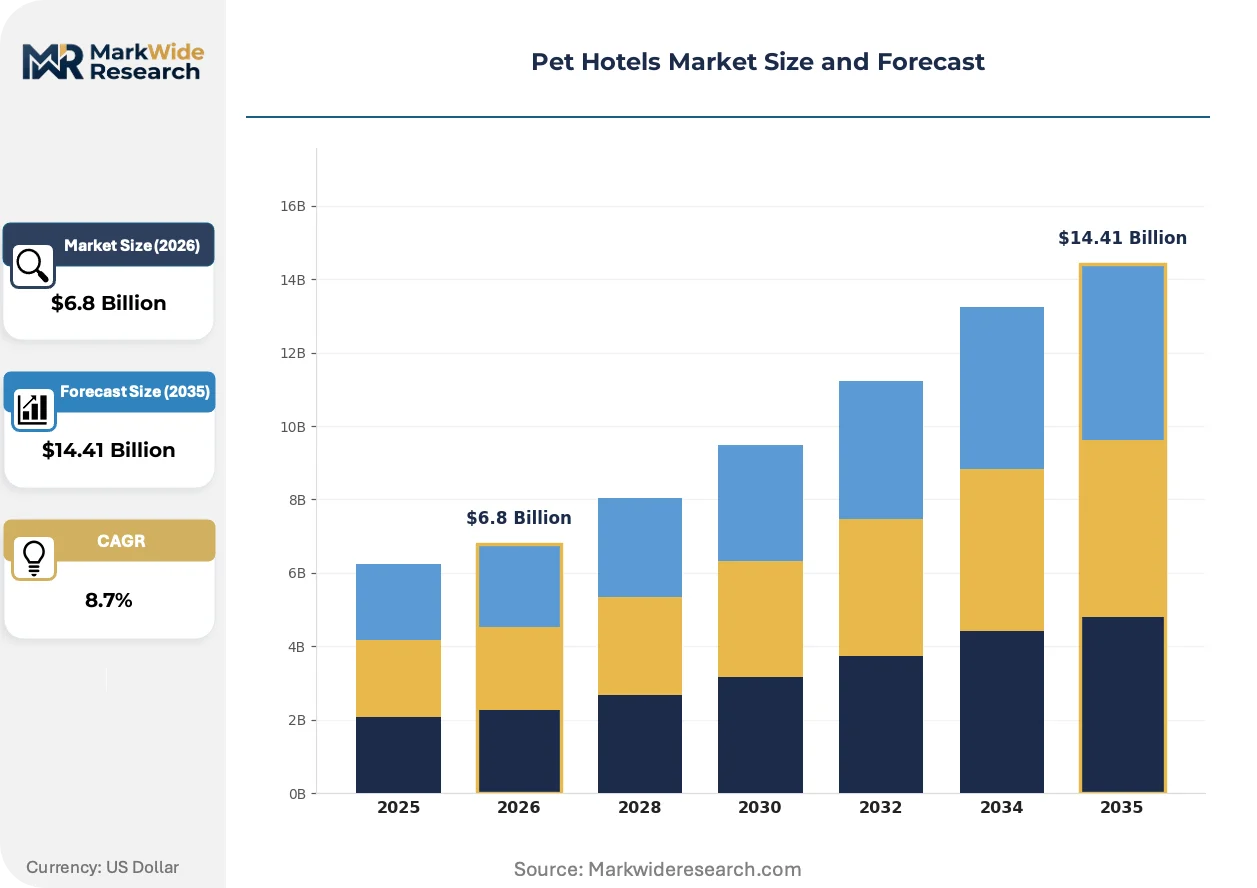
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Hotels, Budget Hotels, Pet Sitting Services, Kennels Facility Type: Indoor Facilities, Outdoor Facilities, Combined Facilities, Specialized Care Units Pet Type: Dogs, Cats, Birds, Exotic Pets Customer Type: Individual Pet Owners, Corporates, Pet Breeders, Welfare Organizations |
| Companies Covered | Loews Hotels, Best Western, IHG (Kimpton), Staypineapple, Wyndham, Marriott International, Hyatt, La Quinta, Hilton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Hotels Market Strategic Shifts
Facility operators are engineering companion animal lodging as experiential hospitality rather than custodial care, importing revenue-management and guest-experience disciplines from human hotel operations.
Smart kennel management platforms integrating IoT climate sensors, automated feeding systems, and owner-facing video streaming is electrifying operational visibility and compressing labor intensity per occupied unit. Premium boutique operators in California and Texas metropolitan corridors are deploying these systems at 60-90 day rollout cycles. The technology is enabling 24-hour staffing models with fractional on-site presence, reshaping unit economics for urban infill locations.
State-level Department of Agriculture kennel licensing regimes are tightening facility construction codes and mandating veterinary oversight ratios that elevate compliance costs for new entrants. These frameworks create defensible positions for incumbents with established inspection records and bonded relationships with local regulators. Multi-state operators are responding by centralizing compliance architecture and deploying dedicated regulatory affairs functions previously absent from regional chains.
Owners now evaluate boarding options through hospitality lenses rather than veterinary referrals, compressing traditional channel dominance and elevating direct-to-consumer discovery through Instagram and TikTok visual documentation of facility amenities. Boutique operators with dedicated content production capabilities are displacing legacy kennels dependent on veterinarian word-of-mouth. This behavioral shift is most visible in California coastal markets where owner review volume and visual amenity documentation correlate directly with pricing power.
Pet Hotels Market Segmentation
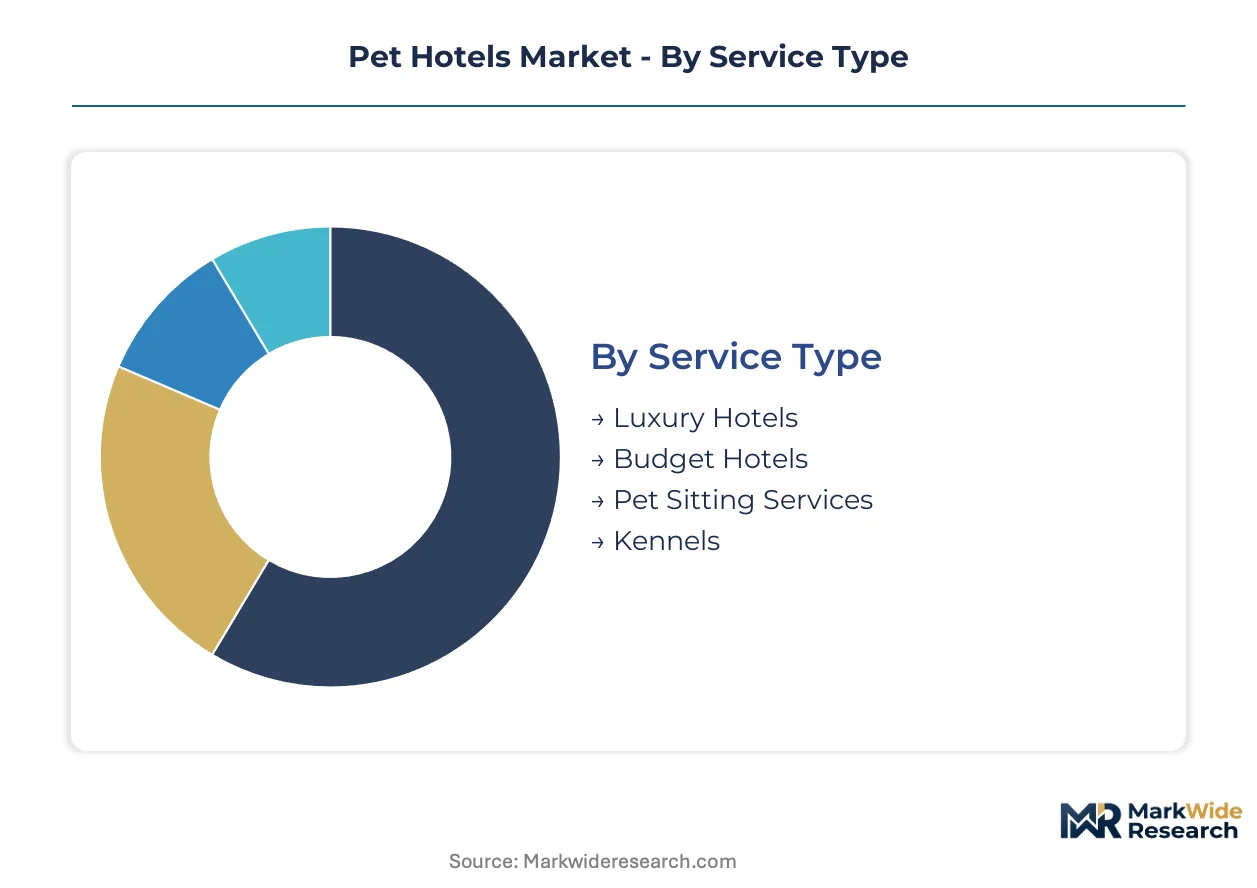
Pet hotels operators calibrate service architecture, facility specifications, and staffing models against distinct customer willingness-to-pay thresholds and animal care requirements. Segmentation discipline separates margin-accretive premium hospitality from commodity boarding vulnerable to gig-economy substitution.
Service Type:
USDA Animal Welfare Act inspection regimes apply uniformly across service tiers, though luxury operators absorb additional municipal hospitality licensing and bonded insurance requirements that budget competitors bypass.
- Luxury Hotels:Climate-controlled suites with video streaming, personalized exercise programming, and veterinary technician staffing. California and Texas metropolitan corridors concentrate demand where remote-work reversals compress owner absence into premium short-stay formats.
- Budget Hotels:Basic kennel infrastructure with standardized feeding and relief schedules. Gig-economy pet sitting platforms undercut price points by substituting home-environment alternatives that bypass facility capex entirely.
- Pet Sitting Services:In-home care models leveraging gig-economy labor pools with minimal regulatory overhead.
- Kennels:Traditional veterinary-adjacent boarding with functional rather than experiential service design.
Luxury hotels sit at the top of the volume ranking, with pet sitting services climbing the fastest.
Facility Type:
Capital intensity and operating cost structures diverge sharply across physical formats, with climate engineering requirements determining geographic addressability in extreme-weather states.
- Indoor Facilities:HVAC-dependent operations with year-round climate control. Texas and Arizona markets unlock capacity through air-quality engineering investments that expand operational geography.
- Outdoor Facilities:Seasonal operations constrained by temperature extremes and municipal noise ordinances. Lower capex requirements attract entrants in temperate coastal California markets.
- Combined Facilities:Hybrid indoor-outdoor programming with flexible space utilization. Austin and Nashville secondary metros exhibit ownership rates approaching coastal levels with undersupplied boutique capacity.
- Specialized Care Units:Medical monitoring infrastructure for post-surgical or geriatric animals requiring veterinary oversight ratios mandated by state-level Department of Agriculture licensing.
Combined facilities command the dominant margin pools, while specialized care units gain share fastest among corporate relocation pipelines generating extended-stay demand.
Pet Type:
Staff credential requirements and liability exposure vary substantially by animal category, with exotic species demanding specialized handling certifications that constrain supply expansion.
- Dogs:Volume anchor driving standardized kennel economics and amenity programming across all service tiers. California metropolitan corridors exhibit highest per-capita boarding frequency.
- Cats:Separate feline-only zones with reduced stress protocols. Boutique operators deploy dedicated content production capabilities targeting owner discovery through Instagram and TikTok visual documentation.
- Birds:Avian-specific climate and noise management with limited specialist capacity.
- Exotic Pets:Reptile and small mammal protocols requiring certified animal behavior specialist credentials with 2-4 year training pipelines.
Dogs generate the dominant revenue base, with cats expanding most quickly as feline-only boutique concepts proliferate.
Customer Type:
Contract structures and pricing sensitivity diverge between discretionary vacation-driven demand and corporate procurement with volume commitments.
- Individual Pet Owners:Discretionary spenders evaluating options through hospitality lenses rather than veterinary referrals. Direct-to-consumer discovery channels displace traditional veterinarian word-of-mouth.
- Corporates:Relocation service procurement generating 14-30 day median stays with lower per-diem sensitivity than vacation-driven demand.
- Pet Breeders:Seasonal volume concentrated around whelping cycles with specialized neonatal care requirements.
- Welfare Organizations:Municipal and nonprofit contracts with cost-recovery rather than margin-maximization objectives.
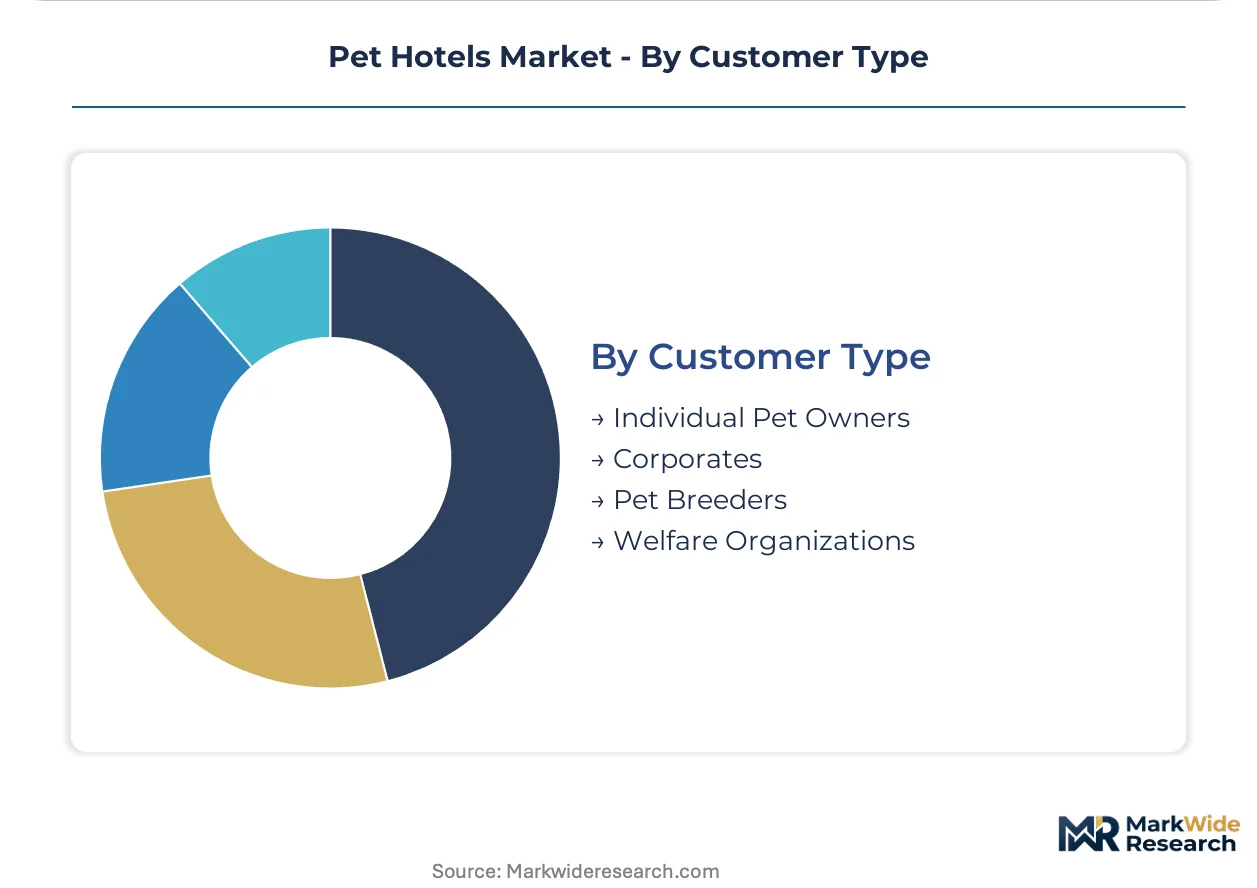
Individual pet owners anchor volume, with corporate accounts gaining share fastest as return-to-office mandates concentrate boarding demand into premium short-stay formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's boutique pet lodging capacity outpaces Texas by a factor of three, yet both states exhibit comparable pet ownership density. Metropolitan corridors in these states concentrate demand where remote-work reversals compress owner absence into premium short-stay formats.
United States
Urban millennial pet owners in California and Texas metropolitan corridors drive boarding demand as return-to-office mandates concentrate absence windows. USDA Animal Welfare Act standards and state-level kennel licensing regimes elevate facility construction baselines. Los Angeles and Dallas-Fort Worth anchor the dominant capacity clusters where climate-controlled indoor-outdoor formats command premium pricing.
United Kingdom
London and Southeast England exhibit hospitality-grade pet lodging growth as owners evaluate options through experiential lenses. The country's national veterinary regulator enforces kennel licensing under the Animal Welfare Act 2006 with local authority inspection regimes. Greater Manchester and Birmingham secondary metros show undersupplied boutique capacity relative to pet ownership rates.
Germany
Bavaria and North Rhine-Westphalia concentrate demand from affluent pet owners seeking veterinary-adjacent boarding with medical monitoring capabilities. German kennel regulations under the country's animal welfare framework mandate specific space and staffing ratios. Berlin and Hamburg urban cores face municipal zoning constraints that limit greenfield facility placement despite concentrated demand.
Japan
Kanto and Kansai metropolitan areas generate premium-tier demand as pet humanization trends accelerate among urban households. METI guidelines and prefectural animal welfare ordinances govern facility standards with emphasis on hygiene and disease prevention. Tokyo and Osaka exhibit the highest per-capita boutique lodging capacity in Asia-Pacific.
Australia
New South Wales and Victoria anchor domestic demand where pet ownership rates exceed OECD averages and travel-driven boarding peaks seasonally. State-level animal welfare legislation administered by departmental inspectors mandates kennel construction codes and veterinary oversight ratios. Sydney and Melbourne metropolitan corridors concentrate climate-controlled facility investment addressing extreme-weather operational challenges.
Pet Hotels Market Competitive Environment
United States hospitality conglomerates anchor the premium tier; European and Asia-Pacific specialists hold mid-market positioning through regional franchise networks. Market structure consolidates around hotel chains with established loyalty ecosystems and standardized pet protocols, while independent boutique operators fragment across metropolitan sub-markets. Three archetypes dominate: legacy hospitality brands with pet-inclusive portfolios, veterinary-adjacent boarding chains with medical monitoring capabilities, and technology-enabled platforms integrating gig-economy sitting services. Competitive moves concentrate on loyalty program integration and amenity standardization across franchise locations.
Within the premium hospitality tier, Marriott International and IHG through its Kimpton brand exemplify archetype leaders leveraging established guest-experience infrastructure. Best Western occupies a position in mid-market accessibility with standardized protocols across franchise networks. These three entities represent the dominant competitive anchors as facility operators replicate hotel-grade service disciplines previously absent from kennel economics.
| Leading Market Players |
|---|
| Loews Hotels |
| Best Western |
| IHG (Kimpton) |
| Staypineapple |
| Wyndham |
| Marriott International |
| Hyatt |
| La Quinta |
| Hilton |
| Others |
Value Chain & Pricing Dynamics
Return-to-office mandates in California and Texas metropolitan corridors compress owner absence windows and concentrate boarding demand into premium short-stay formats, forcing facility operators to absorb HVAC engineering investments and veterinary technician wage premiums that reshape unit economics across service tiers.
Pricing Analysis
Direct-to-consumer booking margins bypass traditional veterinary referral channels and enable operators to capture full rate realization through Instagram and TikTok discovery channels. Three-tier pricing structure across luxury suites, standard kennels, and economy indoor facilities separates climate-controlled indoor-outdoor programming from basic kennel infrastructure. Cost compression in budget tiers intensifies because gig-economy pet sitting platforms substitute home-environment alternatives without facility capex. Corporate relocation accounts exhibit lowest price sensitivity due to 14-30 day median stays with employer reimbursement structures.
Supply Chain Analysis
Climate-controlled kennel construction materials draw from China, Mexico, and domestic HVAC equipment manufacturers with regional fabrication capacity. Veterinary technician labor pools, IoT sensor hardware, and specialized animal behavior training programs constitute critical input dependencies. Single-source vulnerability concentrates in certified animal behavior specialist credentials with 2-4 year training pipelines. Distribution runs through direct franchise development for hospitality conglomerates and regional owner-operator networks for independent boutique concepts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart kennel management platform deployment compresses labor intensity per occupied unit and unlocks 24-hour staffing models with fractional on-site presence, expanding margin capture in urban infill locations.
For Market Incumbents: Acquire secondary metro boutique capacity in Austin, Nashville, and Raleigh-Durham where pet ownership rates approach coastal levels with undersupplied lodging capacity per capita. Consolidate regional chains with established USDA inspection records and bonded regulator relationships before state-level kennel licensing reciprocity frameworks accelerate multi-state expansion timelines for competitors. Defend against gig-economy substitution by embedding IoT-enabled owner visibility and personalized exercise programming that home-environment alternatives cannot replicate. For New Entrants and Emerging Players: Technology-first smart kennel platforms with automated feeding systems and video streaming integration offer white-space entry into corporate relocation boarding with 14-30 day median stays and lower per-diem sensitivity. Target extended-stay formats in Texas metropolitan corridors where return-to-office mandates concentrate demand and climate engineering investments expand operational geography. Deploy direct-to-consumer discovery through visual amenity documentation on Instagram and TikTok to displace legacy kennels dependent on veterinarian word-of-mouth. For Investors and Strategic Acquirers: Asymmetric upside sits with multi-state operators centralizing compliance architecture and dedicated regulatory affairs functions previously absent from regional chains. Long-term viability hinges on consolidation of boutique capacity in secondary metros and technology-enabled operational visibility that reshapes unit economics. Watch for state-level kennel licensing reciprocity framework emergence as inflection indicator accelerating geographic expansion timelines and compressing compliance duplication costs.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Kennel Platform Deployment | IoT climate sensors and automated feeding systems compress labor intensity per occupied unit in California and Texas corridors. |
| Secondary Metro Capacity Expansion | Austin, Nashville, and Raleigh-Durham exhibit pet ownership rates approaching coastal levels with one-third the boutique lodging capacity. |
| Corporate Relocation Contract Procurement | Employer reimbursement structures generate 14-30 day median stays with lower per-diem sensitivity than vacation-driven demand. |
| Regulatory Affairs Function Centralization | Multi-state operators reduce compliance duplication and accelerate expansion timelines through dedicated USDA and state-level kennel licensing expertise. |
| Direct-to-Consumer Discovery Investment | Instagram and TikTok visual amenity documentation displaces veterinarian word-of-mouth in owner evaluation behavior. |
Study Parameters
Multiple input streams — facility operator interviews, veterinary technician workforce surveys, and municipal zoning database analysis — were reconciled with secondary validation from USDA Animal Welfare Act inspection records, state Department of Agriculture kennel licensing filings, and hospitality franchise disclosure documents. Primary discussions with boutique pet hotel operators, corporate relocation service procurement managers, and smart kennel technology vendors combined with bottom-up and top-down triangulation across the analysis window.
Data-stream reconciliation applied service tier, facility type, pet category, and customer type segmentation dimensions across the modeling period. CAGRs were derived from facility capacity expansion trajectories, pet ownership density correlations, and premium service tier adoption curves. Veterinary technician labor scarcity indices and climate-controlled kennel construction cost trends informed industry-specific forecast inputs.
The model holds under sustained return-to-office mandate enforcement and stable USDA inspection regime intensity; deviation in gig-economy platform subsidy levels or municipal zoning liberalization would shift demand concentration patterns. Forecasts reflect assumptions about pet humanization trend persistence and hospitality-grade service expectation elevation. A small set of named triggers — interstate kennel licensing reciprocity adoption, certified animal behavior specialist program expansion, and ADA service animal interpretation evolution — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Food Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
South Korea Organic and Natural Pet Food Market