
 Japan Heated Tobacco Products Market | 2026-2036
Japan Heated Tobacco Products Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Heated Tobacco Products Market Intelligence
A shift from single-source component procurement toward multi-source supplier panels is recalibrating manufacturing economics across the Japan heated tobacco supply base. Philip Morris Japan Inc. leverages captive production of blade heating elements to protect proprietary device architectures. Japan Tobacco Inc. sustains domestic leaf-processing infrastructure that anchors its stick-format supply chain. KT&G Corporation competes through aggressive flavor R&D pipelines targeting menthol-variant preferences.
Heated tobacco products are electronic or battery-powered systems that warm processed tobacco leaf to temperatures below combustion—typically 250-350°C—generating an inhalable aerosol containing nicotine and tobacco flavorants without ash or smoke. The primary commercial purpose is to deliver a cigarette-like experience with reduced toxicant profiles compared to conventional combustion. Devices and heat-not-burn units command the dominant revenue share given recurring hardware replacement cycles and technology upgrade cadences. Tobacco sticks and accessories generate the fastest-expanding margin pools through subscription-style repeat purchases tied to proprietary format lock-in. Flavor-type segmentation shows menthol variants outpacing straight tobacco profiles among switching demographics.
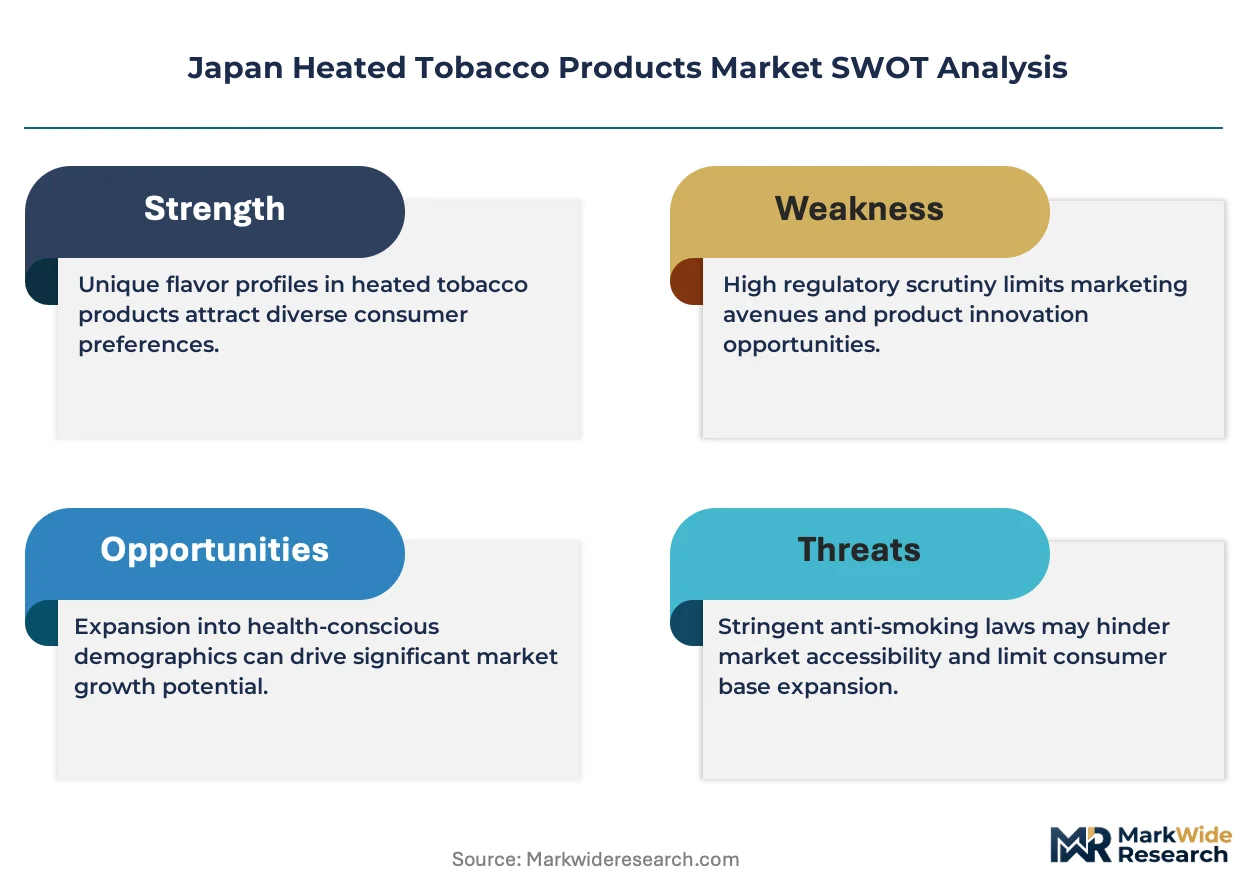
PMDA oversight of modified-risk tobacco product claims, METI electrical appliance safety certifications, and JIS standards for battery systems collectively govern market access and advertising boundaries. These frameworks restrict comparative health messaging while mandating rigorous thermal stability testing that elevates R&D barriers for new entrants. Stakeholders must monitor pending amendments to Japan's Health Promotion Act that could reshape indoor-use permissions and tax parity between heated and combustible formats.
Market Dynamics
METI's revised electrical appliance safety standards for heat-not-burn devices are compressing product development timelines while elevating thermal stability testing costs across the supply base.
Growth Catalysts
- Regulatory clarity on modified-risk positioning:PMDA oversight frameworks provide defined pathways for reduced-exposure claims, enabling investment in clinical substantiation programs.
- Adult smoker switching momentum:The 30-50 age cohort in Greater Tokyo and Osaka-Kobe corridors is migrating from combustible formats at measurable velocity.
- Convenience store channel density:Japan's 55,000-plus konbini outlets provide unmatched last-mile access for stick-format replenishment and device trials.
Market Restraints
- Proprietary format lock-in costs:Device-stick ecosystem compatibility prevents cross-brand switching and fragments consumer choice.
- Input material concentration:Blade heating elements and ceramic substrates depend on limited qualified suppliers in East Asian manufacturing clusters.
- Tax parity uncertainty:Pending Health Promotion Act amendments threaten to compress margin structures if heated tobacco faces combustible-equivalent levies.
Strategic Opportunities
- Fukuoka corridor expansion:Kyushu's metropolitan axis shows underpenetrated convenience store stick sales relative to Kanto and Kansai baselines.
- Flavor R&D acceleration:Menthol-variant pipelines targeting female switching demographics remain nascent versus male-skewed straight tobacco profiles.
- Smoking lounge infrastructure retrofit:Existing designated indoor-use venues in Tokyo and Osaka present partnership channels for device trial and stick vending.
Industry Challenges
- Thermal engineering talent scarcity:Battery systems integration and heat-exchanger design expertise concentrates in automotive and consumer electronics sectors.
- JIS certification timeline compression:METI's tightened testing protocols extend product approval cycles while R&D teams race hardware refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Heated Tobacco Products Market |
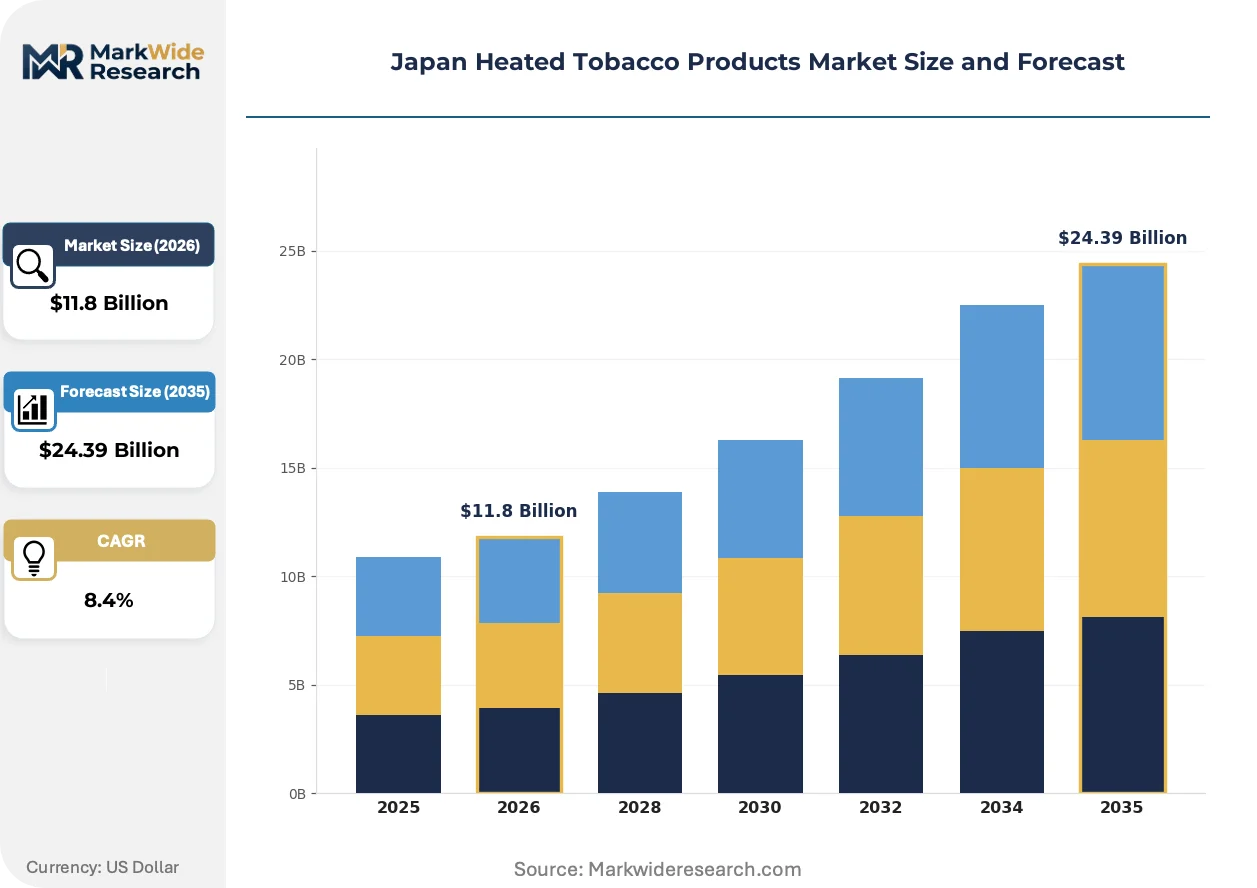
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Tobacco Sticks, Accessories, Heat-Not-Burn Units Customer Type: Retail Consumers, Wholesale Buyers, Online Shoppers, Corporate Clients Distribution Channel: Specialty Stores, Supermarkets, E-commerce Platforms, Convenience Stores Flavor Type: Tobacco, Menthol, Fruit, Herbal |
| Companies Covered | Imperial Brands Plc, Altria Group, Inc., Philip Morris Japan Inc., Philip Morris International Inc., Japan Tobacco International, Japan Tobacco Inc., KT&G Corporation, Imperial Brands, British American Tobacco Japan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Heated Tobacco Products Market Strategic Shifts & Innovations
Hardware miniaturization and aerosol chemistry optimization are converging to reshape competitive differentiation in Japan's heated tobacco segment.
Induction heating architectures are absorbing development resources previously allocated to resistive blade systems. Adult smokers aged 30-50 in metropolitan corridors are adopting induction-based devices for reduced cleaning cycles and temperature precision. This technology transition is absorbing margin from legacy ceramic blade suppliers while rewarding magnetic coil and ferrite core specialists.
METI's 2023 electrical appliance safety certification revisions mandate expanded thermal runaway testing for lithium-ion battery systems. Manufacturers must now submit device-level abuse testing documentation alongside cell-level data. Stick-format hardware categories face the steepest compliance cost escalation as JIS standards tighten on rapid-charge protocols.
Subscription-style stick replenishment is consolidating purchasing decisions from retail impulse toward app-directed auto-delivery. Convenience store operators in Greater Tokyo are responding with dedicated heated tobacco counters and loyalty program integration. This behavioral pivot concentrates stick-format demand among platform-locked consumers and compresses trial rates for competing device ecosystems.
Japan Heated Tobacco Products Market Segmentation
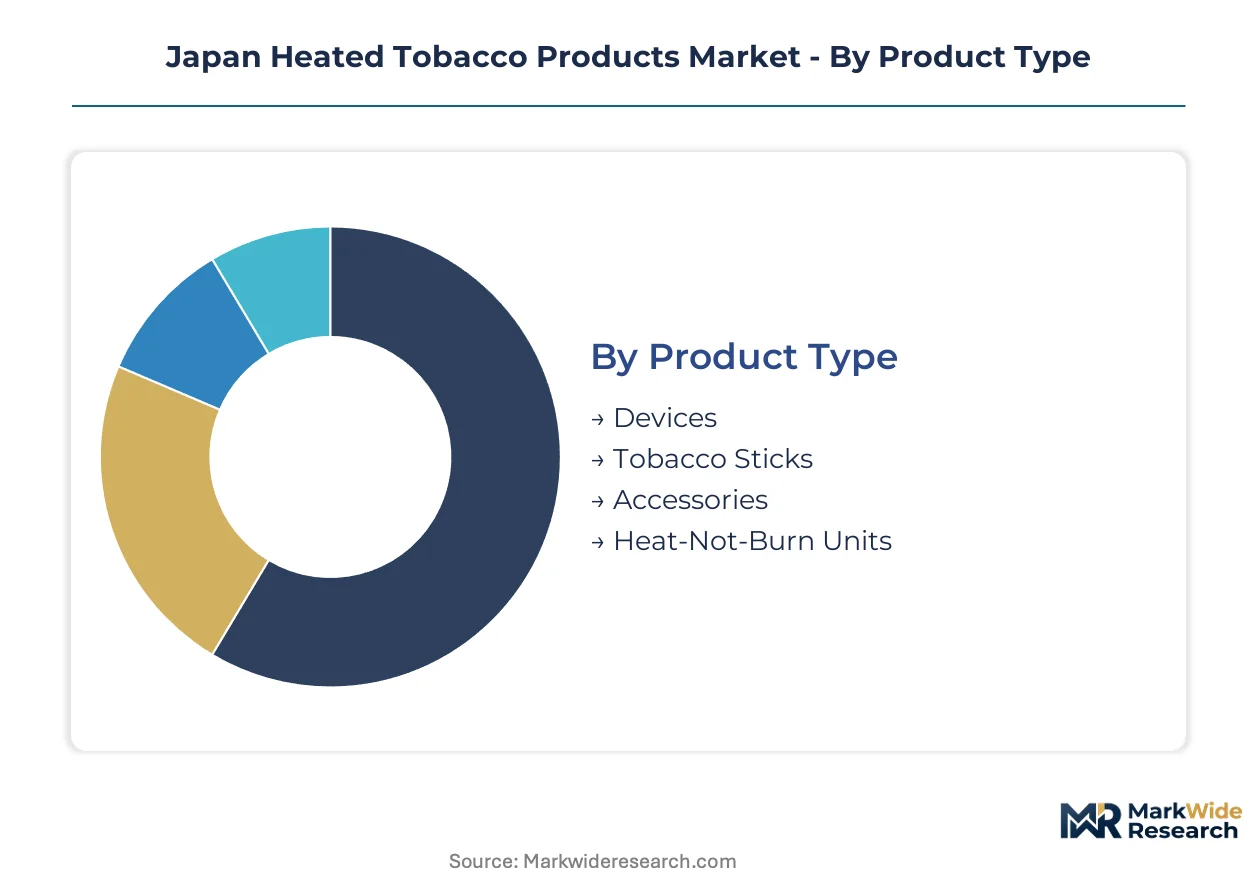
Segmentation in Japan's heated tobacco market reveals how proprietary ecosystems, channel infrastructure, and flavor preferences partition purchasing behavior. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer resource allocation.
Product Type:
The customization-to-standardization spectrum spans captive device-stick systems versus interoperable accessories, with proprietary architectures commanding premium positioning.
- Devices:Electronic heating systems incorporating blade or induction architectures define the primary consumer entry point. Demand concentrates in Greater Tokyo and Osaka-Kobe corridors where smoking lounge infrastructure supports trial and switching from combustible formats.
- Tobacco Sticks:Proprietary consumable formats engineered for specific device thermal profiles generate recurring revenue through format lock-in. These units represent the fastest-growing margin pool as subscription-style replenishment consolidates purchasing decisions toward platform-locked consumers.
- Accessories:Cleaning implements, charging docks, and carrying cases extend device lifecycle and user retention.
- Heat-Not-Burn Units:Integrated device-consumable bundles target first-time adopters seeking simplified onboarding.
Leading the category by volume: Devices. Growing fastest: Tobacco Sticks.
Customer Type:
Volume concentration versus margin extraction divides this category, with institutional procurement running counter to individual switching patterns.
- Retail Consumers:Individual adult smokers aged 30-50 drive switching momentum through convenience store trials and smoking lounge exposure.
- Wholesale Buyers:Regional distributors and retail chains aggregate demand across multiple prefectures, capturing logistics efficiencies.
- Online Shoppers:Subscription-platform users auto-replenish stick inventories through app-directed fulfillment, bypassing impulse-driven konbini purchasing.
- Corporate Clients:Hospitality venues and designated smoking facilities procure device fleets and bulk stick allocations for patron amenities.
Dominant by transaction volume: Retail Consumers. Steepest expansion trajectory: Online Shoppers.
Distribution Channel:
Physical proximity to replenishment occasions versus digital subscription lock-in shapes channel economics and consumer lifetime value.
- Specialty Stores:Dedicated tobacco retailers provide consultative selling and device servicing for experienced users.
- Supermarkets:Mass-market stick availability targets routine grocery trip replenishment in suburban prefectures.
- E-commerce Platforms:Direct-to-consumer channels enable auto-delivery subscriptions and flavor variety bundling.
- Convenience Stores:Japan's 55,000-plus konbini network delivers unmatched last-mile access for impulse stick purchases and device trials in metropolitan corridors.
Highest transaction frequency: Convenience Stores. Gaining share fastest: E-commerce Platforms.
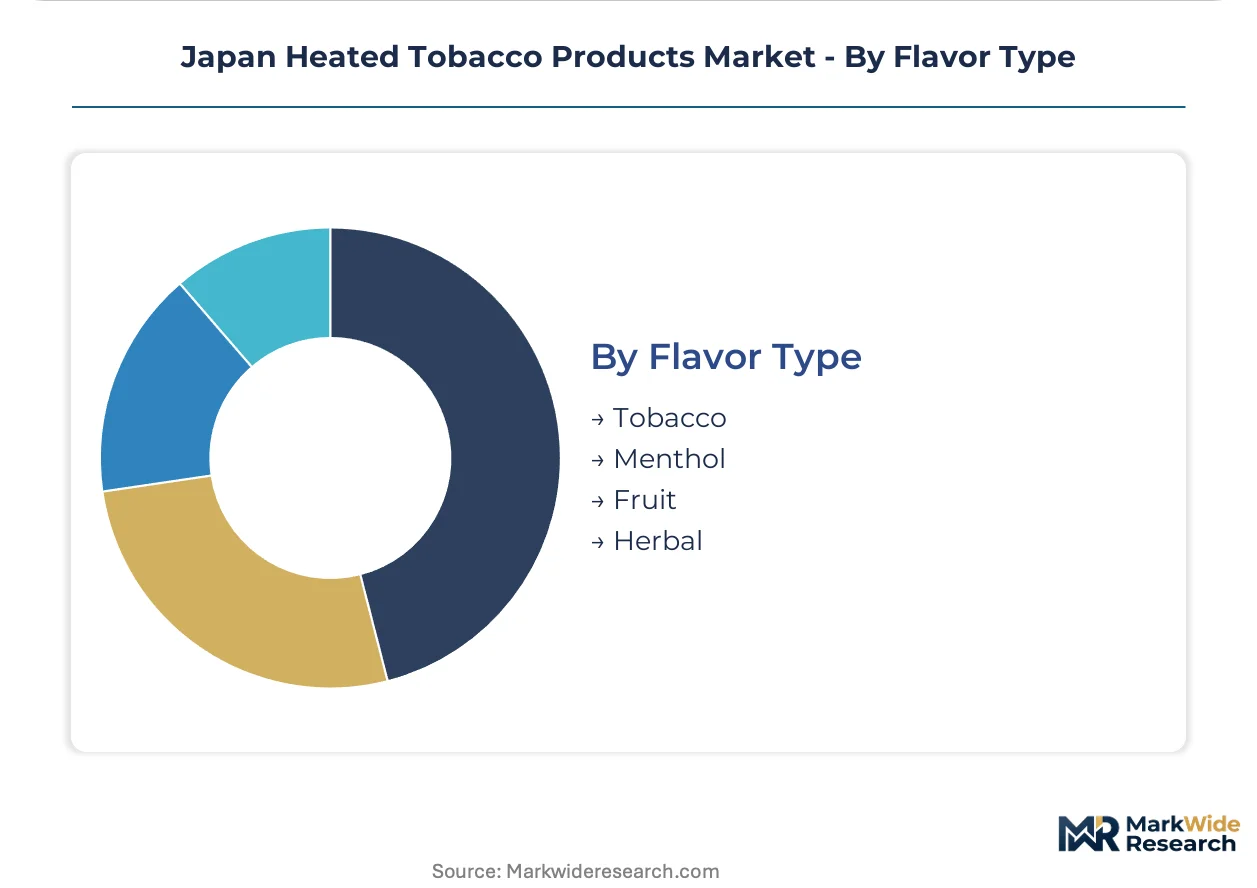
Flavor Type:
Regulatory tolerance for characterizing flavors versus straight tobacco authenticity partitions demographic targeting strategies.
- Tobacco:Unflavored profiles targeting male-skewed switching demographics seeking cigarette-like experience replication.
- Menthol:Cooling-variant formulations dominate female switching cohorts and younger adult adopters in Fukuoka and Osaka metropolitan zones.
- Fruit:Characterizing flavor offerings face tighter PMDA advertising scrutiny under modified-risk claim frameworks.
- Herbal:Non-tobacco botanical formulations occupy niche positioning with limited METI electrical appliance certification pathways.
Current volume leader: Tobacco. Expanding most quickly: Menthol.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic tobacco leaf cultivation in Iwate and Hokkaido prefectures anchors Japan's heated tobacco supply base, with metropolitan consumption corridors driving demand concentration across the archipelago.
Kanto/Tokyo
Adult smokers aged 30-50 in Greater Tokyo generate the highest stick-format consumption velocity nationwide. METI's electrical appliance safety certifications apply most stringently here given product registration density. Convenience store operators in Shinjuku and Shibuya wards maintain dedicated heated tobacco counters with loyalty program integration.
Kansai/Osaka
The Osaka-Kobe corridor exhibits comparable switching momentum from combustible formats with strong menthol-variant preference. PMDA oversight of modified-risk claims shapes manufacturer messaging strategies across Hyogo and Osaka prefectures. Smoking lounge infrastructure in Umeda and Namba districts supports device trial and subscription onboarding.
Kyushu/Fukuoka
Fukuoka metropolitan zones show underpenetrated stick sales relative to Kanto and Kansai baselines despite favorable demographic profiles. METI technical standards enforcement extends to Kyushu manufacturing subcontractors supplying ceramic heating elements. Convenience store expansion in Hakata and Tenjin is accelerating to close the replenishment gap.
Chubu/Nagoya
Aichi prefecture's automotive electronics cluster supplies thermal engineering talent for battery systems integration. JIS standards for rapid-charge protocols are tested extensively at Nagoya-based certification laboratories. Device assembly facilities in Toyota City leverage adjacent precision manufacturing capabilities.
Hokkaido
Sapporo and surrounding municipalities exhibit slower switching velocity due to combustible cigarette tax advantages and indoor-use restrictions. PMDA regulatory frameworks apply uniformly here, though distribution logistics concentrate replenishment in urban corridors. Limited smoking lounge infrastructure constrains device trial opportunities outside Sapporo proper.
Japan Heated Tobacco Products Market Key Industry Players
Global majors compete with regional champions across proprietary device architectures and stick-format ecosystems, producing a tiered structure with captive technology holders at the apex and flavor-specialist challengers contesting mid-tier positioning. Market concentration reflects multi-decade brand equity in combustible tobacco translated into heated format migration. Strategic archetypes include vertically integrated device manufacturers, domestic leaf-processing incumbents, and Korean flavor-innovation specialists. Dominant competitive moves center on backward integration into heating element supply and multi-source supplier panel construction to defray input concentration risk.
Within the captive-technology tier, Philip Morris Japan Inc. and Japan Tobacco Inc. exemplify divergent approaches to ecosystem lock-in, with the former emphasizing blade heating architectures and the latter sustaining domestic leaf-processing infrastructure. KT&G Corporation occupies a challenger position anchored in menthol-variant R&D pipelines. Imperial Brands Plc and Altria Group, Inc. sit within the global diversified tobacco conglomerate archetype, while British American Tobacco Japan represents transnational format adaptation strategies.
| Leading Market Players |
|---|
| Imperial Brands Plc |
| Altria Group, Inc. |
| Philip Morris Japan Inc. |
| Philip Morris International Inc. |
| Japan Tobacco International |
| Japan Tobacco Inc. |
| KT&G Corporation |
| Imperial Brands |
| British American Tobacco Japan |
| Others |
Cost & Logistics Intelligence
Captive technology holders with proprietary device architectures exercise asymmetric pricing power over stick-format replenishment, while multi-source supplier panel construction among mid-tier manufacturers compresses component costs and erodes margin buffers. METI certification timelines and JIS battery standards feed directly into landed cost structures, forcing trade-offs between compliance investment and retail price positioning.
Pricing Analysis
Warranty-bundled device replacements versus unbundled stick purchases split consumer lifetime value calculations across the Japan market. Subscription-style auto-replenishment platforms command premium stick pricing through platform lock-in, while transactional konbini sales compete on per-unit accessibility. Price differentiation hinges on METI certification tier and induction versus legacy blade architecture. Cost compression in entry-level device tiers intensifies as KT&G and regional challengers absorb margin sacrifice for share acquisition. Corporate hospitality buyers exhibit lowest price sensitivity; individual switchers aged 30-50 in Greater Tokyo show highest elasticity to per-stick differentials.
Supply Chain Analysis
Single-source vulnerability sits with East Asian ceramic substrate suppliers concentrated in South Korea and Taiwan, where qualified heating element production clusters. Blade architectures draw from Japanese ferrite core specialists and Chinese magnetic coil manufacturers, while lithium-ion cells feed from South Korean and Japanese battery majors. Tariff exposure through cross-border component flows presents structural risk given METI local-content preferences for electrical appliance certification. Distribution runs through captive direct-to-retail channels for multinational incumbents, with regional distributors handling mid-tier brand logistics across prefectural wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's heated tobacco market represents a consolidation play as METI certification cost escalation and R&D timeline compression force sub-scale competitors toward exit or acquisition. Induction heating transition costs and JIS battery testing requirements disproportionately burden capital-constrained challengers.
For Market Incumbents: Hedge format lock-in erosion by accelerating backward integration into magnetic coil supply and securing dual-source ceramic substrate panels. Philip Morris Japan and Japan Tobacco Inc. must preempt KT&G's menthol-variant pipeline expansion through exclusive Fukuoka corridor convenience store partnerships. Thermal engineering talent scarcity in automotive electronics clusters demands targeted recruitment from Nagoya-based battery systems specialists.
For New Entrants and Emerging Players: METI's 2023 electrical appliance safety certification revisions in Japan open a window for induction-native architectures that bypass legacy blade supplier dependencies. White-space targets concentrate in female-skewed menthol variants and corporate smoking lounge fleet procurement in underpenetrated Kyushu metropolitan zones. Go-to-market execution should prioritize app-directed subscription onboarding over konbini impulse competition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor flavor-R&D specialists with PMDA modified-risk claim pipelines in Greater Tokyo and Osaka-Kobe corridors. Long-term viability hinges on platform-scale subscription retention rather than hardware replacement cycles. The signal to watch is Health Promotion Act amendment progress toward tax parity, which would compress margin structures and accelerate incumbent consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Architecture Migration | Magnetic coil and ferrite core supply chains absorb R&D resources previously allocated to ceramic blade systems. |
| Menthol-Variant Pipeline Expansion | Female switching demographics in Fukuoka and Osaka corridors remain underpenetrated versus male-skewed straight tobacco profiles. |
| Subscription Platform Auto-Replenishment | App-directed stick fulfillment consolidates purchasing decisions and compresses trial rates for competing device ecosystems. |
| Smoking Lounge Infrastructure Partnership | Designated indoor-use venues in Tokyo and Osaka districts present trial and vending channels for device onboarding. |
| Multi-Source Supplier Panel Construction | East Asian ceramic substrate concentration demands dual-qualification programs to defray input disruption risk. |
Research Approach
Document review covered METI technical standard filings, PMDA modified-risk tobacco product submissions, and JIS battery certification records, complemented by interviews with device engineering leads at major manufacturers, convenience store category buyers in Greater Tokyo, and thermal systems procurement managers at automotive electronics suppliers. Secondary validation drew from customs trade data for ceramic substrate imports, SEC filings of global tobacco conglomerates, and prefectural-level smoking lounge licensing databases. Bottom-up stick-format volume modeling and top-down device replacement cycle estimates were triangulated against convenience store point-of-sale patterns.
Historical consumption velocity in Kanto, Kansai, and Kyushu corridors was cross-referenced against panel input from distribution channel partners and regional wholesale aggregators. Segmentation dimensions modeled include product architecture type, flavor variant, customer procurement mode, and metropolitan corridor density. CAGRs were derived from cohort-specific switching momentum analysis and hardware refresh cadence assumptions. Industry-specific forecast inputs incorporated METI certification timeline scenarios and PMDA regulatory pathway probabilities for reduced-exposure claims.
The model assumes a particular technology adoption path favoring induction heating architectures; alternative pathways for resistive blade system persistence would alter the outlook for supplier panel composition and margin distribution. Forecasts reflect assumptions regarding Health Promotion Act amendment timing, tax parity implementation scope, and indoor-use permission frameworks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Premium Cigarette Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Cigarette Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
E-Cigarette and Vaping Market