
 Europe Hair Styling Products Market | 2026-2036
Europe Hair Styling Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Styling Products Market Foresight
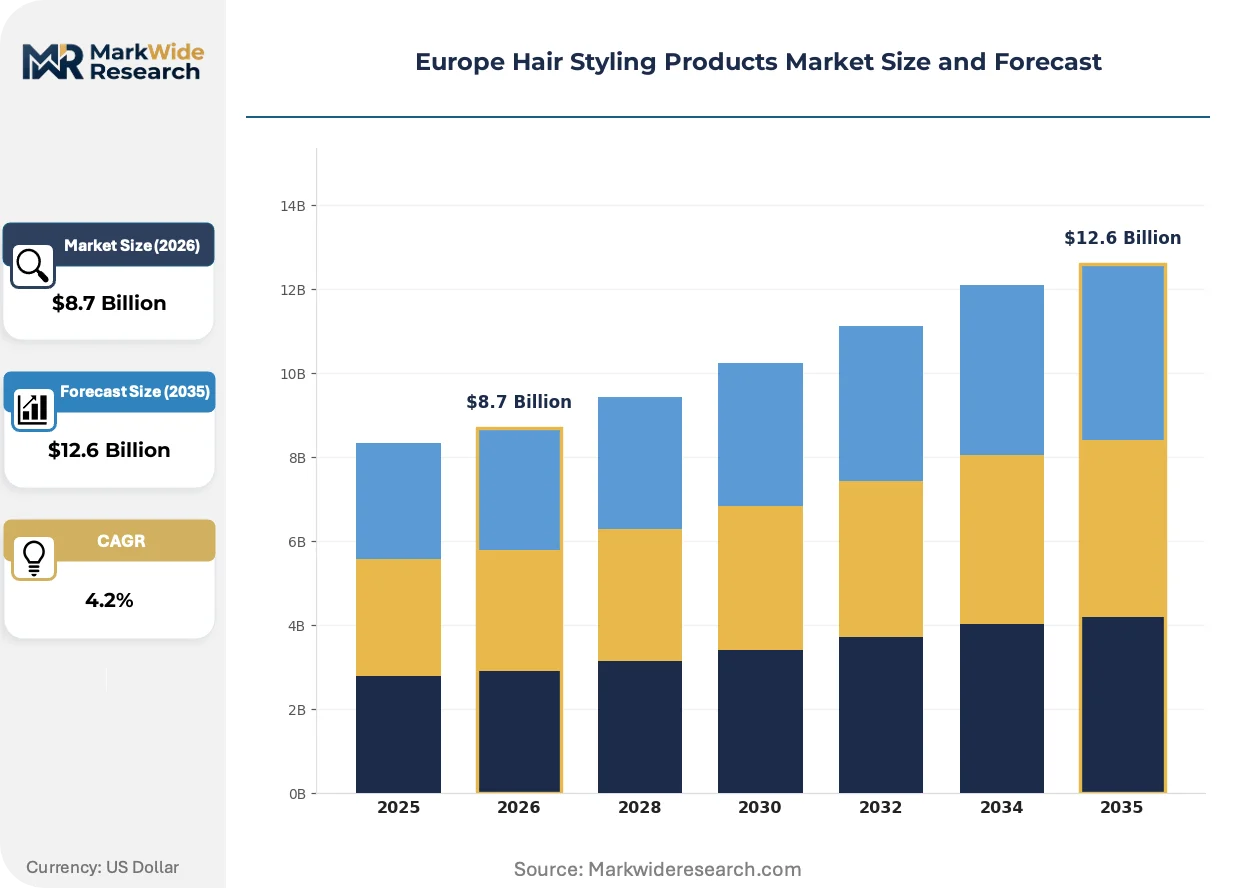
The Europe hair styling products market is restructuring around a sharp divergence between premium salon-grade formulations and mass-market commodity lines. L'Oréal S.A. leverages its professional division to dominate high-margin salon channels across France and Italy. Henkel AG & Co. KGaA anchors its position through Schwarzkopf's deep penetration in German drugstore retail. Beiersdorf AG competes by specializing in waxes and texturizers that command loyalty among male grooming segments in the United Kingdom.
Europe hair styling products encompass gels, mousses, sprays, and waxes formulated with film-forming polymers, emulsifiers, and propellants to deliver hold, volume, and texture for consumer and professional use. Natural and organic formulations now lead growth as salons across Spain and the Netherlands switch to silicone-free and paraben-free alternatives to meet client preferences. Sprays retain the largest volume share but face margin compression, while waxes capture disproportionate value in men's grooming through higher per-unit pricing and repeat purchase frequency.
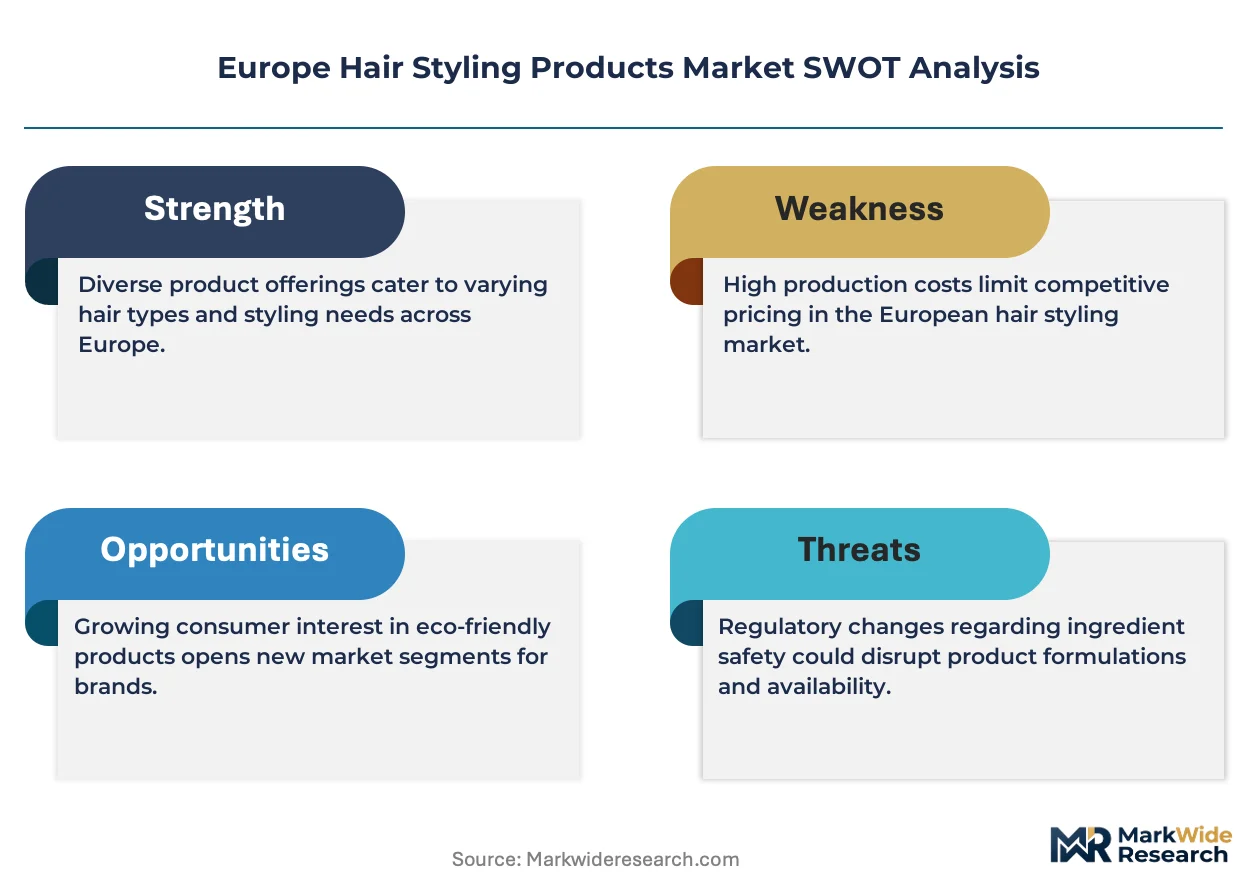
REACH and the EU Green Deal constrain ingredient palettes by mandating biodegradability assessments and restricting microplastic-containing rinse-off products. ECHA's ongoing evaluations of cyclic volatile methylsiloxanes force reformulation timelines that favor suppliers with captive R&D labs over contract manufacturers. Stakeholders must monitor Germany's KBA-equivalent environmental enforcement patterns and France's ANSM cosmetic safety alerts, as these two regulators set the compliance pace that other EU member states follow.
Market Dynamics
REACH-mandated biodegradability assessments are forcing wholesale polymer substitution across European hair styling formulations, compressing R&D timelines while opening competitive gaps between captive labs and contract manufacturers.
Growth Catalysts
- Professional salon channel expansion:High-service hair salons in France and Italy drive premium product attachment rates through stylist recommendation authority.
- EU Green Deal compliance demand:Biodegradable polymer mandates create first-mover advantages for suppliers with validated environmental safety dossiers.
- Men's grooming segment premiumization:Texturizers and matte clays command repeat purchase loyalty through higher per-unit pricing in United Kingdom barbershops.
Market Restraints
- Film-forming polymer supply concentration:Specialty polymer production clusters in German chemical corridors create input bottleneck risks during reformulation waves.
- ECHA cyclic siloxane evaluation timelines:Pending restrictions on volatile methylsiloxanes force precautionary formulation abandonment before final rulings.
- Natural ingredient cost volatility:Plant-derived waxes and gums face harvest-dependent price swings that destabilize mass-market margin structures.
Strategic Opportunities
- Spanish salon organic conversion:Silicone-free and paraben-free demand in Madrid and Barcelona salons outpaces qualified local supplier coverage.
- Refill station channel innovation:Packaging-free bulk dispensing in Dutch urban retail cuts material costs while satisfying circular economy preferences.
- Waterless formulation convergence:Solid styling bars combining concentrated actives with reduced shipping weight target sustainability-motivated professional buyers.
Industry Challenges
- Cosmetic formulation chemist scarcity:Specialized expertise in biodegradable polymer compatibility lags behind regulatory-driven reformulation demand.
- Multi-jurisdiction dossier preparation:Divergent national enforcement patterns between Germany's KBA-equivalent environmental protocols and France's ANSM safety alerts complicate unified product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Styling Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Mousses, Sprays, Waxes Application: Professional, Retail, Salon, Personal Formulation: Natural, Organic, Chemical, Eco-Friendly Target Audience: Women, Men, Teens, Kids |
| Companies Covered | Procter & Gamble Company, Beiersdorf AG, L'Oréal S.A., The Estée Lauder Companies Inc., Kao Corporation, Henkel AG & Co. KGaA, Coty Inc., Amway Corporation, Unilever PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Styling Products Market Shifts & Advancements
Biodegradable film-forming polymers are consolidating technical roadmaps across European hair styling R&D, compressing the viable ingredient palette while rewarding suppliers with validated environmental fate data.
Plant-derived styling polymers are consolidating hold-performance benchmarks previously dominated by petrochemical acrylates. Premium salons in Milan and Paris adopt these bio-based alternatives at accelerated trial rates. The shift is consolidating market share among three specialty chemical houses with captive fermentation capacity.
REACH restriction proposals on microplastic-containing rinse-off products are compressing formulation freedom for gel and mousse categories. ECHA's 2022-2024 restriction roadmap forces proactive abandonment of nylon and polyethylene-derived texturizers. German drugstore retailers now require biodegradability certifications as listing prerequisites.
Barbershop channel disintermediation is reshaping male grooming product access in United Kingdom cities. Direct-to-professional distribution platforms bypass traditional wholesale layers. Manchester and Birmingham barbers now source matte clays and fiber pastes through specialized B2B portals with same-day delivery guarantees.
Europe Hair Styling Products Market Segmentation
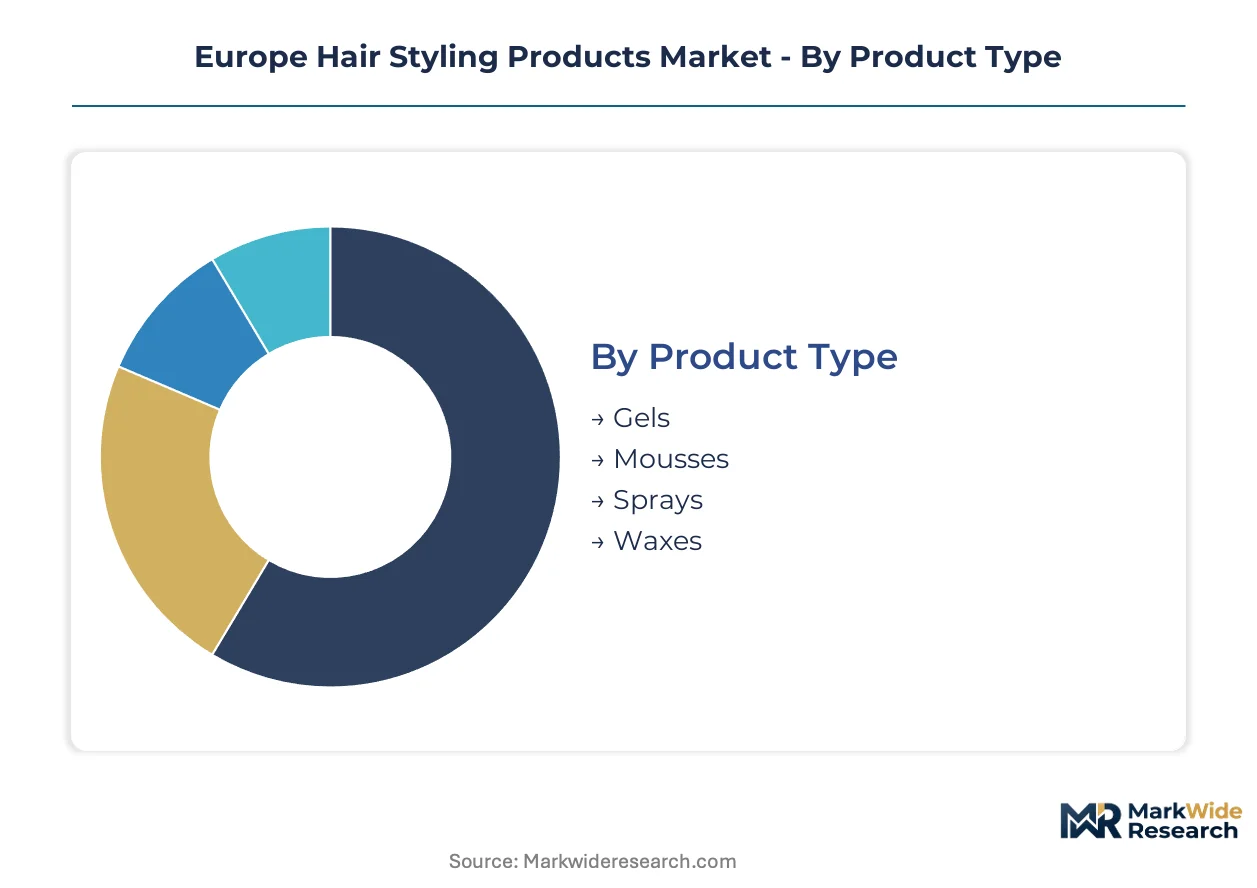
Segmentation in the Europe hair styling products market determines which REACH dossiers and biodegradability certifications each product line must carry. Reformulation timelines and channel access permissions vary sharply across these divides.
Product Type:
REACH-mandated biodegradability assessments apply unevenly across product types, with rinse-off formulations facing stricter scrutiny than leave-in treatments under ECHA's microplastic restriction proposals.
- Sprays:Aerosol and pump-dispensed formulations rely on film-forming polymers suspended in alcohol or water-based carriers. Demand concentrates in French and Italian professional salons where stylists prioritize humidity resistance and rapid drying. ECHA's pending volatile methylsiloxane evaluations force precautionary reformulation of silicone-based shine variants.
- Waxes:Petrolatum, beeswax, and plant-derived wax blends deliver moldable hold and matte finish for texturizing applications. United Kingdom barbershops drive disproportionate value capture through higher per-unit pricing and repeat purchase frequency in male grooming segments.
- Gels:Water-based formulations with carbomer or natural gum thickeners provide maximum hold for structured styles.
- Mousses:Foam-dispersed polymers add volume through lightweight film formation on hair shafts.
Leading the category by volume: Sprays. Growing fastest: Waxes.
Application:
Channel selection determines margin structure and regulatory exposure, with professional-facing lines requiring ANSM safety dossiers in France and KBA-equivalent environmental compliance in Germany.
- Professional:Salon-exclusive formulations carry higher active concentrations and specialized polymers not cleared for retail distribution. German chemical corridors supply captive R&D labs serving this channel with validated biodegradability data.
- Salon:Distinct from broader professional classification, this segment captures stylist-recommended products for at-home maintenance between appointments.
- Retail:Mass-market distribution through drugstore chains in Germany and supermarkets in Spain faces compressed margins but volume scale.
- Personal:Direct-to-consumer e-commerce and specialty beauty retailers target individual purchasers with subscription models.
Highest margin capture: Professional. Expanding most quickly: Salon.
Formulation:
Ingredient sourcing strategy separates segments by supply chain risk profile, with natural-derived waxes facing harvest-dependent price volatility that chemical alternatives avoid.
- Natural:Plant-derived gums, waxes, and essential oils exclude synthetic polymers entirely. Madrid and Barcelona salons convert to these alternatives faster than qualified local suppliers can scale production.
- Organic:Certified formulations meeting EU organic cosmetics standards command listing prerequisites at Dutch refill stations and German drugstore chains.
- Chemical:Petrochemical-derived acrylates and silicones retain performance benchmarks but face phased restriction under REACH microplastic rules.
- Eco-Friendly:Hybrid positioning combining biodegradable synthetic polymers with reduced packaging impact targets circular economy preferences.
Steepest expansion trajectory: Natural. Largest installed base: Chemical.
Target Audience:
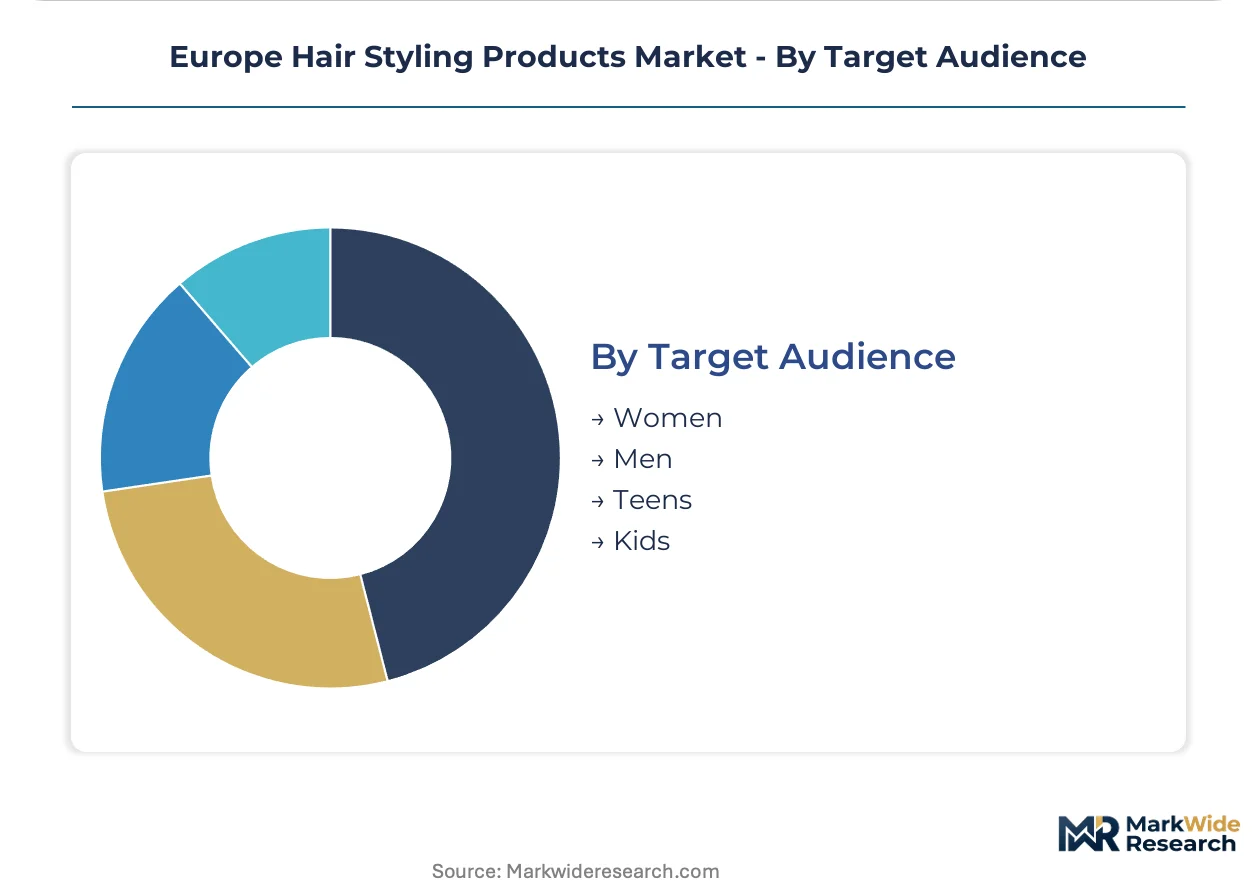
Demographic targeting shapes distribution architecture, with male-focused lines leveraging direct-to-professional portals while female-oriented SKUs dominate retail shelf space.
- Men:Matte clays, fiber pastes, and texturizers distributed through Manchester and Birmingham barbershop B2B portals with same-day delivery guarantees.
- Women:Volume mousses, heat protectant sprays, and finishing serums anchor salon recommendation authority in Paris and Milan.
- Teens:Entry-priced gels and temporary color sprays concentrate in drugstore retail across Spain and the Netherlands.
- Kids:Gentle, tear-free formulations with simplified ingredient lists face distinct safety evaluations under France's ANSM pediatric cosmetic alerts.
Gaining share fastest: Men. Maintaining volume dominance: Women.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris and Milan anchor European salon-grade demand through stylist recommendation networks that drive premium product attachment rates. German chemical corridors supply biodegradable polymer inputs to formulation labs across the continent. REACH enforcement patterns in these three metros establish compliance precedents that smaller member states adopt.
Germany
Professional salon channels in Berlin and Hamburg drive premium styling product volumes through stylist authority and repeat client maintenance purchases. The country's KBA-equivalent environmental protocols enforce stricter biodegradability documentation than baseline REACH requirements. North Rhine-Westphalia's chemical corridor clusters specialty polymer production that feeds captive R&D labs serving salon-exclusive lines.
France
Parisian high-service salons command the highest per-unit pricing for finishing sprays and humidity-resistant formulations across Europe. ANSM cosmetic safety alerts set pediatric and professional-use standards that neighboring regulators reference. Lyon and Marseille distribution hubs channel organic-certified waxes and texturizers to barbershops prioritizing silicone-free alternatives.
United Kingdom
Manchester and Birmingham barbershops drive male grooming segment expansion through direct-to-professional B2B portals with same-day delivery guarantees. The country's post-Brexit chemical regulation divergence creates parallel dossier requirements for GB-market products. London salon chains anchor volume for volume-building mousses and heat protectant sprays recommended for at-home maintenance.
Italy
Milan's fashion-week ecosystem generates concentrated demand for high-hold, rapid-drying sprays among editorial stylists and celebrity hairdressers. EU Green Deal implementation timelines accelerate reformulation deadlines for silicone-based shine variants. Turin and Bologna manufacturing clusters produce plant-derived styling polymers that meet emerging biodegradability certification standards.
Spain
Madrid and Barcelona salons convert to silicone-free and paraben-free formulations faster than qualified local suppliers can scale production capacity. The country's national pharmaceutical regulator aligns cosmetic safety evaluations with ECHA guidance while maintaining distinct pediatric formulation alerts. Valencia port logistics handle bulk natural wax imports facing harvest-dependent price volatility.
Europe Hair Styling Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across salon channel access and biodegradable polymer validation capabilities. The market structures around three tiers: multinational beauty conglomerates with captive professional divisions, mid-scale regional specialists, and contract manufacturers serving private-label retail lines. Consolidation pressure concentrates among polymer suppliers rather than finished goods brands. Dominant competitive moves include portfolio diversification into waterless solid formats and strategic partnerships with refill station operators.
Within the multinational conglomerate tier, L'Oréal S.A., Henkel AG & Co. KGaA, and Beiersdorf AG exemplify divergent channel anchoring strategies. The Paris-based S.A. structure occupies a position tied to professional salon authority. The German KGaA represents scale-driven drugstore retail penetration. The Hamburg-based AG exemplifies male grooming specialization through wax and texturizer concentration. These three anchors demonstrate how geographic origin and legal structure correlate with channel prioritization across the European market.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Beiersdorf AG |
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Coty Inc. |
| Amway Corporation |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Natural wax commodity benchmarks cascade through European hair styling supply chains, compressing margin structures at mass-market tiers while amplifying pricing power for validated biodegradable polymer suppliers serving salon-exclusive channels.
Pricing Analysis
Stylist recommendation authority anchors value-based pricing for professional salon formulations in Paris and Milan. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified biodegradable lines from conventional petrochemical alternatives from private-label drugstore SKUs. Cost compression in mass-market gels and mousses intensifies because ECHA-mandated reformulation timelines compress R&D recovery windows. Teen-oriented drugstore buyers exhibit highest price sensitivity, while United Kingdom barbershops demonstrate lowest sensitivity for matte clay texturizers with proven repeat purchase loyalty.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Lyon, and Milan orchestrate hub-and-spoke patterns for polymer inputs feeding formulation labs across Western Europe. Specialty film-forming polymer production clusters in Germany, plant-derived wax processing in Spain, and aerosol propellant blending in France create geographic interdependence. Raw material dependencies on cyclic methylsiloxanes, carbomer thickeners, and harvest-dependent carnauba wax expose formulators to commodity price volatility. Single-source vulnerability concentrates in German chemical corridors supplying biodegradable polymer alternatives. Distribution runs through professional salon direct-to-professional portals, drugstore retail chains, and Dutch refill station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European hair styling markets are consolidating around captive control of biodegradable polymer supply, with first-movers securing REACH dossier advantages that downstream competitors cannot replicate without 18-24 month regulatory lead times.
For Market Incumbents: Deepen backward integration into fermentation-based polymer production to lock in ECHA-validated environmental fate data before restriction timelines accelerate. Acquire Spanish and Dutch organic-certified suppliers facing capacity constraints from Madrid and Barcelona salon conversion demand. Defend salon channel access by embedding formulation chemists directly with Milan and Paris stylist networks.
For New Entrants and Emerging Players: Enter via waterless solid styling bar formats that bypass aerosol propellant supply constraints and command circular economy premiums at Dutch refill stations. Target United Kingdom barbershop B2B portals with same-day delivery guarantees as the most penetrable channel, where direct-to-professional disintermediation has already eroded incumbent wholesale relationships. Launch through sustainability-certified positioning to access German drugstore listing prerequisites.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale organic formulation specialists in Spain facing harvest-dependent input cost spikes but holding validated ANSM safety dossiers. Long-term viability hinges on regulatory compliance capability rather than brand equity alone, compressing the viable acquisition universe to targets with captive biodegradability certification. Watch ECHA's final cyclic siloxane restriction ruling as the inflection indicator that will trigger accelerated consolidation among polymer-dependent formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Polymers | Captive REACH dossier control locks in 24-month regulatory lead time over contract manufacturers. |
| Waterless Solid Format Development | Eliminates aerosol propellant dependencies while capturing circular economy premiums in Dutch urban retail. |
| Direct-to-Professional Portal Expansion | Bypasses wholesale margin layers in United Kingdom barbershop channels with same-day delivery guarantees. |
| Organic Certification Investment | Meets German drugstore listing prerequisites and Madrid salon conversion demand outpacing local supply. |
| Refill Station Partnership Network | Reduces packaging material costs while aligning with EU Green Deal circular economy implementation timelines. |
Research Methodology
Independent corroboration across formulation chemists at captive R&D labs, procurement directors at German drugstore chains, and regulatory affairs specialists navigating ECHA restriction timelines underwrites the qualitative findings in this study. Primary interviews with salon owners in Paris, Milan, and Barcelona, barbershop operators in Manchester and Birmingham, and distribution channel managers in Rotterdam triangulate demand-side patterns. Secondary validation draws from ECHA restriction proposal documentation, ANSM cosmetic safety alerts, EU Green Deal implementation guidance, and customs trade data on natural wax imports. Bottom-up volume builds from salon channel throughput estimates and retail audit data converge with top-down market sizing across product type, application, and formulation segments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, with segment-specific CAGRs derived from professional salon expansion trajectories, men's grooming premiumization velocity, and regulatory-driven reformulation adoption curves. Segmentation dimensions modeled include product type, application channel, formulation chemistry, and target audience demographics, cross-referenced with national regulatory enforcement patterns in France, Germany, and the United Kingdom. Forecast inputs incorporate biodegradable polymer substitution timelines, cyclic siloxane restriction probability-weighted scenarios, and harvest-dependent natural ingredient price volatility assumptions.
Revisions become necessary when ECHA accelerates restriction timelines, when German KBA-equivalent enforcement diverges from baseline REACH requirements, or when Spanish organic supplier capacity fails to match Madrid and Barcelona salon conversion rates. Forecasts reflect documented assumptions on regulatory adoption, channel shift velocities, and raw material substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
US Color Cosmetics Market