
 Durian Fruit Market | 2026-2036
Durian Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Durian Fruit Market Analysis
Cold-chain digitization is rewriting how perishable durian moves from Thai orchards to Chinese retail shelves. Sunshine International Co., Ltd. leverages blockchain-enabled traceability to sustain premium pricing across Southeast Asian wholesale channels. Thai Agri Foods Public Company Limited anchors its competitive position through backward integration into controlled-atmosphere storage facilities. Charoen Pokphand Group dominates frozen pulp supply contracts with institutional food manufacturers in East Asia.
Durian fruit, the spiky-husked tropical species Durio zibethinus, contains 27-35% edible aril with distinctive volatile sulfur compounds that determine commercial grading; processors flash-freeze pulp at minus 40 degrees Celsius to preserve organoleptic properties for industrial bakery and confectionery applications. Whole durian commands the highest unit margins in fresh export channels, while durian freeze-dried formats attract the fastest volume growth from snack-food manufacturers seeking extended shelf stability. Grade A classification, tied to minimum 30% dry matter content and uniform cavity shape, captures disproportionate margin pools in duty-free retail and gift-box segments.
Thailand's National Bureau of Agricultural Commodity and Food Standards enforces CODEX-aligned maximum residue limits for organophosphates, directly shaping orchard-level pesticide protocols across Chanthaburi and Rayong provinces. China's General Administration of Customs operates port-specific cold-chain inspection regimens that determine market access timing for Malaysian and Thai shipments. Stakeholders must monitor how evolving phytosanitary reciprocity agreements between ASEAN exporters and Chinese provincial authorities reshape seasonal arbitrage opportunities.
Market Dynamics
Cold-chain digitization and blockchain-enabled traceability systems are restructuring competitive advantage across the durian value chain, compressing arbitrage windows between Thai orchards and Chinese retail shelves while raising compliance barriers for conventional-grade exporters.
Growth Catalysts
- Freeze-drying technology maturation:Flash-freeze protocols at minus 40 degrees Celsius now preserve organoleptic properties for industrial bakery and confectionery applications, unlocking year-round ingredient supply for East Asian food manufacturers.
- China's tier-one urban cold-chain infrastructure:Shanghai, Beijing, and Guangzhou now support consistent fresh durian availability outside traditional harvest windows, collapsing seasonal demand spikes into steady consumption curves.
- Thailand's export-grade certification tightening:The Ministry of Agriculture and Cooperatives' stricter protocols create quality-based market segmentation that rewards premium-tier producers with duty-free retail and gift-box channel access.
Market Restraints
- Organophosphate residue compliance costs:Thailand's National Bureau of Agricultural Commodity and Food Standards enforces CODEX-aligned maximum residue limits that reshape orchard-level pesticide protocols across Chanthaburi and Rayong provinces.
- Fresh export supply concentration:Whole durian availability depends on narrow harvest windows and concentrated Thai-Malaysian production geography, exposing price volatility to climate disruption.
- Volatile sulfur compound sensitivity:The distinctive organoleptic signature that defines commercial grading also limits processing flexibility and transport modality options for uncontrolled-atmosphere logistics.
Strategic Opportunities
- Freeze-dried snack-food manufacturing:Extended shelf stability formats attract snack-food manufacturers seeking clean-label tropical fruit ingredients, with volume growth outpacing fresh and frozen pulp categories.
- Blockchain-enabled wholesale channels:Provenance verification systems create pricing premiums in Southeast Asian wholesale markets by documenting cultivar authenticity and cold-chain integrity.
- Controlled-atmosphere storage backward integration:Investment in captive ripening and storage infrastructure allows processors to arbitrage seasonal price spreads and guarantee contract fulfillment to institutional buyers.
Industry Challenges
- Phytosanitary reciprocity negotiation timelines:Evolving agreements between ASEAN exporters and Chinese provincial authorities create unpredictable market access timing that complicates harvest planning and logistics contracting.
- Grade A dry matter calibration:Achieving minimum 30% dry matter content with uniform cavity shape requires cultivar-specific orchard management expertise that concentrates among specialized Thai producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durian Fruit Market |
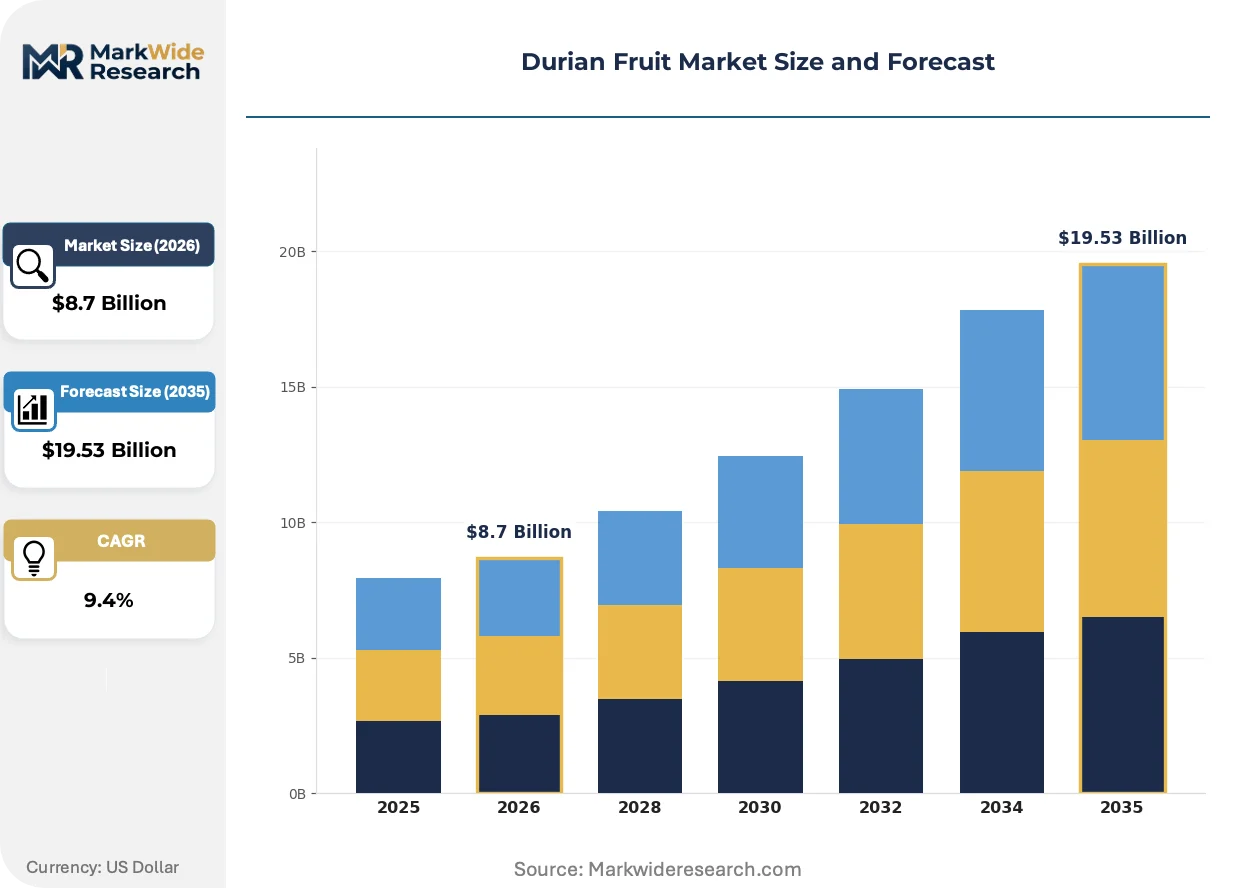
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Durian, Durian Pulp, Durian Freeze-Dried, Durian Puree Grade: Grade A, Grade B, Organic, Conventional Distribution Channel: Online Retail, Supermarkets, Fresh Markets, Wholesale Customer Type: Households, Restaurants, Food Manufacturers, Exporters |
| Companies Covered | Sunshine International Co., Ltd., Thai Agri Foods Public Company Limited, Charoen Pokphand Group, TRL South East Asia, Interfresh Co., Ltd., Top Fruits Sdn Bhd, Chainoi Food Company Limited, Newleaf Plantation Berhad, Hernan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durian Fruit Market Emerging Trajectories
Processing technology convergence and regulatory digitization are compressing traditional quality-assurance timelines while creating new premium capture mechanisms for traceability-verified supply chains.
Hyperspectral imaging systems for non-destructive ripeness assessment are hybridizing with automated sorting lines in Thai packing houses. Premium exporters in Chanthaburi province deploy these systems to reduce manual grading labor and standardize Grade A selection criteria. The technology is hybridizing quality control with throughput speed, enabling real-time cavity-shape evaluation that previously required destructive sampling.
China's General Administration of Customs has implemented port-specific cold-chain inspection regimens that mandate temperature logger documentation for every container. Malaysian and Thai shipments now face divergent clearance timelines depending on arrival port, with Guangzhou and Shenzhen operating distinct phytosanitary protocols. Frozen pulp exporters are responding by pre-positioning inventory in bonded warehouses to buffer against inspection delays.
Direct-to-consumer subscription models for fresh durian are displacing traditional wholesale distribution in China's tier-one cities. Young urban consumers in Shanghai and Beijing now expect cultivar-specific delivery with ripeness guarantees, bypassing wet-market intermediaries. This channel shift concentrates demand forecasting risk with platform operators while transferring cold-chain accountability upstream to Thai exporters.
Durian Fruit Market Segmentation
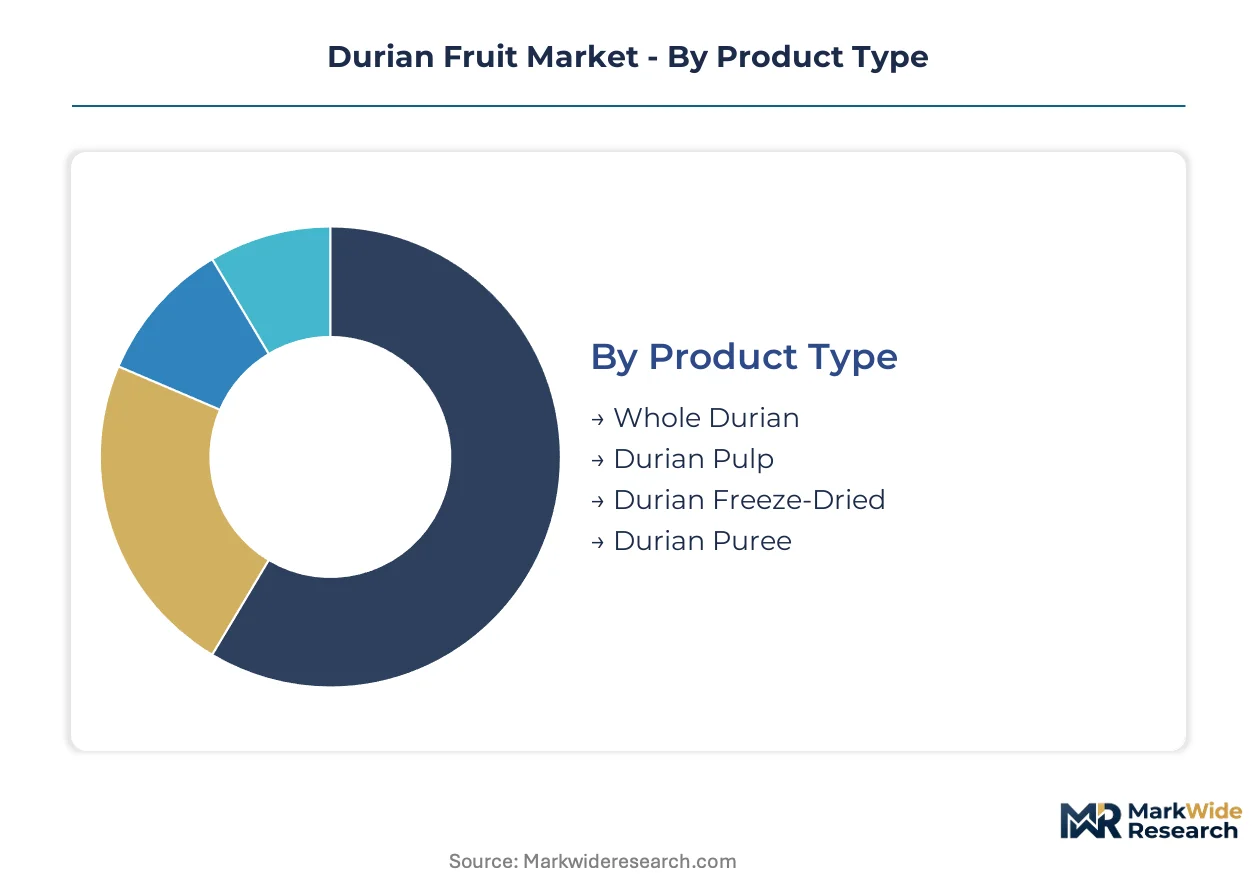
Segmentation in the durian market determines cold-chain investment intensity, phytosanitary compliance tiers, and margin capture mechanisms. Each category reflects distinct procurement patterns between institutional buyers and direct-to-consumer platforms.
Product Type:
After-sales service intensity varies sharply across formats, with whole fresh durian demanding real-time ripeness arbitration and freeze-dried products requiring minimal post-purchase intervention.
- Whole Durian:Fresh-harvested fruit with intact husk requires controlled-atmosphere transport and terminal ripening facilities. Demand concentrates in Shanghai, Beijing, and Guangzhou where direct-to-consumer subscription platforms now guarantee cultivar-specific ripeness windows. Cold-chain accountability sits entirely with Thai exporters under China's port-specific inspection regimens.
- Durian Pulp:Flash-frozen aril segments at minus 40 degrees Celsius preserve volatile sulfur compounds for industrial bakery and confectionery supply. Food manufacturers in East Asia drive procurement through year-round contract structures that buffer against seasonal harvest volatility. Backward integration into captive freezing infrastructure separates premium-tier suppliers from commodity traders.
- Durian Freeze-Dried:Lyophilized formats achieve extended shelf stability for snack-food clean-label formulations.
- Durian Puree:Homogenized pulp serves beverage and dessert manufacturing with standardized viscosity specifications.
By volume, Whole Durian leads. By growth pace, Durian Freeze-Dried is ahead.
Grade:
Cost tier stratification separates duty-free retail access from wholesale commodity channels, with certification compliance costs determining viable participant pools.
- Grade A:Minimum 30% dry matter content and uniform cavity shape specifications govern selection. Gift-box and duty-free retail segments in Chinese tier-one cities capture disproportionate margin pools for certified Thai producers. Hyperspectral imaging systems in Chanthaburi packing houses now automate non-destructive grading that previously required destructive sampling.
- Organic:Cultivar-specific orchard management without synthetic pesticide inputs. Thailand's National Bureau of Agricultural Commodity and Food Standards enforces CODEX-aligned maximum residue limits that reshape protocols across Chanthaburi and Rayong provinces. Compliance documentation creates pricing premiums in Southeast Asian wholesale channels.
- Grade B:Secondary classification for shape irregularities or marginal dry matter content.
- Conventional:Standard cultivation with approved agrochemical protocols under tighter export-grade certification requirements.
By revenue concentration, Grade A dominates premium capture. By regulatory exposure, Organic faces steepest compliance trajectory.
Distribution Channel:
Customer type fragmentation separates institutional procurement patterns from impulse-driven retail purchasing, with channel choice determining cold-chain accountability allocation.
- Online Retail:Platform-operated direct-to-consumer models displace traditional wholesale distribution in Chinese tier-one cities. Young urban consumers expect cultivar-specific delivery with ripeness guarantees, transferring demand forecasting risk upstream to Thai exporters. Subscription mechanics concentrate volume with platform operators who control last-mile cold-chain execution.
- Wholesale:Blockchain-enabled traceability systems create pricing premiums in Southeast Asian markets by documenting cultivar authenticity and cold-chain integrity. Sunshine International Co., Ltd. leverages provenance verification to sustain premium positioning across regional distribution networks. Bulk procurement by institutional buyers favors pre-positioned inventory in bonded warehouses.
- Supermarkets:Modern retail formats with standardized cold-chain specifications and private-label development capacity.
- Fresh Markets:Traditional wet-market intermediaries with minimal traceability infrastructure and price-sensitive purchasing.
By margin retention, Wholesale leads. By volume expansion, Online Retail is climbing the fastest.
Customer Type:
Application maturity separates commodity-grade procurement from specification-driven manufacturing supply, with customer scale determining contract structure and payment terms.
- Food Manufacturers:Industrial bakery, confectionery, and snack-food producers drive freeze-dried and frozen pulp demand through year-round ingredient supply contracts. Charoen Pokphand Group dominates frozen pulp supply contracts across East Asia through backward integration into controlled-atmosphere storage facilities. Specification adherence outweighs price sensitivity in supplier selection.
- Restaurants:Food-service operators in Chinese tier-one cities require consistent fresh availability outside traditional harvest windows. Thai Agri Foods Public Company Limited anchors competitive position through captive ripening infrastructure that arbitrages seasonal price spreads. Menu integration of durian-based desserts drives premium cultivar procurement.
- Households:End-consumer purchasing through retail and platform channels with ripeness arbitration expectations.
- Exporters:Intermediary traders managing cross-border logistics and phytosanitary clearance documentation.
By contract stability, Food Manufacturers lead. By price volatility exposure, Restaurants face steepest seasonal compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese tier-one cities concentrate the highest-value buyer archetypes, while Southeast Asian production clusters anchor supply-side investment. Cold-chain infrastructure gaps and phytosanitary reciprocity negotiations determine regional access hierarchies.
China
Shanghai, Beijing, and Guangzhou drive fresh durian consumption through direct-to-consumer subscription platforms that guarantee cultivar-specific ripeness windows. China's General Administration of Customs operates port-specific cold-chain inspection regimens with divergent clearance timelines at Guangzhou versus Shenzhen. Yangtze River Delta logistics hubs now pre-position Thai and Malaysian inventory in bonded warehouses to buffer against inspection delays.
Thailand
Chanthaburi and Rayong provinces supply the majority of export-grade whole durian and frozen pulp to East Asian food manufacturers. The National Bureau of Agricultural Commodity and Food Standards enforces CODEX-aligned maximum residue limits for organophosphates that reshape orchard-level pesticide protocols. Hyperspectral imaging systems in Chanthaburi packing houses automate non-destructive Grade A selection that previously required destructive sampling.
Malaysia
Pahang and Johor cultivation zones specialize in Musang King cultivars that command premium pricing in Chinese duty-free retail and gift-box segments. Phytosanitary reciprocity agreements with Chinese provincial authorities create unpredictable market access timing that complicates harvest planning. Malaysian exporters face divergent clearance protocols at Chinese ports compared to Thai shipments, compressing seasonal arbitrage windows.
Vietnam
Dak Lak and Lam Dong provinces are expanding durian cultivation acreage to capture displaced demand from Thai supply constraints. The Ministry of Agriculture and Rural Development is negotiating bilateral phytosanitary protocols with Chinese customs authorities to enable formal export channels. Vietnamese producers currently supply regional Southeast Asian markets while awaiting full China market access certification.
Singapore
The city-state functions as a re-export and value-add processing hub for Southeast Asian durian supply chains. Blockchain-enabled traceability systems create pricing premiums in wholesale channels by documenting cultivar authenticity and cold-chain integrity. Singapore-based traders arbitrage seasonal price spreads between Thai harvest windows and Chinese consumption peaks through controlled-atmosphere storage investments.
Durian Fruit Market Vendor Landscape
Channel-controlling players compete with product-specialist players across frozen pulp, freeze-dried formats, and fresh whole fruit segments. The vendor base stratifies into three tiers: integrated agribusiness conglomerates with captive cold-chain infrastructure, mid-scale processors with backward integration into controlled-atmosphere storage, and commodity traders dependent on third-party logistics. Dominant competitive moves include geographic expansion into bonded warehouse pre-positioning and portfolio diversification into freeze-dried snack-food ingredients.
Within the integrated agribusiness tier, Charoen Pokphand Group and Thai Agri Foods Public Company Limited occupy positions that exemplify backward integration strategies. Sunshine International Co., Ltd. anchors the traceability-verified wholesale channel segment. These three entities represent distinct archetypes: conglomerate-scale frozen pulp supply contracting, captive ripening infrastructure for fresh export arbitrage, and blockchain-enabled provenance verification for premium pricing capture.
| Leading Market Players |
|---|
| Sunshine International Co., Ltd. |
| Thai Agri Foods Public Company Limited |
| Charoen Pokphand Group |
| TRL South East Asia |
| Interfresh Co., Ltd. |
| Top Fruits Sdn Bhd |
| Chainoi Food Company Limited |
| Newleaf Plantation Berhad |
| Hernan Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Thai controlled-atmosphere ripening facilities drives supplier prioritization of long-term offtake contracts over spot market exposure, compressing margins for traders lacking backward integration while elevating pricing power for orchard-owning processors.
Pricing Analysis
Cost-plus contracts with Thai Ministry of Agriculture certification indexation dominate institutional procurement for frozen pulp supply. Pricing stratifies across Grade A gift-box, standard export-grade, and conventional wet-market tiers based on dry matter calibration and phytosanitary documentation completeness. Cost compression in conventional-grade channels is intensifying because Vietnam's pending China market access will expand low-cost supply availability. Food manufacturers exhibit lowest price sensitivity due to specification-driven supplier selection, while wet-market intermediaries face highest margin pressure from traceability mandates.
Supply Chain Analysis
Tariff exposure between Malaysia and Chinese provincial customs authorities dominates supply chain risk planning for Musang King exporters. Production gravity centers on Thailand, Malaysia, and emerging Vietnamese cultivation zones in Dak Lak and Lam Dong provinces. Raw material supply draws from specialized pollinator-dependent orchard management, sulfur-compound-sensitive cultivar stock, and CODEX-aligned pesticide input protocols. Single-source vulnerability concentrates in Thai Chanthaburi packing house capacity for Grade A hyperspectral grading. Distribution runs through bonded warehouse pre-positioning in Yangtze River Delta hubs, direct-to-consumer platform fulfillment, and blockchain-verified wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Durian commerce is approaching a platform-economics inflection where subscription-based direct-to-consumer models displace wholesale intermediation, with interoperability between Chinese e-commerce ecosystems and Thai traceability systems determining margin capture distribution.
For Market Incumbents: Entrench control over cultivar-specific genetic stock and captive ripening infrastructure to defend against Vietnamese volume entrants. Charoen Pokphand Group's frozen pulp contracting model and Thai Agri Foods' controlled-atmosphere backward integration demonstrate defensible positioning. Priority investment in hyperspectral grading automation at Chanthaburi facilities preserves Grade A selection throughput advantage.
For New Entrants and Emerging Players: Pursue freeze-dried snack-food ingredient supply contracts where specification barriers are lower than fresh export certification. Vietnamese producers awaiting full China phytosanitary approval offer the most penetrable white-space for regional Southeast Asian market development. Go-to-market positioning through Singapore re-export hubs leverages existing blockchain traceability infrastructure without direct China customs exposure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated Thai exporters with subscription direct-to-consumer contracts in Shanghai and Beijing. Long-term viability over a multi-year horizon favors acquisition targets with captive cold-chain infrastructure rather than trader-dependent business models. The signal to monitor is phytosanitary reciprocity agreement finalization between Vietnamese authorities and China's General Administration of Customs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | Captive ripening infrastructure arbitrages seasonal price spreads for Thai processors. |
| Blockchain-Enabled Traceability Deployment | Sunshine International's provenance verification sustains premium pricing in wholesale channels. |
| Freeze-Dried Format Capacity Expansion | Extended shelf stability unlocks snack-food manufacturer procurement beyond harvest windows. |
| Bonded Warehouse Pre-Positioning | Yangtze River Delta inventory buffers Malaysian and Thai shipments against inspection delays. |
| Hyperspectral Imaging Automation | Chanthaburi packing houses standardize Grade A selection without destructive sampling. |
Methodological Framework
A standing panel of orchard operations managers, cold-chain logistics directors, Chinese platform procurement leads, Thai export certification officers, and East Asian food manufacturer supply planners provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from Thailand's National Bureau of Agricultural Commodity and Food Standards export documentation, China's General Administration of Customs clearance statistics, ASEAN agricultural trade databases, and SEC filings from listed agribusiness conglomerates. Bottom-up volume modeling from cultivar-specific production clusters triangulated against top-down consumption estimates from tier-one city retail audit data.
Scenario-bracketing framed volume and value outputs across the projection horizon through sensitivity testing of phytosanitary reciprocity negotiation timelines and Vietnamese market access certification pathways. Segmentation dimensions modeled include product format, grade certification tier, distribution channel structure, and customer application type. CAGRs derived from historical growth pattern analysis adjusted for structural shifts in cold-chain infrastructure deployment and platform-based demand concentration. Industry-specific forecast inputs incorporated hyperspectral grading adoption curves and freeze-drying technology maturation trajectories.
Sensitivities concentrate around Chinese provincial customs protocol divergence, Vietnamese phytosanitary approval timing, and climate disruption impacts on Thai harvest windows. Forecasts reflect documented assumptions regarding cold-chain digitization penetration and subscription platform growth trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable Brain Devices Market
Others
UK Cat Food Market
Others
Global Extruded Plastics Market
Others
Australia Content Services Platform Market
Others
Middle East Location-Based Services Market
Others
Mexico Retail Market
Others
Rugged Devices Market
Others
Global Hardware Acceleration Market
Others
Singapore Retail Market
Others
Global on-Demand Laundry Service Market
Others
Global Magnetic Flow Meters Market
Others
Augmented Shopping Market
Others
Traditional PC Market
Others
Video-As-A-Service (Vaas) Market
Others
Finished Leather Market
Others
5G Smartphone Market