
 Indoor LBS Market | 2026-2036
Indoor LBS Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor LBS Market Intelligence
Healthcare is rebalancing toward asset tracking and patient flow optimization as hospitals deploy indoor positioning at scale. Microsoft Corporation leverages its Azure cloud infrastructure to anchor hybrid deployment models for enterprise clients. Cisco Systems, Inc. competes through its Wi-Fi access point ecosystem, which integrates location analytics directly into existing network hardware. Qualcomm Incorporated specializes in ultra-wideband chipset design, sustaining its position in high-precision measurement applications.
Indoor location-based services comprise positioning technologies that determine device coordinates within enclosed structures where satellite signals fail. Ultra-wideband achieves centimeter-level accuracy through time-of-flight calculations between anchors and tags, enabling collision avoidance in industrial settings. Wi-Fi and Bluetooth segments dominate current deployment volumes due to minimal incremental hardware costs in retrofitted buildings. Cloud-based delivery is expanding fastest as venues prefer subscription models over capital-intensive on-premises installations. RFID retains strongholds in controlled logistics environments where passive tag economics outperform active alternatives.
The FCC mandates indoor location accuracy for wireless emergency calls, compelling carriers and venue operators to upgrade legacy systems. ETSI and the EU AI Act shape European deployments by imposing transparency requirements on automated location analytics in public spaces. Stakeholders must monitor evolving interoperability standards between Bluetooth and ultra-wideband protocols as device ecosystems fragment across vendor silos.
Market Dynamics
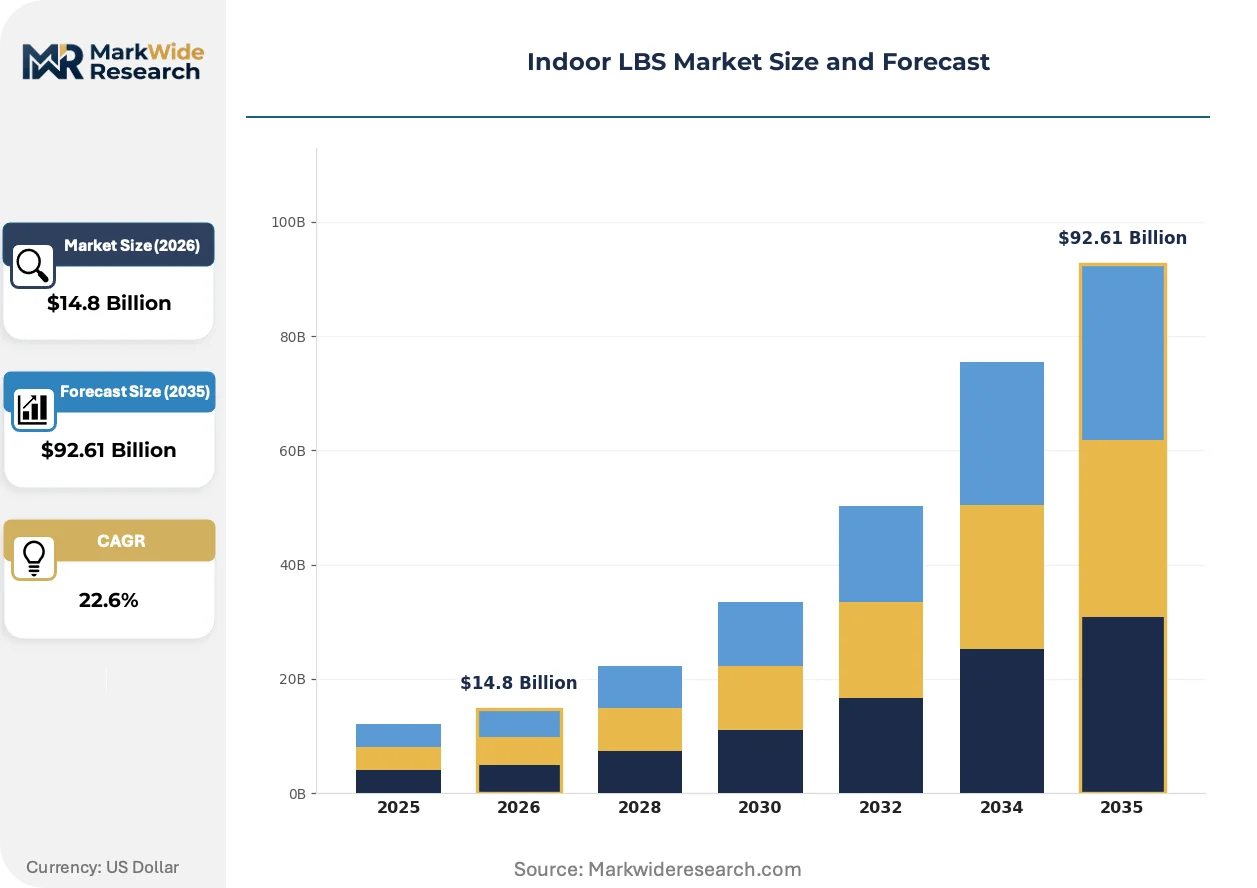
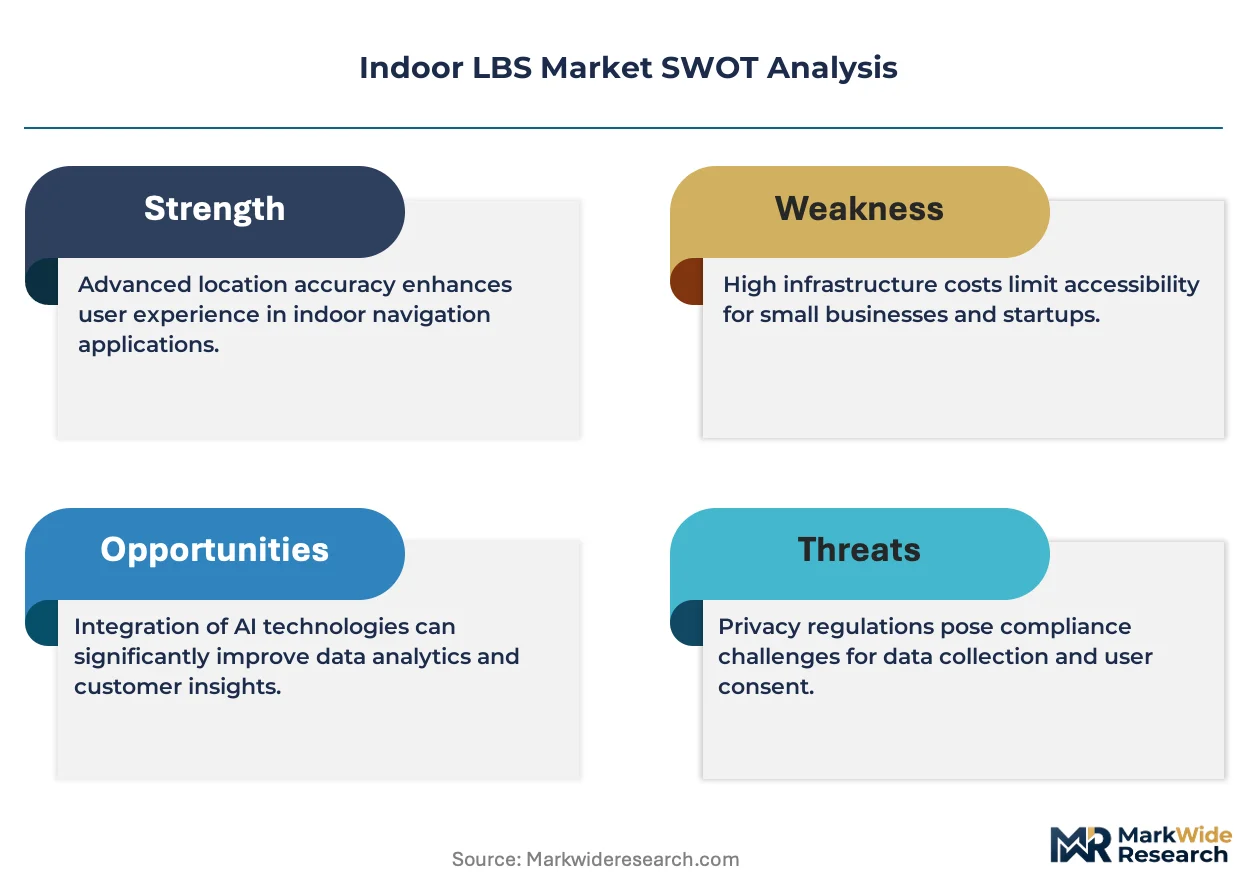
The Indoor LBS Market is restructuring around the collision between FCC-mandated emergency location accuracy and the economics of ultra-wideband deployment. Venue operators face simultaneous pressure to upgrade legacy Wi-Fi systems while containing subscription costs.
Growth Catalysts
- Public Safety Mandates:The FCC's wireless emergency call location requirements compel carriers and building managers to install certified indoor positioning infrastructure across high-occupancy structures.
- Healthcare Asset Tracking:Hospital systems deploy real-time location systems to reduce equipment search time and optimize patient throughput in emergency departments.
- Bluetooth Beacon Economics:Passive beacon networks leverage existing smartphone penetration, eliminating tag costs for visitor-facing wayfinding applications.
Market Restraints
- Ultra-Wideband Hardware Costs:Active UWB tags and anchor infrastructure require capital outlays that retrofit projects in older buildings cannot absorb.
- Signal Interference Complexity:Multi-path propagation in steel-and-concrete environments degrades time-of-flight calculations, limiting precision in industrial warehouses.
- Fragmented Protocol Standards:Non-interoperability between Bluetooth and UWB device ecosystems forces buyers into vendor-locked deployments.
Strategic Opportunities
- Smart Building Convergence:Integration of indoor positioning with HVAC and lighting control systems creates bundled service contracts for facility managers.
- Industrial Collision Avoidance:Forklift and autonomous mobile robot navigation in manufacturing plants drives demand for centimeter-accuracy measurement.
- Cloud Subscription Migration:Venue operators prefer operational expenditure models over on-premises server installations, expanding addressable market for SaaS location platforms.
Industry Challenges
- RF Engineering Talent Scarcity:Deployment of multi-technology positioning networks requires specialists versed in both Bluetooth mesh configuration and UWB time synchronization.
- Legacy Wi-Fi Integration Friction:Existing Cisco and Aruba access point estates must undergo firmware and antenna upgrades to support location analytics without coverage degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor LBS Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $92.61 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, RFID, Ultra-Wideband Application: Retail Navigation, Venue Management, Asset Tracking, Emergency Response End User: Retailers, Healthcare Facilities, Airports, Educational Institutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Microsoft Corporation, CenTrak, Inc., Apple Inc., CommScope, Inc., HERE Global B.V., Cisco Systems, Inc., Qualcomm Incorporated, IndoorAtlas Ltd., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor LBS Market Strategic Shifts & Innovations
Technological convergence is compressing the trade-off between positioning precision and deployment cost. Three forces are actively restructuring competitive positioning and buyer expectations across venue types.
Ultra-wideband chipsets are electrifying the high-precision segment by enabling time-of-flight measurement between anchors and tags without line-of-sight requirements. Automotive suppliers and industrial safety system integrators are adopting UWB for collision avoidance at pace, compressing the viable market for camera-based alternatives in enclosed logistics environments.
The EU AI Act imposes transparency requirements on automated location analytics in public spaces, compelling venue operators to disclose data collection practices. Retail and transportation hubs across Germany and France must now obtain explicit consent for passenger movement tracking, forcing vendors to architect anonymization layers into cloud platforms.
Buyers are unbundling location intelligence from network hardware procurement, shifting toward software-only contracts that run across mixed-vendor access point estates. Enterprise facility managers in the United States now evaluate positioning platforms on API interoperability rather than single-vendor stack coherence, compressing switching costs and accelerating vendor rotation.
Indoor LBS Market Segmentation
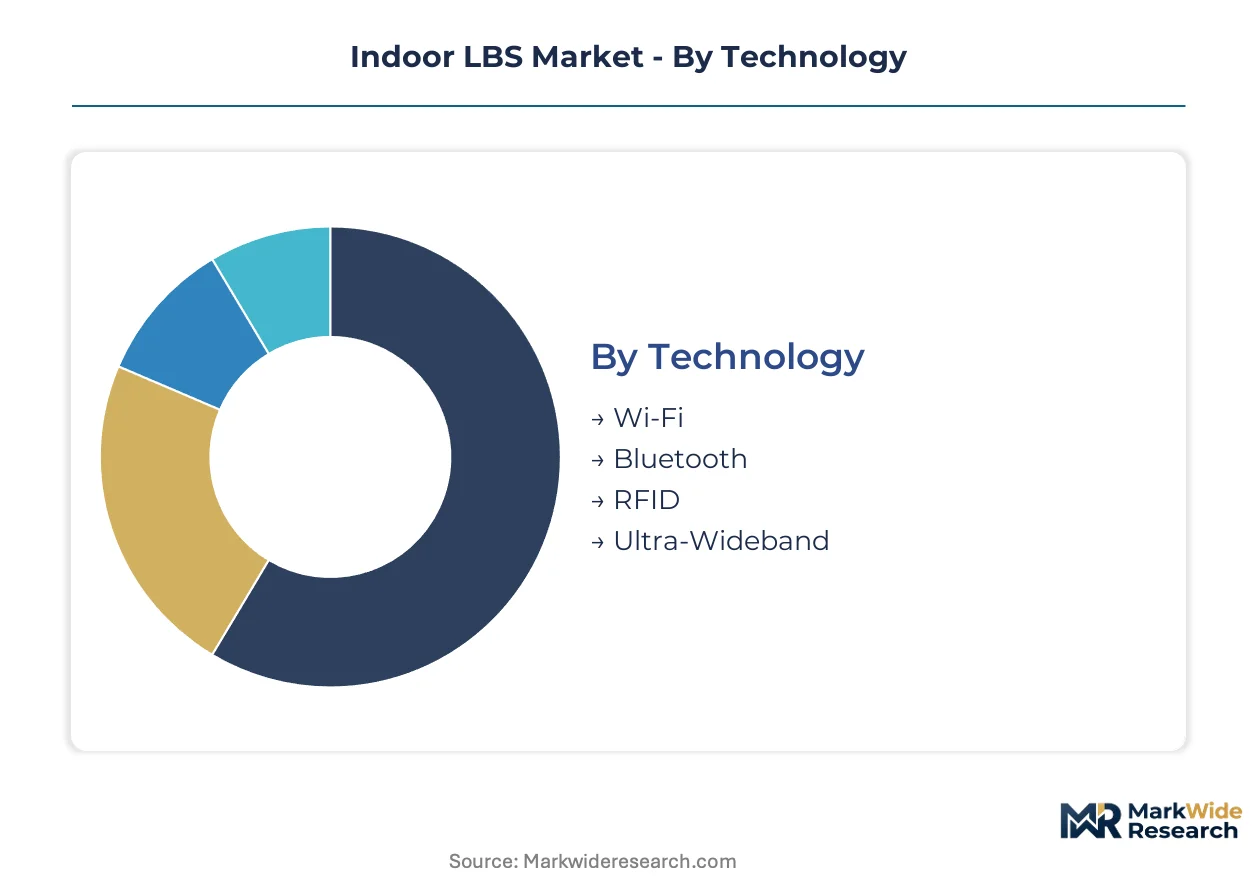
Indoor LBS deployments fragment sharply across technology cost tiers, regulatory compliance thresholds, and operational integration requirements. Buyers select positioning architectures based on precision mandates, legacy infrastructure compatibility, and subscription versus capital expenditure preferences.
Technology:
FCC emergency call accuracy mandates and EU AI Act transparency requirements impose divergent certification burdens across positioning technologies, with public safety applications demanding stricter validation than commercial wayfinding.
- Wi-Fi:Leverages existing 802.11 access point infrastructure for room-level positioning through received signal strength indicators. Retailers in the United States retrofit Wi-Fi location analytics into Cisco and Aruba estates to minimize hardware duplication. FCC indoor location rules for wireless 911 calls accelerate firmware upgrades in high-occupancy venues.
- Bluetooth:Low-energy beacon networks enable proximity detection at sub-meter accuracy using smartphone-native receivers. Airports across Germany and France deploy Bluetooth mesh for passenger wayfinding under GDPR and EU AI Act consent frameworks. Passive beacon economics eliminate tag procurement costs for visitor-facing applications.
- RFID:Passive ultra-high-frequency tags support inventory tracking in controlled logistics environments where line-of-sight scanning suffices. Healthcare facilities in Saudi Arabia utilize RFID for medical equipment audits under SFDA traceability guidelines.
- Ultra-Wideband:Time-of-flight measurement between anchors and tags achieves centimeter precision for collision avoidance. Industrial safety integrators in Japan adopt UWB under METI factory automation standards despite active tag cost premiums.
Wi-Fi sits at the top of the volume ranking, with Ultra-Wideband climbing the fastest.
Application:
Cost tier stratification separates high-precision safety mandates from consumer convenience deployments, with emergency response and asset tracking commanding premium positioning hardware.
- Retail Navigation:Beacon-powered wayfinding guides shoppers to product locations while capturing dwell-time analytics. French retailers anonymize movement data under CNIL guidelines to comply with EU AI Act transparency requirements.
- Venue Management:Integrated positioning optimizes crowd flow and security resource allocation in entertainment complexes. Stadium operators in the United Kingdom deploy hybrid Wi-Fi-Bluetooth systems for attendee experience and safety compliance.
- Asset Tracking:Real-time location systems reduce equipment search time in hospitals and manufacturing plants. Healthcare facilities in South Korea implement RFID-UWB fusion under MFDS medical device traceability rules.
- Emergency Response:FCC-mandated indoor location accuracy for wireless 911 calls drives certified infrastructure deployment. Carriers and building managers in the United States upgrade legacy systems to meet z-axis positioning requirements.
Asset Tracking generates the highest average contract value, with Emergency Response expanding most quickly under regulatory compulsion.
End User:
Customer type determines procurement complexity, with healthcare and aviation sectors imposing stringent validation protocols compared to retail and education.
- Retailers:Department stores and grocery chains prioritize Bluetooth beacon economics for customer analytics and proximity marketing. Deployment favors cloud-based SaaS models to avoid capital-intensive server installations.
- Healthcare Facilities:Hospitals demand real-time location systems for patient flow optimization and equipment tracking. HIPAA compliance in the United States and GDPR in Europe constrain data residency and anonymization architectures.
- Airports:Passenger terminals integrate multi-technology positioning for wayfinding, baggage tracking, and security coordination. Managed services contracts predominate given operational complexity and 24/7 uptime requirements.
- Educational Institutions:Universities deploy indoor positioning for campus navigation and emergency alert systems. Budget constraints favor Wi-Fi-based solutions leveraging existing network infrastructure.
Healthcare Facilities command the steepest pricing premiums, with Airports adopting the most complex multi-vendor integration requirements.
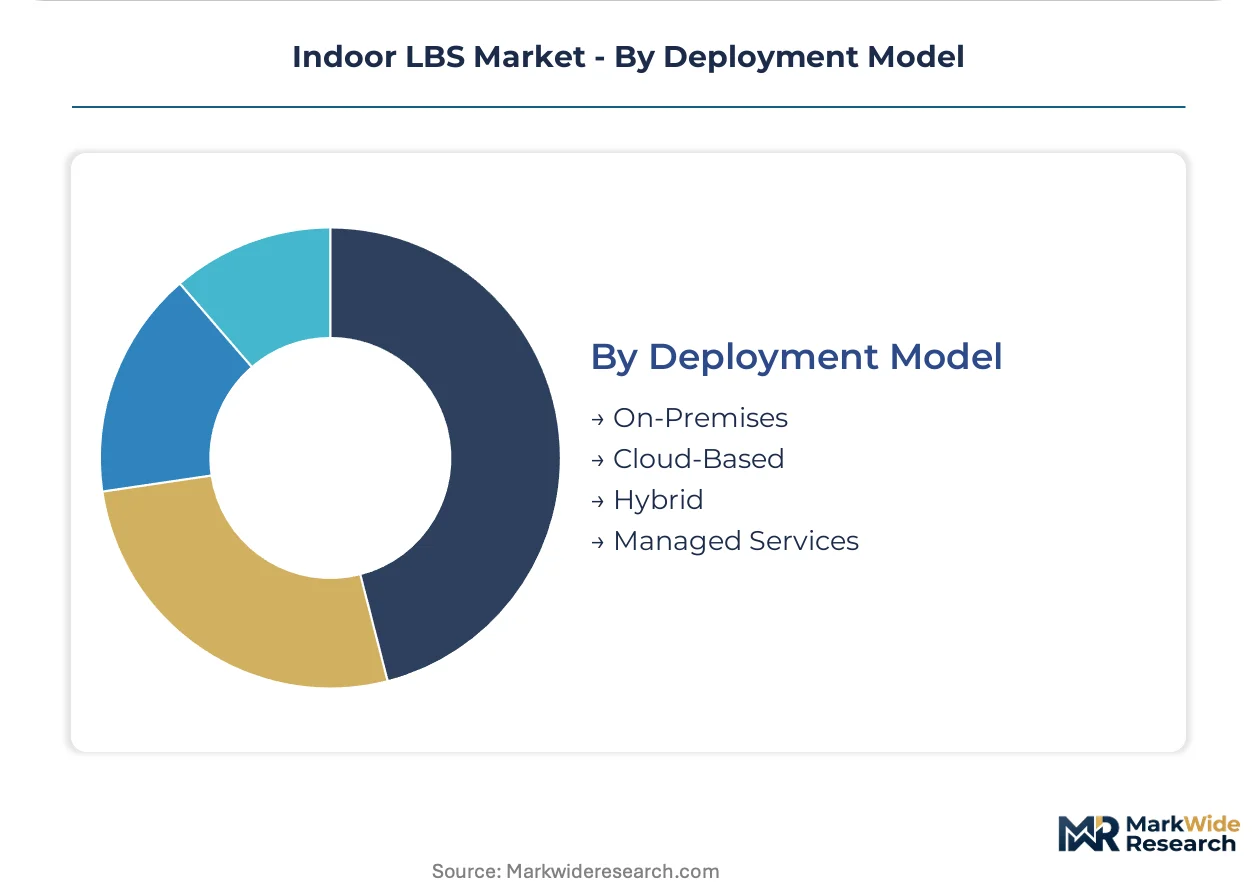
Deployment Model:
Margin structure varies dramatically across delivery mechanisms, with managed services capturing recurring revenue streams and on-premises installations facing compression from cloud migration.
- On-Premises:Dedicated server installations within facility data centers satisfy stringent data sovereignty requirements. Government and defense applications in Switzerland mandate on-premises positioning under Swissmedic and federal data protection rules.
- Cloud-Based:Subscription access to location analytics platforms eliminates hardware procurement and maintenance burdens. Retail and hospitality sectors in Australia prefer cloud delivery under TGA-aligned privacy frameworks for consumer data.
- Hybrid:Edge computing nodes process positioning data locally while cloud platforms handle analytics and visualization. Manufacturing plants in Germany deploy hybrid architectures to balance latency-sensitive collision avoidance with centralized reporting.
- Managed Services:Outsourced operation of positioning infrastructure including hardware maintenance, software updates, and helpdesk support. Airports and healthcare networks in Canada contract managed services under Health Canada privacy and safety oversight.
Cloud-Based deployment dominates new contract signings, with Hybrid architectures gaining share fastest among industrial safety applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping deployment patterns as venue operators migrate cloud workloads toward jurisdictions with lighter consent frameworks while maintaining FCC-compliant infrastructure in the United States for emergency call accuracy.
United States
FCC mandates for z-axis positioning in wireless 911 calls drive certified infrastructure upgrades across high-occupancy venues. Carriers and building managers face compliance deadlines that compress procurement cycles for hybrid Wi-Fi-UWB systems. Hospital networks in Texas and California deploy real-time location systems under HIPAA constraints for patient flow optimization.
Germany
Industrial collision avoidance applications dominate demand as METI-aligned factory automation standards spread through automotive supplier parks. The EU AI Act imposes transparency requirements on automated location analytics in public spaces. Manufacturing plants in Bavaria deploy hybrid edge-cloud architectures to balance latency-sensitive safety systems with centralized reporting.
Japan
METI factory automation standards accelerate ultra-wideband adoption for forklift navigation and autonomous mobile robot coordination. Healthcare facilities implement RFID-UWB fusion under PMDA medical device traceability guidelines. Industrial clusters in Aichi Prefecture and Osaka-Kobe corridor lead deployment density for centimeter-precision measurement systems.
South Korea
MFDS medical device traceability rules compel hospital systems to implement real-time location systems for equipment tracking. Smart building convergence integrates indoor positioning with HVAC and lighting controls in Seoul Capital Area commercial towers. Manufacturing plants in Busan-Ulsan corridor adopt UWB for industrial safety applications.
United Kingdom
Stadium operators deploy hybrid Wi-Fi-Bluetooth systems for attendee experience and safety compliance under UK regulator guidance. GDPR constraints shape cloud platform architectures for retail and transportation hub deployments. London and Manchester clusters concentrate managed services contracts for complex multi-vendor integration requirements.
Indoor LBS Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms capturing recurring revenue while hardware-anchored vendors defend installed-base positions. The vendor base concentrates around three strategic archetypes: hyperscale cloud providers bundling location services into enterprise suites, network infrastructure incumbents integrating analytics into access point estates, and precision-technology specialists commanding premium pricing for ultra-wideband chipsets. Dominant competitive moves include strategic partnerships between software platforms and hardware OEMs, plus vertical integration into edge computing nodes for latency-sensitive industrial applications.
Within the hyperscale tier, Microsoft Corporation and Google LLC anchor cloud-native delivery models that reduce customer capital expenditure. Cisco Systems, Inc. and Qualcomm Incorporated occupy positions bridging network infrastructure and precision measurement domains. These four exemplify how competitive positioning increasingly depends on API interoperability across mixed-vendor estates rather than single-stack coherence.
| Leading Market Players |
|---|
| Microsoft Corporation |
| CenTrak, Inc. |
| Apple Inc. |
| CommScope, Inc. |
| HERE Global B.V. |
| Cisco Systems, Inc. |
| Qualcomm Incorporated |
| IndoorAtlas Ltd. |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Ultra-wideband chipset fabrication costs cascade through three distinct pricing tiers as Taiwan Semiconductor Manufacturing Company wafers move from precision anchor manufacturers to system integrators serving FCC-mandated emergency response deployments.
Pricing Analysis
Distributor margins compress the economics of active UWB tag procurement, forcing buyers into direct OEM relationships for volume deployments above ten thousand units. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified emergency systems from industrial safety applications and consumer-facing wayfinding beacons. Cost compression in the Bluetooth beacon tier intensifies because smartphone-native receiver penetration eliminates tag procurement entirely. Healthcare facilities demonstrate the lowest price sensitivity due to HIPAA compliance premiums, while educational institutions face acute budget constraints favoring Wi-Fi retrofit solutions.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs to North American and European integration facilities amplifies total cost of ownership for time-sensitive UWB deployments. Component sourcing centers on Taiwan for precision chipsets, South Korea for RF front-end modules, and Japan for industrial-grade sensors. Raw material dependencies span silicon wafers, lithium polymer cells for active tags, and specialized antenna substrates. Single-source vulnerability concentrates in TSMC's advanced node capacity for UWB transceivers. Distribution runs through systems integrators with certified installation capabilities rather than commodity electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in cloud platform delivery, where EU AI Act compliance costs in Germany and France exceed United States infrastructure deployment by factor margins that SaaS vendors can capture through jurisdictional workload placement.
For Market Incumbents: Cement hybrid deployment dominance by acquiring edge-computing specialists with METI-certified industrial safety credentials. Fortify API interoperability layers against vendor-locked challengers. Backward integration into UWB anchor manufacturing insulates margin position from Taiwan foundry allocation constraints. For New Entrants and Emerging Players: Mid-sized hospital networks in the United States represent the most penetrable buyer archetype, underserved by Cisco-Aruba estate incumbents yet requiring HIPAA-compliant asset tracking. Target this segment through managed services contracts that bundle FCC-certified infrastructure with subscription analytics. Emphasize rapid deployment timelines against legacy system upgrade friction. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native location platforms because buyer procurement is shifting toward software-only contracts that compress switching costs and accelerate vendor rotation. Platform consolidation captures recurring revenue streams while eliminating redundant R&D spend across overlapping Bluetooth-UWB fusion stacks. Watch for inflection when FCC extends z-axis mandates to multi-floor residential structures.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | Microsoft Azure and Google Cloud platforms compete on mixed-vendor estate compatibility rather than single-stack coherence. |
| Edge Computing Node Deployment | German manufacturing plants balance latency-sensitive collision avoidance with centralized reporting through hybrid architectures. |
| Regulatory Compliance Bundling | FCC-certified infrastructure vendors capture premium pricing from carriers facing wireless 911 accuracy deadlines. |
| Managed Services Expansion | Canadian airports and healthcare networks outsource 24/7 positioning operations under Health Canada oversight. |
| Vertical Application Specialization | Healthcare asset tracking commands steepest pricing premiums due to HIPAA data residency requirements. |
Research Approach
Multiple input streams — primary interviews with facility managers and network engineers, secondary validation through FCC filing databases and METI factory automation standards, plus customs data on UWB chipset imports — were reconciled against hyperscaler capex disclosures and hospital procurement records. Bottom-up triangulation across deployment model preferences and top-down reconciliation with regulatory mandate timelines anchored volume estimates. Primary fieldwork encompassed conversations with Cisco and Aruba estate administrators, healthcare biomedical engineers, and industrial safety integrators in Aichi Prefecture.
Data-stream reconciliation applied across the analysis window modeled technology segmentation by precision tier and regulatory compliance burden, application segmentation by cost sensitivity and integration complexity, and end-user segmentation by procurement authority and validation protocol stringency. CAGRs derived from regression against smart building investment cycles and public safety mandate implementation schedules. Forecast inputs incorporated Bluetooth-UWB protocol interoperability evolution and cloud subscription migration velocity.
Underlying measurement precision varies by segment; emergency response and healthcare asset tracking carry tighter precision than retail wayfinding due to regulatory certification requirements. Forecasts reflect assumptions about FCC rulemaking continuity and EU AI Act enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rugged Tablet Market
Others
Server Market
Others
Healthcare Bioconvergence Market
Others
China Packaging Primers Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Electric Pallet Jack Truck Market
Others
High Voltage Measuring Equipment Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Fibert Market
Others
8K Technology Market
Others
Telecom Transformers Market
Others
Global Smartphone ODM Market
Others
Middle East Smart Home Market
Others
Global Drug Discovery Informatics Market
Others
North America Enterprise Video Market
Others
North America Medical Simulation Market