
 Magnet Wire Market | 2026-2036
Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Magnet Wire Market Intelligence
The rise of electric vehicle manufacturers as a primary buyer archetype is redrawing the competitive positioning for magnet wire suppliers. Sumitomo Electric Industries, Ltd. leverages its extensive R&D in materials science to serve this high-specification automotive demand. In parallel, Tongling Jingda Special Magnet Wire Co., Ltd. specializes in high-volume production, anchoring its position within China's vast industrial ecosystem. Superior Essex Inc. competes through its global manufacturing footprint and diverse product portfolio.
Magnet wire consists of a solid copper or aluminum conductor coated with a thin, durable layer of insulation. This insulation, often a polymer film applied in multiple coats, allows the wire to be tightly wound into coils without short-circuiting. Its primary function is to generate electromagnetic fields within motors, transformers, and inductors. Copper-based enamelled wire continues to dominate the market, while the motor end-user segment represents the fastest-growing application area, driven by industrial automation and vehicle electrification.
Product specifications are heavily influenced by international standards from the IEC, which define performance classes and testing methods. Concurrently, material composition is governed by regulations like the EU's RoHS directive, while market access in China requires adherence to national GB standards. For suppliers, the strategic imperative is to balance investment between capacity for high-thermal-class automotive wires and the cost-competitive industrial-grade segment.
Market Dynamics
The central dynamic shaping the magnet wire market is the technical and investment divergence between high-specification automotive wires and the cost-sensitive industrial-grade segment, driven by vehicle electrification and stringent regulatory compliance demands from bodies like the IEC.
Growth Catalysts
- Vehicle Electrification:Demand from the automotive sector for high-efficiency electric motors in EVs, hybrids, and auxiliary systems acts as a primary market accelerator, particularly for high-thermal-class rectangular wires.
- Industrial Automation:The expansion of factory automation and robotics, especially within China's manufacturing ecosystem, increases consumption of enamelled wire for servomotors, actuators, and control system transformers.
- Renewable Energy Infrastructure:Investment in wind turbine generators and solar power inverters creates consistent demand for large-cross-section magnet wire, supporting grid modernization efforts globally.
Market Restraints
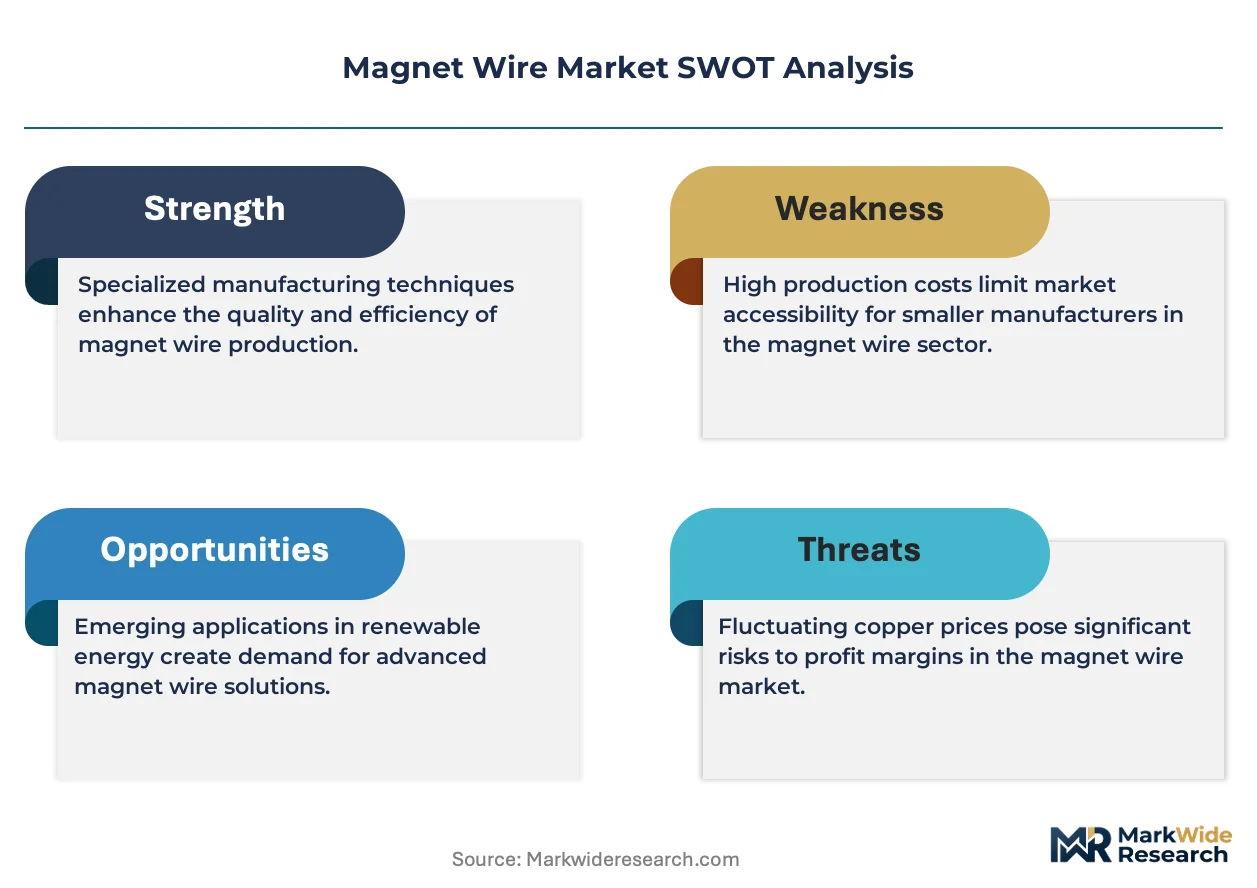
- Copper Price Volatility:As the primary conductor material, copper's significant price fluctuations directly impact magnet wire production costs, creating margin pressure and complicating long-term supply contracts.
- Technical Trade-offs:Increasing insulation thermal class often involves thicker polymer layers, which can reduce the winding space factor and slightly compromise the power density of compact electric motors.
- Substitution Threat from Litz Wire:In high-frequency applications, such as EV charging systems and inverters, Litz wire offers superior performance in mitigating skin effect, posing a substitution risk for solid-conductor magnet wire.
Strategic Opportunities
- Aerospace and Defense Systems:Developing specialized, radiation-resistant, and lightweight aluminum magnet wires opens opportunities in avionics, satellite systems, and military-grade actuators where weight reduction is critical.
- Medical Device Miniaturization:Ultra-fine magnet wire enables the development of more compact and precise coils for medical imaging equipment, implantable devices, and diagnostic sensors.
- High-Speed Rail Networks:The global expansion of high-speed rail projects, particularly in Asia and Europe, presents a significant opportunity for large-volume contracts for traction motor and transformer windings.
Industry Challenges
- Capital-Intensive Production:Establishing manufacturing lines for high-quality, zero-defect automotive-grade magnet wire requires substantial capital investment in precision enamelling machines and automated quality control systems.
- Complex Certification Pathways:Suppliers face long and costly validation processes to meet multiple standards, including IEC performance classes, automotive OEM-specific requirements, and regional chemical regulations like the EU's RoHS.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnet Wire Market |
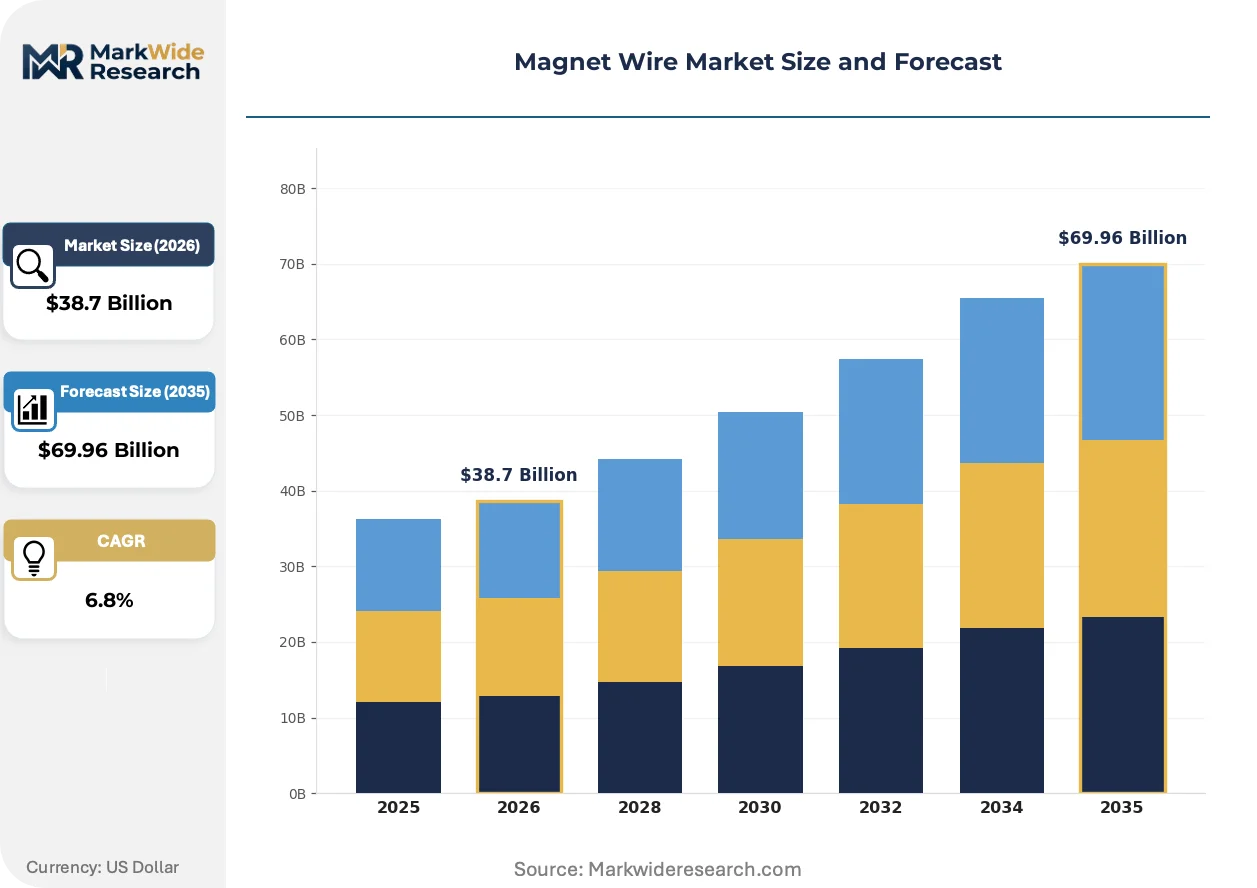
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enamelled Wire, Paper Covered Wire, Polymer Insulated Wire, Fiberglass Insulated Wire End User: Transformers, Motors, Generators, Inductors Material: Copper, Aluminum, Alloy, Others Application: Electrical Equipment, Automotive, Consumer Electronics, Industrial Applications |
| Companies Covered | Sumitomo Electric Industries, Ltd., LS Cable & System Ltd., Furukawa Electric Co., Ltd., Hitachi Metals Ltd., Tongling Jingda Special Magnet Wire Co., Ltd., Superior Essex Inc., Fujikura Ltd., IRCE S.p.A, REA Magnet Wire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnet Wire Market Strategic Shifts & Innovations
Material science advancements are creating a clear performance hierarchy in the market. This evolution is forcing suppliers to choose between specializing in high-performance, application-specific solutions or competing on volume and cost in the standardized industrial segment.
Advanced insulation polymers, particularly modified polyimide and PAI (Polyamide-imide), provide superior thermal resistance and dielectric strength. Automotive and aerospace end-users are rapidly adopting these materials to build more power-dense and reliable motors that operate at higher temperatures. The development of these high-thermal-class materials is bifurcating the supply base between specialists with advanced polymer chemistry expertise and generalists serving industrial-grade needs.
European Union regulations, specifically the RoHS directive, are setting global benchmarks for material composition. The directive restricts the use of certain hazardous substances in insulation formulas, compelling a shift toward lead-free and halogen-free polymers. This regulatory pressure most heavily impacts the high-performance segment, where suppliers must re-qualify new materials with automotive OEMs without compromising thermal endurance or mechanical durability.
A shift toward co-development partnerships is altering traditional purchasing models for high-value applications. Instead of selecting from a catalog, large electric vehicle manufacturers are engaging directly with wire producers to design custom conductor geometries and insulation properties for specific motor platforms. This collaborative procurement model is most visible within the highly integrated automotive supply chains of Germany and China, prioritizing performance optimization over standardized components.
Magnet Wire Market Segmentation
The magnet wire market exhibits diverse segmentation reflecting varied applications and performance requirements. Understanding these categories helps suppliers align product offerings with specific industry needs. This segmentation reveals how material science and end-user demands shape market dynamics.
Product Type:
The distribution channels for magnet wire product types vary significantly, reflecting their specific performance characteristics and target industries.
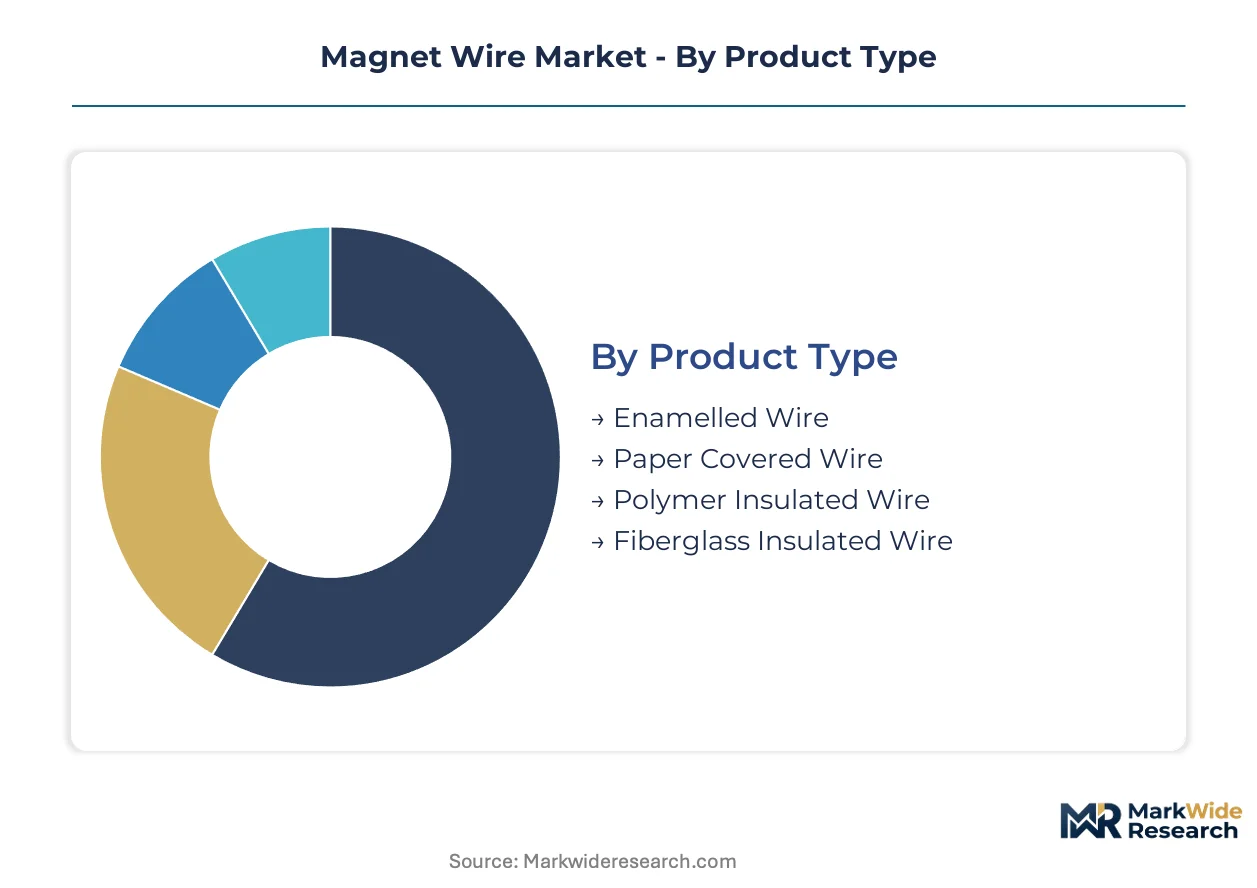
- Enamelled Wire:Solid conductor with a thin, durable polymer film insulation applied in multiple coats. Demand concentrates in the automotive sector for high-efficiency EV motors, driven by the need for compact designs and thermal endurance.
- Polymer Insulated Wire:Features a thicker, often multi-layered, polymer insulation for enhanced dielectric strength and thermal resistance. This type sees concentrated demand in high-voltage industrial applications and specialized aerospace systems, driven by extreme operating conditions.
- Paper Covered Wire:Utilizes cellulose paper as insulation, offering good dielectric properties for large power transformers.
- Fiberglass Insulated Wire:Employs fiberglass braiding, providing high thermal stability for heavy-duty industrial motors and generators.
By volume, Enamelled Wire leads the product type segment. By growth pace, Polymer Insulated Wire is ahead, particularly in high-performance applications.
End User:
The end-user segmentation highlights the primary functional areas where magnet wire is integrated, indicating distinct performance requirements for each application.
- Motors:Converts electrical energy into mechanical energy, utilizing magnet wire to form windings that generate magnetic fields. Demand concentrates in the automotive sector for electric vehicle propulsion and industrial automation systems, spurred by electrification and efficiency mandates.
- Transformers:Changes alternating current voltage levels through electromagnetic induction, relying on magnet wire coils for primary and secondary windings. This segment sees significant demand in grid infrastructure projects and renewable energy installations, driven by global power transmission needs.
- Generators:Produces electrical energy from mechanical energy, requiring robust magnet wire for stator and rotor windings.
- Inductors:Stores energy in a magnetic field, using magnet wire coils in power supplies and signal processing circuits.
Motors exhibit the steepest expansion trajectory due to vehicle electrification. Transformers continue to represent a substantial portion of overall consumption.
Material:
Material choice for magnet wire often reflects a balance between conductivity, mechanical properties, and cost, creating distinct tiers within the market.
- Copper:Offers high electrical conductivity and excellent mechanical strength, making it the predominant conductor material for most magnet wire applications. Demand concentrates across industrial motors and automotive components, driven by performance and reliability requirements.
- Aluminum:Provides a lighter and more cost-effective alternative to copper, particularly for larger cross-sections where weight is a concern. This material sees concentrated demand in power transformers and some industrial motors, influenced by raw material price volatility.
- Alloy:Includes various metallic combinations designed for specific properties like higher strength or temperature resistance in niche applications.
- Others:Encompasses less common conductors or experimental materials for specialized high-performance or research-based uses.
Copper remains the foundational material for magnet wire production. Aluminum gains share fastest in cost-sensitive, large-volume applications.
Application:
The application segments categorize magnet wire usage by the specific industry or product type, revealing distinct customer profiles and regulatory environments.
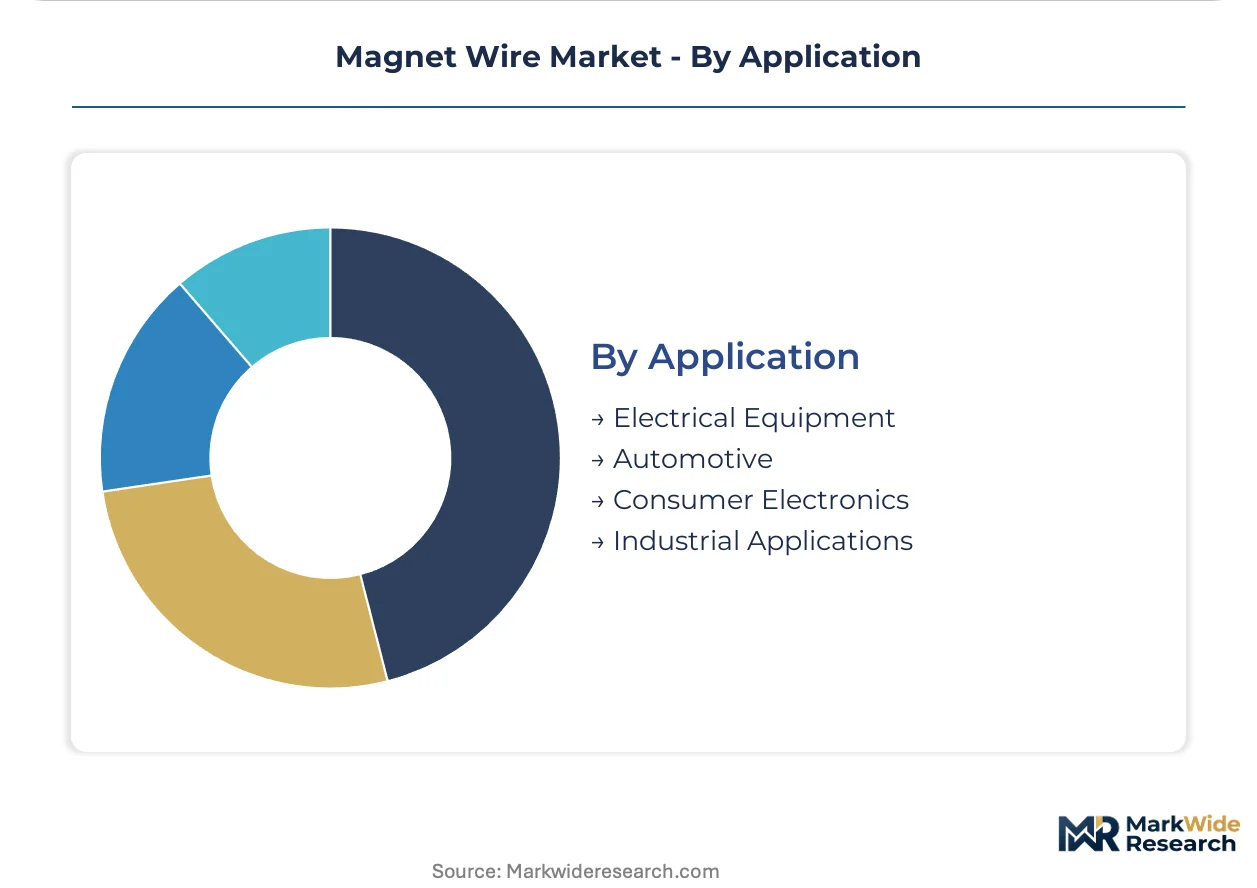
- Automotive:Integrates magnet wire into electric vehicle motors, charging systems, and various auxiliary components, demanding high thermal class and robust performance. Demand concentrates heavily in Germany and China, driven by stringent OEM specifications and production volumes.
- Industrial Applications:Utilizes magnet wire in a wide array of machinery, including factory automation systems, robotics, and heavy-duty motors. This segment sees concentrated demand in manufacturing hubs globally, influenced by the ongoing expansion of automation technologies.
- Electrical Equipment:Covers a broad range of devices like power supplies, lighting ballasts, and household appliances, requiring diverse magnet wire specifications.
- Consumer Electronics:Incorporates fine gauge magnet wire into compact devices such as smartphones, laptops, and audio equipment for coils and transformers.
Automotive applications are climbing the fastest, propelled by vehicle electrification. Industrial Applications continue to anchor significant market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated automotive supply chains in key manufacturing regions underwrite global magnet wire demand. Significant investments in renewable energy infrastructure also drive consumption across diverse geographies. These factors collectively shape regional market dynamics for specialized wire products.
China
Demand for magnet wire in China accelerates due to extensive electric vehicle manufacturing and industrial automation initiatives. Adherence to national GB standards is critical for market access and product qualification. Industrial clusters in the Yangtze River Delta concentrate significant production and consumption of enamelled wire.
Germany
The German automotive sector, particularly for electric vehicles, drives demand for high-thermal-class magnet wire. Compliance with the EU's RoHS directive is mandatory for insulation materials used in components sold here. Manufacturing hubs in Bavaria and Baden-Württemberg lead in specialized wire production for advanced industrial machinery.
United States
The United States sees consistent demand for magnet wire from aerospace and defense systems, alongside renewable energy infrastructure projects. The Inflation Reduction Act (IRA) influences investment in domestic manufacturing capabilities and supply chains. Major industrial centers in the Midwest and Southeast consume significant volumes for motors and transformers.
Japan
Japanese automotive manufacturers and robotics industries generate substantial demand for fine-gauge and high-performance magnet wire. Products must meet stringent JIS standards for quality and reliability in critical applications. The Kanto region, encompassing Tokyo, hosts numerous specialized wire producers and advanced electronics manufacturers.
India
India's expanding industrial automation sector and power infrastructure projects contribute to rising magnet wire consumption. The PLI scheme encourages domestic manufacturing of electrical components, including magnet wire. Maharashtra and Gujarat are key manufacturing hubs for industrial motors and transformers.
Magnet Wire Market Key Industry Players
Listed leaders compete with private specialists across material science innovation and production scale within the magnet wire market. The market structure is tiered, featuring global players alongside niche providers focused on specific applications. Strategic archetypes include R&D-intensive innovators, high-volume manufacturers, and regionally focused specialists. Capacity expansion, strategic partnerships, and portfolio diversification remain dominant competitive moves for market participants.
Global industrial conglomerates like Sumitomo Electric Industries, Ltd. represent the R&D-intensive archetype, leveraging extensive materials science expertise for high-specification automotive demand. Tongling Jingda Special Magnet Wire Co., Ltd. exemplifies the high-volume production model, anchoring its position within China's vast industrial ecosystem for industrial-grade segments. Meanwhile, Superior Essex Inc., an international corporation, occupies a position characterized by a global manufacturing footprint and diverse product portfolio across various end-user segments, balancing cost and performance.
| Leading Market Players |
|---|
| Sumitomo Electric Industries, Ltd. |
| LS Cable & System Ltd. |
| Furukawa Electric Co., Ltd. |
| Hitachi Metals Ltd. |
| Tongling Jingda Special Magnet Wire Co., Ltd. |
| Superior Essex Inc. |
| Fujikura Ltd. |
| IRCE S.p.A |
| REA Magnet Wire |
| Others |
Cost & Logistics Intelligence
The EU's RoHS directive gates magnet wire supply qualification and simultaneously influences pricing differentiation for high-performance insulation materials. This regulatory framework mandates compliance for materials, directly impacting production costs and market access, especially for European automotive OEMs.
Pricing Analysis
Volume-discount tiering structures dominate magnet wire pricing, reflecting economies of scale in production. Price differentiation stems from insulation thermal class and specific OEM certifications. Pricing pressure stems from copper price volatility, impacting industrial-grade segments significantly. Automotive manufacturers are generally the least price-sensitive due to stringent performance requirements, while consumer electronics producers exhibit higher price sensitivity.
Supply Chain Analysis
China anchors magnet wire production, particularly for industrial-grade and high-volume segments, leveraging its vast manufacturing infrastructure. Raw material dependencies center on copper and specialized polymer resins from global suppliers. Single-source vulnerability for high-thermal-class insulation polymers represents a structural risk. Distribution runs through a mix of direct sales to large OEMs and regional distributors serving smaller industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle electrification presents a high-growth disruption for the magnet wire market, driven by the shift towards high-efficiency electric motors.
For Market Incumbents:Compound existing R&D investments in advanced insulation polymers to maintain leadership in high-thermal-class automotive wires. Strategic partnerships with EV manufacturers can secure long-term supply contracts and co-development opportunities. Consolidate market share in industrial-grade segments through cost optimization and regional capacity expansion. The substitution threat from Litz wire in high-frequency applications requires continuous material innovation.
For New Entrants and Emerging Players:Anchor in niche applications like medical device miniaturization or specialized aerospace systems where performance outweighs volume. The automotive auxiliary systems segment offers a penetrable entry point for fine-gauge wires. Focus on developing unique insulation chemistries that meet specific performance gaps, leveraging agile R&D. Go-to-market strategies should emphasize performance validation and technical support for emerging OEMs.
For Investors and Strategic Acquirers:The Inflation Reduction Act reshapes the acquisition landscape, favoring companies with domestic manufacturing capabilities in the United States. Invest in vertically integrated mid-cap specialists possessing proprietary insulation technology or strong relationships with automotive Tier 1 suppliers. Long-term viability hinges on companies capable of navigating complex regulatory certifications and copper price volatility. A signal to watch is the increasing adoption rate of 800V EV architectures, demanding even higher thermal performance wires.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in High-Thermal-Class Insulation R&D | Enables power-dense EV motors and aerospace components, meeting stringent performance standards. |
| Expand Automotive-Grade Production Capacity | Addresses the accelerating demand from global electric vehicle manufacturing hubs in China and Germany. |
| Form Co-Development Partnerships with OEMs | Secures long-term supply agreements and custom wire specifications for next-generation vehicle platforms. |
| Diversify into Lightweight Aluminum Wires | Opens opportunities in aerospace and defense systems, where weight reduction is a critical design factor. |
| Optimize Copper Procurement Strategies | Mitigates margin pressure from volatile raw material costs, enhancing profitability in industrial segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, government publications, and company financial statements. This study involved interviews with automotive OEM engineers, magnet wire R&D directors, procurement managers, and specialized polymer suppliers. Bottom-up and top-down triangulation ensured robust market size and forecast validation.
Segmentation dimensions modeled include product type, end-user, material, application, and key geographic regions across the analysis window. Quantitative analysis derived compound annual growth rates by assessing historical trends and projected technological advancements. Key forecast inputs included electric vehicle production volumes and industrial automation investment levels.
Material uncertainties — including unforeseen shifts in raw material prices or new regulatory mandates — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Magnet Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Rare Earth Magnet Market