
 Global Myelodysplastic Syndrome (MDS) Drugs Market | 2026-2036
Global Myelodysplastic Syndrome (MDS) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Myelodysplastic Syndrome (MDS) Drugs Market Foresight
Market Context with Strategic Players
Oncology clinics and specialized hematology centers is rebalancing toward high-risk MDS and therapy-related subtypes as clinicians prioritize curative-intent protocols. Bristol-Myers Squibb anchors its position through deep R&D investment in hypomethylating agent combinations. Amgen Inc. differentiates via growth factor portfolios that address transfusion-dependent anemia. Takeda Pharmaceutical Company Limited leverages its global hematology franchise to control distribution in Asian and European tertiary centers.
Technical Definition and Structural Segments
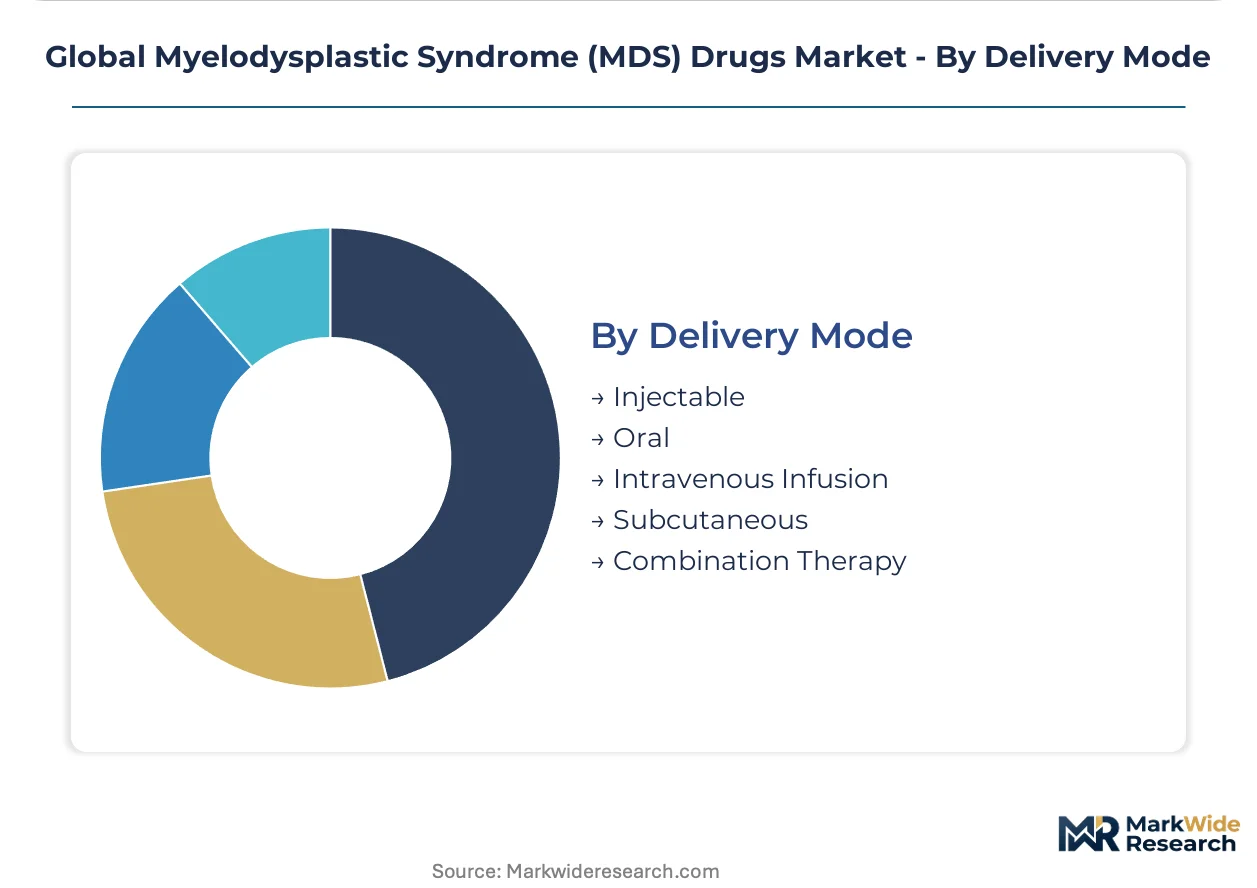
Myelodysplastic Syndrome (MDS) drugs comprise pharmaceutical agents targeting clonal hematopoietic stem cell disorders characterized by peripheral cytopenias, dysplasia in one or more myeloid lineages, and progressive risk of transformation to acute myeloid leukemia; these therapeutics function to modify disease biology, reduce transfusion burden, or delay disease progression in adult patients. Hypomethylating agents occupy the largest revenue pool given their established efficacy in higher-risk disease categories, while immunomodulatory drugs represent the fastest-expanding segment driven by oral administration advantages and expanding labels into lower-risk populations. Injectable delivery modes dominate hospital-based administration, though subcutaneous formulations are gaining traction in ambulatory settings where patient convenience and cost containment intersect.
Regulatory Framework and Forward Outlook
The FDA maintains stringent oncology drug evaluation standards through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use shapes European access through centralized marketing authorization requirements; both frameworks elevate clinical trial design standards and post-market surveillance obligations for MDS developers. Japan's PMDA imposes additional pharmacogenomic data requirements that filter market entry for foreign sponsors. Stakeholders must monitor evolving biomarker-driven trial endpoints and companion diagnostic co-development mandates that will determine which pipeline assets secure priority review status.
Market Dynamics
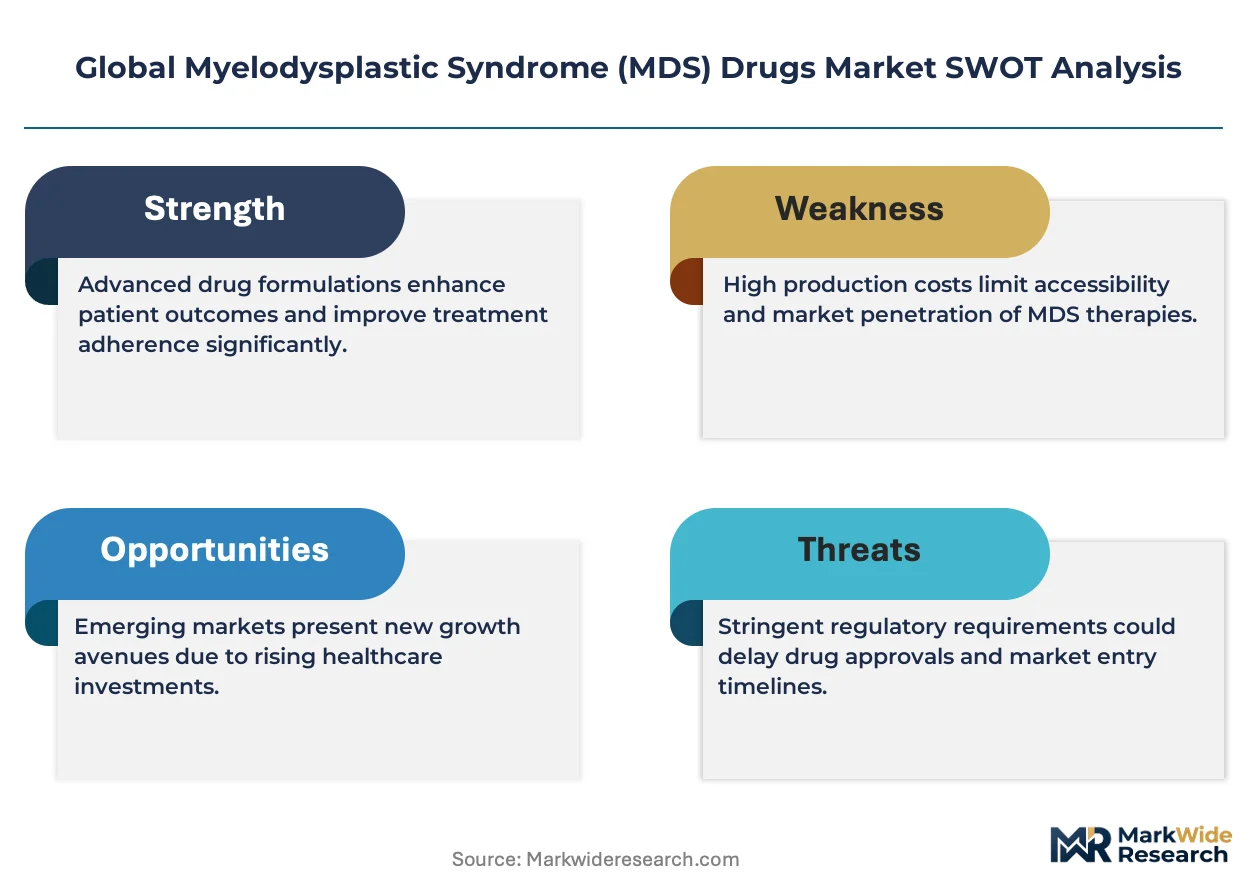
The FDA's accelerated approval pathways for oncology drugs are compressing commercialization timelines while simultaneously elevating post-market evidence requirements, forcing developers to front-load real-world data collection infrastructure before launch.
Growth Catalysts
- Biomarker-driven trial endpoints:The FDA's evolving guidance on surrogate endpoints enables faster regulatory decisions for MDS therapies targeting specific genetic subtypes, reducing time-to-market for precision candidates.
- Hematology center expansion:Specialized treatment infrastructure in the United States, Germany, and Japan is scaling capacity to absorb novel hypomethylating agent combinations and immunomodulatory protocols.
- Subcutaneous formulation development:Ambulatory administration technologies are shifting care delivery from infusion centers to outpatient settings, aligning with payer cost-containment priorities and patient convenience demands.
Market Restraints
- Companion diagnostic co-development mandates:The FDA and EMA now require parallel diagnostic validation, doubling development complexity and extending timelines for biomarker-selected therapies.
- Azacitidine supply concentration:API manufacturing for cornerstone hypomethylating agents clusters among a limited supplier base in India and China, exposing formulators to geopolitical and quality audit risks.
- Transfusion infrastructure dependency:MDS drug efficacy metrics tie to transfusion burden reduction, making market penetration contingent on hospital blood bank capacity rather than standalone pharmaceutical value.
Strategic Opportunities
- Lower-risk MDS label expansion:Immunomodulatory drugs with established higher-risk efficacy profiles can pursue regulatory filings for transfusion-dependent lower-risk populations, unlocking prescriber segments currently managed with supportive care alone.
- Japan's pharmacogenomic data requirements:The PMDA's emphasis on East Asian genetic subgroup analysis creates first-mover advantage for sponsors investing in regional trial infrastructure ahead of foreign competitors.
- Real-world evidence platforms:Electronic health record integration with hematology registries enables post-approval label expansion through prospective observational studies, bypassing traditional randomized trial costs for niche subpopulations.
Industry Challenges
- Hematopathologist workforce scarcity:Accurate MDS diagnosis and risk stratification require specialized morphologic expertise concentrated in academic medical centers, creating diagnostic bottlenecks that limit addressable patient identification.
- Legacy IT integration with cloud-based trial platforms:Hospital systems running on-premise electronic health records face interoperability friction when connecting to decentralized clinical trial technologies, slowing site activation and data capture.
- IP fragmentation across combination regimens:Hypomethylating agent backbone patents overlap with novel agent intellectual property, forcing complex licensing negotiations that delay fixed-dose combination development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Myelodysplastic Syndrome (MDS) Drugs Market |
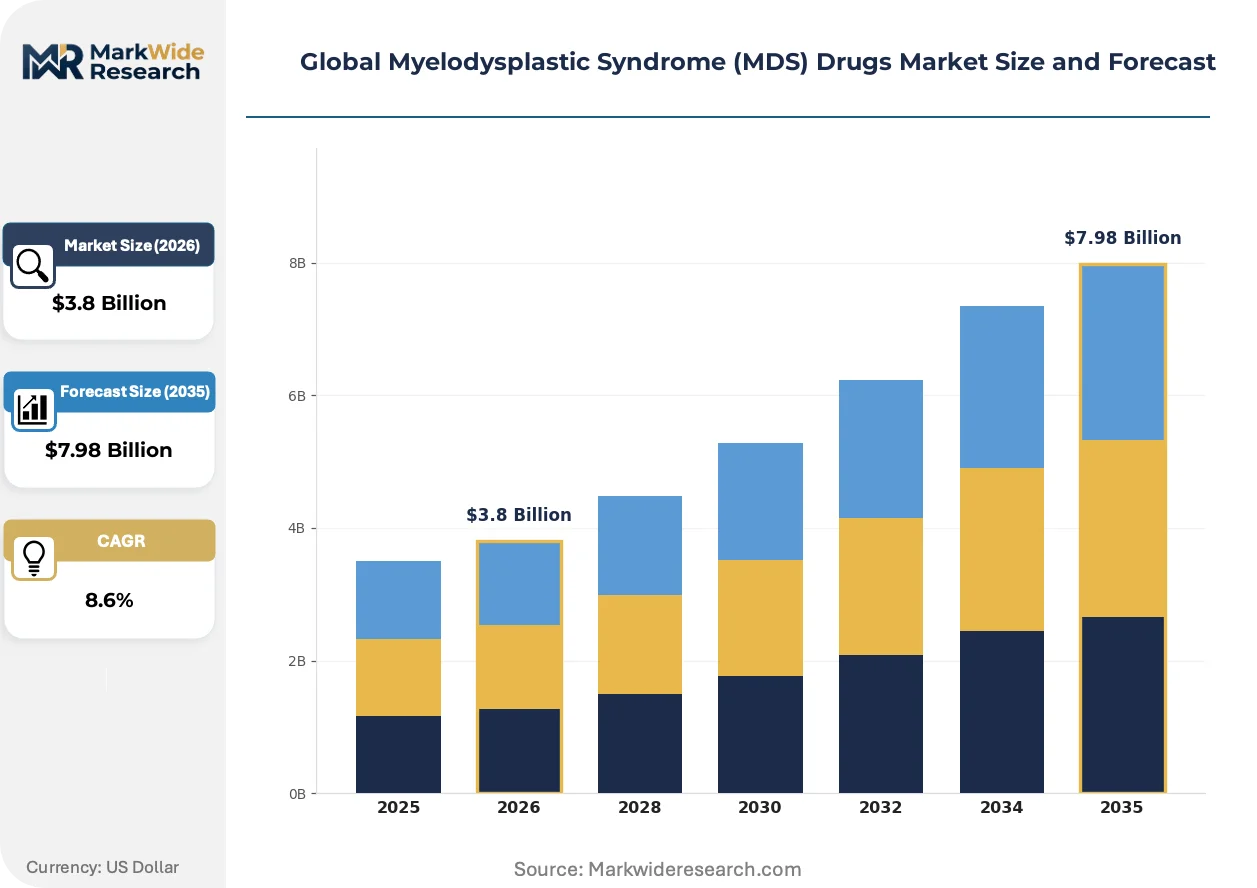
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypomethylating Agents, Immunomodulatory Drugs, Chemotherapy Agents, Growth Factors, Supportive Care Agents Therapy Area: Low-Risk MDS, Intermediate-Risk MDS, High-Risk MDS, Therapy-Related MDS, Secondary MDS End User: Specialized Hematology Centers, Oncology Clinics, Research Institutions, Ambulatory Care Centers, Blood Banks Delivery Mode: Injectable, Oral, Intravenous Infusion, Subcutaneous, Combination Therapy |
| Companies Covered | Bristol-Myers Squibb Company, Otsuka Pharmaceutical Co. Ltd, Amgen Inc., Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Limited, Takeda Pharmaceutical Company Limited, Pfizer Inc., Johnson & Johnson Services, Inc., Astex Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Myelodysplastic Syndrome (MDS) Drugs Market Shifts & Advancements
Next-generation sequencing integration into routine diagnostic workflows is reshaping how MDS is classified, treated, and monitored, moving the field from morphology-based schemas toward molecular risk stratification that directly informs therapeutic selection.
Next-generation sequencing panels are electrifying clinical trial enrollment by enabling real-time molecular eligibility screening. Academic medical centers in the United States and Germany are adopting these platforms at accelerating pace, collapsing the interval between diagnosis and protocol assignment. This compression is displacing traditional histology-first trial models with precision-matched enrollment that prioritizes actionable mutations over blast percentage thresholds.
The EMA's revised guidance on extrapolation of pediatric data for oncology indications is tightening evidentiary standards for adult MDS therapies with potential pediatric applications. Developers must now generate dedicated juvenile toxicology data rather than relying on adult pharmacokinetic bridging studies. Higher-risk disease categories face extended timelines as sponsors retrofit development programs to meet these centralized marketing authorization requirements.
Consolidation among United States oncology group purchasing organizations is compressing formulary access negotiations for MDS therapies. Three major buying coalitions now control procurement for over sixty percent of academic infusion centers, replacing fragmented hospital-level contracting with standardized tiered access agreements. This concentration is most visible in community hematology practices across Texas, Florida, and Ohio, where independent physicians increasingly affiliate with hospital systems to maintain drug margin participation.
Global Myelodysplastic Syndrome (MDS) Drugs Market Segmentation
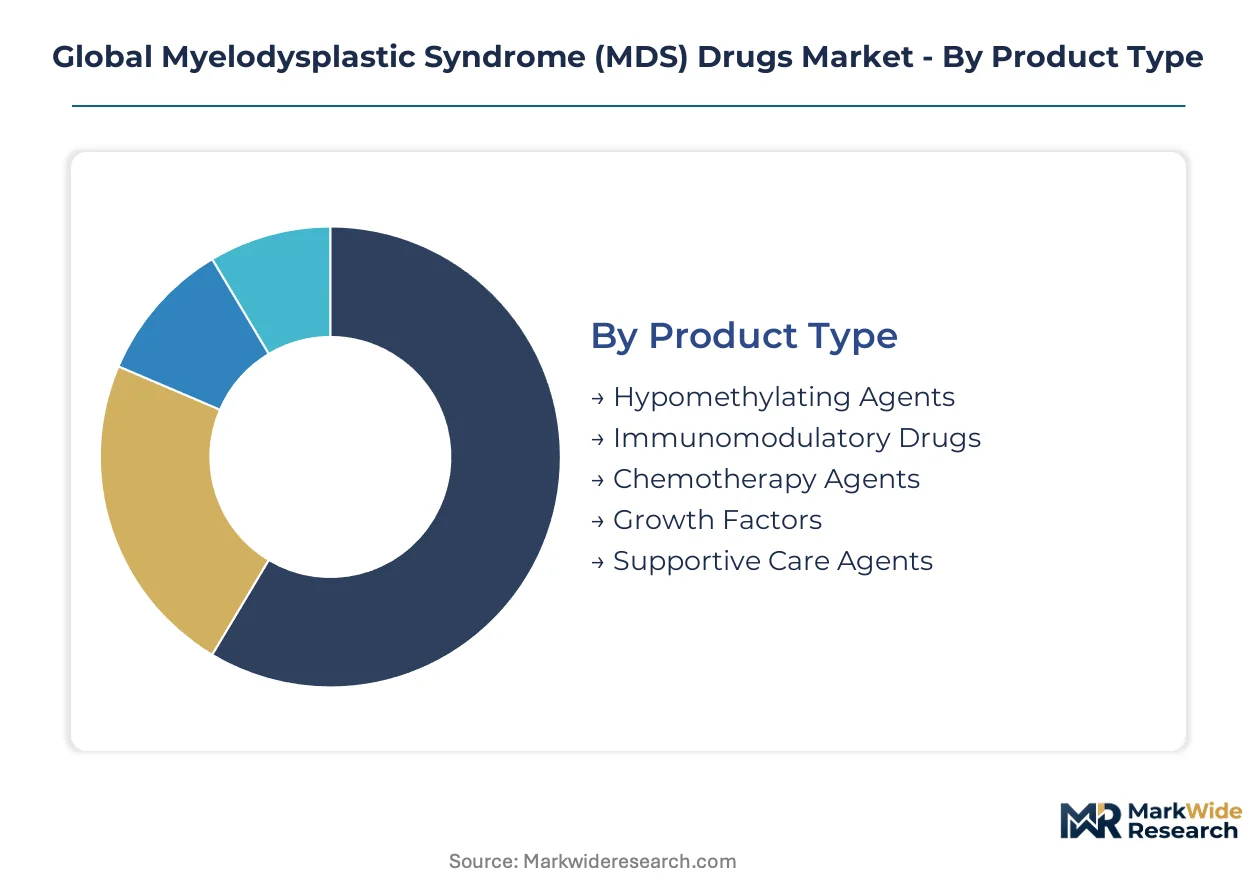
MDS drug purchasing decisions hinge on disease risk stratification, route of administration convenience, and institutional transfusion capacity. Pharmaceutical manufacturers align portfolio investments with these decision nodes to optimize formulary placement and prescribing behavior across treatment settings.
Product Type:
Prescribers weigh disease-modifying potential against toxicity profiles when selecting pharmacologic class, with reimbursement pathways reinforcing established therapeutic hierarchies.
- Hypomethylating Agents:Cytidine analogs that reverse aberrant DNA methylation patterns in malignant hematopoietic clones. Demand concentrates in United States academic medical centers where higher-risk MDS volume supports infusion-based administration infrastructure.
- Immunomodulatory Drugs:Oral agents modulating cytokine signaling and immune surveillance mechanisms. Germany's outpatient hematology networks are absorbing these formulations fastest as ambulatory protocols displace hospital-based transfusion dependency.
- Chemotherapy Agents:Cytotoxic compounds reserved for transformed disease or bridge-to-transplant scenarios.
- Growth Factors:Erythropoiesis-stimulating proteins addressing transfusion-dependent anemia in lower-risk categories.
- Supportive Care Agents:Antimicrobials, iron chelators, and anti-fibrinolytics managing MDS complications.
Hypomethylating agents lead on scale; immunomodulatory drugs lead on momentum.
Therapy Area:
Risk-adapted treatment algorithms segment the addressable population by blast percentage, cytogenetic abnormalities, and transfusion dependence status.
- Low-Risk MDS:Disease characterized by isolated cytopenias without excess blasts or adverse karyotype. Japan's geriatric hematology practices manage this population predominantly through watchful waiting and growth factor support.
- High-Risk MDS:Aggressive subtypes with elevated blast counts or complex cytogenetics demanding immediate disease-modifying intervention. United States tertiary centers concentrate clinical trial enrollment and hypomethylating agent utilization here.
- Intermediate-Risk MDS:Heterogeneous category requiring molecular refinement for therapeutic matching.
- Therapy-Related MDS:Secondary neoplasm arising from prior cytotoxic exposure with distinct genomic landscape.
- Secondary MDS:MDS evolving from antecedent hematologic disorder or environmental insult.
High-risk MDS commands the steepest expansion trajectory; low-risk MDS offers the largest untreated reservoir.
End User:
Site-of-care economics and diagnostic capability determine which institutions capture MDS drug volume.
- Specialized Hematology Centers:Academic institutions with integrated pathology, molecular diagnostics, and transplant services. Germany's university hospital networks anchor European prescribing for novel hypomethylating combinations through protocol-driven care.
- Oncology Clinics:Community-based practices managing stable lower-risk patients. Florida's consolidated oncology groups are shifting these sites toward oral immunomodulatory agents to preserve infusion capacity for higher-acuity cases.
- Research Institutions:Sites conducting investigator-initiated and sponsor-funded clinical trials.
- Ambulatory Care Centers:Standalone infusion facilities competing on convenience and cost.
- Blood Banks:Transfusion-dependent patient management and supportive care coordination.
Specialized hematology centers lead on scale; oncology clinics lead on momentum.
Delivery Mode:
Administration route selection balances bioavailability requirements with patient preference and healthcare system cost structures.
- Injectable:Parenteral formulations requiring healthcare professional administration. United States hospital outpatient departments retain this volume for higher-risk patients needing concurrent transfusion support.
- Subcutaneous:Depot or sustained-release injections enabling self-administration. Japan's home healthcare infrastructure is expanding fastest for this modality as PMDA approvals align with aging-in-place policy priorities.
- Oral:Tablet and capsule formulations maximizing patient autonomy.
- Intravenous Infusion:Extended-duration administration for agents requiring therapeutic drug monitoring.
- Combination Therapy:Sequential or concurrent multi-agent protocols.
Injectable formulations lead on scale; subcutaneous delivery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where MDS drug development concentrates, with sponsors migrating clinical operations toward jurisdictions offering streamlined oncology trial frameworks and favorable reimbursement negotiation climates.
United States
The FDA's Center for Drug Evaluation and Research anchors global MDS drug development through accelerated approval pathways that compress commercialization timelines. Medicare's oncology demonstration projects in Baltimore and Houston are testing value-based reimbursement for hypomethylating agent combinations. Massachusetts biotech clusters concentrate precision medicine infrastructure that supports biomarker-driven trial enrollment.
Germany
University hospital networks in Munich and Heidelberg drive European adoption of novel hypomethylating protocols through protocol-driven care standardization. The EMA's Committee for Medicinal Products for Human Use shapes centralized marketing authorization requirements that elevate clinical trial design standards. North Rhine-Westphalia's outpatient hematology networks are absorbing oral immunomodulatory agents fastest as ambulatory protocols expand.
Japan
The PMDA's pharmacogenomic data requirements filter market entry for foreign sponsors while creating first-mover advantage for regional trial infrastructure investment. Tokyo's geriatric hematology practices manage low-risk MDS through watchful waiting aligned with aging-in-place policy priorities. Osaka's home healthcare infrastructure is expanding subcutaneous formulation delivery capabilities.
India
API manufacturing for cornerstone hypomethylating agents clusters among suppliers concentrated in Hyderabad and Ahmedabad, exposing formulators to quality audit risks. The CDSCO's evolving oncology drug evaluation standards are gradually aligning with FDA and EMA frameworks. Mumbai's contract research organizations are absorbing outsourced clinical trial operations from Western sponsors seeking cost efficiencies.
United Kingdom
NHS England's specialized commissioning frameworks concentrate MDS drug access within designated tertiary hematology centers in London and Manchester. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes that diverge from EMA timelines. Cambridge's genomic medicine clusters are integrating next-generation sequencing into routine diagnostic workflows.
Global Myelodysplastic Syndrome (MDS) Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies controlling disease-modifying agent portfolios while regional formulators capture supportive care and generic substitution opportunities. The vendor base organizes around three strategic archetypes: global oncology majors with deep hypomethylating agent R&D pipelines, biologics specialists leveraging growth factor platforms, and emerging market API-to-formulation integrators. M&A activity concentrates on precision medicine assets with companion diagnostic linkages, while capacity expansion prioritizes subcutaneous and oral formulation technologies that shift site-of-care economics.
Among North American-based innovators, Bristol-Myers Squibb Company and Amgen Inc. occupy positions exemplifying the integrated oncology major archetype, with the former representing deep investment in hypomethylating agent combinations and the latter anchoring growth factor portfolio differentiation. Takeda Pharmaceutical Company Limited exemplifies the Asia-Pacific hematology franchise model, leveraging regional distribution control across tertiary centers. These three entities represent distinct competitive positioning vectors—combination therapy leadership, transfusion burden reduction specialization, and geographic franchise density—that shape how prescriber access and formulary placement negotiations unfold across institutional settings.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Otsuka Pharmaceutical Co. Ltd |
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Limited |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Astex Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up oncology distributors have consolidated procurement leverage across United States infusion centers, compressing hypomethylating agent margins while simultaneously demanding just-in-time inventory guarantees that strain API formulators in India and China.
Pricing Analysis
Hospital group purchasing organization rebates dominate the pricing model, with three-tier pricing structure across premium patented combinations, standard single-agent protocols, and economy-positioned supportive care. Price differentiation hinges on FDA breakthrough therapy designation and companion diagnostic bundling. Cost compression in the standard tier is intensifying because of azacitidine generic entry. Community oncology clinics in Florida and Texas exhibit the highest price sensitivity, while academic medical centers in Massachusetts and Maryland prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for parenteral formulations now mandate qualified API suppliers in both India and China, with secondary validation runs through European contract manufacturers. Active pharmaceutical ingredient production draws from Hyderabad, Ahmedabad, and select Zhejiang province facilities. Cytidine analog synthesis rests on pyrimidine precursor supply from specialized chemical manufacturers. Single-source vulnerability concentrates in the sub-two qualified supplier base for azacitidine API. Distribution runs through temperature-controlled logistics networks serving hospital outpatient departments and specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift toward subcutaneous and oral formulations that reduce infusion center overhead while capturing premium pricing for patient convenience.
For Market Incumbents: Cement formulary dominance through captive manufacturing of companion diagnostics paired with hypomethylating agent backbones. Lock in long-term API offtake agreements with Hyderabad suppliers before CDSCO quality audit tightening reshapes supplier qualification. The threat of biosimilar erythropoiesis-stimulating agents demands preemptive growth factor portfolio refresh. For New Entrants and Emerging Players: Direct-to-specialist digital detailing platforms offer the lowest customer acquisition cost route into the MDS therapeutics space. White-space targets include lower-risk transfusion-dependent populations currently managed with watchful waiting in Japan's geriatric practices, and subcutaneous formulation development for Germany's expanding ambulatory hematology networks. Pursue licensing partnerships with academic medical centers holding investigator-initiated trial infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotechs with phase II-ready immunomodulatory assets lacking companion diagnostic co-development partnerships. Long-term viability favors platforms with biomarker-selected patient identification capabilities and existing relationships with FDA's Center for Drug Evaluation and Research. The signal to watch is accelerated approval pathway utilization rates for novel hypomethylating combinations.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA's parallel validation mandates reshape development timelines and partnership structures for precision candidates. |
| Subcutaneous Formulation Scale-Up | Japan's PMDA approvals for home administration align with national aging-in-place healthcare policy priorities. |
| Real-World Evidence Platform Integration | Electronic health record connectivity with hematology registries enables post-approval label expansion without traditional trial costs. |
| API Supplier Qualification Diversification | CDSCO audit intensity in India and quality compliance requirements in China force redundant manufacturing validation. |
| Lower-Risk MDS Label Expansion | EMA's centralized marketing authorization process rewards sponsors generating dedicated data for transfusion-dependent populations. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors at major oncology GPOs, and hospital procurement managers grounded the qualitative foundation. Secondary validation drew from FDA filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registrations, and Japanese PMDA review reports. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Projected market values across the modeling period reflect patient population sizing by risk stratification, treatment penetration curves for hypomethylating agents and immunomodulatory drugs, and pricing trajectories informed by generic entry timelines. Segmentation dimensions included disease risk category, pharmacologic class, administration route, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating biomarker-driven trial enrollment acceleration and site-of-care shift economics.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing integration into community hematology diagnostics would alter the outlook. Deviation in FDA accelerated approval confirmation trial success rates or EMA pharmacogenomic data requirement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Plasma Protein System Market