
 Deep Fryer Market | 2026-2036
Deep Fryer Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Fryer Market Intelligence
Market Context with Strategic Players
REACH compliance is expanding the cost-of-entry calculus for European-sourced frying equipment, forcing manufacturers to reformulate coatings and electrical assemblies. Henny Penny leverages its Ohio manufacturing base to sustain domestic supply chain control against import tariff volatility. Electrolux Professional competes through integrated kitchen system bundling that anchors fryer sales within broader commercial equipment contracts. Middleby dominates the North American quick-service channel through its captive distribution network and service infrastructure.
Technical Definition and Structural Segments
A deep fryer is a thermostatically controlled cooking appliance that submerges food in heated oil or fat, typically operating between 175°C and 190°C with basket-lift mechanisms and sediment zones for particulate collection. Its primary commercial purpose centers on high-throughput, consistent crust formation for breaded proteins, frozen potato products, and battered goods in foodservice environments. Electric fryers lead the technology dimension through precision temperature control and reduced ventilation requirements, while induction fryers represent the fastest-growing sub-category as operators seek to eliminate open-flame hazards and reduce thermal lag. Floor-standing units anchor the product type mix in full-service restaurants where volume throughput dictates equipment scale, whereas countertop configurations occupy the food truck and catering segments where mobility and space constraints dominate purchasing criteria.
Regulatory Frame and Forward-Looking Close
The FDA's Food Code oil temperature monitoring provisions, EPA grease effluent standards, and EU F-Gas Regulation on fluorinated greenhouse gases collectively reshape equipment specifications and replacement cycles across major markets. These frameworks push manufacturers toward closed-loop oil filtration systems and alternative refrigerant architectures in connected holding cabinets. Stakeholders must monitor how municipal fire codes evolve around induction technology certification, as this determines whether electric or gas fryer investments retain compliance advantage in dense urban foodservice clusters.
Market Dynamics
Induction heating technology is compressing replacement cycles across commercial kitchens as operators prioritize open-flame elimination and thermal precision over legacy gas infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gases accelerate fryer fleet turnover in European foodservice, pushing demand toward electric and induction models with alternative refrigerant architectures in connected holding cabinets.
- Quick-service restaurant densification:Southeast Asian urban corridors, particularly Indonesia's street-to-storefront conversion wave, drive commercial kitchen equipment procurement for standardized frying operations.
- Closed-loop oil filtration:Automated filtration systems reduce oil consumption and labor costs, creating pull from high-volume operators seeking operational efficiency gains.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless price swings compress manufacturer margins and destabilize quoted equipment pricing for project-based buyers.
- Electronics supply concentration:Thermostatic controls and induction coil assemblies concentrate among East Asian component suppliers, exposing lead time risk for Western fryer manufacturers.
- REACH compliance cost escalation:European chemical safety frameworks force coating reformulation and electrical assembly redesign, raising cost-of-entry for equipment sourced into EU markets.
Strategic Opportunities
- India foodservice modernization:FSSAI enforcement of oil quality standards in organized food retail creates first-mover advantage for filtration-integrated fryer suppliers targeting quick-service chains.
- Cloud kitchen proliferation:Delivery-only kitchen operators prioritize compact, ventless electric fryers with remote monitoring capabilities, opening a channel distinct from traditional restaurant procurement.
- US Inflation Reduction Act efficiency incentives:Energy-efficient commercial kitchen equipment tax credits accelerate electric fryer adoption against gas alternatives in American foodservice operations.
Industry Challenges
- Induction technician scarcity:Commercial kitchen service networks lack certified repair capacity for induction coil and power electronics maintenance, extending downtime risk for early adopters.
- Multi-jurisdictional certification lag:Municipal fire code variance across US metropolitan areas delays induction fryer deployment approvals, fragmenting rollout timelines for national chain operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Fryer Market |
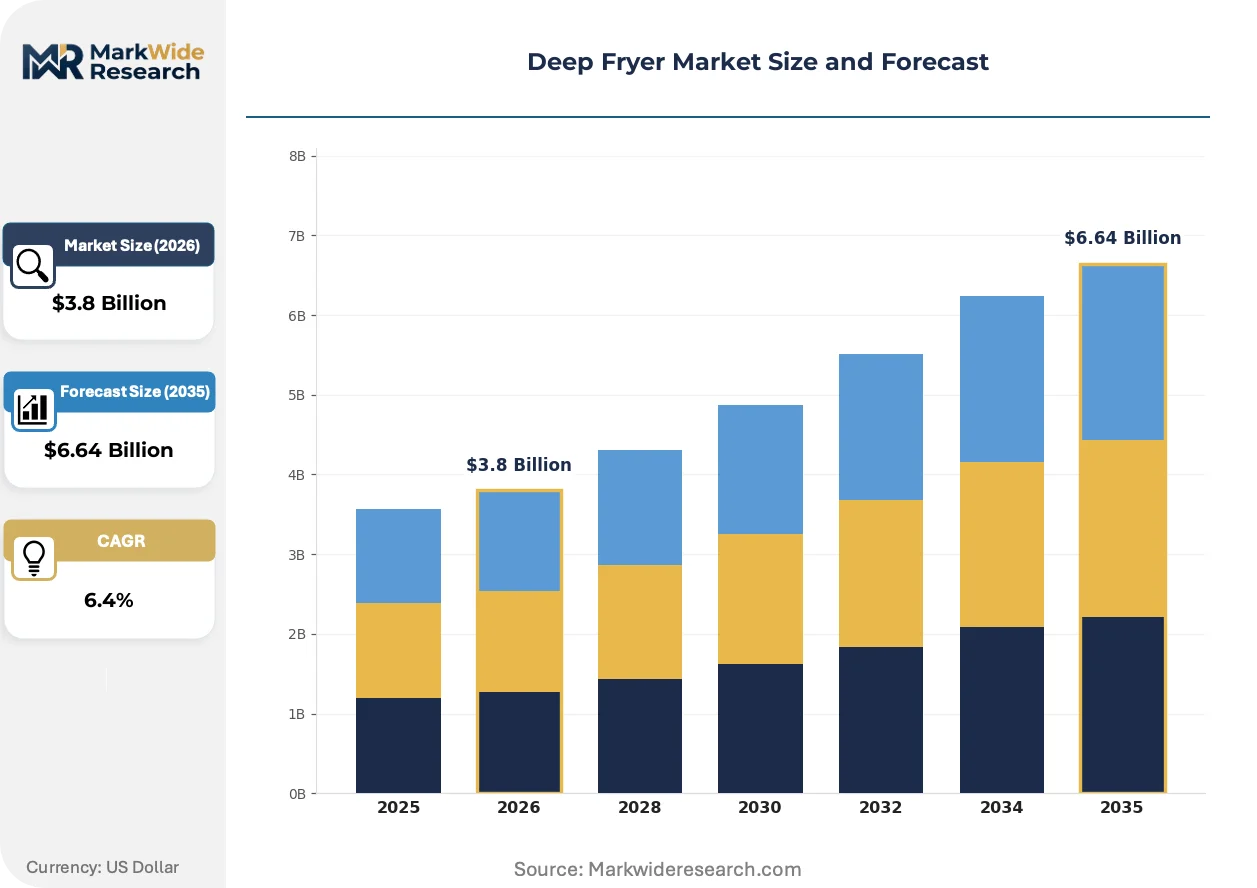
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-standing, Pressure Fryers, Commercial Fryers End User: Restaurants, Fast Food Chains, Catering Services, Food Trucks Technology: Electric Fryers, Gas Fryers, Induction Fryers, Hybrid Fryers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Frymaster, Vulcan, Middleby, ITW, Welbilt, Henny Penny, Pitco, Standex International, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Fryer Market Strategic Shifts & Innovations
Automation and connectivity are redefining fryer value propositions, shifting competitive advantage from thermal engineering to data-driven oil management and predictive maintenance capabilities.
Induction fryer technology is expanding into high-throughput quick-service environments previously dominated by gas equipment. Chains with standardized menu portfolios and centralized procurement functions are piloting induction at flagship locations to validate throughput parity. This technology is expanding into markets where municipal fire codes restrict open flames in dense urban foodservice clusters, compressing gas fryer addressable market share in metropolitan cores.
REACH chemical safety frameworks and EU F-Gas Regulation are jointly reshaping equipment specifications across European foodservice. Manufacturers must reformulate non-stick coatings and redesign electrical assemblies to eliminate restricted substances, extending product development cycles by 12-18 months. Full-service restaurant operators in Germany and France are responding by consolidating purchases with suppliers demonstrating pre-certified compliance pathways.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale restaurant groups seeking to offload maintenance and oil management liability. Third-party service providers bundle fryer hardware with filtration consumables and periodic technician visits, capturing recurring revenue streams. This shift concentrates in UK and US metropolitan markets where labor scarcity elevates the value of outsourced kitchen equipment management.
Deep Fryer Market Segmentation
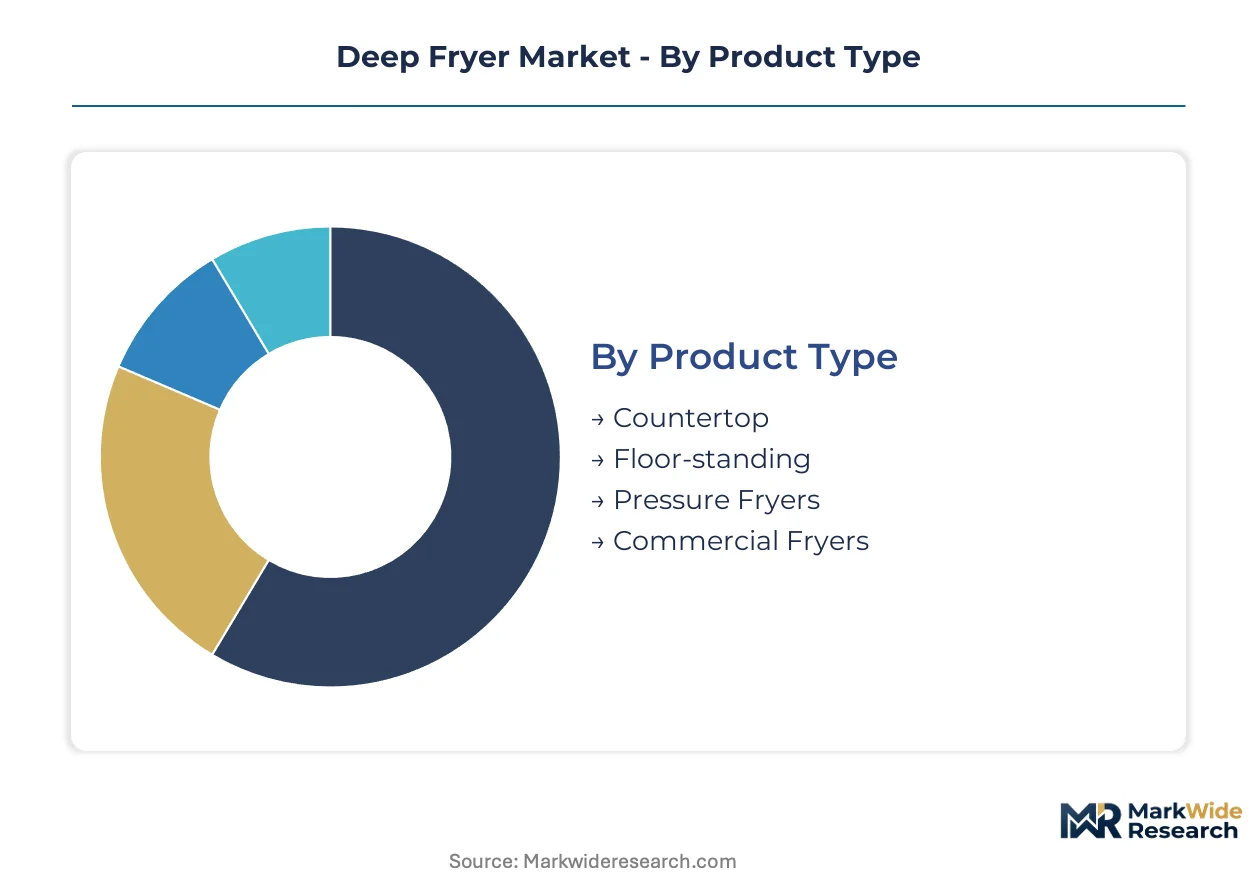
Deep fryer procurement decisions hinge on kitchen configuration, energy infrastructure, and throughput requirements. Segment-specific capital outlays and operating constraints shape equipment selection across foodservice verticals.
Product Type:
Capital-intensity varies sharply across configurations, with floor-standing units demanding the highest upfront investment for installation and ventilation infrastructure.
- Floor-standing:These units anchor high-volume frying operations with oil capacities exceeding 25 liters and multiple vat configurations. Full-service restaurants in Indonesia's urban corridors deploy these for sustained throughput during peak service windows.
- Countertop:Compact units with 5-15 liter capacities plug into standard electrical outlets without dedicated ventilation. Food trucks and catering operators across Southeast Asia favor these for mobility and rapid deployment.
- Pressure Fryers:Sealed-vessel designs cook breaded proteins under elevated pressure, reducing oil absorption and cook times. Quick-service chains standardize on these for menu consistency.
- Commercial Fryers:Broad category encompassing institutional-scale equipment for central kitchens and commissary operations. Cloud kitchen operators in US metropolitan markets specify these for batch production efficiency.
Floor-standing configurations absorb the bulk of installed capacity; countertop units are expanding most quickly through food truck and ghost kitchen proliferation.
End User:
Volume concentration and standardization requirements differentiate procurement patterns across foodservice channels.
- Fast Food Chains:Centralized procurement functions demand equipment with standardized control interfaces and remote monitoring capabilities. Chains across India are retrofitting locations with filtration-integrated models to meet FSSAI oil quality mandates.
- Restaurants:Independent and full-service operators prioritize flexibility for menu variation and kitchen layout adaptation. German and French establishments are consolidating purchases with REACH-compliant suppliers to avoid certification delays.
- Catering Services:Mobile and event-based operations require rapid heat recovery and transport-stable oil containment. Electric countertop units dominate this channel for venue compatibility.
- Food Trucks:Space-constrained operators need ventless electric fryers with low amp draw. Municipal fire code restrictions on open flames in dense US urban cores accelerate electric adoption here.
Fast food chains command the largest equipment volumes; food trucks are climbing the fastest as street-to-storefront conversions proliferate.
Technology:
Energy infrastructure and regulatory compliance create divergent total-cost-of-ownership profiles across heating methodologies.
- Electric Fryers:Precision thermostatic control and reduced ventilation requirements suit operators in jurisdictions with strict emissions standards. These units lead technology deployment in EU markets facing F-Gas Regulation compliance pressures.
- Induction Fryers:Coil-based electromagnetic heating eliminates open flames and compresses thermal lag to under 90 seconds. Pilot deployments in US quick-service flagships are validating throughput parity with gas alternatives.
- Gas Fryers:Legacy infrastructure in established restaurant bases sustains demand where natural gas lines are pre-installed and municipal codes permit open flames.
- Hybrid Fryers:Dual-energy designs allow operators to switch between gas and electric inputs based on utility pricing or regulatory constraints. These appeal to multi-jurisdictional chain operators facing fragmented fire code requirements.
Electric fryers hold the dominant installed base; induction fryers are gaining share fastest as operators prioritize flame elimination and thermal precision.
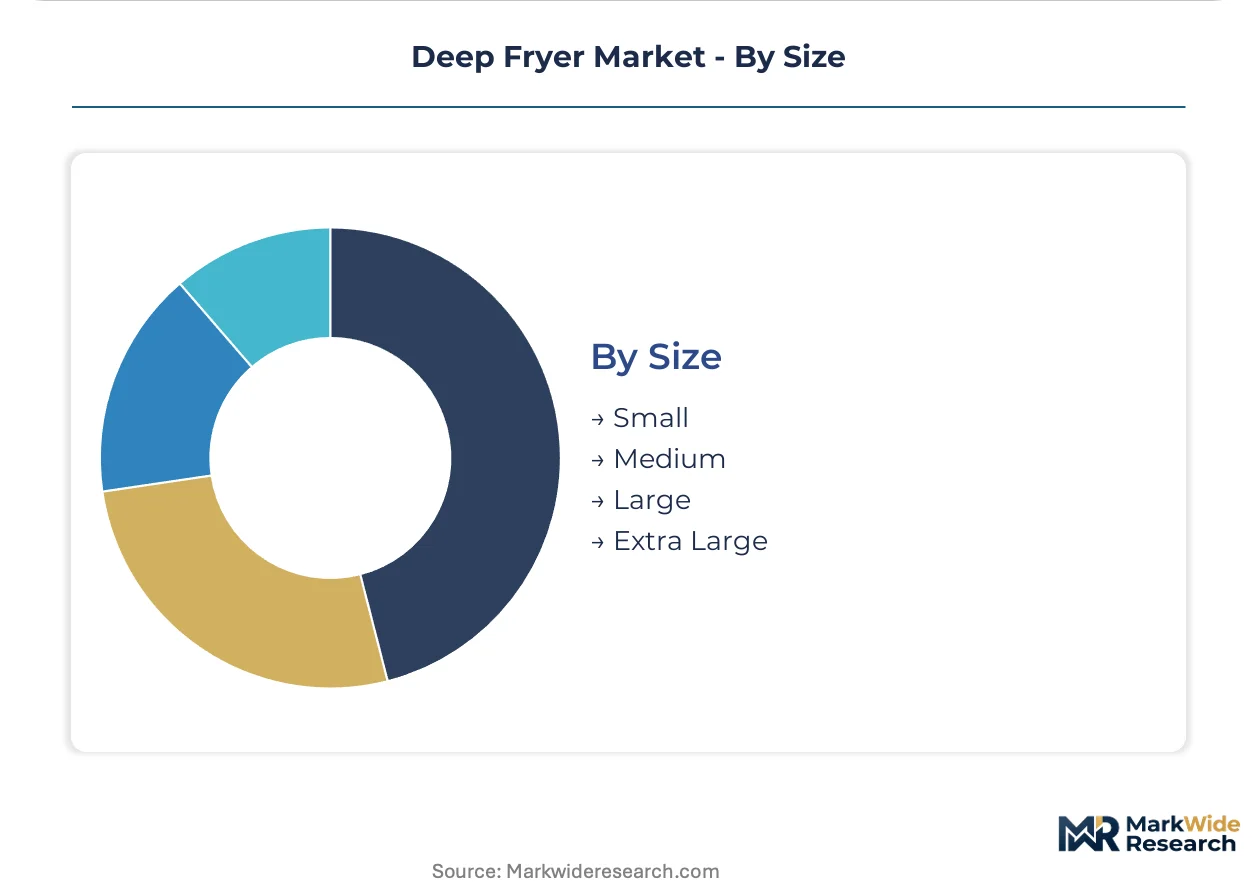
Size:
Oil capacity and footprint dimensions directly correlate with throughput capability and kitchen space allocation.
- Large:30+ liter capacities support sustained high-volume frying for central kitchens and institutional feeders. These units concentrate in quick-service commissary operations across Southeast Asia.
- Medium:15-30 liter ranges balance throughput with space efficiency for independent restaurants. This bracket captures the majority of replacement demand in mature foodservice markets.
- Small:Under 15 liter configurations serve specialty frying stations and limited-menu concepts. Cloud kitchen operators specify these for single-purpose production cells.
- Extra Large:50+ liter industrial designs serve stadium concessions, airport terminals, and centralized production facilities. These require dedicated ventilation and floor reinforcement.
Medium-capacity units represent the largest replacement volume; small configurations are expanding most quickly through delivery-only kitchen proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's special economic zones for food processing concentrate commercial kitchen equipment demand as street-to-storefront conversions accelerate fryer procurement across Southeast Asian urban corridors.
United States
Quick-service restaurant chains drive electric fryer adoption as municipal fire codes tighten open-flame restrictions in dense urban cores. The Inflation Reduction Act's commercial kitchen equipment tax credits accelerate capital replacement cycles. Chicago and New York metropolitan foodservice clusters prioritize ventless induction models for compliance flexibility.
Germany
Full-service restaurant operators consolidate procurement with REACH-compliant suppliers to avoid certification delays on coating reformulations. EU F-Gas Regulation mandates reshape connected holding cabinet specifications. Bavarian and North Rhine-Westphalia hospitality clusters lead fleet turnover toward closed-loop oil filtration systems.
India
FSSAI enforcement of oil quality standards in organized food retail creates procurement pull for filtration-integrated equipment. Quick-service chains retrofit existing locations to meet centralized kitchen mandates. Mumbai and Delhi-NCR urban corridors anchor replacement demand as street-to-storefront conversions formalize commercial operations.
Indonesia
Urban foodservice densification accelerates commercial kitchen equipment procurement across Jakarta and Surabaya metropolitan areas. Local health authorities tighten oil-quality monitoring protocols for quick-service deployments. Street-to-storefront upgrade waves concentrate floor-standing fryer demand in emerging organized retail corridors.
United Kingdom
Equipment-as-a-service contracting displaces capital purchase models among mid-scale restaurant groups seeking outsourced maintenance liability. Labor scarcity in metropolitan markets elevates value of bundled filtration and technician services. London and Birmingham foodservice clusters pilot subscription-based fryer management for operational cost predictability.
Deep Fryer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates around integrated kitchen system bundlers, captive distribution networks, and regional manufacturing bases. Three archetypes dominate: full-line commercial equipment suppliers leveraging cross-selling scale, dedicated frying equipment specialists prioritizing thermal engineering depth, and diversified industrial conglomerates extracting procurement efficiency from multi-category contracts. M&A activity targets filtration technology capabilities and regional service infrastructure expansion.
Within the dedicated equipment tier, Henny Penny and Pitco exemplify manufacturing-base differentiation strategies, while Middleby occupies a position emphasizing captive distribution control. Frymaster and Vulcan sit within the full-line supplier archetype alongside ITW's diversified industrial positioning. Electrolux Professional represents the European integrated-systems approach, with Welbilt and Standex International anchoring mid-market consolidation plays through portfolio breadth rather than single-category dominance.
| Leading Market Players |
|---|
| Frymaster |
| Vulcan |
| Middleby |
| ITW |
| Welbilt |
| Henny Penny |
| Pitco |
| Standex International |
| Electrolux Professional |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance gates qualified supply access for connected holding cabinets and compresses premium-tier pricing power toward manufacturers with pre-certified refrigerant architectures. Buyers lacking REACH-compliant coating pathways face extended product development cycles that disqualify them from European procurement tenders.
Pricing Analysis
Short lead-time premiums command pricing advantages as operators facing compressed replacement cycles prioritize rapid deployment over spot inventory discounts. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Pricing pressure stems from stainless steel input volatility compressing manufacturer margins. High-volume quick-service chains exhibit lowest price sensitivity due to standardized procurement functions; independent restaurants demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
CE marking and UL certification gating restricts component sourcing to qualified East Asian and North American suppliers. Thermostatic controls and induction coil assemblies concentrate among Taiwan, South Korea, and China manufacturing bases. Grade 304 and 316 stainless steel feedstock draws from Indonesian nickel processing and Chinese mill production. Single-source vulnerability in power electronics creates lead time exposure for Western fryer manufacturers. Distribution runs through captive dealer networks and integrated kitchen equipment bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market favors consolidation plays as REACH compliance cost escalation forces smaller coating reformulators and electrical assembly designers from European competition.
For Market Incumbents: Deepen captive service infrastructure to lock in quick-service chain accounts against emerging induction specialists. Acquire filtration technology capabilities to capture recurring revenue streams from oil management outsourcing. Expand Ohio and domestic manufacturing footprints to insulate against tariff exposure on East Asian component imports.
For New Entrants and Emerging Players: Cloud kitchen operators represent the most penetrable buyer archetype as delivery-only concepts prioritize compact ventless electric configurations with remote monitoring. Target UK metropolitan markets where equipment-as-a-service contracting displaces capital purchase models. Lead with subscription-based fryer management bundling filtration consumables and technician visits.
For Investors and Strategic Acquirers: Municipal fire code harmonization around induction certification is the leading indicator that electric fryer adoption will accelerate against gas alternatives in dense urban cores. Five-to-ten year viability favors manufacturers with backward integration into power electronics and regional service networks. Watch for consolidation signals when mid-scale restaurant groups abandon capital purchase models for outsourced kitchen equipment management.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Oil Filtration Integration | Captures recurring revenue from FSSAI compliance-driven retrofit cycles across Indian quick-service chains. |
| Induction Technology Certification Investment | Secures municipal fire code approval in Chicago and New York metropolitan foodservice clusters. |
| Regional Manufacturing Footprint Expansion | Insulates margin position against stainless steel price volatility and import tariff exposure. |
| Equipment-as-a-Service Platform Launch | Addresses UK labor scarcity through bundled maintenance and oil management liability transfer. |
| REACH-Compliant Coating Reformulation | Maintains European market access as ECHA restrictions eliminate non-qualified competitors. |
Research Approach
Multi-period observation of oil quality enforcement actions, municipal fire code amendments, and quick-service chain procurement patterns anchored the trend analysis, supplemented by interviews with commercial kitchen equipment procurement directors, foodservice facility managers, aftermarket service technicians, and regulatory compliance officers. Secondary validation drew from FDA Food Code provisions, EU F-Gas Regulation filings, FSSAI enforcement circulars, and customs trade data on stainless steel mill shipments. Bottom-up equipment deployment counts triangulated against top-down foodservice operator expenditure estimates.
Segment-weighting across product type, technology, end-user channel, and oil capacity tiers structured the analytical framework across the projection horizon. CAGRs derived from replacement cycle compression rates, regulatory mandate phase-in schedules, and urban foodservice densification trajectories. Induction pilot deployment validation at US quick-service flagships and Southeast Asian street-to-storefront conversion velocity served as industry-specific forecast inputs.
Revisions become necessary when REACH substance restriction amendments, municipal fire code harmonization failures, or stainless steel commodity price shocks materialize outside modeled ranges. Forecasts reflect assumptions on technician certification network expansion and oil filtration automation adoption curves. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or Inflation Reduction Act credit program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Global Wine Tanks Market