
 Shawarma Grill Machine Market | 2026-2036
Shawarma Grill Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shawarma Grill Machine Market Analytics
Aftermarket service revenue is reshaping margin distribution across the Shawarma Grill Machine value chain. Viatto leverages its European distribution network to capture recurring parts and maintenance contracts. Fimar anchors its competitive stance through deep specialization in stainless steel fabrication for vertical grill architectures. Ozti competes aggressively on manufacturing scale from its Turkish production base.
A shawarma grill machine is a vertical or horizontal rotating spit cooking apparatus, typically constructed from stainless steel with infrared or ceramic burner systems capable of reaching surface temperatures exceeding 300°C, designed to roast stacked meat for commercial foodservice output. Electric grill configurations command premium positioning in European urban kitchens where gas infrastructure restrictions apply, while gas grill variants dominate Middle Eastern markets where propane access remains cost-advantaged. Stainless steel construction leads material preference due to sanitation compliance and thermal durability, though aluminum alternatives gain traction in mobile food truck deployments where weight reduction dictates specification.
NSF International standards govern commercial food equipment safety in the United States, while CE marking under the EU Machinery Directive regulates European market access and operational guarding requirements. Turkey's Ministry of Industry and Technology enforces domestic manufacturing certifications that shape regional export competitiveness. Stakeholders must monitor evolving energy efficiency thresholds across jurisdictions as electrification mandates intensify specification divergence between gas and electric product lines.
Market Dynamics
Aftermarket service revenue streams are restructuring margin distribution across the Shawarma Grill Machine value chain, with recurring parts and maintenance contracts displacing upfront equipment sales as the primary profit center for specialized distributors.
Growth Catalysts
- NSF International certification:Food trucks across the United States face mandatory equipment upgrades to meet commercial food safety standards, accelerating replacement cycles for compliant vertical grill systems.
- Mobile dining proliferation:Food truck operators in Canada and Mexico are expanding shawarma menu offerings, creating concentrated demand for compact, high-output vertical rotisserie units.
- Stainless steel thermal durability:Commercial kitchens prioritize NSF-rated stainless steel construction for sanitation compliance and extended service life under continuous high-temperature operation.
Market Restraints
- CE marking complexity:Evolving EU Machinery Directive requirements for operational guarding and energy efficiency are extending product approval timelines for European market entry.
- Gas infrastructure dependency:Middle Eastern markets remain locked into propane-dependent vertical grill architectures, constraining electrification transitions despite efficiency mandates.
- Turkish manufacturing concentration:Dense equipment replacement cycles and local production clusters in Turkey create supply-side vulnerability to regional logistics disruptions.
Strategic Opportunities
- Electric grill premium positioning:Urban kitchens in Germany and France face gas infrastructure restrictions, opening white space for infrared ceramic burner systems with precision temperature control.
- Aluminum weight reduction:Mobile food truck deployments in the United States are specifying aluminum alternatives to stainless steel, enabling chassis load optimization and fuel efficiency gains.
- EU Green Deal electrification:Intensifying energy efficiency thresholds across European jurisdictions are mandating specification divergence that favors electric product line development.
Industry Challenges
- Certification timeline compression:Manufacturers face parallel NSF International, CE marking, and Turkish Ministry of Industry validation tracks, straining technical documentation resources.
- Skilled fabrication scarcity:Deep specialization in vertical grill stainless steel welding and infrared burner assembly limits qualified production workforce availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shawarma Grill Machine Market |
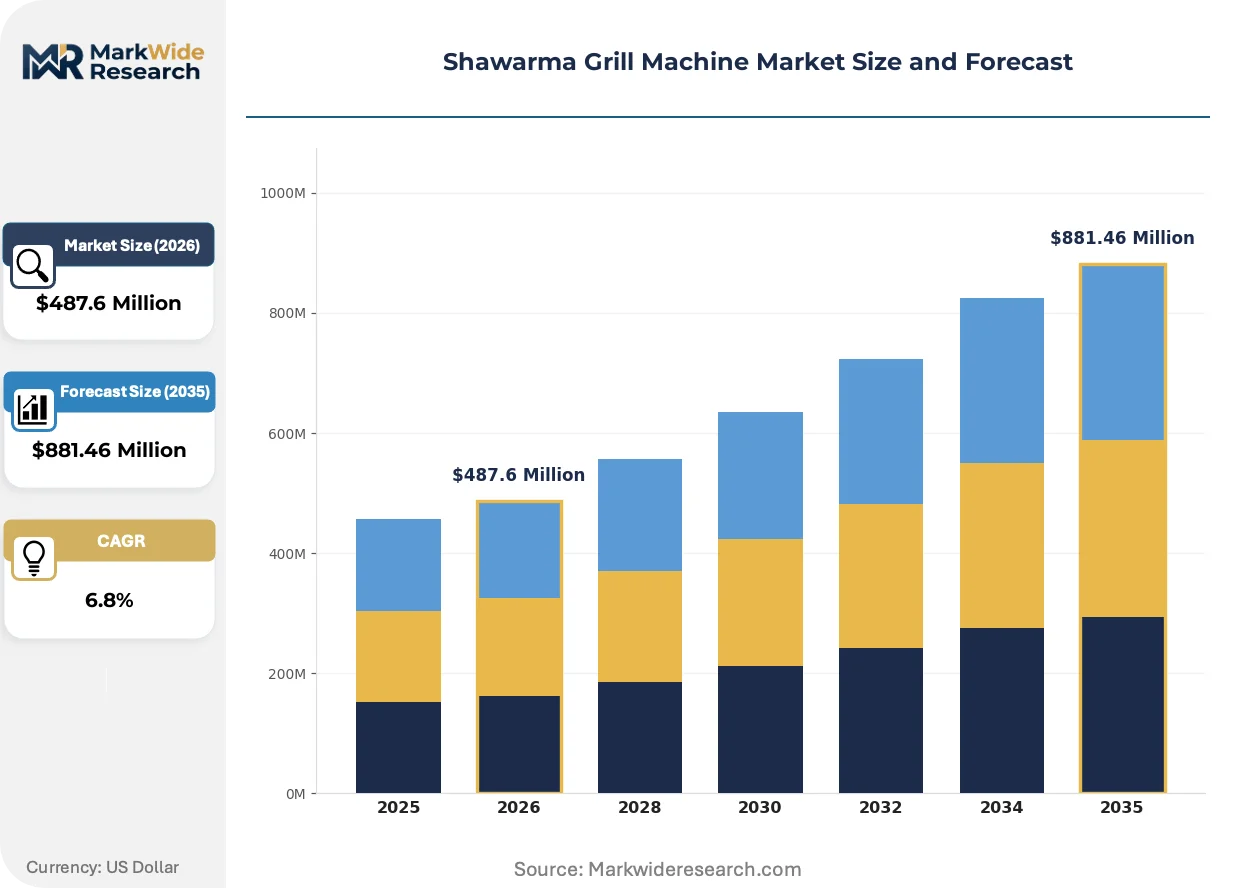
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Grill, Horizontal Grill, Electric Grill, Gas Grill Power Rating: Low Power, Medium Power, High Power, Variable Power End User: Restaurants, Food Trucks, Caterers, Home Users Material: Stainless Steel, Aluminum, Cast Iron, Metal Alloy |
| Companies Covered | Viatto, Fimar, Atesy, Spinning Grillers, Ozti, Hurakan, Eksi, Paramount, Grill Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shawarma Grill Machine Market Evolving Landscape
Equipment specification is diverging sharply between gas and electric architectures as electrification mandates and infrastructure constraints reshape buyer preferences across metropolitan and mobile foodservice segments.
Infrared ceramic burner technology is hybridizing with precision electronic ignition systems to deliver surface temperatures exceeding 300°C with reduced thermal lag. Full-service restaurants in France and Germany are adopting these configurations to meet kitchen ventilation restrictions. The convergence is compressing demand for traditional gas-only vertical grills in urban European markets.
EU Machinery Directive amendments governing operational guarding and energy efficiency are forcing redesigns of vertical spit access mechanisms and exhaust integration. Turkish exporters must retool guarding systems to maintain CE marking validity. Electric grill variants with sealed burner housings are capturing specification share in Netherlands and Belgium commercial kitchen tenders.
Food truck operators are unbundling after-sales service from equipment purchase, procuring vertical grills through specialized distributors while sourcing maintenance through third-party commercial kitchen service networks. This procurement fragmentation is visible across California, Texas, and Florida mobile dining clusters. Distributors are responding with parts-only subscription models detached from original equipment transactions.
Shawarma Grill Machine Market Segmentation
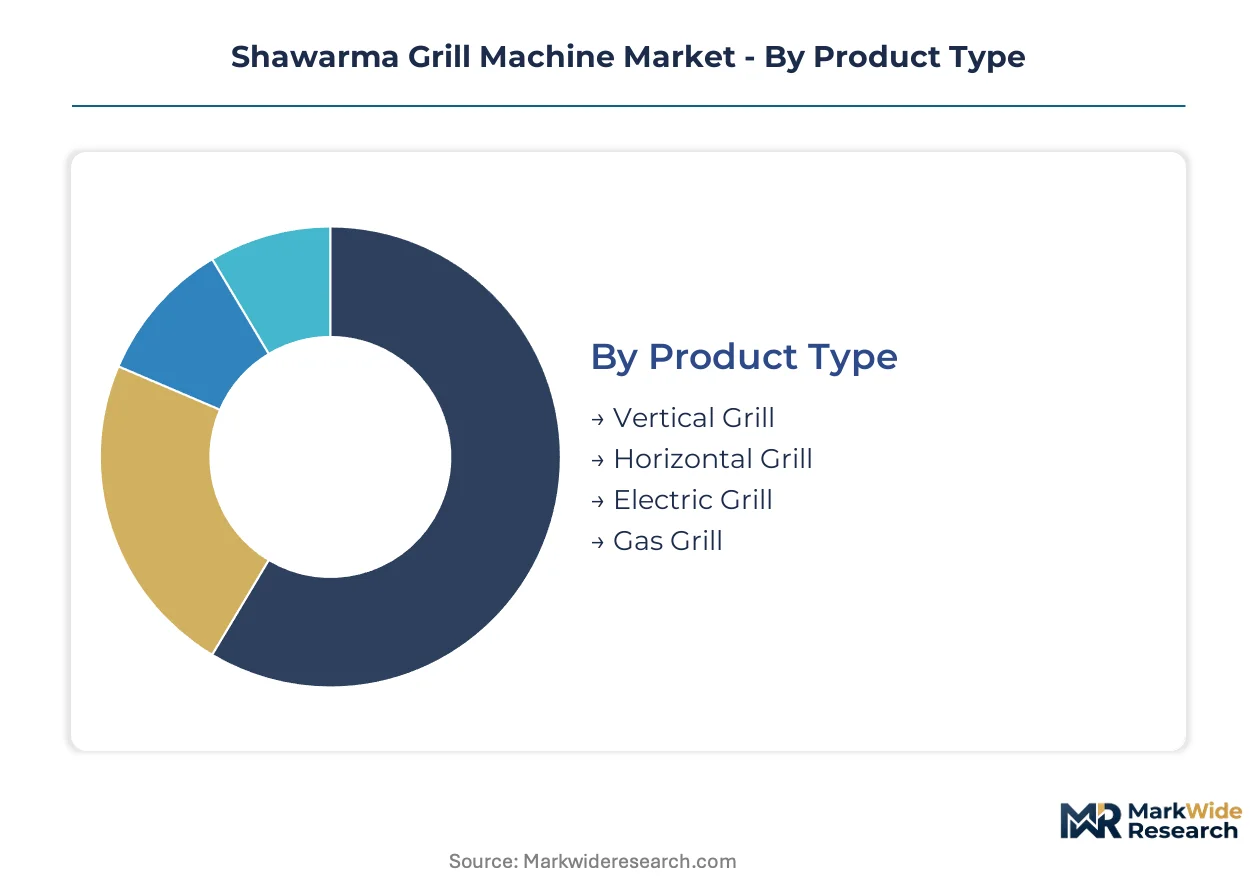
Aftermarket service intensity varies sharply across shawarma grill configurations, with vertical architectures demanding specialized maintenance contracts that reshape distributor margin structures. Product type and power rating segmentation determines replacement part predictability and technician training requirements.
Product Type:
Vertical grill systems generate the densest aftermarket revenue streams due to motor assembly wear and spit bearing replacement cycles.
- Vertical Grill:Rotating spit architectures with infrared or ceramic burner systems reaching surface temperatures exceeding 300°C dominate full-service restaurant installations. Demand concentrates in Turkey and Germany where traditional shawarma preparation sustains dense equipment replacement cycles and NSF International certification requirements elevate specification standards.
- Horizontal Grill:Flat-surface cooking configurations with direct flame contact suit high-throughput commercial kitchens prioritizing batch consistency. Food trucks across Texas and Florida specify compact horizontal units where chassis space constraints limit vertical spit clearance.
- Electric Grill:Infrared ceramic systems with precision electronic ignition serve urban European kitchens facing gas infrastructure restrictions.
- Gas Grill:Propane-dependent architectures dominate Middle Eastern markets where fuel access remains cost-advantaged.
By volume, vertical grills lead. By growth pace, electric configurations are expanding most quickly.
Power Rating:
Energy efficiency thresholds across European jurisdictions are forcing specification divergence between fixed-output and variable power architectures.
- Low Power:Compact units under 3kW thermal output serve mobile food truck deployments where electrical load limits apply. Caterers in California and Florida specify these configurations for generator compatibility.
- Medium Power:Standard commercial ratings between 3-6kW balance throughput against ventilation requirements in mid-scale restaurants.
- High Power:Industrial-grade systems exceeding 6kW thermal output feature reinforced stainless steel construction for continuous operation. Demand concentrates in high-volume shawarma chains across Saudi Arabia and UAE where throughput dictates specification.
- Variable Power:Modular burner systems with adjustable thermal zones enable precision temperature control for mixed protein stacking. Full-service restaurants in France and Netherlands adopt these configurations to meet EU Green Deal efficiency mandates.
Medium power units dominate installed base. Variable power systems are gaining share fastest.
End User:
Procurement fragmentation is unbundling equipment purchase from after-sales service across mobile dining segments.
- Restaurants:Full-service establishments prioritize NSF-rated stainless steel construction and sealed burner housings for sanitation compliance. German and Belgian commercial kitchen tenders specify electric variants with CE marking validity.
- Food Trucks:Mobile operators specify aluminum alternatives to reduce chassis weight and optimize fuel efficiency. California, Texas, and Florida clusters drive concentrated demand for compact vertical rotisserie units.
- Caterers:Event-service providers favor portable medium-power configurations with rapid setup protocols.
- Home Users:Residential-grade electric grills with reduced thermal output serve enthusiast segments in European urban markets.
Restaurants command the largest revenue pool. Food trucks are climbing the fastest.
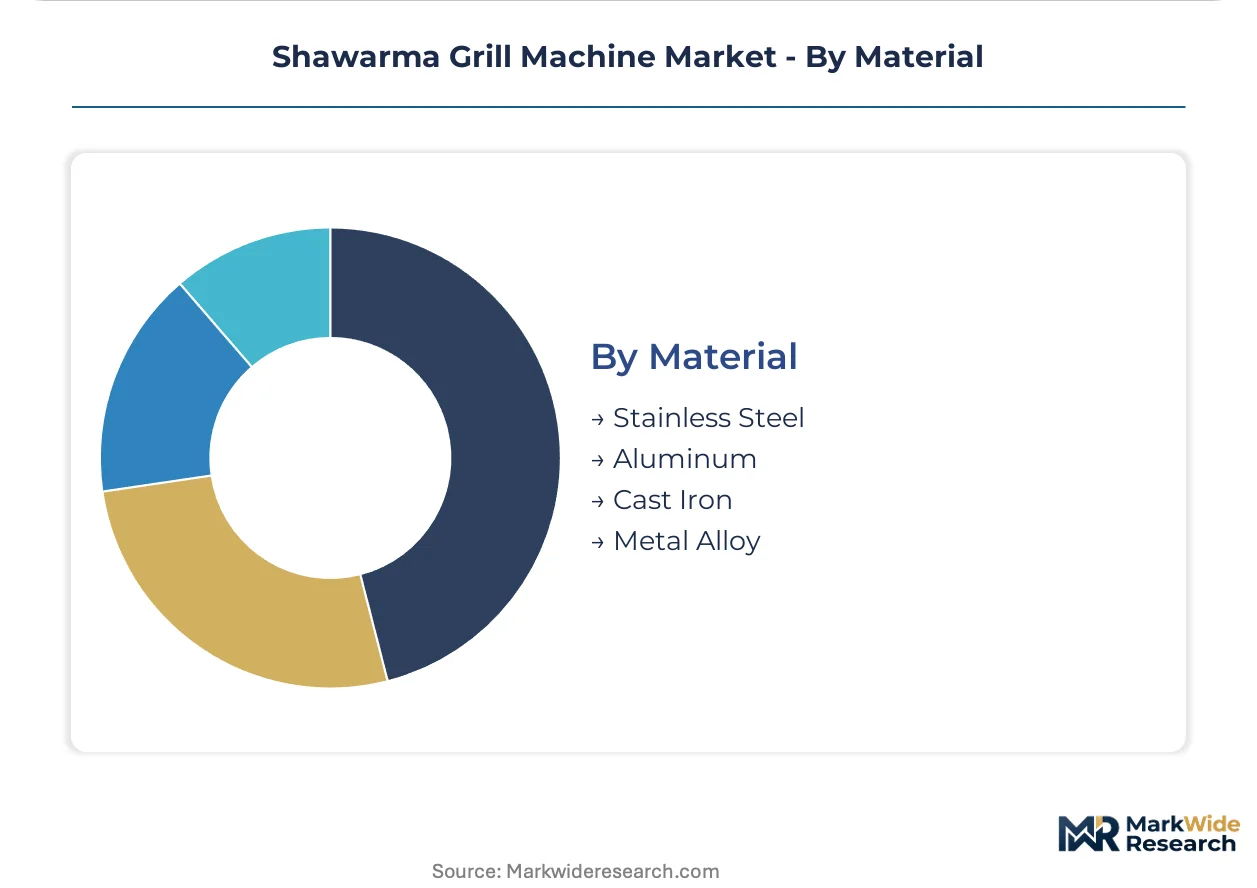
Material:
Weight reduction imperatives in mobile deployments are disrupting traditional stainless steel dominance.
- Stainless Steel:NSF-rated 304-grade construction leads material preference for thermal durability and sanitation compliance. Turkish manufacturing clusters specialize in vertical grill stainless steel fabrication for export markets.
- Aluminum:Lightweight alternatives enable chassis load optimization for food truck operators across North America. Surface coating technologies address thermal conductivity limitations in high-output configurations.
- Cast Iron:Traditional heat retention properties suit horizontal grill architectures in heritage-style establishments.
- Metal Alloy:Hybrid compositions balance thermal performance with fabrication cost in economy-tier product lines.
Stainless steel leads by installed volume. Aluminum is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food truck operators in the United States display acute price sensitivity to upfront equipment costs, while full-service restaurants in Germany absorb premium pricing for electric configurations to satisfy ventilation restrictions.
United States
California, Texas, and Florida mobile dining clusters drive concentrated demand for compact vertical rotisserie units. NSF International certification mandates force equipment upgrades across food truck fleets. Los Angeles and Houston operators specify aluminum alternatives to optimize chassis load and fuel efficiency.
Germany
Urban kitchens in Berlin and Munich face gas infrastructure restrictions that open white space for infrared ceramic burner systems. EU Machinery Directive amendments govern operational guarding and exhaust integration requirements. Commercial kitchen tenders in Frankfurt specify sealed burner housings with CE marking validity.
Turkey
Traditional shawarma preparation sustains dense equipment replacement cycles in Istanbul and Ankara. The Ministry of Industry and Technology enforces domestic manufacturing certifications that shape regional export competitiveness. Local production clusters specialize in vertical grill stainless steel fabrication for European and Middle Eastern markets.
United Arab Emirates
High-volume shawarma chains in Dubai and Abu Dhabi prioritize industrial-grade systems exceeding 6kW thermal output. MOHAP facility licensing requirements elevate sanitation compliance standards. Equipment procurement concentrates in Sharjah industrial zones where Turkish manufacturers maintain distribution partnerships.
France
Full-service restaurants in Paris and Lyon adopt variable power configurations to meet EU Green Deal efficiency mandates. CE marking under the EU Machinery Directive regulates operational guarding requirements. Commercial kitchen tenders in Marseille specify electric grill variants with precision temperature control for mixed protein stacking.
Shawarma Grill Machine Market Competitive Landscape
Specialist fabricators and scale-driven manufacturers split the market into distinct competitive orbits. Turkish production clusters anchor supply-side concentration through dense vertical integration into stainless steel sourcing and burner assembly. European distributors capture aftermarket service revenue through recurring parts contracts. Strategic moves center on geographic expansion through distribution partnerships and product line diversification across gas and electric architectures.
Within the specialist fabricator tier, Fimar and Ozti exemplify divergent geographic positioning strategies. Fimar occupies a position among Italian stainless steel specialists serving European full-service restaurant tenders. Ozti anchors Turkish scale-driven manufacturing from its Anatolian production base. Viatto sits within the European distribution archetype, leveraging network density to capture recurring maintenance contracts detached from original equipment transactions.
| Leading Market Players |
|---|
| Viatto |
| Fimar |
| Atesy |
| Spinning Grillers |
| Ozti |
| Hurakan |
| Eksi |
| Paramount |
| Grill Master |
| Others |
Value Network & Pricing Analysis
Istanbul's dense manufacturing clusters for vertical grill stainless steel fabrication concentrate capacity dynamics that feed downstream pricing power toward Turkish exporters serving European and Middle Eastern markets. Equipment specification divergence between gas and electric architectures creates tiered margin structures where after-sales service contracts displace transactional equipment sales as the dominant profit mechanism.
Pricing Analysis
Recurring parts and maintenance contracts generate the densest lifetime value streams across the Shawarma Grill Machine value chain. Three-tier pricing structure across premium, standard, and economy levels separates NSF-rated stainless steel configurations with sealed burner housings from aluminum alternatives for mobile deployments. Pricing pressure stems from food truck operator price sensitivity in California and Texas markets where upfront equipment costs dominate procurement decisions. Full-service restaurants in Germany and France absorb premium positioning for electric infrared ceramic systems to satisfy ventilation restrictions.
Supply Chain Analysis
304-grade stainless steel feedstock draws from Turkish domestic mills and Italian specialty metal suppliers serving Fimar's fabrication operations. Infrared ceramic burner components and precision motor assemblies for rotating spit architectures rest on sourcing relationships concentrated in Turkey, Italy, and Germany. Single-source vulnerability sits with specialized welding technicians qualified for vertical grill stainless steel fabrication under NSF International and CE marking standards. Distribution runs through specialized commercial kitchen equipment distributors capturing aftermarket service revenue detached from original equipment transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified production workforce availability for infrared burner assembly and vertical grill stainless steel welding constrains capacity expansion across the Shawarma Grill Machine market. Fabrication skill scarcity limits qualified technician pipelines and shapes competitive positioning toward captive training investments.
For Market Incumbents: Insulate margin structures by deepening backward integration into stainless steel sourcing and burner component manufacturing to offset parts-only subscription models from specialized distributors. Capture recurring maintenance contracts through proprietary technician certification programs that lock out third-party commercial kitchen service networks threatening aftermarket revenue displacement. For New Entrants and Emerging Players: Mid-power electric grill configurations for urban European kitchens facing gas infrastructure restrictions represent the most penetrable entry point given specification divergence mandates from EU Green Deal efficiency thresholds. Aluminum alternative vertical grills for North American food truck operators enable chassis load optimization narratives that differentiate against established stainless steel incumbents. Target procurement fragmentation by unbundling equipment from service through third-party maintenance network partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified foodservice equipment conglomerates with underoptimized shawarma grill machine product lines lacking dedicated aftermarket service infrastructure. Long-term viability hinges on electrification transition exposure and European regulatory compliance capabilities rather than gas-dependent Middle Eastern market concentration. Watch CE marking amendment implementation timelines as inflection indicators for product redesign investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Sourcing | Turkish manufacturers secure captive supply of 304-grade material against Italian specialty mill pricing volatility. |
| Electric Product Line Diversification | Infrared ceramic burner development captures specification share in German and French urban kitchen tenders facing gas restrictions. |
| Aftermarket Service Network Expansion | Parts-only subscription models detached from equipment transactions defend distributor margins against procurement fragmentation. |
| Aluminum Alternative Development | Weight reduction configurations penetrate California and Texas food truck clusters where chassis load optimization dictates specification. |
| CE Marking Compliance Investment | Operational guarding redesigns maintain European market access validity under EU Machinery Directive amendments. |
Research Methodology
The analysis maps vertical grill, horizontal grill, electric, and gas configurations, each validated through equipment distributor interviews, commercial kitchen operator procurement heads, aftermarket service technicians, and stainless steel fabrication specialists. Primary fieldwork combined with secondary validation from NSF International certification databases, EU Machinery Directive regulatory filings, Turkish Ministry of Industry and Technology export records, and commercial kitchen equipment trade customs data. Bottom-up installed base estimates triangulated against top-down market sizing across product type, power rating, end user, and material segmentation dimensions.
Assumption sets held electrification mandate intensity and gas infrastructure restriction timelines fixed while varying food truck fleet expansion rates and commercial kitchen replacement cycle acceleration scenarios across the projection horizon. Segmentation modeling incorporated product architecture, thermal output tier, buyer category, and construction material dimensions. CAGRs derived from unit shipment trajectory analysis against average selling price evolution, with forecast inputs including NSF certification upgrade compliance deadlines and EU Green Deal efficiency threshold implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate development for foodservice, propane price volatility, and stainless steel commodity cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and technology substitution rates. Cross-checking against commercial kitchen equipment association shipment reports and food truck licensing authority fleet data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Double Stack Oven Market