
 Clothing Iron Market | 2026-2036
Clothing Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing Iron Market Analysis
The EU Ecodesign Directive is repositioning demand toward lower-wattage, energy-efficient clothing irons across European retail channels. Panasonic leverages its ceramic heating technology leadership to sustain premium positioning in Asian markets. Philips anchors its European presence through compliance-focused R&D and established retail partnerships.
A clothing iron is a heated pressing appliance, typically incorporating an aluminum or stainless steel soleplate with power ratings from 1000W to 2000W, designed to remove wrinkles from fabric through applied heat and pressure. Steam irons dominate household purchases due to faster crease removal, while garment steamers represent the fastest-expanding segment among urban consumers seeking fabric-care versatility without direct contact. Dry irons retain cost-sensitive demand in emerging markets where electricity reliability constrains appliance selection.
The EU Ecodesign Directive and REACH compliance frameworks shape product material choices and energy labeling requirements across Europe, while the US Consumer Product Safety Commission enforces cord-safety standards that influence design specifications for North American imports. China's GB standards and MIIT efficiency guidelines govern domestic manufacturing benchmarks and export certification. Stakeholders must monitor evolving efficiency thresholds and material restrictions to maintain market access across major trading blocs.
Market Dynamics
The EU Ecodesign Directive is compressing power tolerances for household appliances, forcing manufacturers to re-engineer heating elements and soleplate materials while maintaining thermal performance. This regulatory pressure is restructuring R&D allocation across the supply base.
Growth Catalysts
- MIIT efficiency guidelines:China's domestic manufacturing benchmarks are accelerating local production scale and reducing export certification friction for appliance makers targeting Asian retail channels.
- Hotel procurement expansion:Hospitality chains in Southeast Asia are standardizing commercial-grade steam iron specifications across property portfolios, creating volume pull for durable 1800W-2200W units.
- Ceramic heating elements:Advanced alumina-ceramic composite technology is reducing warm-up latency by 40% versus traditional aluminum cores, repositioning premium tier expectations.
Market Restraints
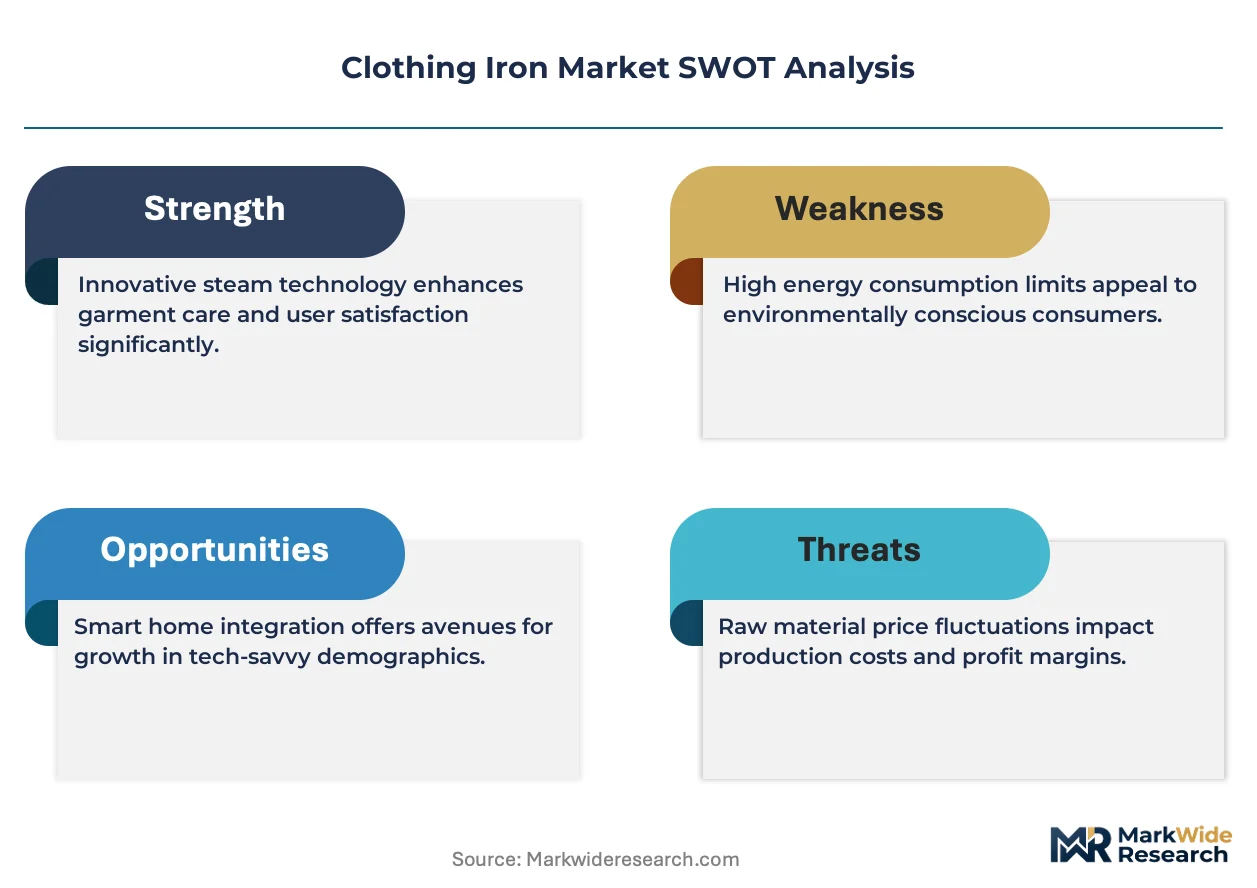
- Aluminum price volatility:Soleplate material costs fluctuate with LME aluminum futures, compressing margin stability for mid-tier manufacturers without backward integration into metal forming.
- REACH substance restrictions:European chemical compliance frameworks are limiting certain anti-corrosion coatings and polymer additives, forcing reformulation of handle assemblies and cord sheathing.
- Garment steamer substitution:Vertical steam appliances are capturing urban apartment demand where storage constraints and fabric delicacy concerns reduce iron purchase intent.
Strategic Opportunities
- Rural electrification corridors:India's grid expansion into tier-3 and tier-4 towns is creating first-time appliance demand among households previously reliant on commercial pressing services.
- Smart home integration:IoT-enabled irons with app-controlled temperature presets and automatic shutoff are expanding into connected-home ecosystems as auxiliary nodes.
- EU Green Deal alignment:Products achieving A+++ energy labeling under updated Ecodesign tiers gain preferential placement in major European retail chains and public procurement frameworks.
Industry Challenges
- Thermal engineering talent scarcity:Specialized expertise in compact heating element design and steam chamber fluid dynamics concentrates among aging cohorts in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of UL, CE, and GB mark approvals extends product launch windows by 8-14 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing Iron Market |
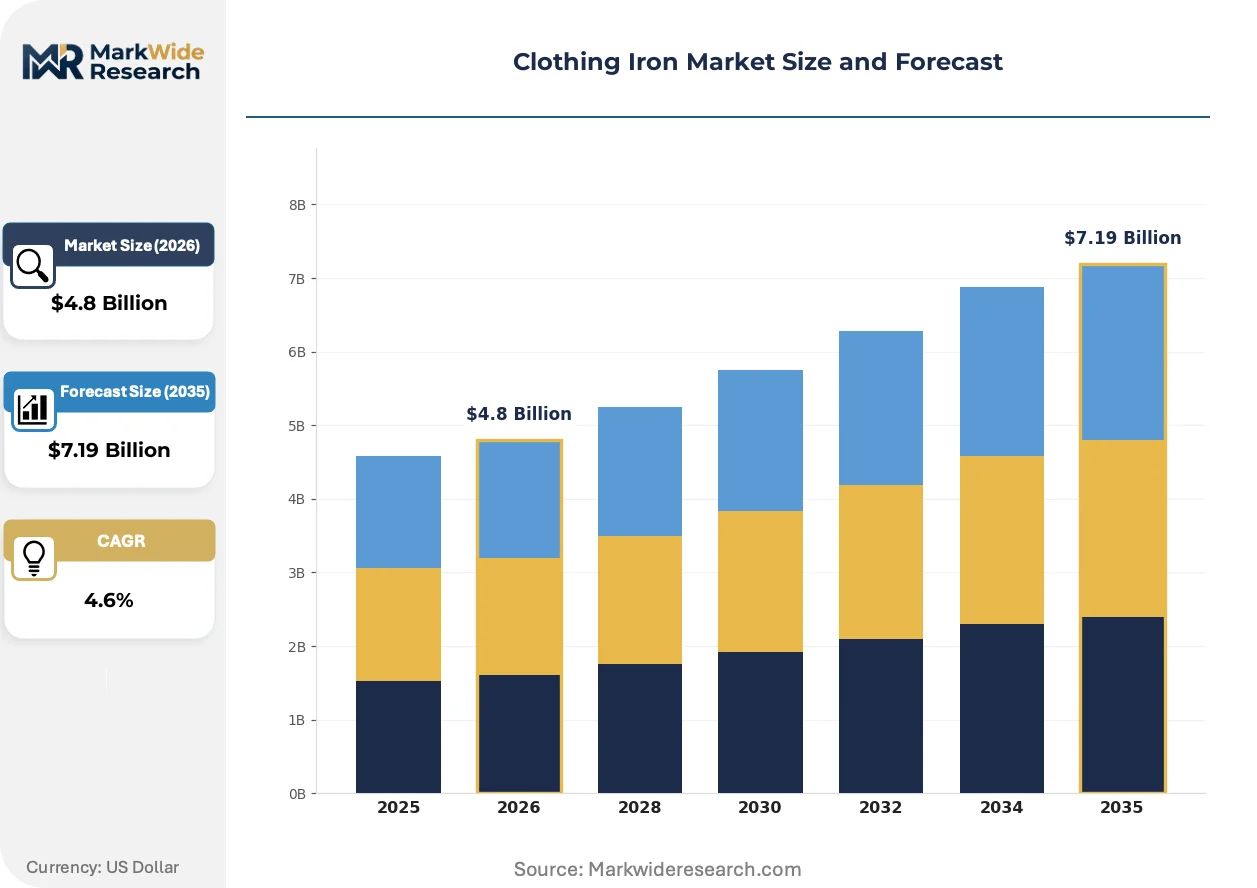
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Iron, Dry Iron, Garment Steamer, Travel Iron End User: Households, Hotels, Retailers, Laundry Services Heating Technology: Ceramic, Stainless Steel, Aluminum, Teflon Power Rating: 1000W, 1200W, 1500W, 2000W |
| Companies Covered | Panasonic, Philips, CHI, Russell Hobbs, Conair, Rowenta, Tefal, Breville, BLACK+DECKER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing Iron Market Emerging Trajectories
Product architecture is bifurcating between precision-engineered premium units and cost-optimized essentials, with connectivity and sustainability features defining the widening gap between tiers.
Ceramic-coated soleplates with embedded microsteam channels are expanding into mid-market positioning, delivering glide performance previously restricted to professional-grade equipment. Boutique hotels and serviced apartment operators are adopting these units at 2-3x the pace of standard steam irons. The technology is expanding into private-label manufacturing for European retail chains seeking differentiation without proprietary R&D investment.
The EU Ecodesign Directive's 2027 efficiency thresholds are mandating standby power below 0.5W and active heating efficiency minimums, forcing redesign of traditional thermostat architectures. Manufacturers are responding with predictive heat algorithms and improved thermal insulation. Premium European product lines face the steepest compliance engineering costs, accelerating consolidation among smaller regional brands.
Urban consumers are unbundling garment care from traditional retail channels, purchasing irons through direct-to-consumer platforms and subscription-box adjacent models. Specialty textile retailers and laundry service apps are inserting appliance recommendations into customer journeys. This pattern is most pronounced in Seoul, Tokyo, and Shanghai, where space-constrained households prioritize curated product discovery over big-box selection.
Clothing Iron Market Segmentation
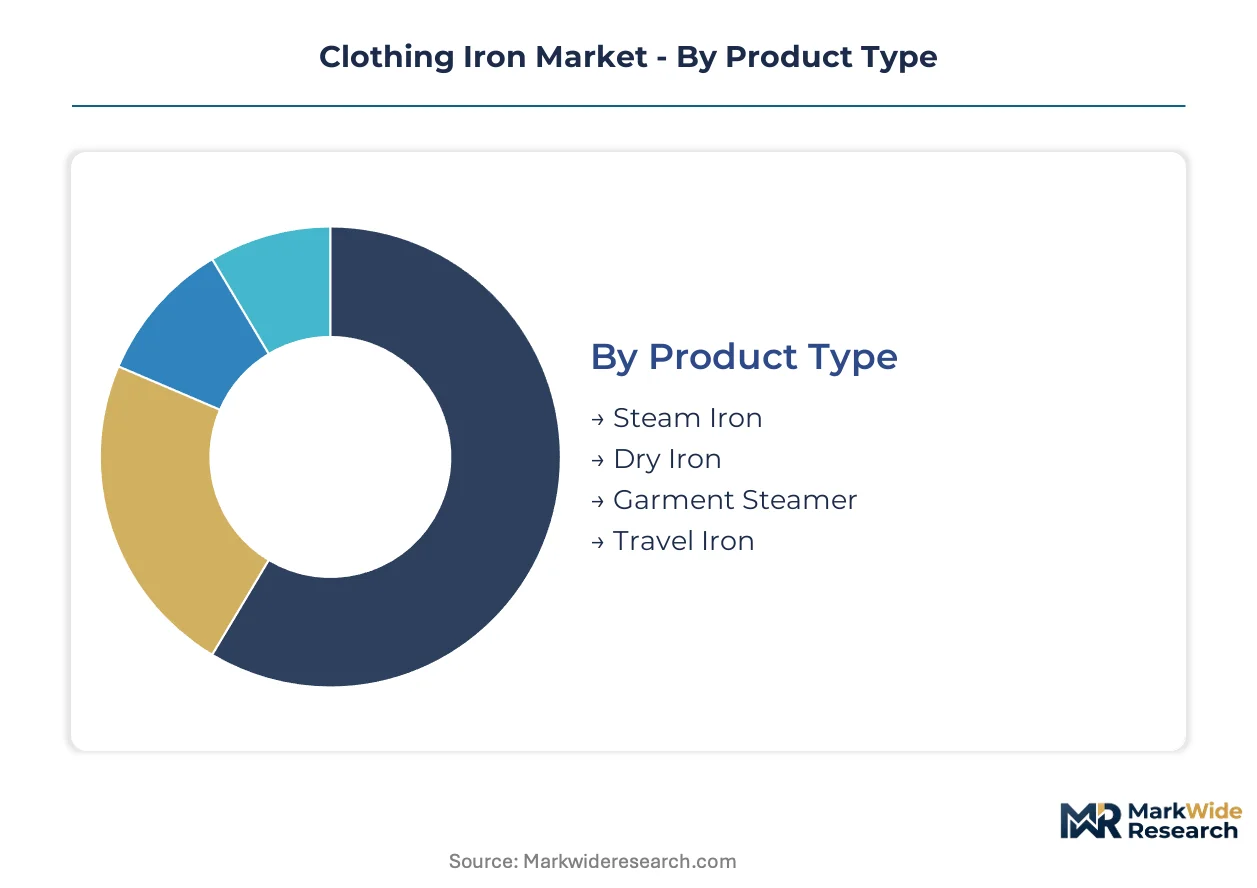
Clothing iron purchasing patterns diverge sharply between replacement-driven household decisions and bulk procurement cycles in hospitality. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where cost engineering dominates supplier selection.
Product Type:
Replacement cycles vary dramatically across product architectures, with steam functionality now standard in urban markets while travel formats exploit portability premiums.
- Steam Iron:Units integrate pressurized steam chambers delivering 20-50g/minute output through micro-perforated soleplates for rapid crease penetration. Demand concentrates in Chinese urban households where MIIT efficiency guidelines favor thermostatically controlled models over basic resistive heating. European procurement is compressing toward A+++ certified units under tightening Ecodesign thresholds.
- Garment Steamer:Vertical steam appliances eliminate soleplate contact through suspended garment hanging systems, reducing fabric scorch risk on delicates. Urban apartment demand in Seoul and Tokyo is displacing traditional irons where storage constraints and silk/wool care requirements intersect.
- Dry Iron:Simpler resistive heating elements without steam generation circuits suit electricity-unreliable environments and price-sensitive first-time buyers.
- Travel Iron:Compact foldable designs with dual-voltage switching target business travelers and hospitality minibars, commanding 40-60% unit price premiums over standard household equivalents.
Steam iron sits at the top of the volume ranking, with garment steamer climbing the fastest.
End User:
Procurement scale and specification complexity separate fragmented household purchasing from concentrated commercial accounts with standardized durability requirements.
- Households:Individual purchase decisions prioritize ergonomic handle design, cord length, and self-cleaning functions. Replacement timing correlates with housing moves and marriage formation in emerging Asian markets.
- Hotels:Southeast Asian hospitality chains specify commercial-grade 1800W-2200W units with anti-drip valves and 3-meter cord sets for housekeeping efficiency. Procurement aggregates through regional distribution contracts with 3-5 year replacement schedules.
- Retailers:Private-label sourcing for European discount chains and Asian hypermarkets demands cost-optimized platforms with cosmetic differentiation through color and handle styling.
- Laundry Services:Commercial pressing operations in India's tier-2 cities require gravity-feed steam systems with 2-liter water tanks, distinct from handheld residential formats.
Households generate the highest absolute unit volume, though hotels are expanding procurement fastest as hospitality development accelerates across Vietnam and Indonesia.
Heating Technology:
Material science differentiation in soleplate construction determines thermal uniformity, glide friction, and corrosion resistance across price tiers.
- Ceramic:Alumina-ceramic composite cores reduce warm-up latency by 40% versus aluminum through superior thermal conductivity and heat retention. Panasonic and premium European lines anchor positioning around this technology in Asian markets.
- Stainless Steel:AISI 304-grade soleplates offer scratch resistance and compatibility with tap water minerals without calcification buildup. German and Italian manufacturers favor this material for professional-grade equipment.
- Aluminum:Cast or stamped aluminum cores with anodized or nickel coatings dominate mid-tier pricing through lower material costs, though LME price volatility squeezes margin stability.
- Teflon:Polytetrafluoroethylene coatings reduce fabric adhesion on budget units, though REACH substance restrictions in Europe are limiting certain polymer formulations in handle assemblies and cord sheathing.
Aluminum commands the highest production volume, with ceramic gaining share fastest as warm-up speed becomes a primary purchase criterion in premium urban markets.
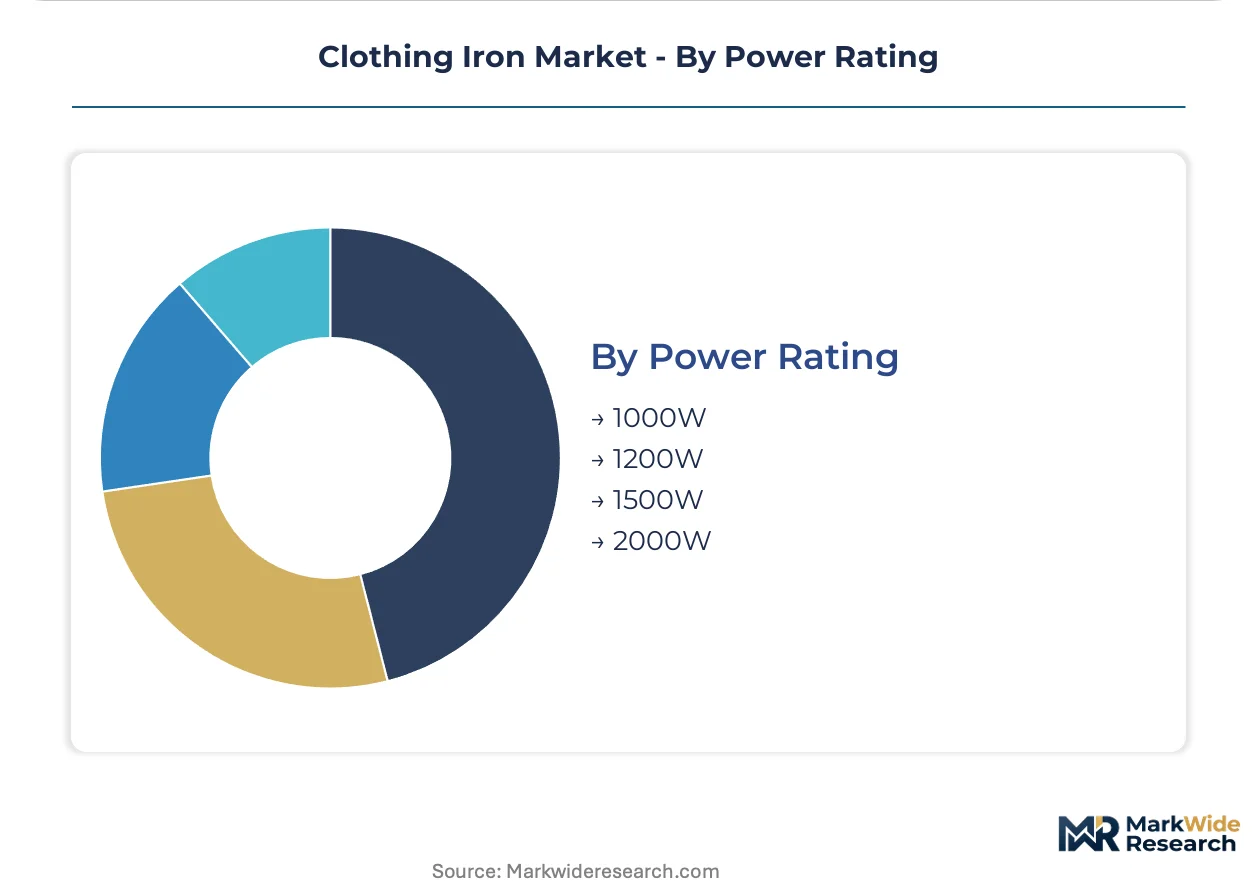
Power Rating:
Regulatory efficiency mandates and grid infrastructure constraints segment demand across wattage bands with distinct geographic concentration.
- 2000W:Maximum residential power draw for rapid heating and steam generation, standard in North American and European markets with robust electrical infrastructure. EU Ecodesign Directive's 2027 standby power limits below 0.5W are forcing thermostat redesign in this tier.
- 1500W:Balanced thermal output for mid-market steam irons, prevalent in Chinese urban households where MIIT guidelines set efficiency benchmarks without prohibiting performance.
- 1200W:Entry steam iron specification for emerging markets with voltage fluctuation concerns, common in Indian tier-3 and tier-4 towns where rural electrification is expanding first-time appliance penetration.
- 1000W:Dry iron and travel format standard, minimizing circuit load in older buildings and generator-powered environments across Africa and South Asia.
1500W occupies the highest shipment volume position, with 1200W expanding most quickly as India's grid extension unlocks new household formation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The clothing iron industry traces its modern manufacturing lineage to early 20th century electrification in Germany and the United States, where industrial-scale metal forming and heating element engineering first converged. Today, production gravity has shifted toward Asian manufacturing clusters while European and North American markets anchor premium consumption and regulatory innovation.
China
Domestic manufacturing scales under MIIT efficiency guidelines are consolidating supply around Guangdong and Zhejiang provinces. GB standards certification now governs both domestic retail and export qualification to Southeast Asian markets. The Yangtze River Delta cluster around Shanghai and Suzhou is absorbing R&D talent from multinational joint ventures.
Germany
Professional-grade equipment demand from commercial laundry operators sustains premium manufacturing in North Rhine-Westphalia. The EU Ecodesign Directive's 2027 standby power thresholds are forcing thermostat architecture redesigns among established appliance engineers. The Stuttgart region retains specialized thermal engineering expertise for ceramic heating element development.
United States
Hotel procurement standardization across Marriott and Hilton portfolios is concentrating volume demand for commercial-grade 1800W-2200W units. The Consumer Product Safety Commission enforces cord-safety standards that shape import specifications from Asian contract manufacturers. Southeast distribution corridors through Atlanta and Miami serve Caribbean and Latin American re-export channels.
India
Rural electrification under the Saubhagya scheme is unlocking first-time appliance demand in tier-3 and tier-4 towns across Uttar Pradesh and Bihar. BIS certification requirements for household appliances are tightening quality thresholds for both domestic producers and Chinese imports. The Delhi-NCR manufacturing belt is scaling assembly operations for 1200W entry steam irons.
Japan
Urban apartment downsizing in Tokyo and Osaka is accelerating garment steamer substitution for traditional irons among space-constrained consumers. METI energy efficiency labeling programs are repositioning consumer preference toward rapid-warmup ceramic models. The Chubu region around Nagoya maintains precision ceramic forming capabilities for premium heating element supply.
Clothing Iron Market Vendor Landscape
Premium-margin players sit above commodity-margin players across heating technology sophistication and soleplate material composition. The vendor base organizes into three tiers: multinational appliance conglomerates with integrated R&D and retail distribution, regional specialists focused on hospitality procurement contracts, and private-label assemblers serving discount retail channels. Consolidation pressure concentrates among mid-tier European brands facing Ecodesign compliance engineering costs. Dominant competitive moves include ceramic heating technology licensing agreements and backward integration into soleplate metal forming.
Among Asian electronics conglomerates, Panasonic exemplifies premium-tier positioning through ceramic heating technology leadership. Philips anchors European market presence through compliance-focused R&D investment and established retail partnerships. Conair occupies a position within North American commercial hospitality supply chains. These three represent divergent archetypes: technology-differentiated Asian multinational, regulation-advantaged European incumbent, and procurement-integrated North American specialist.
| Leading Market Players |
|---|
| Panasonic |
| Philips |
| CHI |
| Russell Hobbs |
| Conair |
| Rowenta |
| Tefal |
| Breville |
| BLACK+DECKER |
| Others |
Supply Flow & Price Mechanics
Hotel procurement concentration across Southeast Asian hospitality chains anchors contract-based pricing with multi-year volume commitments and specification lock-ins. This buyer archetype's aggregated demand creates pricing power asymmetry against fragmented household retail channels where brand premiums dissipate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceramic-heating units with sub-30-second warm-up from aluminum-core mid-market models and dry iron essentials. Price differentiation rests on MIIT efficiency certification tiers and soleplate material grade, with EU Ecodesign A+++ labeling commanding placement premiums in European retail. Cost compression in mid-tier aluminum soleplate manufacturing is intensifying because LME price volatility erodes margin stability for non-integrated producers. Economy-tier buyers in Indian tier-3 towns exhibit highest price sensitivity, while boutique hotel operators absorb premium ceramic technology without elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang province manufacturing clusters for heating element assembly and soleplate metal forming. Ceramic alumina composite cores draw from Nagoya precision forming facilities, while cord sheathing polymers hinge on South Korean petrochemical supply. Tariff exposure runs through US CPSC cord-safety compliance reshaping import specifications. Distribution runs through regional hospitality procurement consortia in Southeast Asia and European retail chain private-label aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic heating technology premiumization and MIIT efficiency compliance cost-downs create margin expansion headroom for positioned players. Supply consolidation around compliant manufacturers reinforces pricing power asymmetry.
For Market Incumbents: Deploy ceramic heating element licensing agreements to capture technology rents while garment steamer substitution threatens traditional iron volume. Backward integration into soleplate metal forming defends margin stability against aluminum price volatility. Ecodesign compliance engineering investments in Stuttgart and North Rhine-Westphalia anchor European market access against consolidation pressure. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms in Seoul and Tokyo where urban apartment downsizing prioritizes curated discovery over big-box selection. India's rural electrification corridors offer white-space penetration for 1200W entry steam irons with BIS certification. Hospitality procurement standardization across Vietnam and Indonesia presents volume aggregation opportunities through regional distribution contracts. For Investors and Strategic Acquirers: European appliance conglomerates are the most active acquirer in this space, targeting mid-tier brands facing Ecodesign compliance engineering cost burdens. Five-to-ten year viability favors manufacturers with captive ceramic heating technology or hospitality procurement integration. Watch for MIIT efficiency guideline threshold revisions as inflection signals for Chinese domestic manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Technology Licensing | Panasonic and premium European lines monetize R&D through technology transfer agreements with mid-tier assemblers. |
| Backward Integration into Soleplate Forming | Captive aluminum and stainless steel metal forming insulates margin stability from LME futures volatility. |
| Ecodesign A+++ Certification Investment | European retail chain preferential placement and public procurement eligibility hinge on updated efficiency thresholds. |
| Hospitality Procurement Contract Aggregation | Marriott and Hilton portfolio standardization concentrates volume demand for commercial-grade 1800W-2200W specifications. |
| Direct-to-Consumer Platform Launch | Seoul and Tokyo urban consumers unbundle garment care from traditional retail through subscription-adjacent discovery models. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance R&D directors, hospitality procurement managers, retail category buyers, and thermal engineering specialists with secondary validation. Customs records, MIIT efficiency disclosure databases, EU Ecodesign registration filings, and hospitality industry procurement databases anchored volume estimates. Bottom-up shipment data from manufacturing clusters in Guangdong, Zhejiang, and Delhi-NCR triangulated against top-down retail audit patterns.
Historical reference periods spanning pre-pandemic baselines through recent efficiency regulatory implementation anchored projection parameters across the analysis window. Segmentation modeling incorporated product architecture, heating technology material composition, power rating bands, and end-use procurement patterns. CAGRs derived from trend extrapolation of technology substitution rates and regulatory compliance cost curves, with ceramic heating adoption velocity and rural electrification penetration as primary forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts affecting aluminum tariff structures and unforeseen breakthroughs in solid-state heating element technology. Forecasts reflect documented assumptions regarding MIIT guideline stability and EU Ecodesign threshold enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Induction Cooktops Market
Appliances
Refrigerator Repair Service Market
Appliances
Mobile Refrigerators Market
Appliances
Mexico Washing Machine Market
Appliances
South Africa Laundry Appliances Market
Appliances
UAE Microwave Ovens Market
Appliances
Oman Microwave Ovens Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Kuwait Dishwasher Market
Appliances
Small Appliances Market
Appliances
Smart Dishwasher Market
Appliances
Electric Hand Dryer Market
Appliances
China Induction Hobs Market
Appliances
North America Washing Machine Market
Appliances
Europe Microwave Oven Market
Appliances
Japan Massage Equipment Market