
 Electric Kettle Market | 2026-2036
Electric Kettle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Kettle Market Intelligence
Buyer concentration among urban apartment dwellers and remote-work professionals is realigning procurement patterns toward compact, feature-rich units. Hamilton Beach Brands leverages broad retail distribution to sustain volume leadership in North America. Zojirushi Corporation anchors premium positioning through precision temperature engineering. Koninklijke Philips N.V. competes across multiple wattage tiers with connected-kettle variants.
An electric kettle is a self-contained vessel with an integrated electric heating element, typically rated between 1200W and 2000W, designed to bring water to boiling point for beverage preparation and light cooking applications. Jug kettles dominate household volume due to ergonomic handling and faster boil times, while travel kettles capture incremental growth from mobile hospitality and compact-living segments. Stainless steel and glass materials command price premiums over plastic alternatives as consumers prioritize durability and aesthetic integration with kitchen environments.
The EU Ecodesign Directive and CE marking requirements shape minimum efficiency standards and electrical safety compliance for European market access. The US Consumer Product Safety Commission and FDA indirect food-contact regulations govern material safety and auto shut-off reliability in American retail channels. Stakeholders must monitor evolving wattage caps and material restriction lists as jurisdictions tighten energy and chemical compliance thresholds.
Market Dynamics
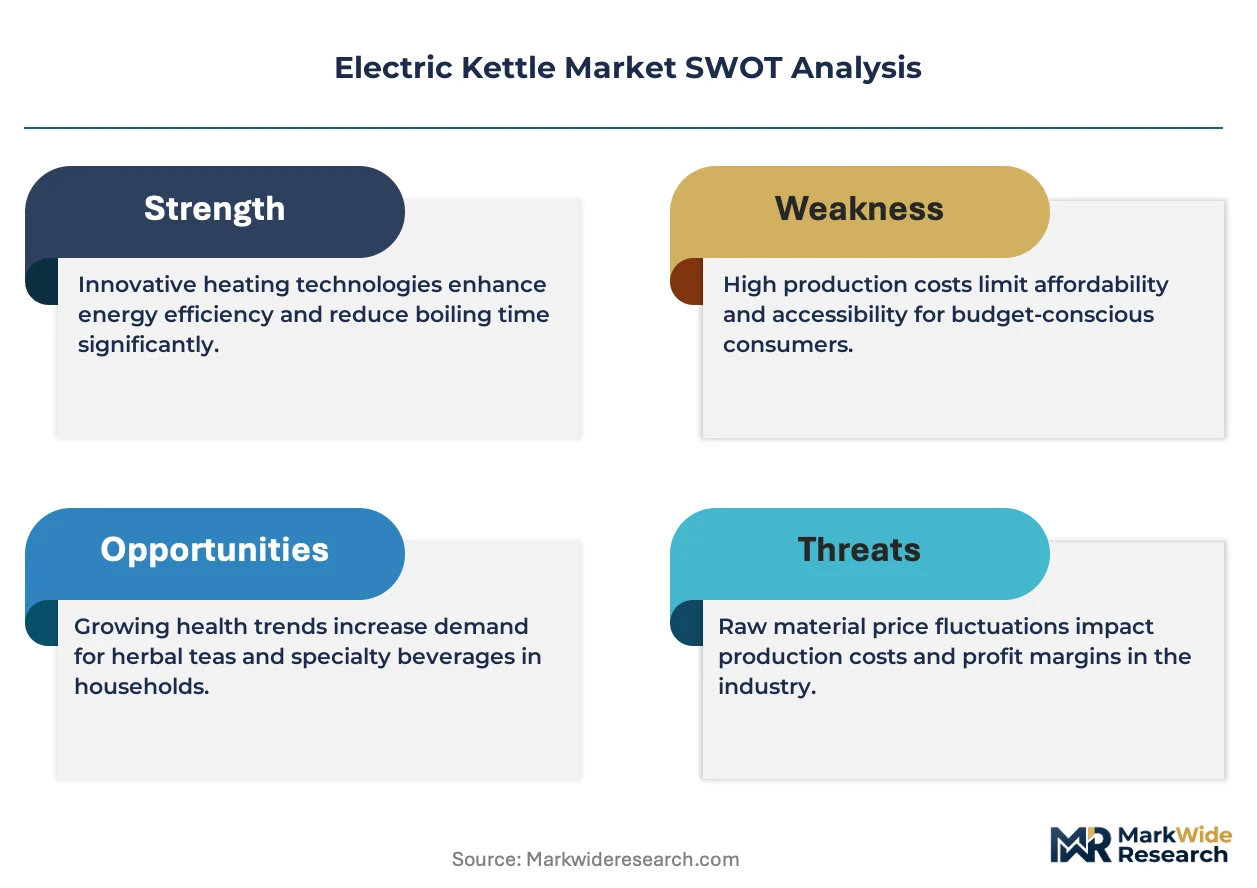
EU Ecodesign Directive wattage caps and material restriction lists are forcing manufacturers to redesign heating elements and housing compositions, compressing margins for suppliers unprepared for compliance retooling.
Growth Catalysts
- Urban apartment densification:Remote-work professionals in compact living spaces demand space-efficient appliances with multi-function capability, pulling unit volume toward 1.0-1.5 liter capacities.
- REACH material standards:European chemical compliance is accelerating substitution of bisphenol-A plastics with borosilicate glass and food-grade stainless steel in premium tiers.
- Dual carbon targets:China's MIIT efficiency mandates are driving rapid adoption of induction-compatible base plates and improved thermal insulation in manufacturing clusters.
Market Restraints
- Copper and nickel price volatility:Heating element wire costs fluctuate with London Metal Exchange pricing, squeezing margin on entry-level plastic models.
- Guangdong supply concentration:Over 60% of global production capacity sits within 200 kilometers of Shenzhen, creating vulnerability to port congestion and power rationing.
- Stovetop kettle substitution:Gas-connected households in Southern Europe and rural North America retain incumbent boiling methods, capping electric penetration.
Strategic Opportunities
- Indian tier-2 urbanization:Cities like Pune and Ahmedabad show underpenetrated electric kettle ownership among middle-class households transitioning from stovetop methods.
- IoT-enabled temperature precision:Integration of Bluetooth connectivity and app-controlled brewing profiles opens wellness and specialty coffee segments.
- Extended Producer Responsibility schemes:EU WEEE directive amendments create first-mover advantage for brands with modular, repairable designs and take-back infrastructure.
Industry Challenges
- Cross-border certification timelines:UL listing for US market entry and CE marking for European access require 8-14 month validation cycles, delaying product launches.
- Thermostat calibration expertise:Precision engineering talent for boil-dry protection and temperature control systems concentrates in Japanese and German component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Kettle Market |
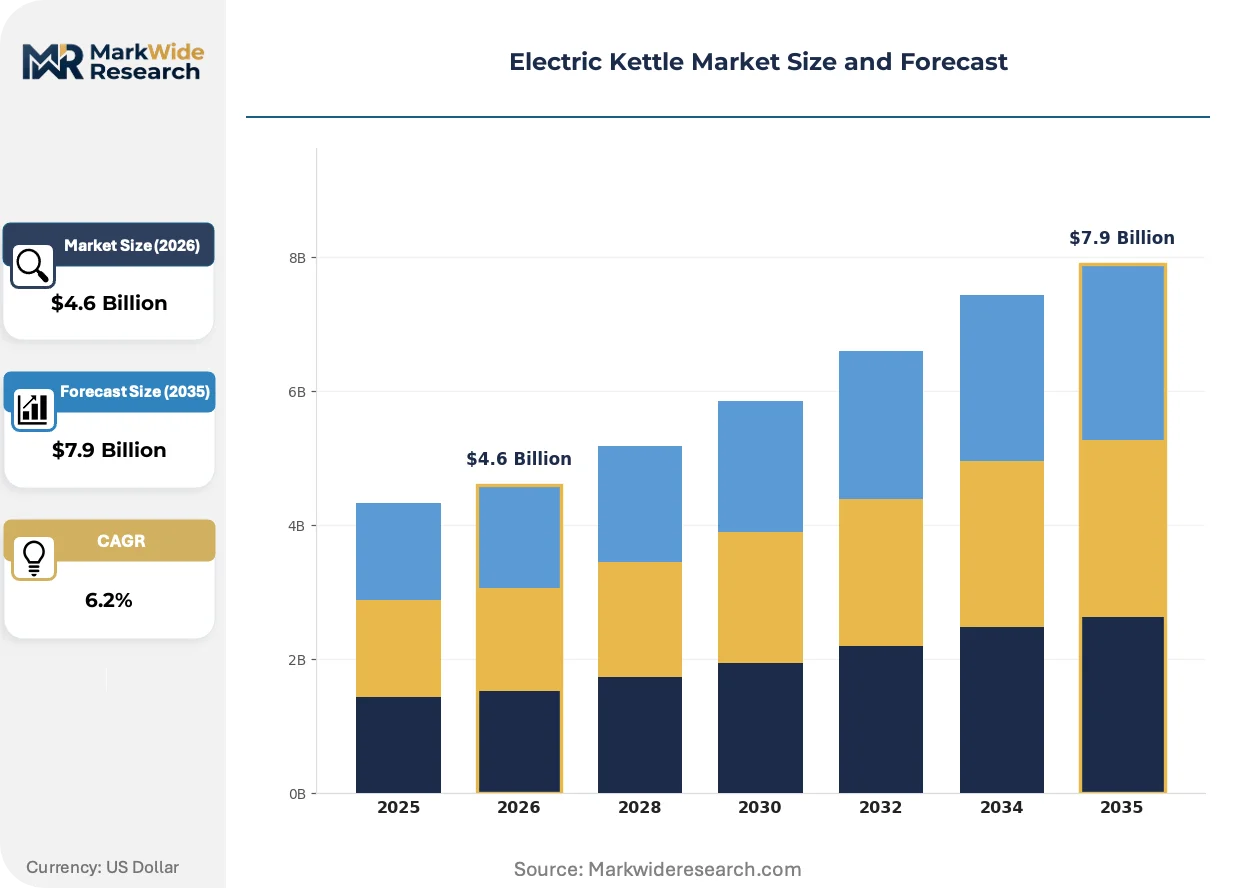
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.9 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jug Kettles, Travel Kettles, Stovetop Kettles, Induction Kettles Material: Stainless Steel, Glass, Plastic, Copper Power Rating: 1500W, 2000W, 1200W, 1800W Feature: Auto Shut-off, Temperature Control, Keep Warm, Cordless Design |
| Companies Covered | Hamilton Beach Brands, Inc., Zojirushi Corporation, Koninklijke Philips N.V., Tefal, Russell Hobbs, Electrolux AB, Cuisinart, Panasonic, Breville Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Kettle Market Strategic Shifts & Innovations
Intelligent temperature control and sustainable material transitions are redefining product architecture, while distribution channels fragment between direct-to-consumer platforms and specialized kitchen retail.
Variable-temperature kettles with digital interfaces and programmable presets are expanding into the specialty tea and pour-over coffee enthusiast segment. Premium buyers in Germany, Japan, and the Pacific Northwest adopt these units at 3-4x the rate of basic boil-only models. The technology is compressing the addressable market for single-function appliances while opening subscription-accessory revenue streams.
REACH Annex XVII restrictions on phthalates and heavy metals in food-contact materials are forcing reformulation of plastic housings and seal gaskets. Manufacturers serving European retail channels now specify Tritan copolyester or uncoated stainless steel to maintain shelf placement. Small-component suppliers in Zhejiang province face capital requirements for testing laboratory accreditation.
Specialty beverage shops and co-working spaces now specify gooseneck spout kettles with flow-rate control for commercial brewing consistency. This procurement pattern displaces traditional hospitality supply contracts and channels volume through B2B kitchen equipment distributors. The shift concentrates in Melbourne, Copenhagen, and Brooklyn where third-wave coffee culture anchors equipment standards.
Electric Kettle Market Segmentation
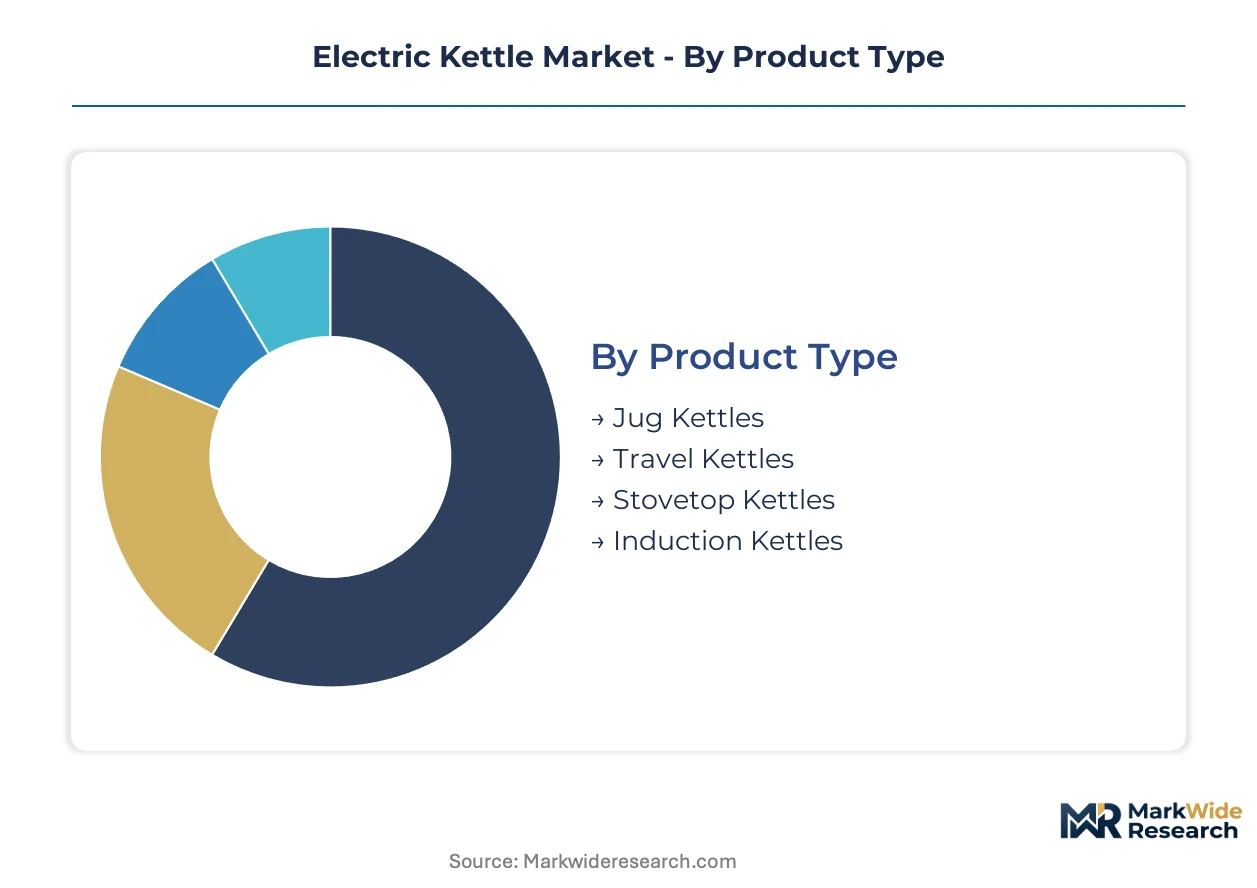
Electric kettle segmentation reveals divergent capital requirements across product architectures and material specifications. Manufacturers must align production investments with distinct compliance burdens and end-use durability expectations.
Product Type:
Jug kettles demand the highest upfront tooling investment due to multi-part molding and integrated base engineering. Travel kettles require minimal capital but face compressed margins from price-sensitive procurement.
- Jug Kettles:Ergonomic vessel designs with integrated heating bases and 1.0-1.7 liter capacities dominate household volume. Urban apartment dwellers in China and Germany favor these units for rapid boil times and countertop stability, though heating element calibration adds manufacturing complexity.
- Travel Kettles:Compact 0.5-0.8 liter units with dual-voltage compatibility target mobile hospitality and remote-work professionals. Demand concentrates in Japanese business hotels and European co-living spaces where space constraints override performance preferences.
- Stovetop Kettles:Traditional vessel designs without electrical components serve gas-connected households in Southern Europe and rural North America where incumbent boiling methods persist.
- Induction Kettles:Ferromagnetic base plates compatible with induction cooktops appeal to efficiency-focused consumers in Germany and the Netherlands pursuing dual carbon targets.
Jug kettles absorb the bulk of installed capacity; travel kettles are expanding most quickly.
Material:
Raw material selection determines compliance pathway and price positioning across regulatory jurisdictions. Stainless steel and glass command premium shelf placement but require supplier qualification investments.
- Stainless Steel:Food-grade 304 and 316 compositions deliver durability and thermal stability for daily-use households. REACH Annex XVII compliance in European retail channels favors uncoated grades over plastic alternatives, though nickel price volatility squeezes margin.
- Glass:Borosilicate constructions with thermal shock resistance target aesthetic-conscious buyers in Pacific Northwest and Japanese markets. Specialty tea enthusiasts value visual water clarity, yet fragility limits commercial hospitality adoption.
- Plastic:Bisphenol-A-free polymers dominate entry-level retail through mass-market distributors in India and Southeast Asia. Ecodesign Directive material restrictions are accelerating substitution in premium European tiers.
- Copper:Antimicrobial properties and rapid thermal conductivity serve heritage-brand positioning in UK and French markets, though oxidation maintenance limits volume penetration.
Stainless steel captures the largest production footprint; glass is climbing the fastest among premium repositioning strategies.
Power Rating:
Wattage tiers align with regional electrical infrastructure and boiling speed expectations. Higher ratings require thicker gauge wiring and enhanced thermostat engineering.
- 1500W:Balanced thermal output for standard 120V North American circuits without dedicated wiring. Remote-work professionals in US urban apartments favor this tier for rental-property compatibility.
- 2000W:Maximum residential wattage for 240V European and Asian markets delivers sub-4-minute boil times for 1.5 liter volumes. MIIT efficiency mandates in China are driving thermal insulation improvements at this tier.
- 1200W:Entry-level rating for budget retail and travel applications where portability outweighs speed. Indian tier-2 urbanization is pulling volume here as middle-class households transition from stovetop methods.
- 1800W:Mid-tier positioning for premium jug designs targeting specialty coffee enthusiasts in Melbourne and Copenhagen where temperature stability matters more than raw speed.
1500W and 2000W ratings together dominate manufacturing allocation; 1800W is gaining share fastest among precision-temperature repositioning efforts.
Feature:
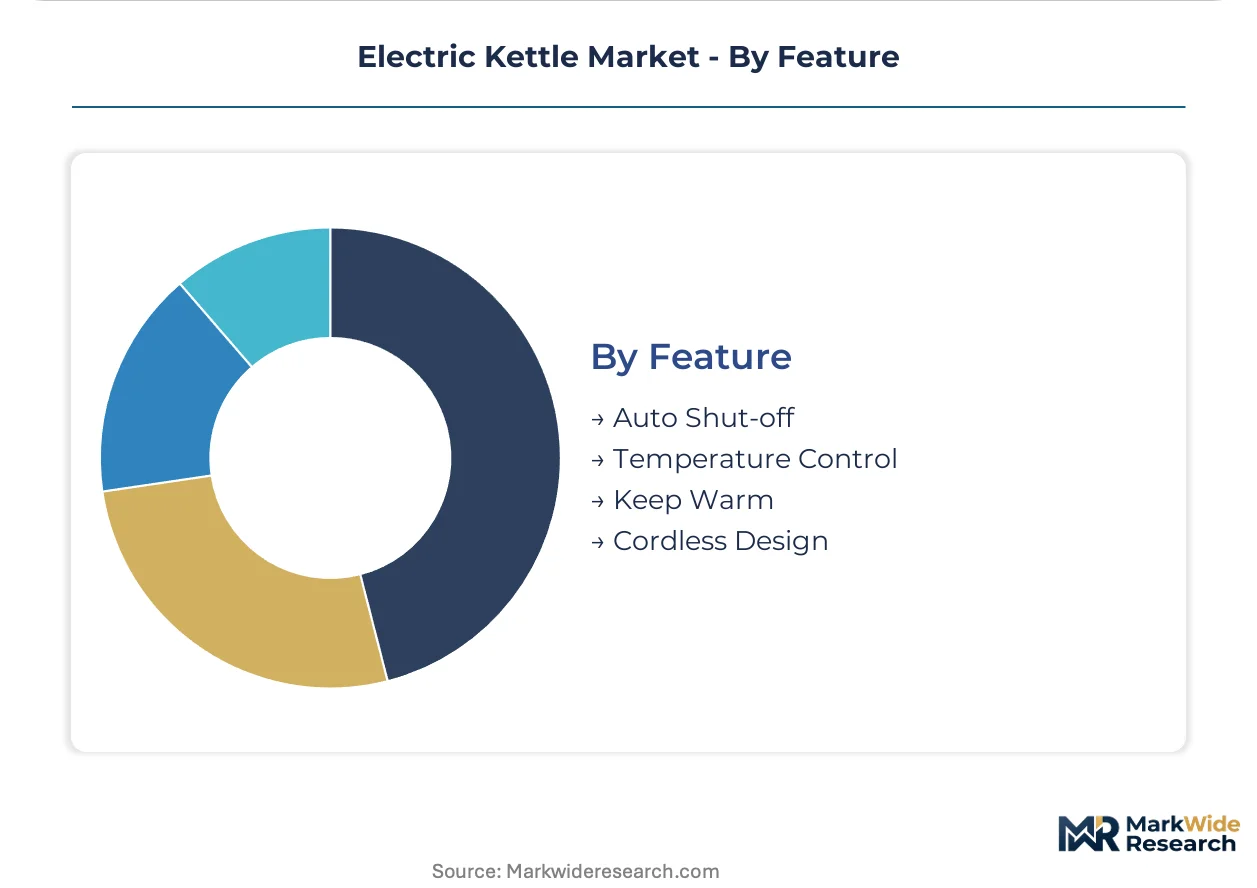
Functional differentiation determines bill-of-materials complexity and aftermarket revenue potential. Smart connectivity and precision engineering require component sourcing from specialized suppliers.
- Auto Shut-off:Dry-boil protection via bimetallic thermostats is mandatory for US CPSC compliance and CE marking. Japanese and German component suppliers concentrate calibration expertise, creating procurement bottlenecks.
- Temperature Control:Digital interfaces with programmable presets for green tea, coffee, and infant formula target wellness segments in Germany and Japan. Bluetooth-enabled variants open subscription-accessory revenue streams.
- Keep Warm:Thermal retention systems maintaining 80-90°C for 30-60 minutes serve multi-beverage households in China and South Korea. Energy consumption trade-offs face tightening Ecodesign Directive scrutiny.
- Cordless Design:360-degree rotating bases with concealed cord storage address ergonomic priorities in compact European kitchens. Zhejiang suppliers dominate base-plate manufacturing.
Auto shut-off commands the widest installed base; temperature control shows the steepest expansion trajectory among specialty beverage enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of electric kettle manufacturing and domestic consumption, while Germany, Japan, the United States, and India represent distinct demand profiles shaped by regulatory frameworks and kitchen culture preferences.
China
Urban apartment densification in Shanghai and Shenzhen pulls unit volume toward 1.0-1.5 liter capacities with rapid boil requirements. MIIT efficiency mandates under dual carbon targets are accelerating adoption of induction-compatible base plates and improved thermal insulation. Manufacturing clusters in Guangdong province, concentrated within 200 kilometers of Shenzhen, anchor over sixty percent of global production capacity.
Germany
Specialty coffee enthusiasts in Berlin and Hamburg drive demand for variable-temperature kettles with digital interfaces and programmable presets. EU Ecodesign Directive wattage caps and REACH Annex XVII material restrictions are forcing redesign of heating elements and housing compositions. Industrial activity in North Rhine-Westphalia and Bavaria supports precision thermostat calibration expertise concentrated among component suppliers.
Japan
Wellness-focused households in Tokyo and Osaka prioritize precision temperature engineering for green tea and infant formula preparation. METI efficiency standards and JIS electrical safety regulations govern product specifications for domestic retail. Zojirushi Corporation anchors premium positioning through boil-dry protection systems sourced from specialized domestic engineering talent.
United States
Remote-work professionals in New York and Los Angeles favor 1500W units compatible with standard 120V rental-property circuits without dedicated wiring. US Consumer Product Safety Commission auto shut-off requirements and FDA indirect food-contact material regulations govern retail channel access. Hamilton Beach Brands leverages broad retail distribution across mass-market and specialty kitchen channels.
India
Middle-class households in Pune and Ahmedabad are transitioning from stovetop boiling methods, pulling volume toward 1200W entry-level ratings. BIS electrical safety certification and FSSAI food-contact material standards create compliance thresholds for organized retail. Domestic procurement concentrates through e-commerce platforms and modern trade formats in tier-2 urban centers.
Electric Kettle Market Key Industry Players
Chinese producers anchor the scale-driven tier; Japanese and European specialists hold premium positioning through precision engineering. The vendor base fragments across mass-market retail distributors, component-integrated manufacturers, and specialty beverage equipment providers. Three archetypes dominate: broad-line kitchen appliance conglomerates, precision temperature engineering specialists, and regional retail-brand licensors. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into connected-kettle variants.
Among Japanese precision specialists, Zojirushi Corporation exemplifies the engineering-focused archetype through its domestic thermostat calibration capabilities. Dutch conglomerate Koninklijke Philips N.V. occupies a position across multiple wattage tiers with connected variants. American mass-market player Hamilton Beach Brands, Inc. anchors volume leadership through retail distribution density. These three represent divergent strategic paths: precision premiumization, multi-tier connectivity, and broad-channel scale.
| Leading Market Players |
|---|
| Hamilton Beach Brands, Inc. |
| Zojirushi Corporation |
| Koninklijke Philips N.V. |
| Tefal |
| Russell Hobbs |
| Electrolux AB |
| Cuisinart |
| Panasonic |
| Breville Group Ltd. |
| Others |
Cost & Logistics Intelligence
Induction-compatible base plate adoption under China's MIIT efficiency mandates is simultaneously raising tooling capital requirements for manufacturers and concentrating procurement leverage among Guangdong suppliers with thermal engineering capabilities. This technology transition compresses margins for plastic-model producers while rewarding stainless steel specialists with pricing power in European REACH-compliant tiers.
Pricing Analysis
Volume-vs-margin splits sharply across material tiers. Three-tier pricing structure across premium, standard, and economy levels separates borosilicate glass and 316-grade stainless steel from BPA-free plastic alternatives. Price differentiation hinges on REACH Annex XVII certification status and wattage tier compliance with EU Ecodesign Directive caps. Cost compression in entry-level plastic models is intensifying because nickel price volatility feeds directly into heating element wire costs. Indian tier-2 households exhibit highest price sensitivity, while Japanese wellness buyers accept premiums for precision temperature calibration.
Supply Chain Analysis
CE marking and UL listing qualification gates create 8-14 month validation cycles that filter supplier participation. Manufacturing concentrates in China, Germany, and Japan. Raw material flows draw from Zhejiang province for plastic housings, Japanese component suppliers for thermostat systems, and German engineering firms for precision calibration. Single-source vulnerability concentrates in Guangdong province where over sixty percent of global capacity sits within 200 kilometers of Shenzhen. Distribution runs through mass-market retail chains in North America, specialized kitchen equipment distributors in Europe, and e-commerce platforms in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric kettle market sits in a technology-transition phase where variable-temperature digital interfaces and IoT connectivity are displacing basic boil-only architectures. Incumbents must navigate this shift while defending against stovetop kettle substitution in gas-connected households.
For Market Incumbents: Anticipate margin compression from REACH material restrictions by accelerating substitution of plastic housings with Tritan copolyester or uncoated stainless steel. Prioritize certification investment in CE marking and UL listing to maintain shelf placement in European and North American retail channels. Vertical integration into thermostat calibration capabilities reduces dependency on Japanese and German component suppliers. For New Entrants and Emerging Players: Capture white-space opportunity in Indian tier-2 urban centers where middle-class households transition from stovetop boiling methods. Specialty coffee shops and co-working spaces in Melbourne, Copenhagen, and Brooklyn represent penetrable B2B segments with flow-rate control requirements. Direct-to-consumer platforms with subscription-accessory revenue streams offer viable go-to-market positioning against entrenched retail distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in precision temperature engineering specialists with proprietary thermostat calibration capabilities and modular repairable designs aligned with EU WEEE directive amendments. Long-term viability favors suppliers with take-back infrastructure and thermal insulation expertise serving dual carbon target jurisdictions. Watch for inflection in copper and nickel price volatility as margin compression signal across entry-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Premium Tier Introduction | Variable-temperature kettles with digital interfaces capture 3-4x pricing multiples in German and Japanese wellness segments. |
| Direct-to-Consumer Launch | Bluetooth-enabled variants with app-controlled brewing profiles bypass traditional retail markups in specialty coffee channels. |
| Sustainability Repositioning | Modular repairable designs aligned with EU WEEE directive amendments secure first-mover advantage in Extended Producer Responsibility schemes. |
| Distribution Channel Expansion | B2B kitchen equipment distributors in Melbourne and Copenhagen displace traditional hospitality supply contracts for gooseneck spout specifications. |
| Backward Integration | In-house production of induction-compatible base plates reduces exposure to Guangdong supply concentration and port congestion risks. |
Research Approach
Independent corroboration across primary interviews with appliance brand managers, category buyers at mass-market retailers, precision thermostat engineers, and supply chain planners underwrites the qualitative findings. Secondary validation draws from MIIT efficiency mandate filings, EU Ecodesign Directive regulatory updates, REACH Annex XVII restriction lists, and customs trade data for heating element wire imports. Bottom-up unit economics triangulate against top-down market sizing across wattage tiers, material specifications, and regional regulatory clusters.
Comparable-period anchoring to historical MIIT implementation phases and EU Ecodesign Directive adoption curves shaped the forecast window construction. The analytical framework models volume and value across product type, material grade, power rating tier, feature complexity, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate convergence analysis incorporating urban apartment densification rates, specialty coffee shop expansion trajectories, and tier-2 urbanization patterns in India.
The model holds under stable nickel and copper pricing conditions; deviation in London Metal Exchange volatility or Guangdong power rationing intensity would shift margin assumptions across entry-level tiers. Forecasts reflect documented assumptions on regulatory timeline adherence and consumer substitution elasticity from stovetop methods. A model refresh is warranted upon material change in EU Ecodesign Directive wattage cap amendments or MIIT dual carbon target acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Electric Rice Cooker Market
Appliances
Bahrain Dishwashers Market
Appliances
GCC Dishwashers Market
Appliances
Commercial Microwave Ovens Market
Appliances
Colombia Laundry Appliances Market
Appliances
Global Massage Chairs Market
Appliances
Europe Garment Steamers Market
Appliances
South Africa Laundry Appliances Market
Appliances
Refrigerator Door Seal Market
Appliances
Hair Removal Appliances Market
Appliances
Europe Induction Hobs Market
Appliances
Global Home Ice Maker Market
Appliances
China Washing Machine Market
Appliances
Electric Rice Cooker Market
Appliances
Europe Microwave Oven Market
Appliances
Automatic Dishwasher Market