
 Global Electric Water Heaters Market | 2026-2036
Global Electric Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Water Heaters Market Analysis
Licensed plumber shortages across Germany and the United States is redrawing installation capacity and pushing demand toward simpler retrofit-ready storage models. Rheem Manufacturing Company leverages its North American distribution network to sustain contractor loyalty programs, while Bosch Thermotechnology anchors its European position through heat pump-electric hybrid development. Haier Group competes on manufacturing scale in Asia, operating integrated facilities that control component costs across the tankless segment.
Electric water heaters convert electrical energy into thermal energy through immersed resistance elements or heat pump compressors, typically achieving energy factors between 0.90 and 3.5 depending on technology class, with primary purpose being reliable domestic and commercial hot water delivery. Storage units retain heated water in insulated tanks ranging from 20 to 120 gallons, whereas tankless systems activate only on flow detection, eliminating standby losses. The residential installation category dominates volume, though commercial applications in hotels and hospitals generate disproportionate margin pools due to scale requirements and service contract attachment.
The US Department of Energy appliance standards and EU Ecodesign Directive jointly constrain minimum efficiency thresholds, forcing incumbents to redesign heating elements and insulation packages. China's GB standards and NMPA-equivalent quality certifications shape export eligibility for manufacturers targeting its domestic market. Stakeholders must monitor regulatory divergence between efficiency mandates in Brussels and Washington, as compliance fragmentation threatens to segment product architectures and strain engineering resources across incompatible certification paths.
Market Dynamics
Heat pump technology integration is compressing the efficiency gap between electric resistance and gas-fired systems, forcing manufacturers to redesign product architectures around hybrid compressors and advanced insulation packages.
Growth Catalysts
- EU Ecodesign Directive tightening:Minimum efficiency thresholds for water heating products are rising, compelling replacement of aging storage units across Germany, France, and Italy.
- China's tier-one apartment density:Gas infrastructure limitations in Shanghai and Beijing favor electric solutions for high-rise residential installations.
- Heat pump compressor advancement:CO2-based systems achieve energy factors above 3.0, expanding addressable market into colder climate zones previously served by fossil fuel.
Market Restraints
- Copper and nickel price volatility:Resistance element and heat exchanger materials expose manufacturers to commodity swings that compress margin on entry-tier products.
- Licensed plumber concentration:Installation capacity constraints in Germany and the United States limit retrofit velocity regardless of product availability.
- Natural gas infrastructure lock-in:Existing piped networks in the Netherlands and United Kingdom create substitution friction for residential electrification.
Strategic Opportunities
- India's urban housing stock:Penetration of organized water heating remains below 15% in secondary cities, creating first-mover positioning for tankless electric systems.
- Commercial heat-as-a-service:Hotels and hospitals in Japan are contracting operational responsibility rather than capital purchase, opening recurring revenue streams.
- Smart grid integration:Demand-response capability aligns with FERC Order 2222 implementation, enabling utility-sponsored installation subsidies in US deregulated markets.
Industry Challenges
- Heat pump refrigeration certification:Technician licensing for flammable refrigerant handling lags equipment deployment, creating installation bottlenecks.
- Legacy electrical panel capacity:Residential service upgrades required for high-amperage tankless units extend sales-to-commission cycles and increase customer acquisition cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Water Heaters Market |
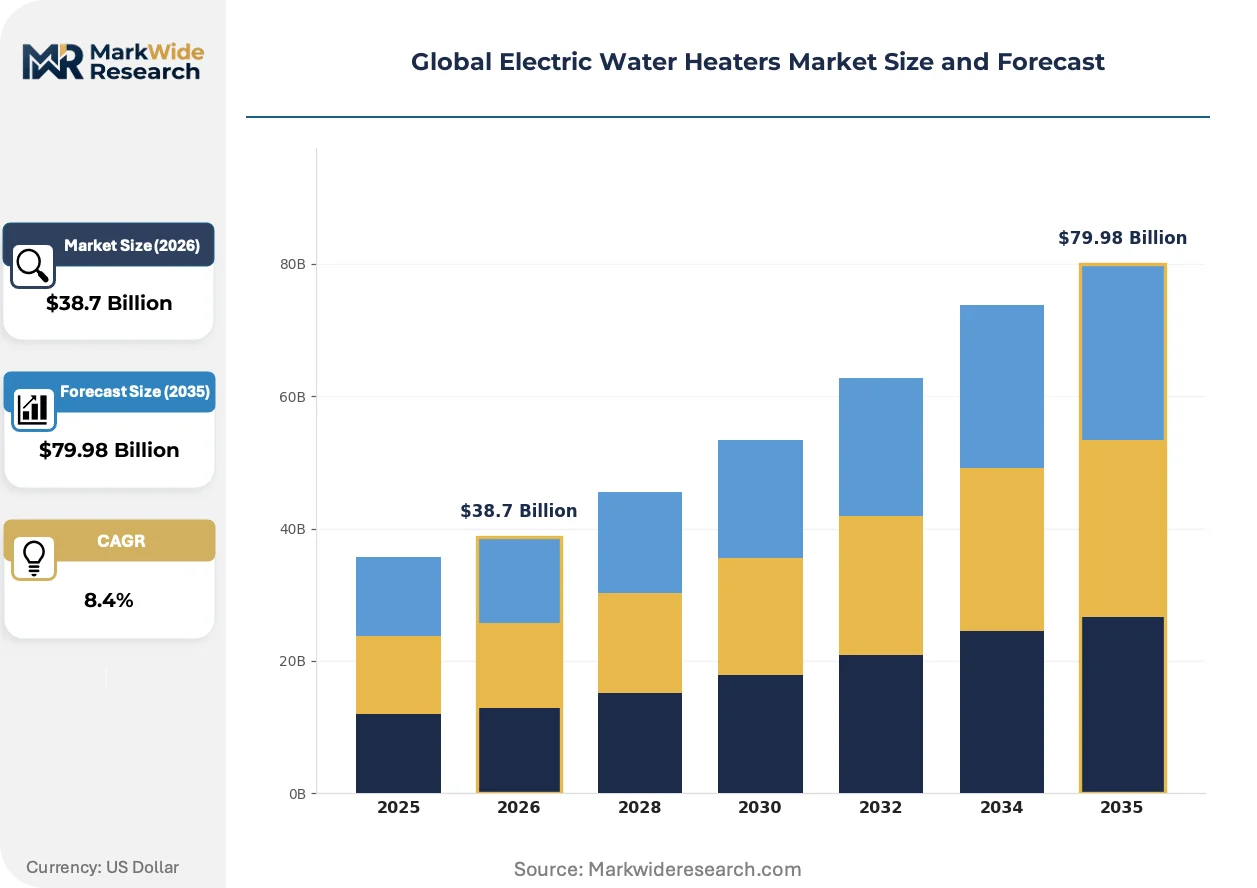
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage, Tankless, Point-of-Use, Hybrid Installation Type: Residential, Commercial, Industrial, Outdoor Energy Source: Electric, Solar, Heat Pump, Others End User: Households, Hotels, Restaurants, Hospitals |
| Companies Covered | A.O. Smith Corporation, Rheem Manufacturing Company, Bradford White Corporation, Ariston Thermo Group, Haier Group, Bosch Thermotechnology, Rinnai Corporation, Midea Group, Whirlpool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Water Heaters Market Emerging Trajectories
Digital control systems and connectivity modules are embedding intelligence into thermal management, shifting competitive differentiation from hardware specifications toward software-enabled optimization and predictive maintenance capabilities.
Condensing heat pump architectures are miniaturizing. These systems extract thermal energy from ambient air using compact scroll compressors and microchannel heat exchangers. Apartment developers in South Korea and Japan specify them for mechanical closet installations where footprint constraints previously excluded heat pump technology. The form factor reduction is miniaturizing addressable market boundaries, enabling penetration into dense urban housing previously reserved for tankless resistance units.
REACH regulation amendments are restricting hydrofluorocarbon refrigerants with high global warming potential. Manufacturers must reformulate working fluids or redesign compressor systems to comply with phasedown schedules. The F-Gas Regulation revision most affects air-source heat pump water heaters sold across Nordic markets, where cold-climate performance depends on refrigerant thermodynamic properties.
Building energy management systems are consolidating control authority. Multi-family developers in Germany and California now specify water heaters with BACnet or Modbus integration as standard, unbundling equipment purchase from controls procurement. This specification shift compresses distributor margins while elevating engineering support requirements for original equipment manufacturers targeting commercial verticals.
Global Electric Water Heaters Market Segmentation
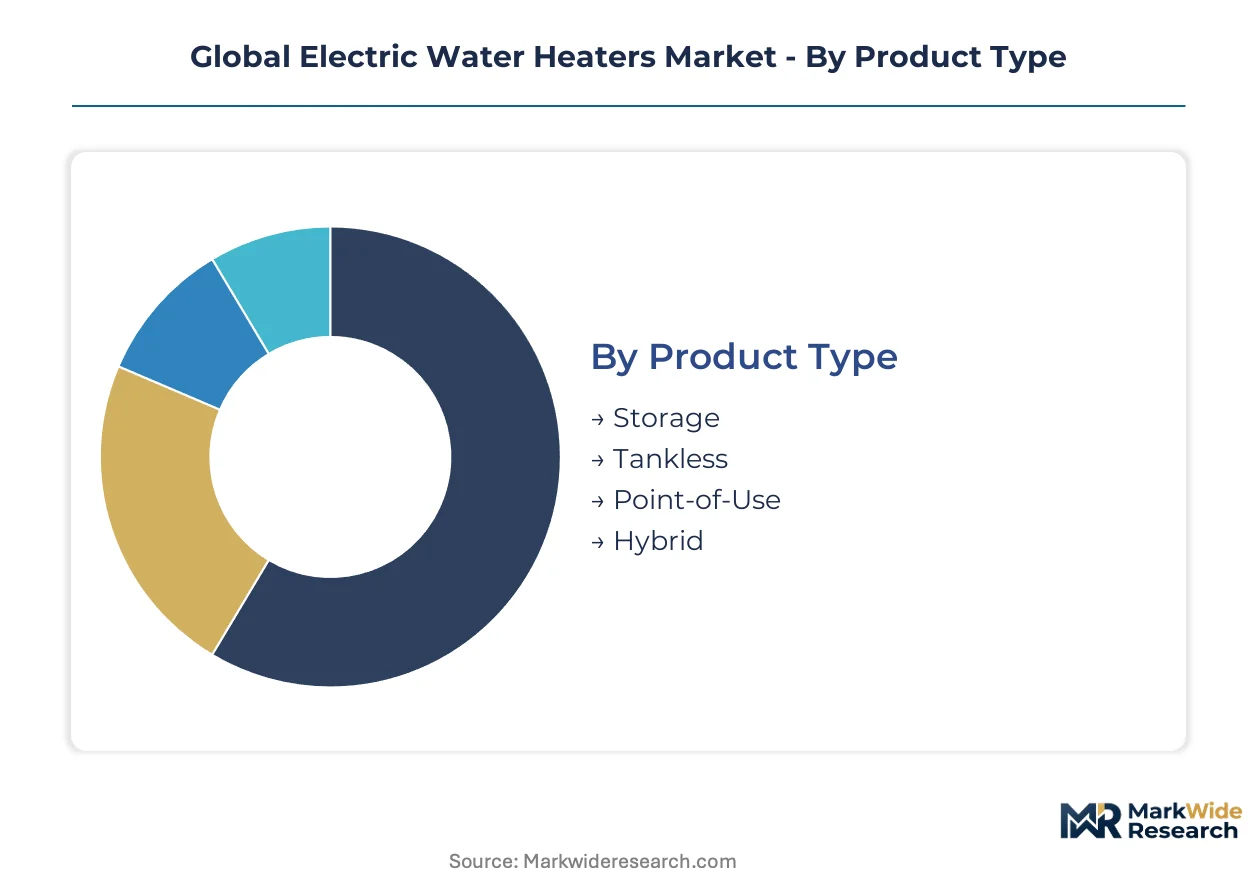
Segmentation in electric water heating reveals how efficiency regulations, installation constraints, and end-use economics reshape competitive positioning. Manufacturers must align product architectures with distinct margin profiles across residential retrofits, commercial service contracts, and emerging heat pump categories.
Product Type:
Margin pools concentrate in systems that command premium pricing through efficiency certification or installation flexibility.
- Storage:Insulated tanks ranging from 20 to 120 gallons retain heated water for on-demand delivery. Replacement cycles accelerate across Germany and Italy as EU Ecodesign thresholds tighten, with contractor loyalty programs sustaining incumbent positions in North American retrofit channels.
- Tankless:Flow-activated resistance elements eliminate standby thermal losses and reduce mechanical footprint. Demand concentrates in Shanghai and Beijing apartment towers where gas infrastructure constraints and space limitations favor compact electric solutions.
- Point-of-Use:Compact under-sink units serve isolated fixtures in commercial kitchens and remote bathroom pods.
- Hybrid:Heat pump-electric combinations achieve energy factors above 3.0 using ambient air extraction. Cold-climate performance improvements expand addressable markets into Nordic zones previously reserved for fossil fuel systems.
The dominant share belongs to Storage, while Hybrid is closing the gap fastest.
Installation Type:
Volume distribution tracks building stock age, energy code stringency, and licensed technician availability by geography.
- Residential:Single-family and multi-family installations dominate unit shipments. Retrofit velocity in the United States and Germany faces plumber shortage constraints regardless of product availability.
- Commercial:Hotels and hospitals generate disproportionate margin pools through scale requirements and attached service contracts. Japan's heat-as-a-service contracting models shift capital expenditure to operational responsibility.
- Industrial:Process hot water systems serve manufacturing facilities with continuous thermal loads.
- Outdoor:Weatherized enclosures serve utility buildings and remote infrastructure in climate-extreme zones.
Residential captures the volume base, though Commercial yields superior per-unit economics.
Energy Source:
Technology selection determines regulatory compliance pathways and cold-climate performance boundaries.
- Electric:Resistance elements deliver energy factors of 0.90 to 0.95 with minimal installation complexity. China's tier-one cities favor electric solutions where apartment density and gas infrastructure gaps limit alternatives.
- Solar:Thermal collection systems with electric backup serve sun-belt residential markets and sustainability-mandated commercial projects.
- Heat Pump:Compressor-based extraction achieves energy factors of 2.0 to 3.5. CO2 refrigerant systems penetrate Nordic markets as F-Gas Regulation amendments phase down high-GWP alternatives.
- Others:Biomass and geothermal hybrids serve niche off-grid and deep-green building applications.
Electric maintains installed base dominance, yet Heat Pump is gaining share fastest on efficiency mandate alignment.
End User:
Customer economics vary sharply between price-sensitive household replacement and commercial lifecycle contracting.
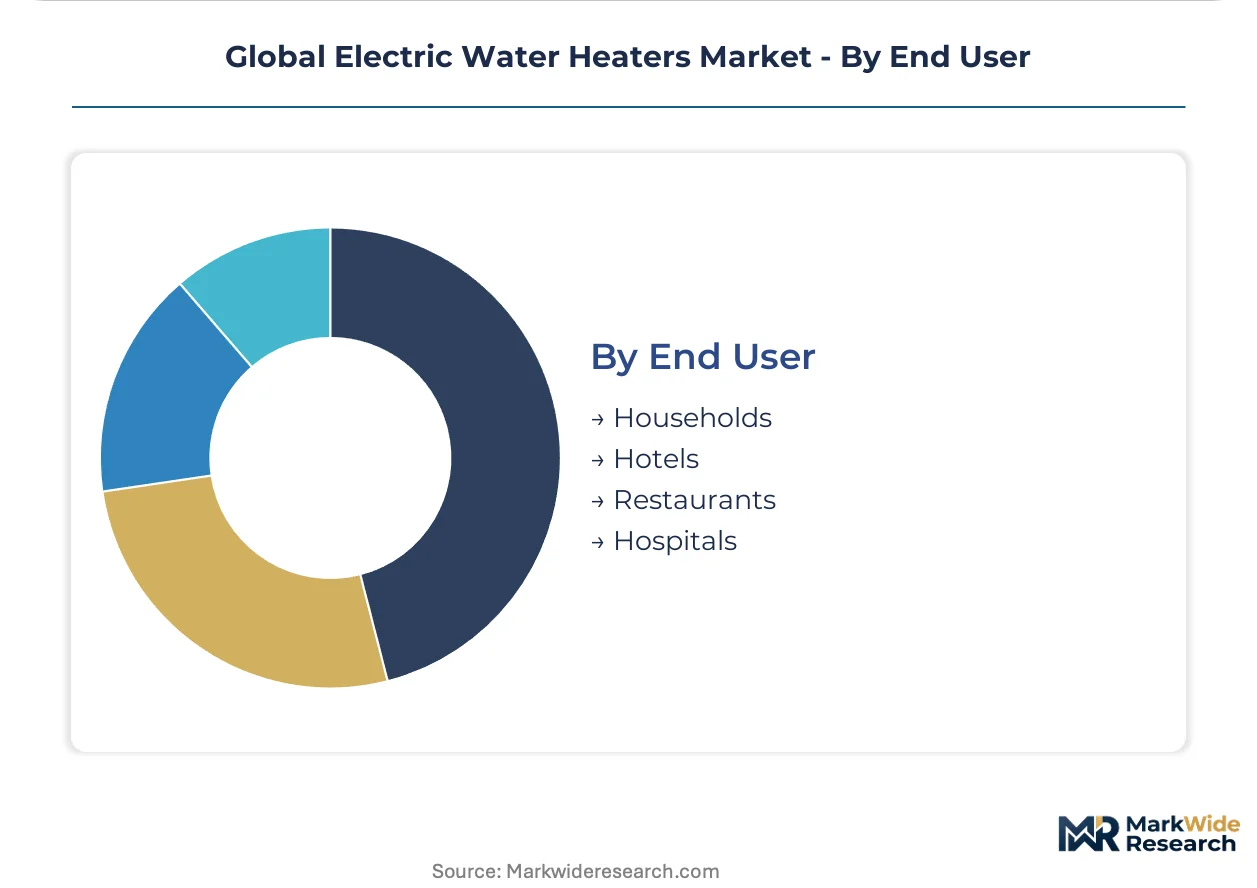
- Households:Individual consumers prioritize first-cost minimization and retrofit compatibility. India's secondary cities present first-mover opportunities where organized water heating penetration remains below 15 percent.
- Hotels:Hospitality operators demand reliability guarantees and operational cost predictability. Japanese hotel chains increasingly contract operational responsibility rather than capital purchase.
- Restaurants:Food service requires high-recovery-rate systems for dishwashing and sanitation compliance.
- Hospitals:Healthcare facilities specify redundant capacity and infection control protocols with 24/7 thermal availability requirements.
Households anchor volume, while Hotels command premium positioning through service contract attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB standards enforcement and dual carbon targets that accelerate electric heating adoption in high-rise residential clusters.
United States
Retrofit demand concentrates in aging suburban housing stock across Texas and Florida where gas infrastructure gaps favor electric resistance units. FERC Order 2222 enables utility-sponsored demand-response subsidies that compress customer acquisition costs for smart-enabled systems. The Southeast corridor from Atlanta to Charlotte exhibits fastest replacement velocity as electrical contractor networks expand installation capacity.
Germany
EU Ecodesign Directive tightening forces replacement of pre-2015 storage units across Bavaria and North Rhine-Westphalia. The country's national building energy regulator enforces efficiency thresholds that elevate heat pump-electric hybrid specifications. Industrial clusters around Stuttgart and Munich drive commercial heat-as-a-service contracting for hospital and hotel verticals.
China
Apartment density in Shanghai and Beijing exceeds 25,000 units per square kilometer, constraining gas infrastructure penetration and favoring compact electric solutions. NMPA-equivalent quality certifications shape export eligibility for manufacturers targeting domestic distribution. The Yangtze River Delta manufacturing belt concentrates tankless production capacity with integrated component supply chains.
Japan
Commercial heat-as-a-service models shift capital expenditure to operational responsibility across Tokyo and Osaka hospitality sectors. METI efficiency standards for water heating equipment exceed global baselines, compressing import eligibility for non-compliant manufacturers. The Kanto region anchors CO2 heat pump deployment in multi-family developments with mechanical closet footprint constraints.
India
Organized water heating penetration remains below 15% in secondary cities including Pune and Hyderabad, creating first-mover positioning for tankless electric systems. BIS certification requirements for electrical appliances shape product eligibility for domestic market entry. Western Maharashtra and Gujarat industrial corridors concentrate manufacturing investment for export-oriented production.
Global Electric Water Heaters Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in manufacturers controlling compressor technology and distribution networks. The structure exhibits moderate consolidation at the top, followed by fragmentation across regional specialists and component suppliers. Two strategic archetypes dominate: vertically integrated appliance conglomerates with captive heat pump compressor production, and plumbing-channel specialists leveraging contractor loyalty programs. Competitive moves center on hybrid system R&D acceleration and strategic partnerships with building energy management system providers.
Among North American fabricators, Rheem Manufacturing Company and Bradford White Corporation exemplify the contractor-anchored distribution archetype. Haier Group and Midea Group occupy positions within the scale-driven integrated tier, leveraging Chinese manufacturing density to control component costs across product categories. Bosch Thermotechnology represents the European heat pump-electric hybrid specialist, with its GmbH structure reflecting German engineering-focused positioning.
| Leading Market Players |
|---|
| A.O. Smith Corporation |
| Rheem Manufacturing Company |
| Bradford White Corporation |
| Ariston Thermo Group |
| Haier Group |
| Bosch Thermotechnology |
| Rinnai Corporation |
| Midea Group |
| Whirlpool Corporation |
| Others |
Supply Flow & Price Mechanics
CO2 refrigerant substitution for hydrofluorocarbons redraws component sourcing geography while compressing margin structures for cold-climate heat pump systems. This dual transformation forces manufacturers to rebalance procurement between established Asian compressor suppliers and emerging European refrigerant formulators.
Pricing Analysis
Long-term offtake contracts dominate procurement for copper heating elements and nickel-plated resistance coils, insulating tier-one manufacturers from spot market volatility. Price differentiation hinges on energy factor certification tier and after-sales service bundling, with EU Ecodesign-compliant hybrids commanding substantial premiums over baseline resistance units. Cost compression in entry-tier storage models intensifies as Chinese exporters leverage integrated component production. Residential retrofit buyers exhibit highest price sensitivity, while Japanese commercial heat-as-a-service contracts demonstrate lowest elasticity due to operational responsibility transfer.
Supply Chain Analysis
China anchors tankless production through Yangtze River Delta manufacturing clusters, while Germany and Japan concentrate heat pump compressor assembly. Raw material dependencies center on copper cathodes from Chilean mines, nickel from Indonesian processing facilities, and rare-earth magnets for high-efficiency motors. Single-source vulnerability in CO2 scroll compressor technology creates procurement bottlenecks for cold-climate hybrid systems. Distribution runs through plumbing contractor networks in North America and specialized HVAC distributors across European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against gas-fired condensing boilers and emerging thermal battery technologies that threaten core electric resistance segments.
For Market Incumbents: Fortify market position through captive heat pump compressor production and accelerated hybrid system certification under tightening EU Ecodesign thresholds. Secure exclusive distribution agreements with building energy management system providers to lock out challenger brands from commercial specification channels.
For New Entrants and Emerging Players: Lead with tankless electric systems targeting India's secondary cities where organized water heating penetration remains minimal. Pursue direct-to-developer sales models in South Korean multi-family construction, bypassing established plumbing contractor networks that incumbent brands dominate.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated appliance conglomerates with in-house compressor technology and established certification pathways across multiple regulatory jurisdictions. Monitor F-Gas Regulation amendment implementation timelines as inflection indicators for refrigerant-dependent asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Compressor Backward Integration | Captive CO2 scroll production insulates margin from refrigerant supply bottlenecks under REACH phasedown schedules. |
| Smart Grid Demand-Response Certification | FERC Order 2222 compliance unlocks utility-sponsored installation subsidies in US deregulated markets. |
| Commercial Heat-as-a-Service Launch | Japanese hospitality contracting models shift capital expenditure to recurring operational revenue streams. |
| Hybrid System Ecodesign Pre-Certification | Early EU compliance secures specification preference as minimum efficiency thresholds tighten across Germany and Italy. |
| India Distribution Channel Expansion | BIS-certified tankless systems capture first-mover positioning in Pune and Hyderabad secondary city markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with product development executives at heating equipment manufacturers, regulatory compliance officers, and licensed plumbing contractors across Germany, the United States, and China; and secondary validation through customs trade databases, EU Ecodesign Directive implementation reports, and SEC filings from publicly traded appliance conglomerates. Bottom-up shipment estimates triangulated against top-down energy consumption projections across residential and commercial building stock.
Across the analysis window, the forecast framework modeled volume and value trajectories across product type, installation category, energy source technology, and end-user vertical. CAGRs derived from regression analysis against regulatory mandate implementation schedules and building retrofit velocity indicators. Cold-climate performance coefficients and refrigerant thermodynamic properties served as technology-specific forecast inputs for heat pump segment sizing.
The analysis sits within stated boundaries; outcomes outside continued EU Ecodesign enforcement, stable copper-nickel commodity pricing, and sustained China residential construction would require recalibration. Recalibration cycles align with material shifts in efficiency mandate timelines and refrigerant regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Japan Massage Equipment Market
Appliances
Personal Care Appliances Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Small Electric Kettles Market
Appliances
Wall Oven Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
United States Microwave Oven Market
Appliances
Hairdryer Market
Appliances
Household Vacuum Cleaners Market
Appliances
Consumer Appliances Market
Appliances
Electric Iron Market
Appliances
Refrigerated Cabinet Market
Appliances
Automatic Dishwasher Market
Appliances
China Induction Hobs Market
Appliances
North America Personal Care Appliances Market
Appliances
Asia Pacific Water Heater Market