
 United States Frozen Yogurt Market | 2026-2036
United States Frozen Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen Yogurt Market Analytics
Franchise leasing and asset-light expansion models are reshaping competitive entry in the United States frozen yogurt landscape. Menchie's Group Inc. leverages a turnkey franchise system that minimizes capital barriers for new operators. Yogurtland Franchising Inc. anchors its growth in high-foot-traffic retail pads across Sun Belt metropolitan areas. TCBY sustains brand relevance through co-location strategies inside convenience retail and travel plazas.
Frozen yogurt is a cultured dairy or non-dairy frozen dessert containing live and active bacterial cultures, typically manufactured through batch freezing at temperatures between negative twenty and negative twenty-five degrees Celsius to achieve a target overrun of twenty to thirty-five percent, serving as a lower-fat alternative to ice cream in commercial foodservice and retail channels. The non-dairy segment is expanding fastest as oat and coconut milk bases displace traditional dairy formulations among lactose-intolerant and vegan consumers. Supermarkets and convenience stores still dominate volume, though food trucks are capturing impulse occasions in dense urban corridors. Margin pools concentrate in organic and probiotic-positioned SKUs where premium pricing offsets higher ingredient costs.
The FDA governs frozen yogurt labeling under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees Grade A dairy sourcing standards that constrain supply chain flexibility for dairy-based producers. State-level health departments enforce varying pasteurization and handling codes that complicate multi-state franchise operations. Stakeholders must monitor evolving clean-label expectations and plant-based certification standards to align product portfolios with shifting consumer trust signals.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing dairy-based frozen yogurt manufacturers toward reformulation, compressing margin structures while opening white space for probiotic-forward and plant-based alternatives in self-serve and retail channels.
Growth Catalysts
- Probiotic-forward formulations:Live and active bacterial cultures are migrating from niche health-food positioning into mainstream self-serve franchise menus, attracting wellness-focused millennials in university dining programs.
- Sun Belt metropolitan expansion:California, Texas, and Florida anchor year-round foot traffic through climate-sustained consumption patterns and high-density retail pad development.
- Non-dairy base innovation:Oat and coconut milk formulations are displacing traditional dairy among lactose-intolerant consumers, expanding addressable demand in urban food halls.
Market Restraints
- Grade A dairy sourcing rigidity:USDA standards constrain supply chain flexibility for dairy-based producers, limiting multi-state franchise agility.
- State-level pasteurization code fragmentation:Varying health department handling requirements across jurisdictions complicate standardized franchise operations.
- Ice cream substitution pressure:Premium ice cream brands capture indulgence occasions through fat-content positioning that frozen yogurt's lower-fat profile cannot match.
Strategic Opportunities
- Food truck channel penetration:Mobile units capture impulse occasions in dense urban corridors where fixed retail footprint costs are prohibitive.
- Clean-label certification alignment:Organic and plant-based certification standards create premium pricing pools that offset higher ingredient costs in supermarket channels.
- Convenience retail co-location:Travel plazas and c-store partnerships extend brand reach beyond traditional mall-based self-serve formats.
Industry Challenges
- Reformulation R&D timeline compression:FDA-mandated label changes force accelerated product development cycles without guaranteed consumer acceptance of taste-profile adjustments.
- Multi-state compliance coordination:Franchise operators must navigate divergent state health department codes while maintaining brand consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen Yogurt Market |
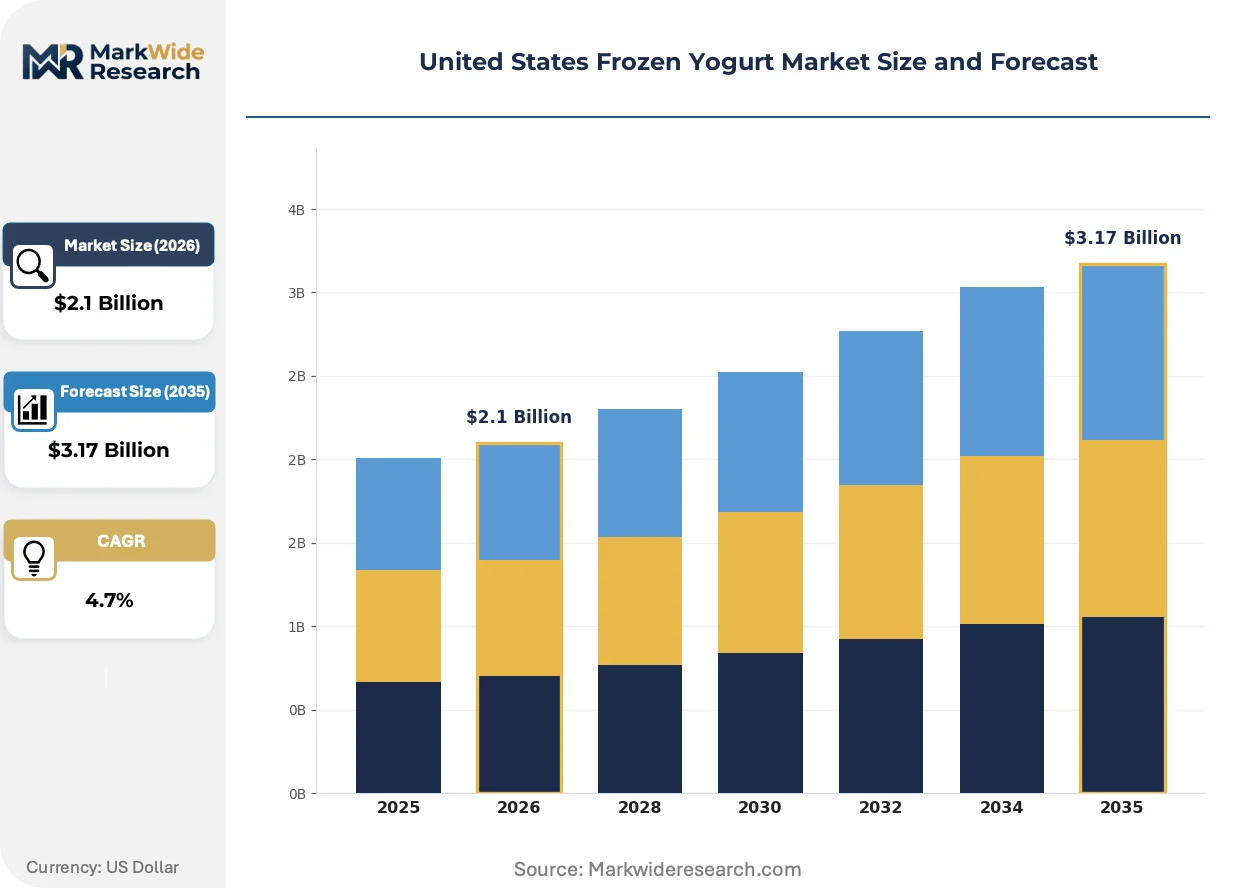
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low-Fat, Non-Dairy, Organic Flavor Category: Chocolate, Vanilla, Strawberry, Mango Distribution Channel: Supermarkets, Convenience Stores, Online, Food Trucks Customer Type: Families, Young Adults, Health Conscious, Students |
| Companies Covered | Unilever, Danone SA, Dairy Farmers of America Inc., Wells Enterprises Inc., Lactalis, General Mills Inc., Menchie's Group Inc., TCBY, Yogurtland Franchising Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen Yogurt Market Evolving Landscape
Three interconnected shifts are restructuring how frozen yogurt reaches consumers: manufacturing technology is pivoting toward plant-based bases, federal labeling mandates are accelerating ingredient transparency, and procurement patterns are fragmenting across emerging channels.
Batch freezing technology is migrating from dairy-optimized systems toward hybrid equipment capable of processing oat and coconut milk bases at negative twenty to negative twenty-five degrees Celsius. Equipment manufacturers are retrofitting legacy lines to handle lower-fat, higher-water-content plant formulations without overrun degradation. This migration from single-base to multi-base capability is enabling co-manufacturers to serve both dairy and vegan brand portfolios from shared facilities.
The FDA's added-sugar disclosure mandate under the Federal Food, Drug, and Cosmetic Act is compelling manufacturers to reformulate recipes or accept degraded shelf positioning. Reformulation toward sugar alcohols and natural sweeteners is compressing formulation flexibility while elevating R&D costs. Dairy-based SKUs face the steepest compliance burden, accelerating investment in alternative base development.
University dining programs and urban food halls are consolidating procurement authority away from traditional distributor relationships toward direct supplier negotiations. Self-serve franchise operators are responding with volume-commitment contracts that bypass regional dairy distributors. This channel disintermediation is most visible in California and Texas, where franchise density supports direct logistics investment.
United States Frozen Yogurt Market Segmentation
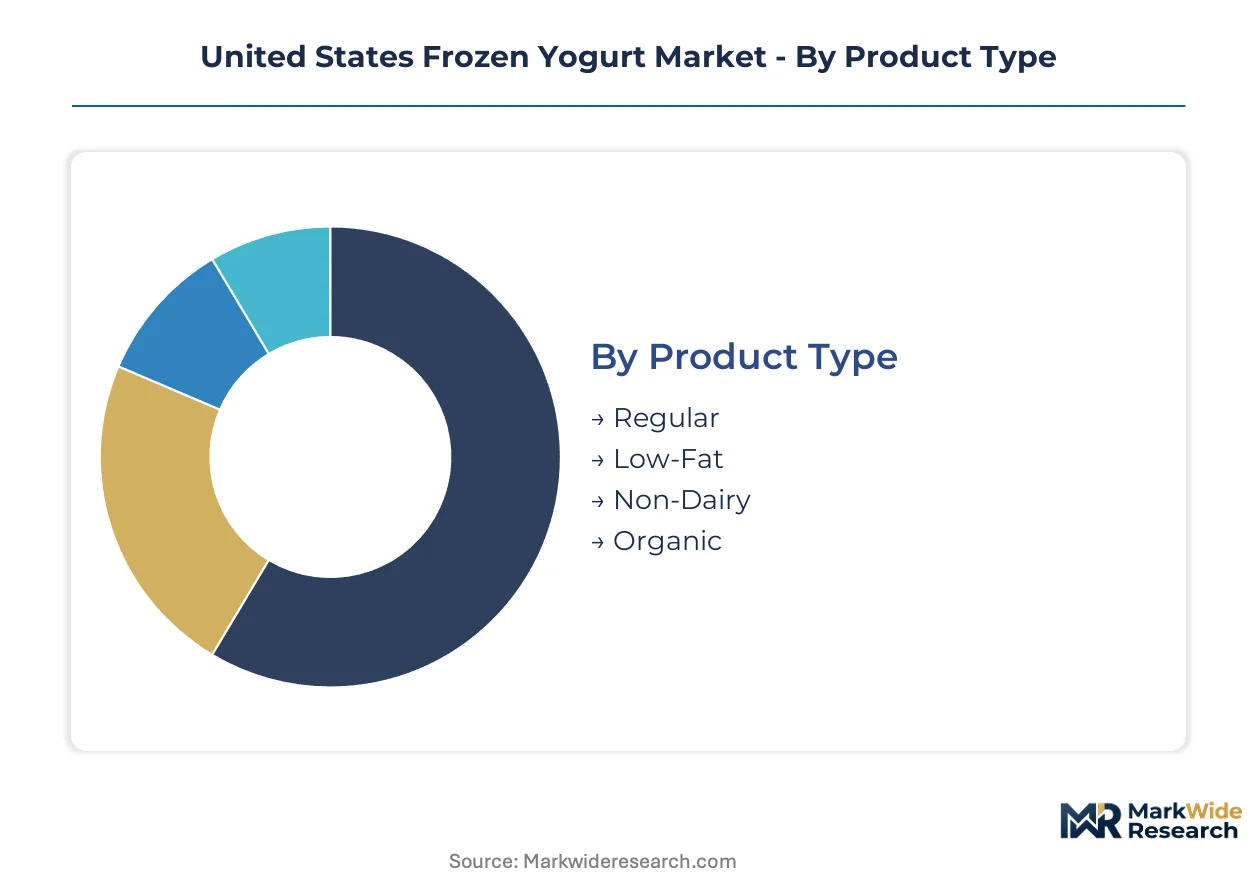
Frozen yogurt segmentation in the United States reflects divergent consumption occasions, from impulse convenience purchases to deliberate wellness-driven selections. Manufacturers and franchise operators calibrate formulation, flavor, and channel strategy against distinct customer priorities that vary by demographic and geography.
Product Type:
Use-case spectrum spans indulgence-driven regular formulations through restricted-diet alternatives, with each tier commanding different margin structures and production complexity.
- Regular:Full-fat dairy base with standard overrun of twenty to thirty-five percent delivers the creamiest mouthfeel. Demand concentrates in Sun Belt mall-based self-serve locations where climate sustains year-round foot traffic and consumers prioritize taste over nutritional restriction.
- Non-Dairy:Oat and coconut milk bases processed at negative twenty to negative twenty-five degrees Celsius serve lactose-intolerant and vegan consumers. California and Texas urban food halls drive fastest adoption as Gen Z and millennial diners seek plant-forward alternatives without sacrificing frozen dessert occasions.
- Low-Fat:Reduced butterfat content meets USDA Grade A standards while targeting calorie-conscious consumers.
- Organic:Certified organic dairy or plant bases command premium shelf positioning in supermarket channels.
Established volume favors Regular; emerging adoption favors Non-Dairy.
Flavor Category:
Flavor preference maps to occasion type and daypart, with classic profiles anchoring baseline volume and tropical variants capturing seasonal and ethnic-food trends.
- Vanilla:Neutral base enables topping customization in self-serve formats, making it the highest-velocity SKU across franchise systems. University dining programs in Florida and Texas specify vanilla as the mandatory flavor for procurement contracts due to its compatibility with diverse consumer preferences.
- Mango:Tropical positioning resonates with Hispanic and Asian-American consumer segments concentrated in California and Texas metropolitan corridors. Food truck operators in Los Angeles and Houston report mango as the top-selling rotating flavor during summer months.
- Chocolate:Cocoa-based formulation competes directly with ice cream for indulgence occasions.
- Strawberry:Fruit-forward profile aligns with clean-label and reduced-sugar positioning.
Vanilla generates the steadiest revenue base; mango climbs the fastest in urban coastal markets.
Distribution Channel:
Channel selection determines margin capture, with fixed retail offering scale economies and mobile formats providing geographic flexibility.
- Supermarkets:Multi-SKU freezer sets in California, Texas, and Florida generate highest absolute volume through repeat pantry-stocking purchases. FDA Nutrition Facts labeling compliance costs are amortized across large production runs, enabling competitive unit pricing against premium ice cream.
- Food Trucks:Mobile units capture impulse traffic in dense urban corridors where real estate costs prohibit fixed storefronts. Austin, Miami, and Los Angeles operators report strongest performance near universities and evening entertainment districts.
- Convenience Stores:Grab-and-go single-serve formats target travel plaza and commuter occasions.
- Online:Direct-to-consumer shipping remains constrained by cold-chain logistics costs.
Supermarkets dominate absolute volume; food trucks gain share fastest in high-rent coastal metros.
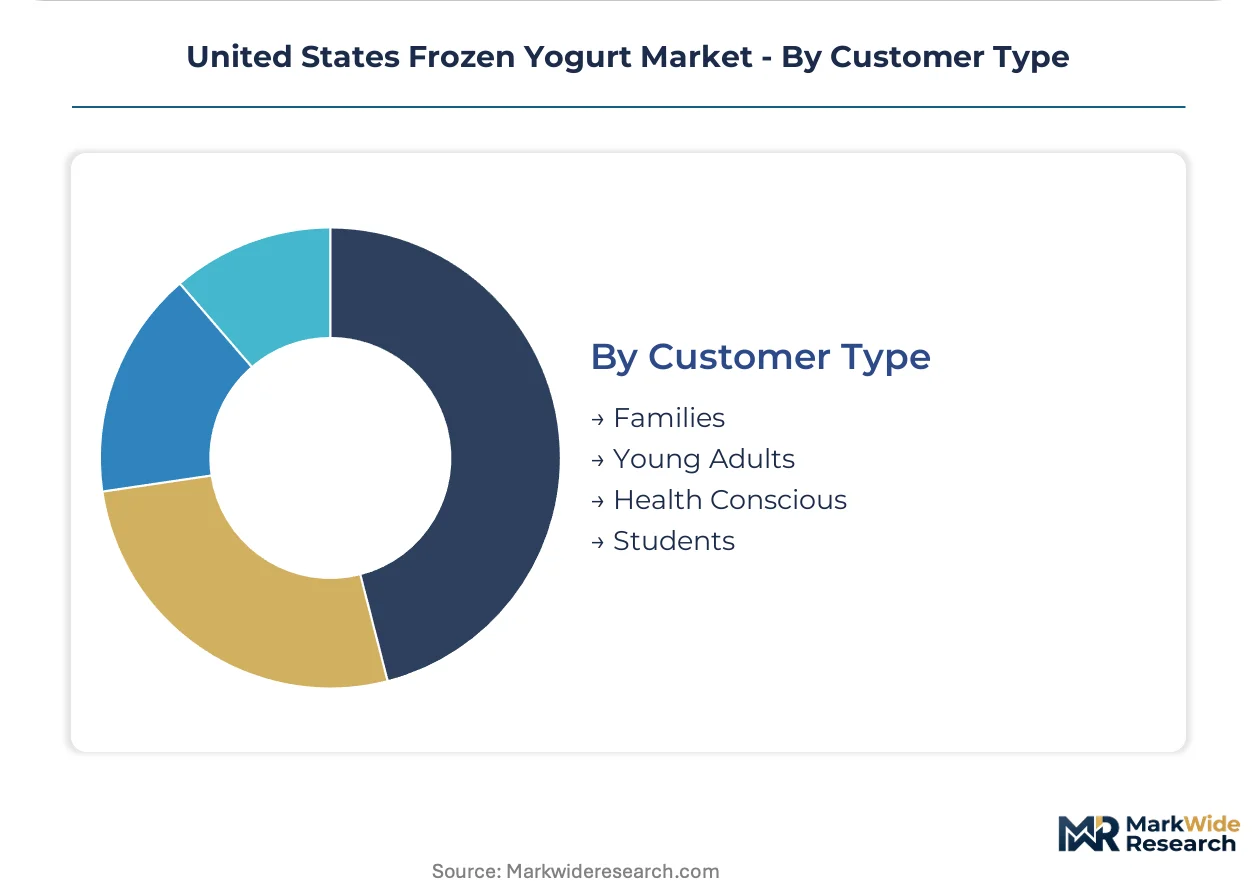
Customer Type:
Demographic targeting shapes flavor innovation, portion sizing, and marketing channel allocation across franchise and retail strategies.
- Health Conscious:Probiotic-forward and reduced-sugar formulations attract millennials willing to pay premium prices for functional benefits. This segment concentrates in California urban food halls and drives R&D investment in live and active culture stability through distribution.
- Students:Price-sensitive demand in university dining programs favors value-engineered formulations with bulk topping bars. Texas and Florida public university systems represent the largest contracted volume outside traditional retail.
- Families:Multi-occasion purchasing spans self-serve weekend outings and supermarket take-home tubs.
- Young Adults:Social-media-visible consumption in Instagram-optimized store environments drives trial.
Health Conscious customers deliver highest margin per transaction; Students provide the steadiest institutional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California and Texas outstrips the Midwest by double-digit margins, reflecting climate-driven demand concentration and franchise density asymmetries that reshape investment allocation across the United States frozen yogurt landscape.
California
Los Angeles and San Francisco food halls anchor probiotic-forward and non-dairy innovation, with Gen Z consumers driving oat milk base adoption. The California Department of Public Health enforces pasteurization codes that exceed federal minimums, complicating multi-state franchise standardization. San Diego's self-serve corridor along Garnet Avenue sustains year-round foot traffic through climate-advantaged positioning.
Texas
Austin and Dallas metropolitan areas concentrate university dining contracts and food truck entrepreneurship, with students generating institutional volume. The Texas Department of State Health Services operates under Grade A dairy sourcing standards that align with USDA requirements. Houston's urban core hosts the densest food truck cluster outside California, capturing impulse occasions near entertainment districts.
Florida
Miami and Orlando retail pads sustain franchise profitability through twelve-month warm-weather consumption, with tourist traffic amplifying baseline demand. The Florida Department of Agriculture and Consumer Services regulates dairy handling with inspection frequencies that vary by county. Tampa's university corridor along Fowler Avenue anchors contracted volume with public dining programs.
New York Metro
Manhattan and Brooklyn food halls drive premium pricing for organic and clean-label SKUs, with health-conscious millennials accepting higher per-ounce costs. The New York State Department of Health enforces labeling requirements that anticipate FDA added-sugar disclosure mandates. Queens mobile operators report strongest performance near transit hubs where fixed retail costs are prohibitive.
Pacific Northwest
Seattle and Portland urban corridors favor plant-based formulations, with vegan consumer density supporting non-dairy SKU development. The Washington State Department of Health coordinates with Oregon authorities on interstate franchise compliance. Portland's food cart pods along Hawthorne Boulevard represent experimental channel formats with national replication potential.
United States Frozen Yogurt Market Competitive Landscape
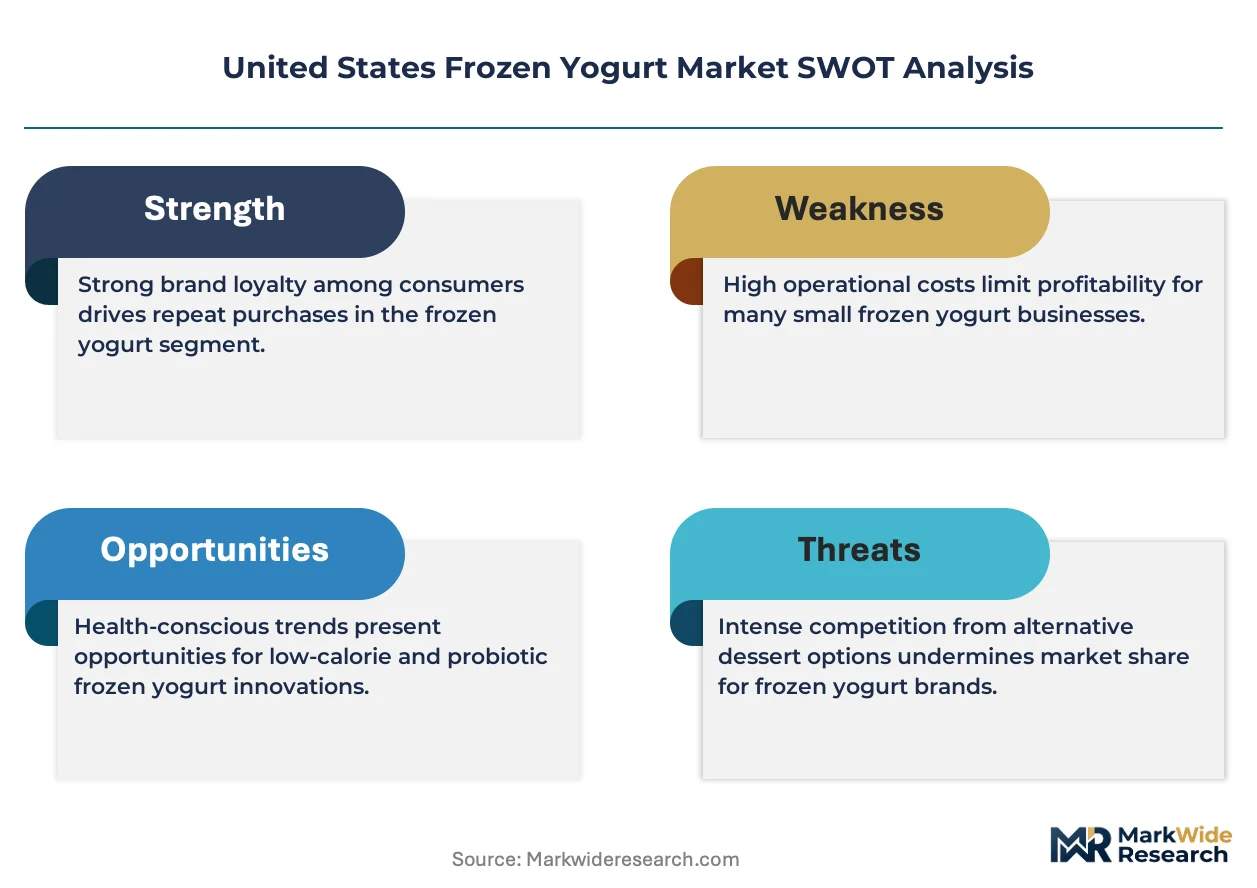
Platform integrators command the system tier; component specialists sit upstream in base formulation and culture supply. The United States frozen yogurt market structures around franchise systems, dairy processors, and retail brand licensors competing through differentiated channel access. Three archetypes dominate: self-serve franchise platforms, co-manufacturing dairy processors, and retail brand licensors. Competitive moves concentrate on co-location partnerships with convenience retail and travel plazas, alongside accelerated reformulation toward probiotic-forward and reduced-sugar positioning.
Among franchise platform operators, Menchie's Group Inc., TCBY, and Yogurtland Franchising Inc. exemplify the asset-light expansion model that minimizes capital barriers for new operators. These companies occupy positions across the Sun Belt metropolitan corridor, anchoring growth strategies in high-foot-traffic retail pads and university dining programs. Their competitive positioning reflects the channel disintermediation visible in California and Texas, where direct supplier negotiations bypass traditional distributor relationships.
| Leading Market Players |
|---|
| Unilever |
| Danone SA |
| Dairy Farmers of America Inc. |
| Wells Enterprises Inc. |
| Lactalis |
| General Mills Inc. |
| Menchie's Group Inc. |
| TCBY |
| Yogurtland Franchising Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Grade A dairy processing capacity across the Midwest is forcing California and Texas franchise operators to absorb premium logistics costs while commanding higher per-ounce pricing in climate-advantaged markets. This regional utilization gap simultaneously constrains supply flexibility and amplifies pricing power for operators with direct supplier relationships.
Pricing Analysis
The customization-premium spread between standard self-serve base pricing and configured-to-order probiotic-forward formulations spans significant margin tiers. Three-tier pricing structure across premium organic, standard dairy, and economy non-dairy levels reflects certification grade and live culture count differentiation. Pricing pressure stems from FDA-mandated added-sugar reformulation costs that compress formulation flexibility without guaranteed consumer acceptance. University dining programs exhibit highest price sensitivity due to volume-contract procurement, while health-conscious millennials in urban food halls demonstrate lowest sensitivity for functional benefit positioning.
Supply Chain Analysis
Extended payment terms from dairy processors to oat milk base suppliers are restructuring working capital requirements across co-manufacturing networks. Supply concentrates in California dairy cooperatives, Midwest Grade A processing facilities, and Southeast coconut milk import hubs. Raw material dependencies span live bacterial cultures, organic dairy solids, and plant-based hydrocolloids. Tariff exposure on imported coconut milk creates single-source vulnerability for non-dairy formulations. Distribution runs through direct franchise logistics in Sun Belt corridors and regional dairy distributors in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States frozen yogurt market represents high-growth disruption as FDA labeling mandates and plant-base innovation simultaneously compress legacy margins and open premium white space. This regulatory-technological inflection rewards operators with reformulation agility and clean-label certification depth.
For Market Incumbents: Insulate core Sun Belt franchise density by securing multi-year Grade A dairy contracts before processing capacity tightens further. Accelerate backward integration into live culture propagation to control probiotic stability through distribution. Co-location partnerships with travel plazas and convenience retail defend against food truck channel erosion.
For New Entrants and Emerging Players: Pursue food truck penetration in high-rent coastal metros where fixed retail costs exclude incumbent franchise formats. Target Pacific Northwest urban corridors for oat milk base experimentation given vegan consumer density. Launch through university dining program direct contracting to bypass distributor markup layers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among self-serve franchise platforms with turnkey operator support systems. Long-term viability over the next decade hinges on reformulation R&D depth and multi-state compliance infrastructure. Acquisition targets should demonstrate direct supplier negotiation capabilities in California or Texas. Monitor FDA enforcement patterns on added-sugar disclosure as the critical inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic Formulation R&D Investment | Live culture stability through cold-chain distribution commands premium shelf positioning in California supermarkets. |
| Non-Dairy Base Capacity Expansion | Oat and coconut milk processing lines enable vegan SKU portfolios that capture Gen Z trial in Texas food halls. |
| Direct Supplier Contracting | Volume-commitment agreements with California dairy cooperatives bypass regional distributor margin layers. |
| Multi-State Compliance Infrastructure | Standardized pasteurization protocols navigate fragmented state health department codes for franchise scalability. |
| Convenience Retail Co-Location | Travel plaza partnerships extend brand reach beyond traditional mall-based self-serve formats in Florida. |
Research Methodology
Initial hypotheses were tested against primary input from franchise operations directors, dairy procurement managers, university dining program contract officers, and state health department inspectors and refined through secondary validation. Primary fieldwork encompassed structured interviews with self-serve platform operators and co-manufacturing facility managers. Secondary sources included FDA Federal Register filings on Nutrition Facts labeling, USDA Grade A dairy production statistics, state health department code compilations, and Nielsen retail audit data. Bottom-up franchise unit economics and top-down category expenditure estimates were triangulated to anchor volume assumptions.
Demand-supply balance modeling incorporated capacity utilization rates at Grade A dairy processing facilities against probiotic-forward SKU growth trajectories. Segmentation dimensions spanned product type, flavor category, distribution channel, and customer archetype across the projection horizon. CAGRs were derived from regression analysis of historical consumption patterns adjusted for regulatory inflection impacts. Industry-specific forecast inputs included live culture viability research timelines and state-level pasteurization code adoption rates.
Sensitivities concentrate around FDA enforcement intensity on added-sugar disclosure and plant-based base ingredient cost volatility. Forecasts reflect documented assumptions regarding consumer taste acceptance of reformulated profiles and franchise operator capital availability for equipment retrofit. Macroeconomic contraction affecting discretionary dessert expenditure, regulatory deviation from proposed labeling timelines, or breakthroughs in culture stabilization technology would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Germany Frozen Snack Market