
 Europe Hyaluronic Acid-Based Dermal Fillers Market | 2026-2036
Europe Hyaluronic Acid-Based Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hyaluronic Acid-Based Dermal Fillers Market Insights
The capital-intensity divergence between integrated manufacturers and contract-dependent peers is rotating competitive advantage toward firms with captive hyaluronic acid fermentation and cross-linked gel production. Allergan Aesthetics (AbbVie) leverages its vertically controlled supply chain to secure batch consistency across European distribution hubs. Galderma Laboratories sustains R&D intensity through dedicated biopolymer research facilities in Switzerland and France. Merz Pharma anchors its position with specialized manufacturing scale for monophasic filler formulations.
Europe hyaluronic acid-based dermal fillers comprise injectable, resorbable gels synthesized through bacterial fermentation of Streptococcus-derived hyaluronic acid, subsequently stabilized via chemical cross-linking with 1,4-butanediol diglycidyl ether (BDDE) to achieve viscoelastic properties measured in Pascals. These formulations restore subcutaneous volume, smooth rhytides, and enhance facial topography through minimally invasive delivery. Non-surgical fillers occupy the dominant revenue position given their alignment with outpatient clinical workflows and reduced recovery protocols. Facial volume restoration leads application demand as aging demographics across Italy and Spain prioritize mid-face rejuvenation. Dermatology clinics capture the highest margin pool through direct-to-patient service bundling and premium pricing for physician-administered injections.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies in Germany and the Netherlands conducting expanded clinical evaluation reviews that extend approval timelines for novel cross-linking technologies. EMA pharmacovigilance requirements mandate post-market safety surveillance for adverse event reporting across all member states. France's ANSM maintains additional national vigilance protocols for aesthetic injectables beyond baseline EU compliance. Stakeholders must monitor evolving MDR guidance on substance-based device classification and prepare for potential re-certification costs that could reshape competitive economics.
Market Dynamics
EU MDR recertification timelines are compressing commercialization windows for novel cross-linking chemistries, forcing manufacturers to front-load clinical evidence generation and restructure quality management systems ahead of 2027 renewal cycles.
Growth Catalysts
- France's ANSM vigilance protocols:Heightened post-market surveillance requirements elevate trust in CE-marked products, accelerating patient willingness to undergo repeat injection protocols in Paris and Lyon aesthetic clinics.
- Streptococcus zooepidemicus fermentation optimization:Yield improvements in bacterial HA production reduce raw material cost volatility for integrated manufacturers operating fermentation assets in Germany and Switzerland.
- Italy's mid-face rejuvenation demand:Aging demographics in Milan and Rome prioritize submalar volume restoration, expanding addressable patient pools beyond traditional nasolabial fold correction.
Market Restraints
- BDDE cross-linker supply concentration:Three chemical manufacturers in Germany and China control 1,4-butanediol diglycidyl ether production, exposing filler producers to input cost spikes during pharmaceutical-grade shortage events.
- EMA pharmacovigilance reporting burdens:Mandatory adverse event documentation across all 27 member states consumes 15-20% of regulatory affairs headcount for mid-tier manufacturers lacking automated vigilance infrastructure.
- Collagen-stimulating injectable substitution:Poly-L-lactic acid and calcium hydroxylapatite alternatives capture volume in patients seeking longer-lasting correction, particularly in Spain's cost-sensitive private clinic segment.
Strategic Opportunities
- Poland's underpenetrated dermatology network:Warsaw and Krakow private aesthetic clinics operate at 40% capacity utilization versus Western European peers, offering first-mover expansion potential for premium filler portfolios.
- Telemedicine-integrated consultation channels:Hybrid virtual assessment and in-clinic injection protocols reduce patient acquisition costs for Netherlands-based medical spa chains targeting time-constrained professionals.
- EU Green Deal biopolymer incentives:Fermentation-derived HA qualifies for sustainable manufacturing tax credits in Belgium and Denmark, rewarding producers with carbon-verified supply chains.
Industry Challenges
- Notified body capacity constraints:Germany's TÜV SÜD and Netherlands' BSI face 18-month backlogs for MDR technical documentation review, delaying novel product launches and freezing R&D amortization schedules.
- Injection technique standardization gaps:Variable cannula depth training across Spain's non-physician injector workforce elevates complication rates and malpractice exposure for clinic operators.
- Legacy ERP integration with UDI compliance:Small Portuguese distributors struggle to embed EUDAMED-compatible traceability modules into existing inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hyaluronic Acid-Based Dermal Fillers Market |
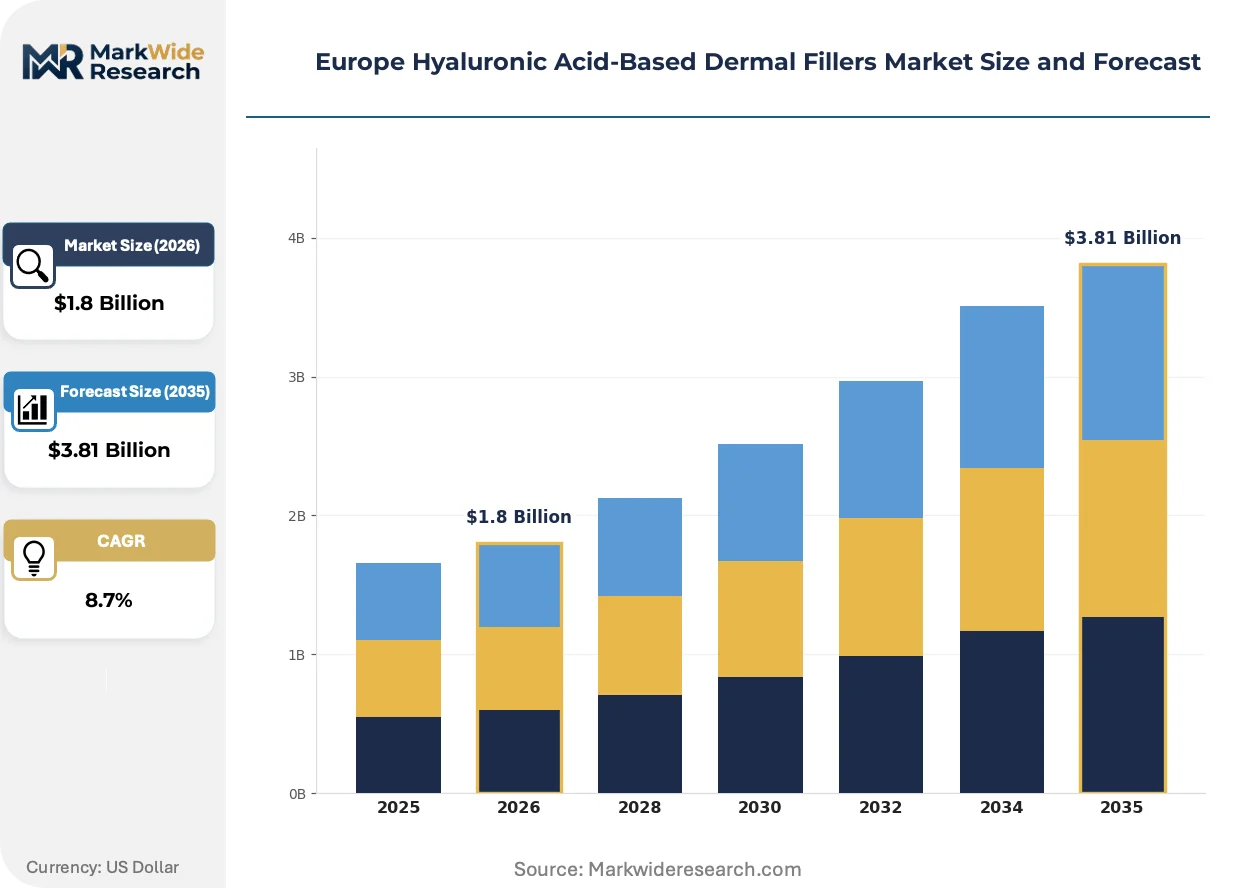
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Surgical Fillers, Surgical Fillers, Semi-Permanent Fillers, Temporary Fillers End User: Dermatology Clinics, Medical Spas, Hospitals, Cosmetic Surgery Centers Application: Facial Volume Restoration, Lip Enhancement, Wrinkle Reduction, Facial Contouring Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Allergan Aesthetics (AbbVie), Galderma Laboratories, Merz Pharma, Laboratoires VIVACY, Teoxane Laboratories, Sinclair Pharma, Genzyme Corporation, Bioxis Pharmaceuticals, Anika Therapeutics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hyaluronic Acid-Based Dermal Fillers Market Trends and Innovations
Cross-linking density modulation and patient-specific rheology matching are displacing one-size-fits-all filler portfolios, while regulatory data requirements reshape competitive investment priorities across the value chain.
Low-molecular-weight HA pre-blending with high-G' gels is miniaturizing injection volumes needed for equivalent aesthetic outcomes. German dermatology clinics in Munich and Hamburg adopt these co-injection protocols for periorbital and lip applications. The technology is miniaturizing unit economics per treatment site, compressing revenue per syringe while expanding patient throughput and repeat visit frequency.
EU MDR substance-based device classification guidance is recalibrating clinical evaluation requirements for novel cross-linking chemistries. Manufacturers must now submit biocompatibility studies beyond ISO 10993 baseline for BDDE alternatives. France and Germany bear the heaviest documentation burden, with notified bodies demanding 24-month implantation data for category III reclassifications.
Direct-to-clinic procurement platforms are fragmenting traditional distributor relationships in the United Kingdom. Aesthetic nurses and independent prescribers in London and Manchester now source fillers through specialized B2B marketplaces with transparent pricing. This channel shift is most pronounced among mid-volume accounts previously captive to regional wholesale agreements.
Europe Hyaluronic Acid-Based Dermal Fillers Market Segmentation
Channel configuration across Europe's hyaluronic acid filler market determines margin capture and regulatory exposure. Product flow through dermatology clinics versus medical spas creates divergent pricing power and service bundling opportunities.
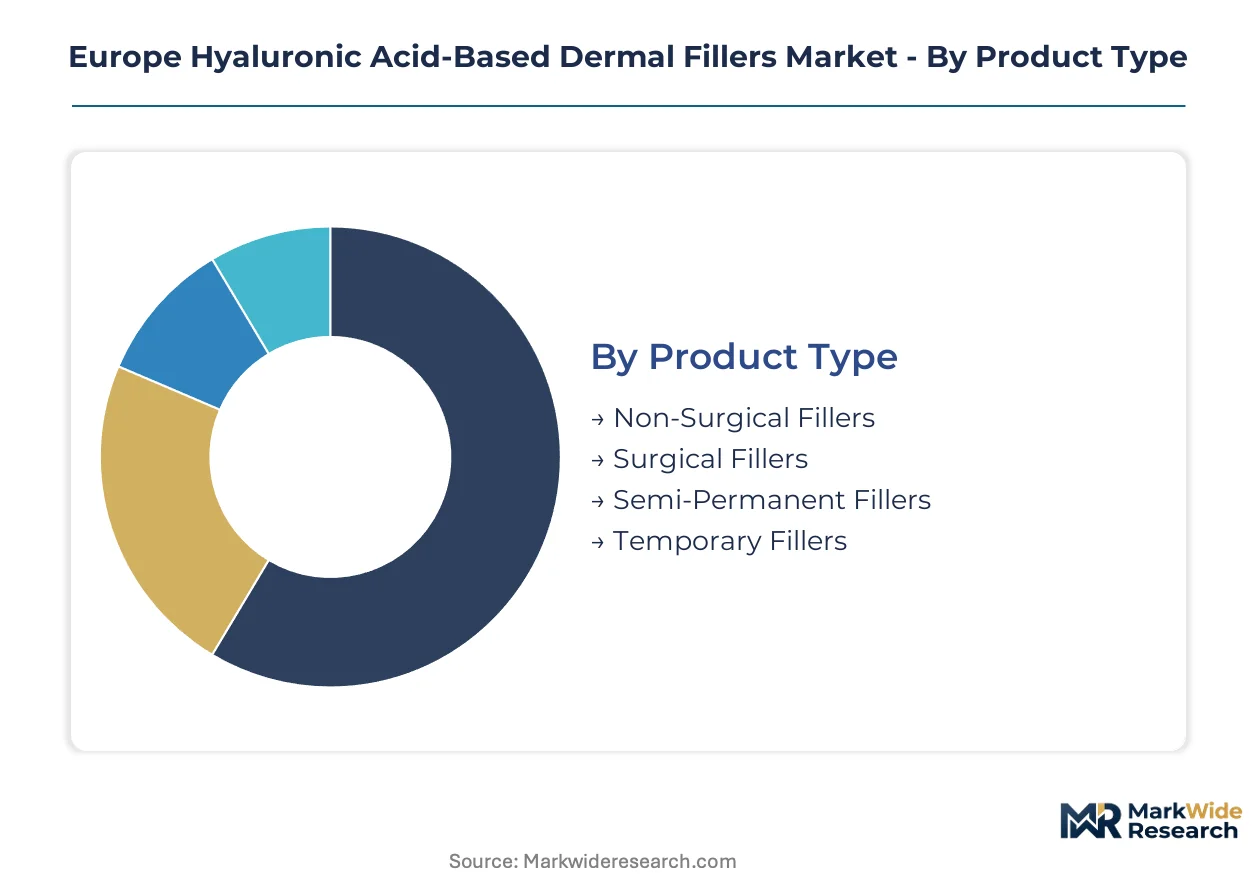
Product Type:
Non-surgical formulations dominate clinic procurement channels, while surgical and semi-permanent variants concentrate in hospital-affiliated cosmetic surgery centers with stricter inventory protocols.
- Non-Surgical Fillers:Injectable resorbable gels stabilized via BDDE cross-linking achieve viscoelastic properties measured in Pascals for subcutaneous volume restoration. Demand concentrates in Germany's private dermatology clinic network, where outpatient workflows and reduced recovery protocols align with patient throughput targets. By volume, non-surgical fillers lead. By growth pace, semi-permanent formulations are expanding most quickly.
- Surgical Fillers:Higher-viscosity formulations requiring cannula placement in deeper tissue planes support intraoperative volume sculpting during blepharoplasty or rhytidectomy. France's hospital-based cosmetic surgery centers maintain dedicated procurement contracts for these specialized applications.
- Semi-Permanent Fillers:Moderate cross-linking density extends residence time to 18-24 months, appealing to Milan and Rome patients prioritizing reduced injection frequency. Spain's cost-sensitive private clinics substitute these for permanent implants.
- Temporary Fillers:Low-G' gels with rapid enzymatic degradation suit first-time patients in Warsaw and Krakow aesthetic clinics seeking reversible outcomes.
Margin stratification follows residence time: temporary formulations command lowest per-syringe pricing, while semi-permanent variants capture premium positioning.
End User:
Service delivery economics vary sharply by setting—dermatology clinics bundle physician consultation fees, while medical spas compete on appointment accessibility and loyalty program structures.
- Dermatology Clinics:Physician-administered injections with direct-to-patient service bundling capture the highest margin pool across the value chain. Munich and Hamburg clinics adopt low-molecular-weight HA pre-blending protocols for periorbital applications.
- Medical Spas:Non-physician injector models in Paris and Lyon aesthetic clinics accelerate patient throughput through streamlined consultation-to-injection workflows. ANSM vigilance protocols elevate trust in CE-marked products, supporting repeat visit frequency.
- Hospitals:Reconstructive and post-traumatic applications in United Kingdom NHS-affiliated centers require formal tender processes and centralized purchasing.
- Cosmetic Surgery Centers:Combined surgical and non-surgical service portfolios in London and Manchester integrate filler procurement with operating room supply chains.
Patient acquisition costs run lowest at medical spas, while dermatology clinics defend pricing power through physician credential differentiation.
Application:
Anatomical targeting determines syringe volume requirements and cross-linking specification, with mid-face applications driving multi-syringe treatment protocols.
- Facial Volume Restoration:Submalar and cheek augmentation utilizing high-G' gels addresses aging demographic priorities across Italy and Spain. Milan clinics report strongest demand concentration for this indication.
- Lip Enhancement:Low-to-moderate cross-linking formulations balance projection with natural mobility. Co-injection protocols miniaturizing unit economics per treatment site expand patient throughput in German urban centers.
- Wrinkle Reduction:Superficial dermal placement for rhytide correction competes with neuromodulator combination therapies in Netherlands medical spa chains.
- Facial Contouring:Jawline and chin augmentation applications require specialized cannula techniques; variable training depth across Spain's injector workforce elevates complication exposure.
Revenue per patient peaks with facial volume restoration due to multi-syringe requirements, while lip enhancement drives highest annual visit frequency.
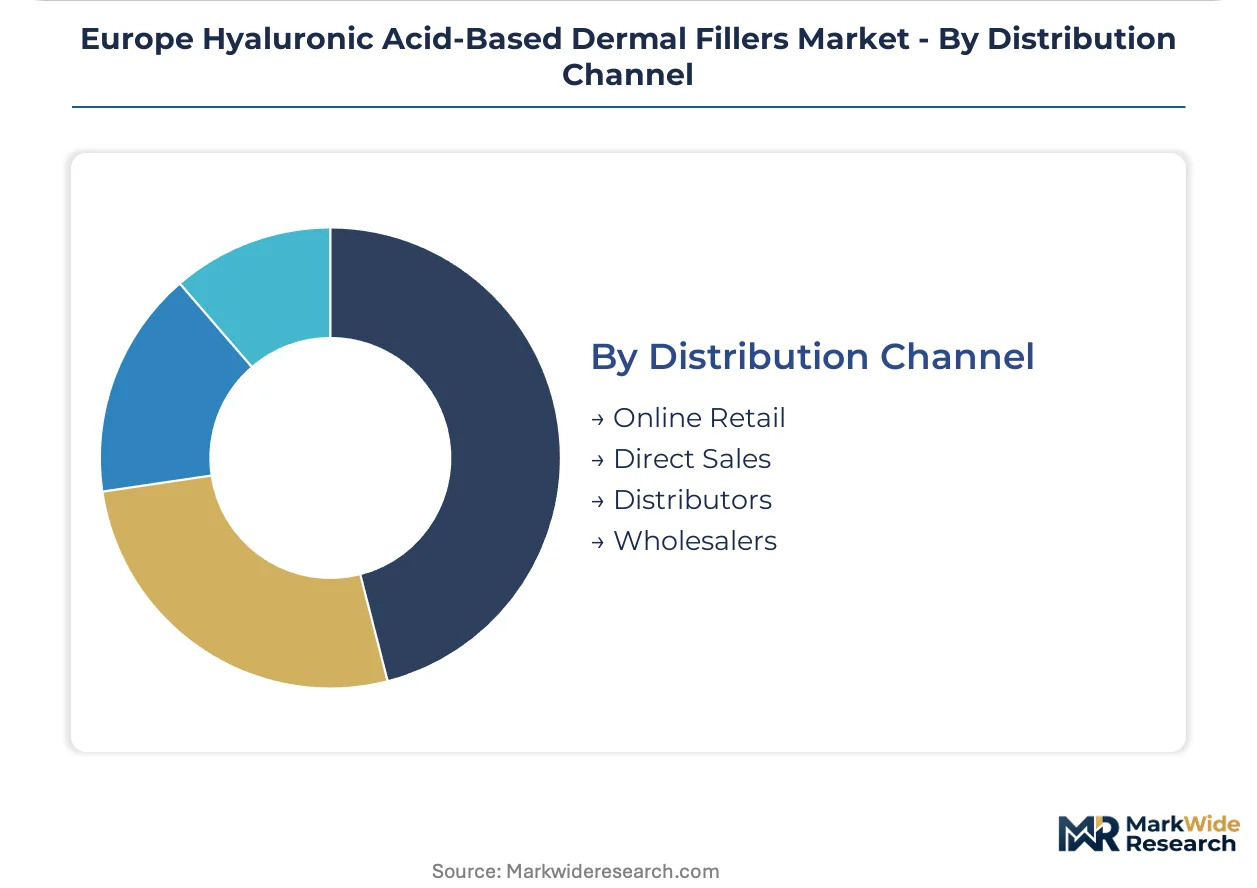
Distribution Channel:
Channel fragmentation accelerates as direct-to-clinic platforms displace traditional wholesale relationships, particularly among mid-volume United Kingdom accounts.
- Direct Sales:Manufacturer-to-clinic relationships dominate premium filler portfolios, with allergen and Galderma field forces maintaining dedicated coverage of Germany's largest dermatology networks.
- Distributors:Regional wholesalers retain relevance for Portuguese and Polish clinics lacking procurement scale for direct manufacturer contracts.
- Online Retail:Specialized B2B marketplaces with transparent pricing fragment traditional relationships; London aesthetic nurses now source through these channels.
- Wholesalers:Inventory pooling for small Belgian and Danish clinics leverages consolidated purchasing power amid EUDAMED traceability compliance requirements.
Direct sales channels capture highest manufacturer margin, while online retail gains fastest share among independent prescribers and nurse-led practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's private dermatology networks, while Spain's cost-sensitive clinic segment operates on compressed margins. The regulatory burden from EU MDR recertification cycles redistributes competitive advantage toward integrated manufacturers with captive quality management infrastructure.
Germany
Munich and Hamburg dermatology clinics drive demand for low-molecular-weight HA pre-blending protocols in periorbital applications. The country's Federal Institute for Drugs and Medical Devices enforces stringent MDR technical documentation standards through notified bodies like TÜV SÜD. Bavaria's medical device manufacturing corridor anchors fermentation-based HA production for integrated supply chains.
France
Paris and Lyon aesthetic clinics report elevated patient willingness for repeat injection protocols under ANSM vigilance protocols. The national medicines safety agency maintains additional post-market surveillance requirements beyond baseline EU compliance. Île-de-France's hospital-based cosmetic surgery centers sustain dedicated procurement contracts for specialized surgical filler applications.
United Kingdom
London and Manchester medical spas fragment traditional distributor relationships through direct-to-clinic B2B marketplaces. The Medicines and Healthcare products Regulatory Agency aligns with EMA pharmacovigilance frameworks for adverse event documentation. Independent aesthetic nurses in the Southeast accelerate channel shift toward transparent pricing platforms.
Italy
Milan and Rome clinics prioritize submalar volume restoration as aging demographics expand addressable patient pools beyond nasolabial fold correction. The Italian Medicines Agency implements EU MDR substance-based device classification guidance with extended clinical evaluation timelines. Lombardy's private dermatology network captures premium positioning through physician-administered injection bundling.
Poland
Warsaw and Krakow private aesthetic clinics operate at 40% capacity utilization versus Western European peers, creating first-mover expansion potential. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products processes CE marking documentation for cross-border commercialization. The country's underpenetrated dermatology infrastructure rewards early entrants with premium filler portfolios.
Europe Hyaluronic Acid-Based Dermal Fillers Market Competitive Landscape
Concentration sits with integrated pharmaceutical conglomerates possessing captive fermentation assets and cross-linked gel production capabilities. Three to four multinational manufacturers control the premium tier through vertically controlled supply chains that secure batch consistency. Strategic archetypes span integrated biopolymer specialists, contract-dependent formulation houses, and regional private-label distributors. Competitive moves center on MDR recertification preparation and direct-to-clinic procurement platform development.
Among Switzerland and France-based biopolymer research specialists, Galderma Laboratories exemplifies the R&D-intensive archetype through dedicated fermentation optimization programs. Allergan Aesthetics (AbbVie) occupies a position representing vertically integrated supply chain control across European distribution hubs. Merz Pharma anchors the monophasic formulation specialization tier with manufacturing scale concentration in regional production assets.
| Leading Market Players |
|---|
| Allergan Aesthetics (AbbVie) |
| Galderma Laboratories |
| Merz Pharma |
| Laboratoires VIVACY |
| Teoxane Laboratories |
| Sinclair Pharma |
| Genzyme Corporation |
| Bioxis Pharmaceuticals |
| Anika Therapeutics |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month MDR recertification backlogs at Germany's TÜV SÜD compress inventory turnover for novel cross-linking chemistries, concentrating pricing power with integrated manufacturers holding captive fermentation assets while contract-dependent peers absorb carrying cost penalties.
Pricing Analysis
The customization-premium spread between patient-specific rheology-matched formulations and standard BDDE-cross-linked gels widens as Munich dermatology clinics adopt low-molecular-weight HA pre-blending protocols. Three-tier pricing structure across premium, standard, and economy levels stratifies by cross-linking density and residence time, with semi-permanent formulations commanding highest positioning. Pricing pressure stems from collagen-stimulating injectable substitution in Spain's cost-sensitive private clinic segment. Medical spas exhibit highest price sensitivity due to non-physician injector models, while dermatology clinics defend premiums through physician credential differentiation.
Supply Chain Analysis
BDDE cross-linker supply concentration in Germany and China exposes filler producers to input cost spikes during pharmaceutical-grade shortage events. Streptococcus zooepidemicus fermentation capacity clusters in Germany, Switzerland, and France, with Bavaria's medical device manufacturing corridor anchoring integrated hyaluronic acid production. Raw material dependencies span bacterial HA feedstock, 1,4-butanediol diglycidyl ether cross-linker, and sterilized syringe packaging. Single-source vulnerability concentrates in BDDE chemical synthesis. Distribution runs through direct sales for premium portfolios and specialized B2B marketplaces fragmenting traditional wholesale relationships in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where EU MDR regulatory entrenchment creates switching costs that lock clinic procurement relationships and freeze out undercapitalized challengers.
For Market Incumbents: Secure batch consistency through backward integration into Streptococcus fermentation assets, insulating against BDDE supply concentration shocks. Expand quality management infrastructure ahead of 2027 MDR renewal cycles to exploit notified body capacity constraints that delay rival product launches. Collagen-stimulating injectable substitution from poly-L-lactic acid alternatives threatens volume in Southern European price-sensitive segments. For New Entrants and Emerging Players: CE marking fast-track through Poland's Office for Registration of Medicinal Products offers regulatory arbitrage against Western European backlog delays. Target Warsaw and Krakow aesthetic clinics operating at 40% capacity utilization versus Western peers, where underpenetrated dermatology networks reward first-mover premium portfolios. Deploy telemedicine-integrated consultation channels to reduce patient acquisition costs among time-constrained professionals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across monophasic filler manufacturing as MDR substance-based device classification demands expanded clinical evaluation infrastructure. Five-to-ten year viability favors integrated biopolymer specialists with captive fermentation and cross-linked gel production capabilities. Watch EUDAMED traceability compliance costs as the inflection signal separating scalable mid-tier manufacturers from distressed contract-dependent peers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Advancement | Early submission to Germany's TÜV SÜD secures recertification queue position ahead of 2027 renewal cycles. |
| Fermentation Capacity Expansion | Bavaria and Switzerland-based assets reduce raw material cost volatility for integrated hyaluronic acid supply chains. |
| Direct-to-Clinic Procurement Platform | B2B marketplace development captures mid-volume United Kingdom accounts fragmenting from regional wholesale agreements. |
| Biopolymer Research Facility Investment | Dedicated Switzerland and France laboratories sustain R&D intensity for novel cross-linking density modulation. |
| Telemedicine-Integrated Consultation Channel | Hybrid virtual assessment protocols reduce patient acquisition costs for Netherlands-based medical spa chains. |
Research Methodology
Desk research of EMA pharmacovigilance databases, EU MDR guidance documents, and notified body technical documentation precedes structured interviews with regulatory affairs leads at dermal filler manufacturers, procurement managers at German dermatology clinic networks, biomedical engineers specializing in viscoelastic gel characterization, and ANSM vigilance officers. Secondary validation draws from CE marking registries, hospital procurement databases, and customs trade data for hyaluronic acid feedstock flows. Bottom-up patient volume modeling triangulates against top-down manufacturer shipment estimates across the analysis window.
Variance decomposition separates volume growth from pricing mix effects across product type, end user setting, anatomical application, and distribution channel dimensions. CAGRs derive from segmented patient population projections, treatment frequency assumptions, and syringe-per-procedure coefficients. Industry-specific forecast inputs incorporate MDR recertification timeline scenarios and BDDE cross-linker supply elasticity parameters throughout the projection horizon.
Underlying assumptions cover stable EU MDR enforcement intensity and continued bacterial fermentation yield improvements, with deviation risk concentrated in notified body capacity bottlenecks extending approval timelines and collagen-stimulating injectable substitution accelerating in cost-sensitive Southern European markets. Practitioners should keep alternative scenarios live as EUDAMED traceability requirements and Green Deal biopolymer incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market