
 Fractionated Shea Butter in Cosmetics and Personal Care Market | 2026-2036
Fractionated Shea Butter in Cosmetics and Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Fractionated Shea Butter in Cosmetics and Personal Care Market Foresight
Modular ingredient kits and unbundled oil-in-water emulsion systems are recalibrating how cosmetic formulators procure shea derivatives. AAK AB leverages its integrated African crushing assets to secure traceable supply chains for premium brands. Cargill anchors its position through backward integration into Ghanaian and Burkina Faso cooperatives. BASF competes on oleochemical modification capabilities that tailor melting points for specific climate zones.
Fractionated shea butter is a lipid obtained by molecular distillation or solvent fractionation of Vitellaria paradoxa nut butter, yielding a liquid olein fraction with elevated stearic and oleic acid content and a sharply narrowed melting range near 20–25°C; this engineered profile serves as a non-comedogenic emollient and stable carrier in temperature-variable formulations. Organic fractionated shea butter commands the widest margin pool as certified supply tightens against rising clean-label mandates. Skin moisturizers lead application volume, though anti-aging products represent the fastest-expanding segment as peptide-shea complexes gain traction in prestige channels.
EMA cosmetic ingredient guidelines, REACH registration thresholds for imported oleochemicals, and FDA cosmetic labeling rules under the Modernization of Cosmetics Regulation Act collectively elevate compliance costs for new market entrants while rewarding documented traceability. ISO 16128 natural origin standards further segment supplier credibility tiers. Stakeholders must monitor evolving bioprospecting regulations in West African source countries and decide whether to build direct cooperative relationships or rely on established distributor networks with existing export licenses.
Market Dynamics
Clean-label mandates and REACH registration thresholds are compressing supplier pools while concentrating procurement among certified organic grade holders with documented West African cooperative relationships.
Growth Catalysts
- EMA cosmetic ingredient guidelines:These standards accelerate premium brand adoption of traceable oleochemicals by mandating documented natural origin claims across EU formulations.
- Peptide-shea complex innovation:Prestige anti-aging channels drive demand for bioactive lipid carriers that stabilize temperature-sensitive actives in variable climates.
- Ghanaian cooperative supply networks:Direct sourcing relationships reduce export license friction and secure priority allocation during harvest volatility.
Market Restraints
- Shea nut harvest volatility:West African rainfall patterns create input cost instability that squeezes margin predictability for fractionation operators.
- REACH registration thresholds:ECHA compliance costs for imported oleochemicals filter out mid-tier distributors lacking dedicated regulatory affairs capacity.
- Synthetic ester substitution:Petrochemical emollients from palm and coconut derivatives compete on price in mass-market moisturizers.
Strategic Opportunities
- India personal care expansion:BIS natural origin standards and FSSAI cosmetic rules create early-mover advantage for certified organic grade suppliers.
- Modular ingredient kit formats:Unbundled oil-in-water emulsion systems let indie formulators customize shea olein ratios without dedicated R&D infrastructure.
- ISO 16128 credibility tiering:Third-party certification unlocks premium positioning against uncertified competitors in clean-label channels.
Industry Challenges
- Bioprospecting compliance timelines:Evolving West African export regulations delay shipment clearances and stretch working capital cycles.
- Oleochemical modification capex:Molecular distillation equipment for tailored melting point engineering demands substantial upfront investment.
- Traceability system integration:Blockchain and GPS mapping technologies require specialized talent scarce in traditional shea trading houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractionated Shea Butter in Cosmetics and Personal Care Market |
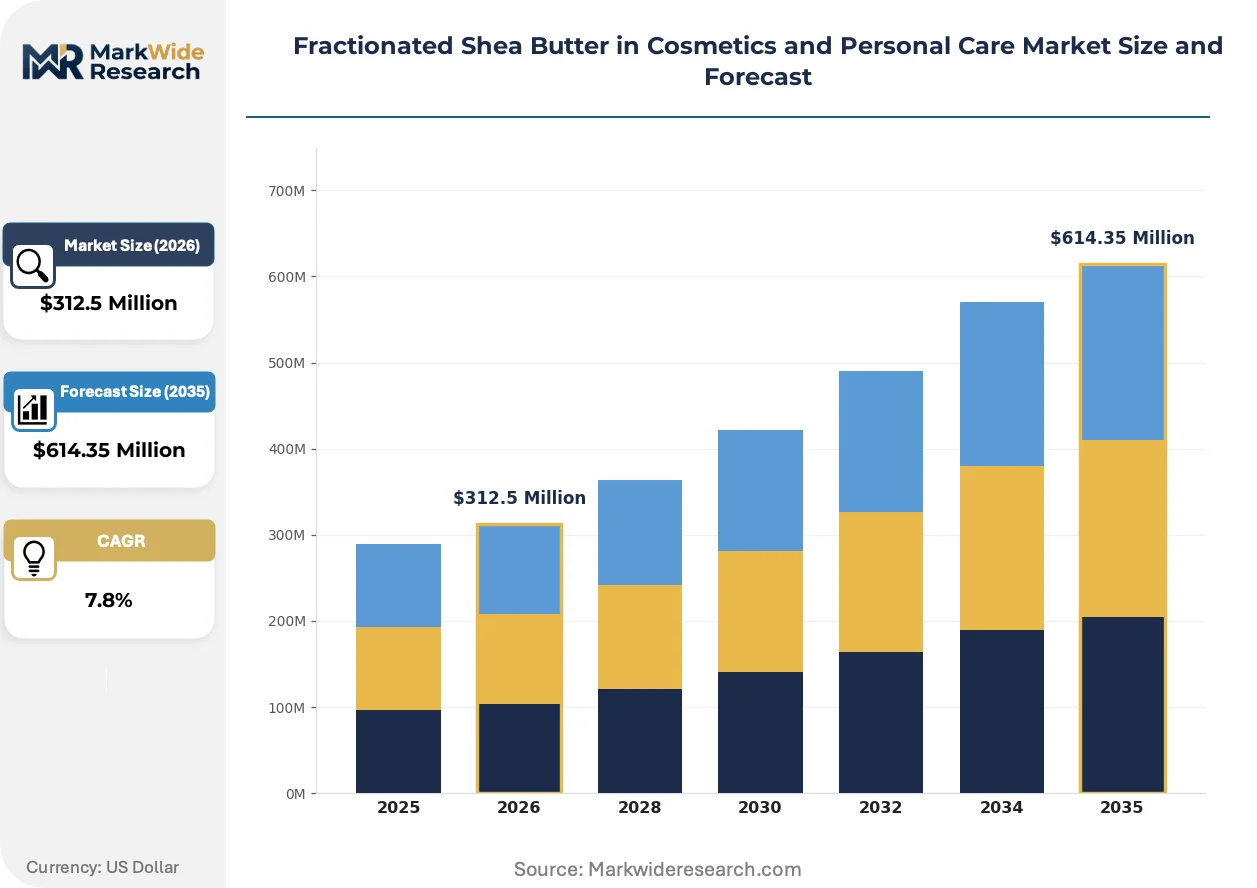
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fractionated Shea Butter, Refined Fractionated Butter, Unrefined Fractionated Shea, Specialty Grades Application: Skin Moisturizers, Hair Conditioners, Lip Care, Sun Protection, Anti-aging Products End User: Beauty Salons, Cosmetic Manufacturers, Dermatology Clinics, Spa Centers, Private Label Brands Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales, Pharmacies |
| Companies Covered | AAK AB, Cargill, Olvea Group, BASF, Croda International, Unilever, L'Oréal, Estée Lauder Companies, Ghana Nuts Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractionated Shea Butter in Cosmetics and Personal Care Market Shifts & Advancements
Formulation science and regulatory architecture are converging to reward precision-engineered lipids with verifiable supply chain documentation over commodity shea derivatives.
Molecular distillation systems for shea olein fractionation is consolidating production among operators with captive African crushing assets. Prestige cosmetic houses in France and Germany now specify narrow melting range specifications that only advanced fractionation delivers. This technical barrier compresses viable supplier counts while elevating margin capture for integrated processors.
REACH registration thresholds for imported oleochemicals force distributors to maintain ECHA-compliant dossiers or exit the EU market entirely. Mid-tier trading houses without dedicated regulatory capacity face exclusion from premium brand procurement lists. French and German luxury formulators now require REACH documentation as a baseline qualification, not a differentiator.
Buyer concentration among certified organic grade seekers is shortening supplier qualification cycles and demanding real-time harvest traceability. Indie formulators in the United States increasingly bypass traditional distributors for direct cooperative relationships with Ghanaian and Burkina Faso women's groups. This channel compression rewards suppliers with existing export licenses and GPS-mapped shea park documentation.
Fractionated Shea Butter in Cosmetics and Personal Care Market Segmentation
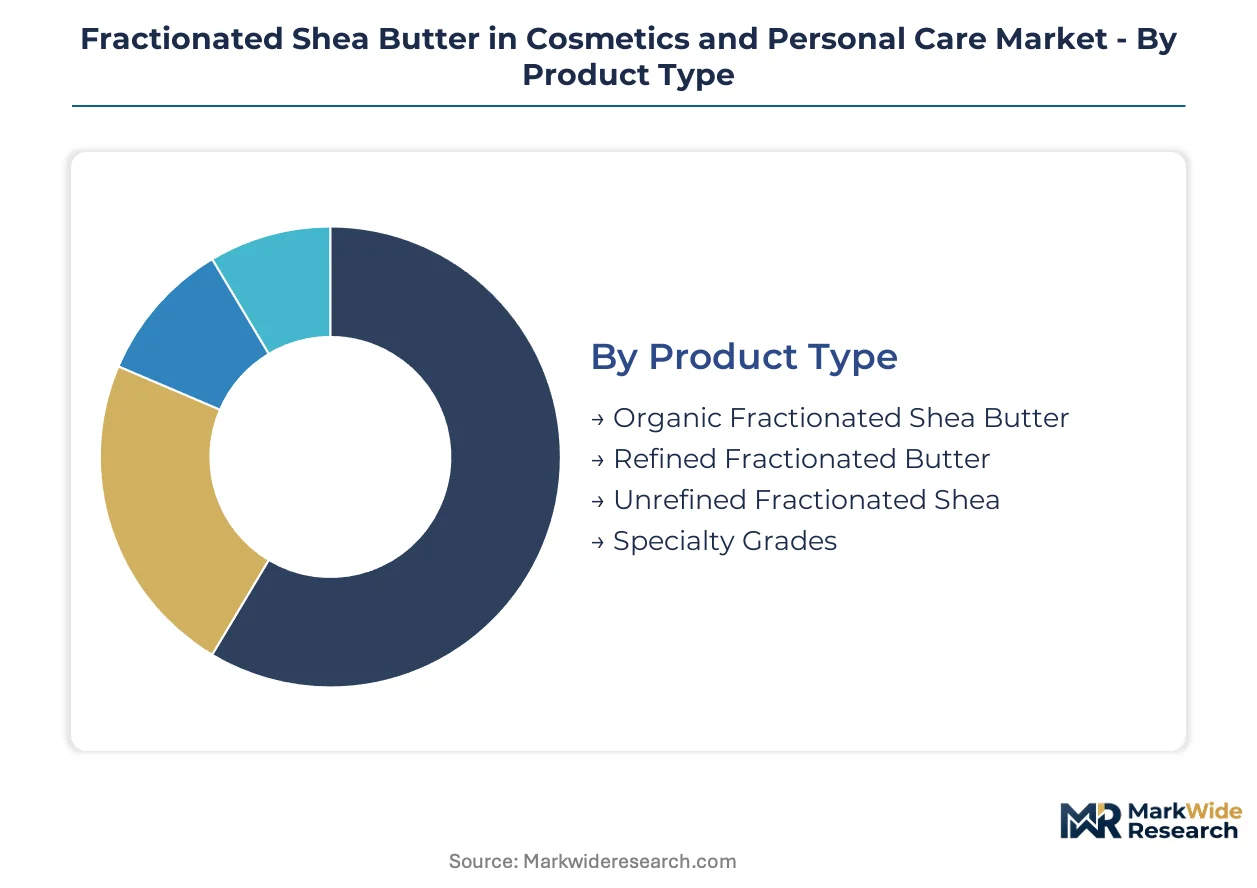
Segmentation in fractionated shea butter markets separates commodity traders from value-capturing specialists. Certified grades command procurement priority among prestige formulators, while application-specific tailoring determines margin retention across climate-variable formulations.
Product Type:
Standardization tightens at the commodity end while customization expands at the premium tier, creating divergent investment requirements for fractionation equipment and certification documentation.
- Organic Fractionated Shea Butter:Cold-pressed olein fraction retaining full tocopherol profile and ISO 16128-compliant natural origin certification. French and German luxury houses source this grade exclusively, with EMA cosmetic ingredient guidelines mandating documented cooperative provenance from Ghanaian and Burkina Faso networks.
- Refined Fractionated Butter:Bleached and deodorized olein with neutral sensory characteristics for mass-market compatibility. Cosmetic manufacturers in the United States specify this grade for cost-sensitive moisturizers where clean-label positioning takes secondary priority to formulation stability.
- Unrefined Fractionated Shea:Minimal processing preserves characteristic nutty aroma and amber coloration for artisanal channels.
- Specialty Grades:Custom melting point engineering via molecular distillation for climate-specific deployment.
Leading the category by volume: Refined Fractionated Butter. Growing fastest: Organic Fractionated Shea Butter.
Application:
Volume concentration sits with daily-use formats, while clinical positioning and actives stabilization drive fastest expansion and margin capture.
- Skin Moisturizers:Body lotions and facial creams absorb the largest olein volumes, with peptide-shea complex innovation elevating functional claims in prestige channels. Indie formulators in the United States specify narrow melting range fractions for temperature-variable retail environments.
- Anti-aging Products:Prestige serums deploy fractionated shea as bioactive lipid carriers for temperature-sensitive peptides. French dermatology clinics and German cosmetic houses specify REACH-registered grades with documented traceability from cooperative crushing assets.
- Hair Conditioners:Rinse-off applications favor cost-optimized refined grades for slip and detangling performance.
- Lip Care:Stick and balm formats require specific hardness profiles from stearin-rich fractions.
- Sun Protection:Olein fractions serve as dispersing media for mineral UV filters in reef-safe formulations.
Highest volume absorption: Skin Moisturizers. Steepest expansion trajectory: Anti-aging Products.
End User:
Procurement scale and technical specification sophistication separate institutional buyers from fragmented service channel demand.
- Cosmetic Manufacturers:Integrated formulators with captive R&D specify custom melting points and certificate-of-analysis documentation for climate-zone tailoring. Direct cooperative relationships with Ghanaian women's groups bypass distributor markups for volume commitments.
- Private Label Brands:Contract manufacturers serving retailer-owned brands balance cost minimization against emerging clean-label mandates. REACH registration requirements filter supplier pools toward established distributors with ECHA-compliant dossiers.
- Beauty Salons:Professional back-bar consumption favors mid-tier refined grades with consistent sensory profiles.
- Dermatology Clinics:Clinical positioning demands organic certification and hypoallergenic testing documentation.
- Spa Centers:Wellness-oriented positioning prioritizes unrefined grades with aromatic authenticity.
Dominant procurement volume: Cosmetic Manufacturers. Gaining share fastest: Private Label Brands.
Distribution Channel:
Channel selection determines working capital intensity and traceability system requirements for supplier qualification.
- Wholesale Distributors:Traditional trading houses with established export licenses from Ghana and Burkina Faso aggregate harvest volumes for fractional resale. REACH registration maintenance and GPS-mapped shea park documentation separate viable EU suppliers from excluded mid-tier operators.
- Online Retailers:Direct-to-formulator platforms enable indie brands to source certified organic grades without minimum order constraints. Real-time harvest traceability via blockchain verification commands premium positioning in clean-label channels.
- Specialty Stores:Ingredient-focused retailers serve artisanal formulators with small-batch unrefined offerings.
- Direct Sales:Cooperative-to-brand relationships compress margin extraction for traceability priority buyers.
- Pharmacies:Clinical-grade distribution requires GMP-compliant handling and stability documentation.
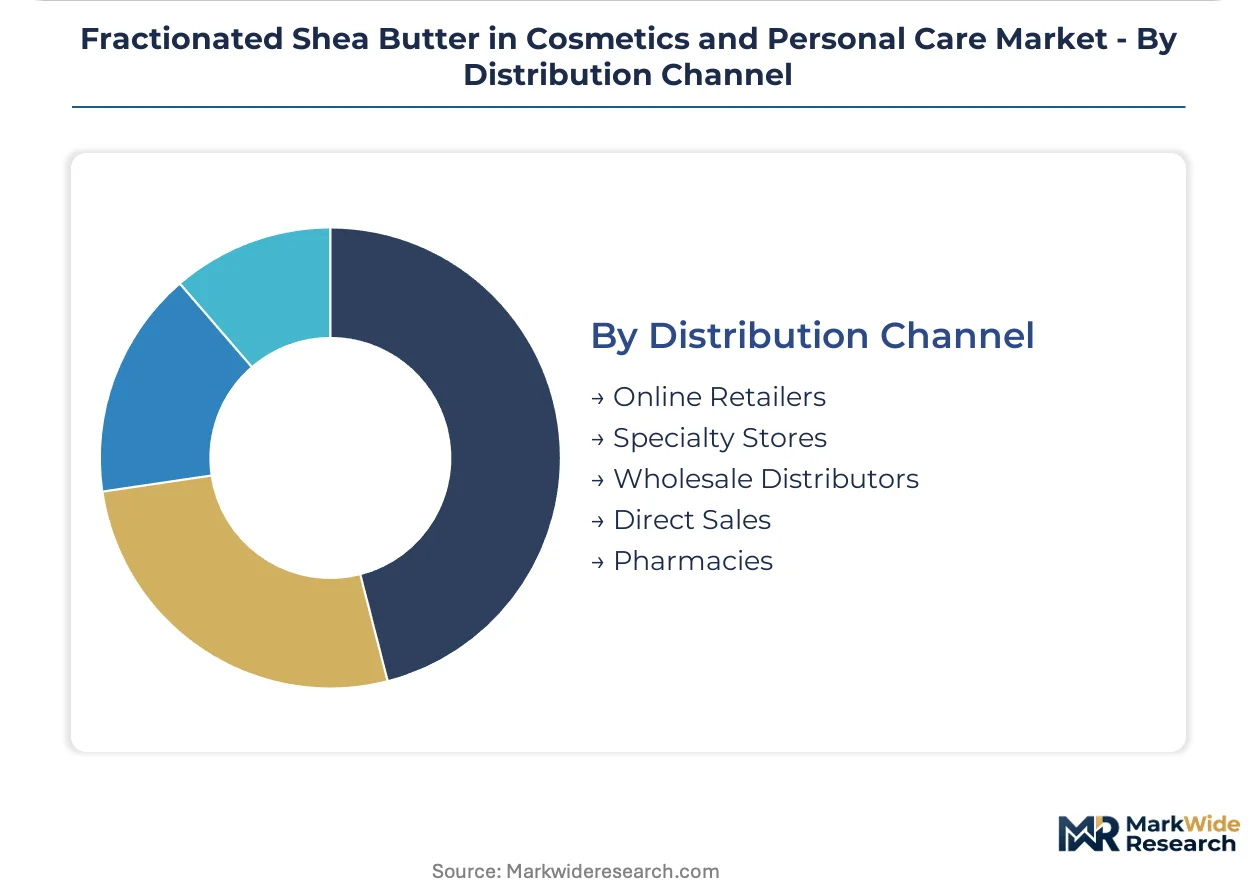
Primary volume pathway: Wholesale Distributors. Expanding most quickly: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African crushing assets supply raw shea nuts while French, German, and United States formulators absorb refined olein fractions. This production-consumption divide shapes trade flows, regulatory compliance burdens, and supplier qualification requirements across three continents.
United States
Indie formulators in Brooklyn and Los Angeles drive demand for certified organic grades with GPS-mapped cooperative provenance. FDA cosmetic labeling rules under the Modernization of Cosmetics Regulation Act elevate documentation requirements for imported oleochemicals. Prestige brands in Manhattan and San Francisco now specify REACH-registered equivalents even for domestic formulations.
Germany
Luxury cosmetic houses in Hamburg and Düsseldorf mandate narrow melting range specifications from molecular distillation systems. ECHA REACH registration thresholds filter supplier pools toward established distributors with compliant dossiers. The Rhine-Ruhr industrial corridor concentrates fractionation capacity for climate-tailored olein engineering.
France
Paris-based dermatology clinics and Grasse fragrance houses source exclusively from Ghanaian and Burkina Faso cooperative networks with EMA cosmetic ingredient guideline documentation. ANSM oversight of cosmetic safety reinforces traceability mandates. The Île-de-France region anchors EU procurement priority for premium peptide-shea complexes.
Ghana
Women's cooperative crushing operations in Tamale and Wa supply traceable shea nuts to integrated processors with captive African assets. Export license requirements and evolving bioprospecting regulations stretch working capital cycles for mid-tier trading houses. The Northern Region concentrates shea park documentation efforts for blockchain-verified supply chains.
India
BIS natural origin standards and FSSAI cosmetic rules create early-mover openings for certified organic grade suppliers in Mumbai and Bangalore personal care manufacturing. Domestic formulators increasingly specify shea olein for Ayurveda-positioned moisturizers. Maharashtra and Karnataka absorb rising volumes as clean-label mandates penetrate mass-market channels.
Fractionated Shea Butter in Cosmetics and Personal Care Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Integrated processors with captive African crushing assets command premium positioning through traceability documentation. Mid-tier distributors face exclusion from EU procurement lists as REACH compliance costs escalate. Dominant competitive moves include backward integration into Ghanaian cooperative networks and molecular distillation capacity expansion for climate-specific melting point engineering.
Within the integrated processor tier, AAK AB and Cargill exemplify archetypes leveraging upstream control over West African supply chains. BASF occupies a position among oleochemical modification specialists competing on tailored lipid engineering. Ghana Nuts Company represents the cooperative-anchored model that indie formulators increasingly favor for direct sourcing relationships.
| Leading Market Players |
|---|
| AAK AB |
| Cargill |
| Olvea Group |
| BASF |
| Croda International |
| Unilever |
| L'Oréal |
| Estée Lauder Companies |
| Ghana Nuts Company |
| Others |
Supply & Pricing Matrix
Family-owned cooperative networks in Ghana and Burkina Faso anchor upstream supply, concentrating pricing power among integrated processors with captive crushing assets while compressing margins for distributor-dependent traders facing REACH compliance burdens.
Pricing Analysis
Margin tightening in refined grades reflects synthetic ester substitution from palm and coconut derivatives in mass-market moisturizers. Three-tier pricing structure across organic certified, refined, and unrefined levels separates procurement pools, with ISO 16128 compliance commanding widest spreads. Cost-down pressure on mid-tier distributors accelerates because ECHA registration thresholds filter out operators lacking dedicated regulatory capacity. Private label brands exhibit highest price sensitivity; prestige cosmetic houses in France and Germany show least.
Supply Chain Analysis
REACH registration and EMA cosmetic ingredient guidelines gate supplier qualification, rewarding documented traceability. Production concentrates in Ghana, Burkina Faso, and Ivory Coast as source countries, with fractionation capacity clustering in Germany and France. Molecular distillation equipment, shea nut harvests, and cooperative export licenses constitute critical input dependencies. Single-source vulnerability from West African rainfall volatility threatens input cost stability. Distribution runs through wholesale distributors with established export licenses, though online retailer channels expand for indie formulator direct access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and bioprospecting regulation delays force consolidation, eliminating mid-tier distributors lacking ECHA dossier capacity or GPS-mapped shea park documentation.
For Market Incumbents: Hedge harvest volatility through multi-origin cooperative contracts spanning Ghanaian and Burkina Faso networks. Deepen molecular distillation capabilities for climate-specific melting point engineering that prestige formulators specify. Secure blockchain traceability systems ahead of indie formulator demands for real-time cooperative provenance verification. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian personal care manufacturing offers white-space entry before BIS natural origin standards fully mature. Target modular ingredient kit formats for United States indie formulators lacking dedicated R&D infrastructure. Pursue direct cooperative relationships with documented GPS-mapped shea parks as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distributors with existing REACH registrations in Germany and France facing working capital strain from bioprospecting clearance delays. Long-term viability centers on integrated processors with captive African crushing assets and fractionation capacity. Monitor ECHA enforcement intensity against non-compliant oleochemical imports as inflection signal for supplier pool compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Networks | Secures priority shea nut allocation during harvest volatility for integrated processors. |
| Molecular Distillation Capacity Expansion | Enables custom melting point engineering for climate-variable prestige formulations. |
| Blockchain Traceability Implementation | Meets GPS-mapped shea park documentation demands from clean-label cosmetic houses. |
| REACH Registration Dossier Investment | Maintains EU market access as ECHA thresholds filter mid-tier distributors. |
| Modular Ingredient Kit Development | Captures United States indie formulator demand without minimum order constraints. |
Research Methodology
Document review covered trade flow databases, ECHA registration filings, and cooperative export license records, complemented by interviews with cosmetic formulators, shea cooperative managers, oleochemical procurement leads, and regulatory affairs specialists at REACH-registered distributors. Secondary sources included customs declarations from Ghana and Burkina Faso, ISO 16128 certification registries, and FDA cosmetic ingredient disclosure filings. Bottom-up volume estimates from cooperative crushing capacity and top-down demand calibration from cosmetic manufacturer procurement data were triangulated.
Cross-referencing historical price spreads against panel input from fractionation operators anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product certification tier, application category, end-user procurement scale, and distribution channel structure. CAGRs were derived from trend extrapolation of olein volume absorption adjusted for regulatory compliance cost pass-through. Peptide-shea complex innovation velocity and clean-label mandate penetration rates served as industry-specific forecast modifiers.
Inputs from cooperative export license databases and ECHA registration rolls were available through the study window; gaps in real-time harvest yield data introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and bioprospecting timeline evolution. A model refresh is warranted upon material change in ECHA REACH threshold enforcement or West African export regulation restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Liposome in Cosmetics Market