
 Facial Essence Market | 2026-2036
Facial Essence Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Essence Market Foresight
The gap between premium fermented essences and mass-market hydrators is expanding as ingredient storytelling splits consumer willingness to pay. SK-II leverages its Pitera biotechnology heritage to sustain pricing power in Asian duty-free channels. Shiseido anchors its regional dominance through integrated R&D labs in Kobe and Yokohama that control fermentation supply chains. Augustinus Bader differentiates via TFC8 cell-renewal positioning that commands dermatologist endorsement in European and North American clinics.
Facial essence denotes a lightweight, water-based treatment product with molecular weights typically below 500 Da for enhanced epidermal penetration, designed to deliver concentrated actives before moisturizer application. Hydrating essences lead volume through hyaluronic acid and glycerin formulations, while anti-aging essences capture margin pools via peptide and retinol complexes. Brightening essences containing niacinamide and arbutin represent the fastest-growing ingredient-led segment as pigmentation concerns drive clinical positioning in Southeast Asian and Latin American markets.
FDA cosmetic labeling requirements and the EU Cosmetics Regulation govern ingredient disclosure and safety substantiation, while China's NMPA filing process dictates market access timelines for imported essence brands. South Korea's MFDS enforces functional cosmetic standards for whitening and wrinkle-improvement claims that shape product development pipelines. Stakeholders must monitor evolving microbiome-friendly certification frameworks and state-level clean beauty legislation in California and New York that could redefine permissible preservative systems.
Market Dynamics
Fermentation biotechnology patents filed by South Korean and Japanese conglomerates are compressing R&D cycles for bio-active essences. These intellectual property clusters now determine which ingredient platforms achieve commercial scale before regulatory filing deadlines.
Growth Catalysts
- Clean-label mandates under EU Cosmetics Regulation:Ingredient transparency requirements are accelerating reformulation toward botanical extracts and away from synthetic preservatives. Export-oriented suppliers must maintain dual formulation pipelines to serve European and Asian markets simultaneously.
- Functional cosmetic standards enforced by South Korea MFDS:Whitening and wrinkle-improvement claim substantiation creates defensible positioning for brands that complete clinical testing. This regulatory moat protects premium pricing against mass-market competitors.
- Peptide complex adoption in dermatology clinics:Medical channel endorsement is pulling high-net-worth consumers toward clinically positioned essences. Physician recommendation carries particular weight in Chinese tier-one cities and Southeast Asian urban centers.
Market Restraints
- Hyaluronic acid feedstock volatility:Fermentation-derived sodium hyaluronate supply concentrates among Chinese biotech suppliers. Price swings in this input compress margin pools for mid-tier hydrating essence producers.
- REACH compliance costs for botanical extracts:European chemical safety dossier requirements add twelve to eighteen months to ingredient qualification timelines. Smaller formulators lack capital reserves to sustain extended regulatory review periods.
- Sheet mask substitution in mass hydration:Single-use mask formats capture trial-oriented consumers seeking immediate visual results. Essence penetration in entry-level skincare routines faces displacement from this adjacent category.
Strategic Opportunities
- Microbiome-friendly certification frameworks:Third-party standards for preservative-free and pH-balanced formulations are emerging in California and New York state legislation. Early adopters gain shelf space differentiation in clean beauty retail channels.
- Men's grooming vertical expansion:Post-shave essence application represents underdeveloped usage occasion in North American and European markets. Gender-neutral packaging and marketing unlock incremental volume without dedicated SKU proliferation.
- Direct-to-physician sampling programs:Bypassing traditional retail markup structures allows premium brands to capture clinic channel loyalty. Dermatologist co-development agreements create exclusive distribution relationships.
Industry Challenges
- Fermentation scientist talent scarcity:Industrial biotechnology programs in South Korea and Japan produce insufficient candidates for expanding R&D lab networks. Compensation inflation in Seoul and Yokohama clusters squeezes mid-cap brand development budgets.
- Legacy preservative system requalification:Reformulating established essence lines for microbiome-friendly positioning requires full stability testing and consumer safety studies. Timeline compression demands compete with new product launch priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Essence Market |
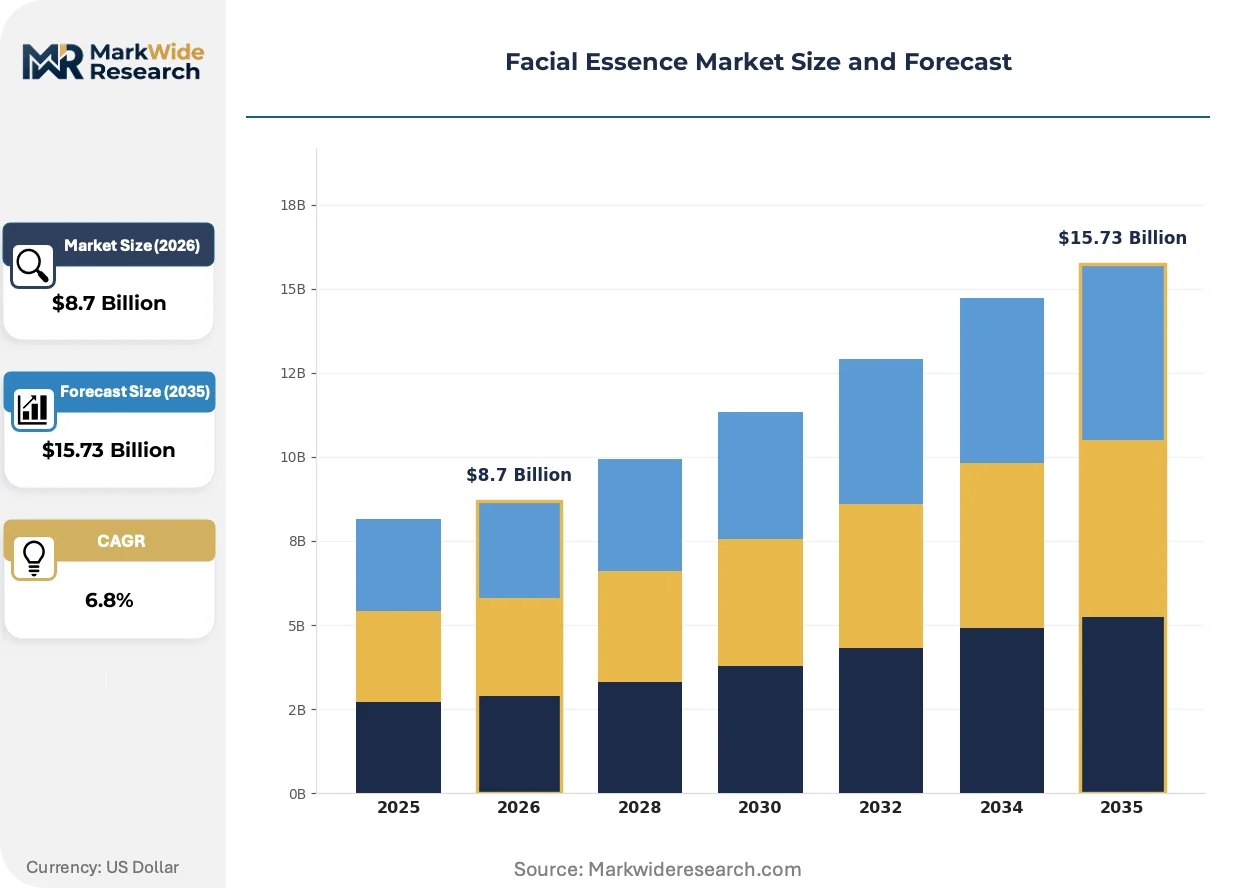
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Essences, Brightening Essences, Anti-Aging Essences, Soothing Essences End User: Women, Men, Teens, Unisex Ingredient Type: Botanical Extracts, Synthetic Ingredients, Essential Oils, Vitamin Enriched Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Beauty Salons |
| Companies Covered | SkinCeuticals, EltaMD, SK-II, Eminence Organic Skin Care, Sunday Riley, Shiseido, Obagi Medical, NEOCUTIS, Augustinus Bader, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Essence Market Shifts & Advancements
Biotechnology platforms are fragmenting competitive advantage away from marketing scale toward proprietary organism libraries and fermentation process patents. This shift rewards capital-intensive R&D infrastructure over traditional brand-building expenditures.
Cell-free fermentation extracts are decentralizing production economics for niche bio-active ingredients. Specialty biotech firms in South Korea and Japan are licensing their organism strains to regional contract manufacturers. This technology diffusion enables mid-tier brands to access previously captive supply chains without vertical integration into fermentation facilities.
China's NMPA filing process revisions are compressing market access timelines for imported functional cosmetics. The streamlined documentation requirements reduce registration costs for essence brands seeking whitening or anti-aging claim approvals. European and Japanese heritage labels with existing clinical data repositories are accelerating their China market entry strategies to exploit this regulatory window.
Subscription-based replenishment models are capturing high-lifetime-value consumers in North American direct-to-consumer channels. Automated reorder algorithms tied to usage tracking replace traditional retail discovery for core skincare routines. This behavioral shift concentrates brand loyalty among algorithm-optimized players while eroding impulse purchase opportunities for competing labels.
Facial Essence Market Segmentation
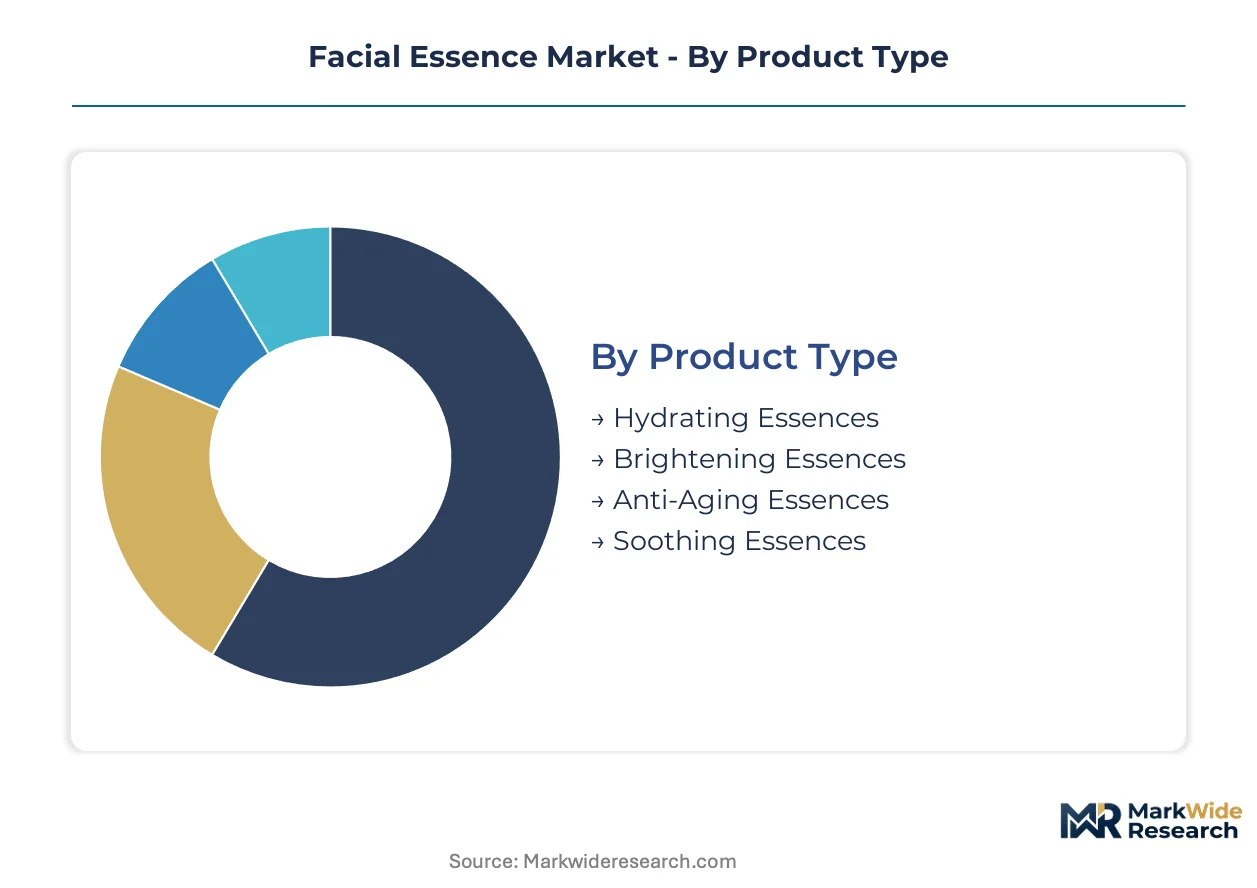
Facial essence manufacturers configure product portfolios across four intersecting dimensions that determine pricing architecture and channel strategy. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape investment prioritization.
Product Type:
Volume concentrates in hydrating formulations while premium pools concentrate in bio-active anti-aging platforms with clinical claim substantiation.
- Hydrating Essences:Hyaluronic acid and glycerin-based formulations dominate unit sales through mass-market retail and drugstore channels. Chinese tier-one cities and Southeast Asian urban centers absorb the highest volumes as entry-point skincare adoption accelerates among first-time essence users.
- Anti-Aging Essences:Peptide complexes and retinol derivatives command dermatology channel placement and subscription replenishment models. South Korea MFDS functional cosmetic certification creates regulatory moats that protect premium positioning against unverified competitors.
- Brightening Essences:Niacinamide and arbutin formulations target pigmentation concerns in tropical climates and post-inflammatory skincare routines.
- Soothing Essences:Centella asiatica and madecassoside variants address barrier repair following aesthetic procedures and retinoid tolerance building.
Today's leader: Hydrating Essences. Tomorrow's challenger: Anti-Aging Essences.
End User:
Gendered marketing architectures are fragmenting as unisex positioning captures share from legacy female-targeted SKUs.
- Women:Historical core demographic with established multi-step routine adherence and highest category lifetime value. Mature markets in Japan and South Korea show saturation while Chinese and Southeast Asian penetration continues expanding.
- Unisex:Fastest-climbing segment as minimalist packaging and gender-neutral ingredient storytelling unlock male-adjacent trial. North American direct-to-consumer brands and European clean beauty retailers drive format innovation.
- Men:Post-shave application occasions remain underdeveloped outside South Korea and Japan, representing whitespace in Western markets.
- Teens:Early routine adoption through K-beauty influencer content and affordable entry-price essences.
Women anchor current revenue. Unisex formulations are gaining share fastest.
Ingredient Type:
Clean-label mandates are compressing synthetic ingredient pipelines while fermentation biotechnology unlocks novel botanical bio-actives.
- Botanical Extracts:Fermentation-processed plant derivatives from South Korean and Japanese R&D labs command supply chain premiums. EU Cosmetics Regulation transparency requirements accelerate reformulation toward traceable botanical sourcing.
- Vitamin Enriched:Niacinamide, vitamin C derivatives, and panthenol complexes anchor clinical positioning in brightening and barrier repair segments.
- Synthetic Ingredients:Peptide libraries and stabilized retinols retain technical necessity despite clean beauty headwinds.
- Essential Oils:Fragrance-forward positioning in aromatherapy-aligned spa and salon channels, with dermatology caution limiting facial application growth.
Botanical Extracts dominate premium shelf space. Vitamin Enriched formats are expanding most quickly.
Distribution Channel:
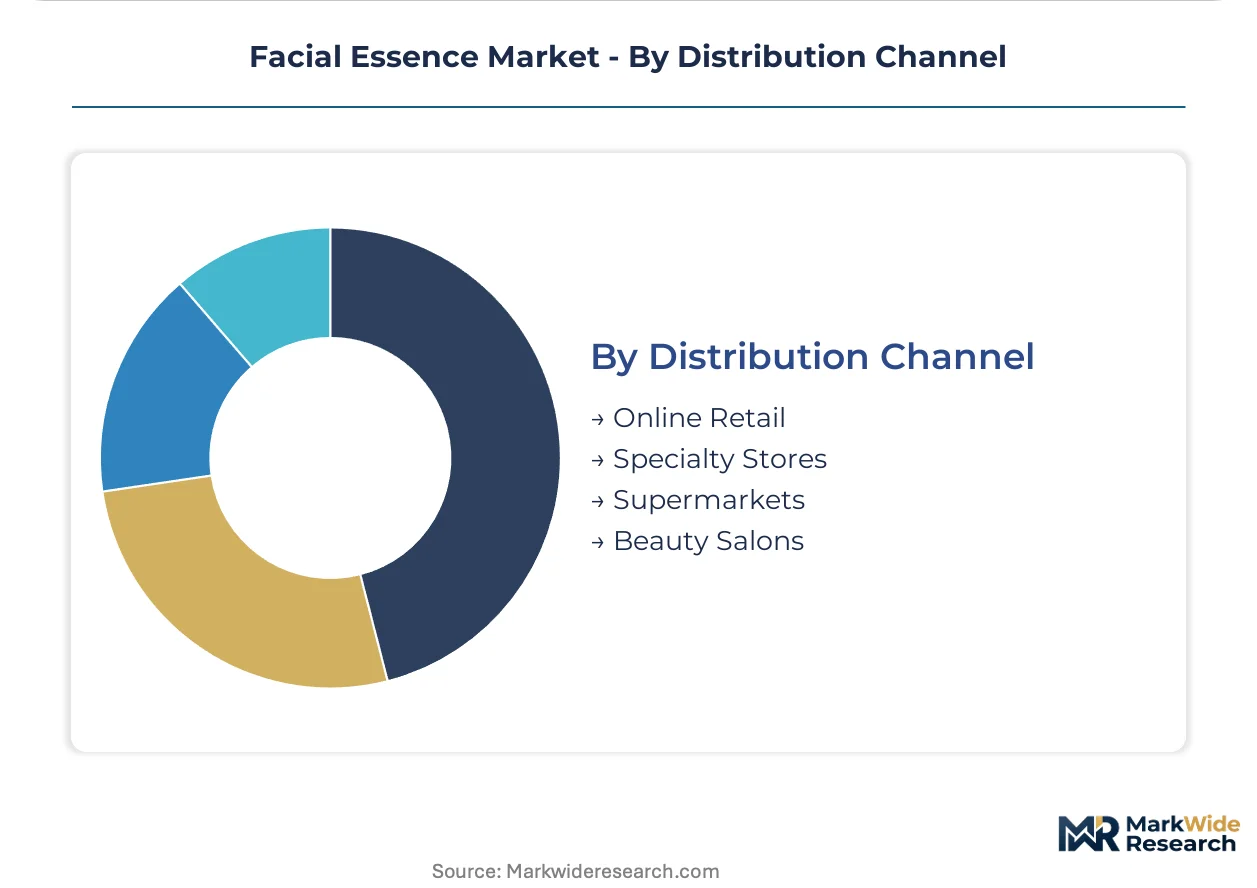
Channel mix determines margin capture and consumer data access, with digital-native brands bypassing traditional retail markup structures.
- Online Retail:Subscription algorithms and social commerce integration concentrate high-lifetime-value consumers in North American and Chinese markets. Automated replenishment replaces impulse discovery for core routine products.
- Specialty Stores:Sephora, Ulta, and Asian beauty specialty chains provide discovery environment and sampling infrastructure for new brand entry.
- Beauty Salons:Professional endorsement and post-treatment retail capture premium price realization in clinical positioning strategies.
- Supermarkets:Mass-market hydrating essences achieve volume through convenience purchasing and promotional pricing.
Online Retail leads growth trajectory. Beauty Salons defend margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's fermentation biotechnology heritage contrasts with China's regulatory acceleration, as both markets pull global formulation standards in divergent directions while Japan preserves integrated R&D control over supply chains.
China
NMPA filing process revisions compress market access timelines for imported functional cosmetics with whitening and anti-aging claims. Tier-one cities including Shanghai and Beijing concentrate demand where domestic brands compete with heritage Japanese and Korean labels for digital share of voice and premium shelf space.
South Korea
Millennial and Gen Z consumers sustain premium skincare routines that pull innovation toward fermented bio-actives and clean-label botanicals. MFDS functional cosmetic standards for whitening and wrinkle-improvement claims create regulatory moats protecting premium positioning. Seoul anchors R&D lab networks where fermentation scientist talent scarcity drives compensation inflation.
Japan
Heritage biotechnology positioning commands pricing power in Asian duty-free channels and domestic prestige retail. Integrated R&D labs in Kobe and Yokohama control fermentation supply chains for proprietary bio-active platforms. METI industrial policy supports cosmetic biotechnology exports through standardized quality certification frameworks.
United States
Subscription-based replenishment models capture high-lifetime-value consumers through automated reorder algorithms tied to usage tracking. FDA cosmetic labeling requirements govern ingredient disclosure while California and New York state-level clean beauty legislation redefines permissible preservative systems. Direct-to-consumer brands concentrate in digitally native channels bypassing traditional retail markup structures.
Germany
EU Cosmetics Regulation and REACH compliance requirements shape ingredient transparency mandates across export-oriented supply chains. ECHA chemical safety dossier requirements extend botanical extract qualification timelines. Dermatology channel endorsement pulls high-net-worth consumers toward clinically positioned essences in urban centers including Munich and Hamburg.
Facial Essence Market Competitive Landscape
Top-tier vendors anchor biotechnology heritage and integrated R&D control, while mid-cap specialists license fermentation platforms from regional contract manufacturers. The competitive field fragments across three strategic archetypes: heritage conglomerates with captive supply chains, clinical positioning specialists with dermatology channel access, and clean-native digital brands with subscription algorithm optimization. Dominant competitive moves include strategic partnerships for bio-active ingredient licensing and geographic expansion through streamlined regulatory filing in priority markets.
Within the heritage biotechnology tier, Shiseido and SK-II exemplify integrated R&D control over fermentation supply chains. Augustinus Bader occupies a position at the clinical-specialist intersection with cell-renewal positioning commanding dermatologist endorsement in European and North American channels. Among clean-native specialists, Sunday Riley represents algorithm-optimized subscription retention models in North American direct-to-consumer markets.
| Leading Market Players |
|---|
| SkinCeuticals |
| EltaMD |
| SK-II |
| Eminence Organic Skin Care |
| Sunday Riley |
| Shiseido |
| Obagi Medical |
| NEOCUTIS |
| Augustinus Bader |
| Others |
Supply & Pricing Matrix
Sodium hyaluronate feedstock indices from Chinese biotech suppliers cascade through three distinct pricing tiers, compressing margins for mid-tier hydrating essence producers while premium fermented bio-active platforms sustain pricing power through captive fermentation supply chains in South Korea and Japan.
Pricing Analysis
Capacity additions in Chinese sodium hyaluronate fermentation facilities are reshaping price floors for mass-market hydrating essences. Three-tier pricing structure across premium, standard, and economy levels separates SK-II's Pitera biotechnology heritage from mid-tier peptide complexes and entry-level glycerin formulations. Pricing pressure stems from sheet mask substitution in trial-oriented consumer segments. Mass-market buyers in Southeast Asian urban centers show highest price sensitivity, while dermatology channel consumers in Chinese tier-one cities accept premium positioning.
Supply Chain Analysis
Fermentation-derived bio-active supply rests on South Korean, Japanese, and Chinese biotechnology infrastructure. Key inputs include proprietary organism strain libraries, cell-free fermentation extracts, and stabilized peptide complexes. Single-source vulnerability concentrates in Seoul and Yokohama R&D lab networks where scientist talent scarcity threatens expansion timelines. Distribution runs through duty-free channels, direct-to-consumer subscription platforms, and dermatology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where streamlined NMPA filing timelines in China compress market access costs relative to REACH compliance burdens in Europe, rewarding brands with existing clinical data repositories.
For Market Incumbents: Extend fermentation platform licensing agreements to regional contract manufacturers, decoupling R&D scale from capital-intensive facility ownership. Cell-free fermentation technology diffusion threatens captive supply advantages. Backward integration into organism strain libraries preserves differentiation against mid-tier competitors accessing shared biotech infrastructure.
For New Entrants and Emerging Players: California's microbiome-friendly certification frameworks open a window for preservative-free positioning in clean beauty retail channels. Post-shave essence occasions in North American men's grooming represent underdeveloped whitespace. Direct-to-physician sampling programs bypass traditional retail markup structures for clinic channel entry.
For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-positioning specialists commanding dermatology endorsement and algorithm-optimized subscription retention models. Long-term viability favors brands with proprietary fermentation process patents over marketing-dependent labels. Watch NMPA filing volume acceleration as inflection indicator for China market access competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Licensing | Decentralizes bio-active production economics for mid-tier brands seeking premium ingredient access. |
| Microbiome Certification Investment | California and New York state legislation redefines permissible preservative systems for clean beauty positioning. |
| Dermatology Channel Expansion | Physician endorsement carries particular weight in Chinese tier-one cities and Southeast Asian urban centers. |
| Subscription Algorithm Optimization | Automated replenishment tied to usage tracking concentrates high-lifetime-value consumers in North American markets. |
| Dual Formulation Pipeline Maintenance | EU Cosmetics Regulation transparency mandates require parallel supply chains for European and Asian markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation scientists at South Korean and Japanese R&D labs, regulatory affairs specialists navigating NMPA and REACH filings, dermatology clinic procurement managers, and clean beauty retail buyers with secondary validation from MFDS functional cosmetic registration databases, EU Cosmetics Regulation ingredient disclosure filings, and customs trade data for sodium hyaluronate feedstock movements. Bottom-up brand-level revenue estimates triangulated against top-down category sizing from retail audit channels.
Segment-weighted modeling across product type, end user, ingredient category, and distribution channel dimensions generated volume and value trajectories over the projection horizon. CAGRs derived from trend-line extrapolation of historical growth patterns adjusted for regulatory filing acceleration effects and biotechnology patent expiration schedules. Industry-specific inputs included fermentation capacity expansion announcements and microbiome-friendly certification adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA policy reversal or REACH compliance timeline extensions. Forecasts reflect assumptions around consumer routine adherence and channel mix stability. Regulatory filing delays, hyaluronic acid feedstock price spikes, and sheet mask category innovation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market