
 Eyelash Enhancing Agents Market | 2026-2036
Eyelash Enhancing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Eyelash Enhancing Agents Market Analysis
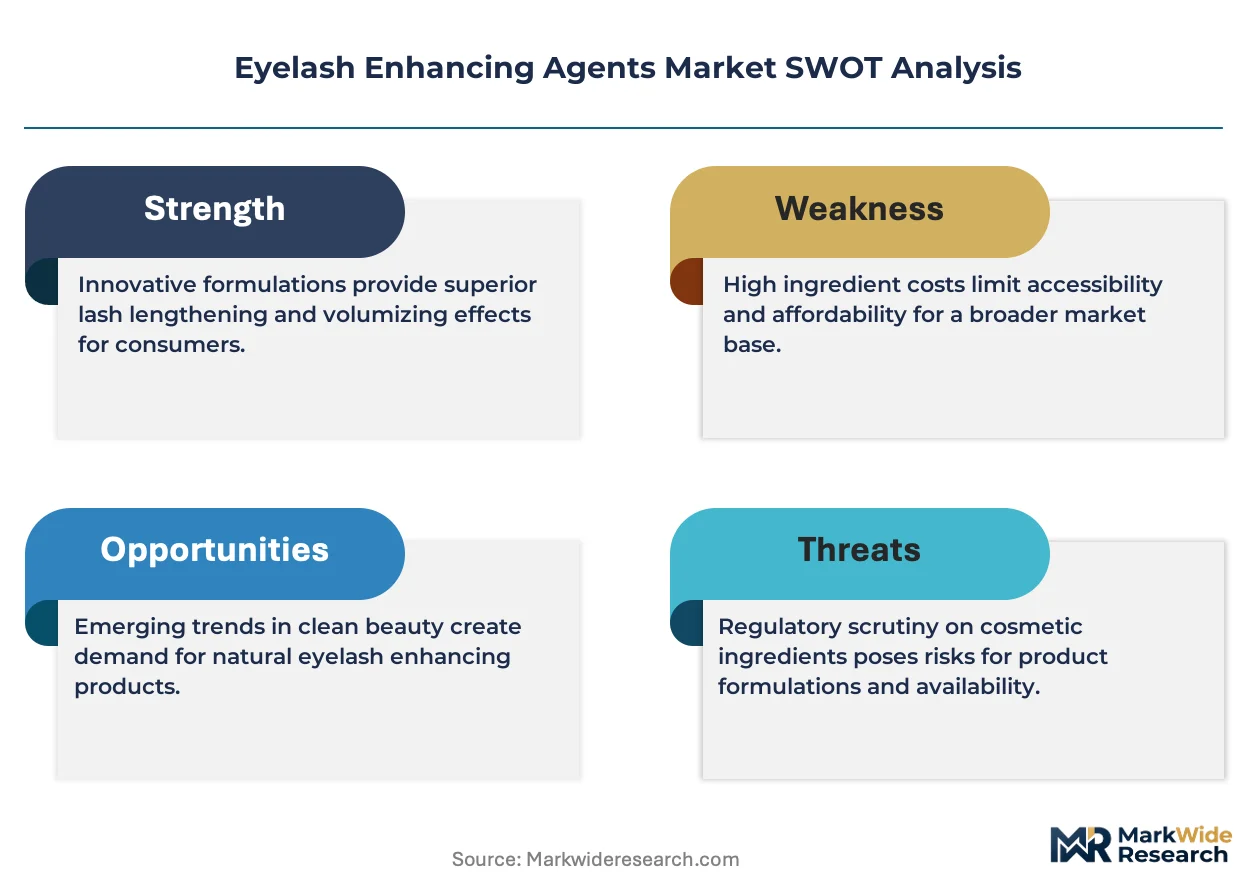
The EU Green Deal is rebalancing formulation priorities across the eyelash enhancing agents sector, compelling manufacturers to phase out certain synthetic prostaglandin analogs and prioritize biodegradable conditioning bases. L'Oréal S.A. leverages its integrated R&D pipeline to fast-track clean-label peptide alternatives, while The Estée Lauder Companies Inc. anchors its premium positioning through dermatologist-validated claims and controlled clinical testing. AbbVie Inc. competes in the therapeutic segment with its established prescription-grade heritage, sustaining physician trust channels that mass-market entrants struggle to replicate.
Eyelash enhancing agents comprise topical formulations designed to stimulate keratinocyte proliferation in the hair follicle, typically incorporating prostaglandin derivatives, peptides, biotin, or panthenol at concentrations between 0.01% and 0.15% active ingredient, with primary commercial purpose spanning cosmetic lengthening, therapeutic restoration post-chemotherapy, and daily conditioning maintenance. Serums dominate value capture due to higher per-unit pricing and repeat purchase frequency, while the therapeutic application segment commands premium positioning through clinical validation requirements that mass cosmetic channels cannot easily satisfy. The online distribution channel is expanding fastest, though specialty stores retain margin advantages through personalized consultation and professional-grade product access.
FDA oversight of prostaglandin-containing lash serums as drug-device combinations, EMA's REACH-aligned scrutiny of cosmetic ingredient safety dossiers, and the EU AI Act's emerging implications for algorithm-driven personalized beauty recommendations collectively shape product development timelines and market access pathways. Compliance investments now function as competitive moats, particularly for entrants lacking established regulatory affairs infrastructure. Stakeholders must monitor evolving jurisdictional classifications that could reclassify over-the-counter serums as prescription-required therapeutics in key markets.
Market Dynamics
The EU Green Deal's ingredient disclosure mandates are compressing formulation timelines across the eyelash enhancing agents sector, forcing manufacturers to retire synthetic prostaglandin analogs and validate biodegradable peptide alternatives through accelerated stability testing protocols.
Growth Catalysts
- EU Green Deal compliance deadlines:REACH-aligned safety dossier requirements are accelerating clean-label R&D investment, pushing peptide-based formulations toward commercial scale faster than historical cosmetic development cycles.
- Post-chemotherapy therapeutic restoration:Oncology centers in the United States are expanding dermatologist partnerships for prescription-grade lash serums, creating dedicated channels for clinically validated products.
- Direct-to-consumer subscription infrastructure:Automated replenishment platforms are compressing customer acquisition costs and locking in recurring revenue streams for serum manufacturers.
Market Restraints
- Prostaglandin API supply concentration:Active pharmaceutical ingredient manufacturing for bimatoprost analogs clusters among Chinese contract manufacturers, exposing formulators to geopolitical logistics disruptions and customs clearance volatility.
- FDA drug-device classification friction:Over-the-counter serums containing prostaglandin derivatives face reclassification risk as prescription-required therapeutics, threatening mass-market distribution economics.
- Peptide synthesis cost structure:Solid-phase peptide manufacturing requires specialized resin substrates and protected amino acid building blocks that command premium spot pricing versus petroleum-derived cosmetic actives.
Strategic Opportunities
- Clean-label convergence with microbiome science:Prebiotic conditioning bases paired with keratin-stimulating peptides are opening positioning territory between mass cosmetics and prescription therapeutics.
- Professional salon channel expansion:Licensed estheticians in California and New York are dispensing therapeutic-grade serums under physician supervision, bypassing traditional retail margin structures.
- EMA centralized procedure harmonization:Mutual recognition pathways for cosmetic active safety assessments are reducing redundant toxicology spend for pan-European product launches.
Industry Challenges
- Formulation chemist talent scarcity:Cosmetic science programs produce fewer graduates with dual expertise in peptide chemistry and regulatory toxicology than the sector's reformulation pipeline demands.
- Clinical validation capex intensity:Prospective lash growth studies require standardized photography protocols, independent grading panels, and six-month observation windows that strain mid-tier marketing budgets.
- Supply chain reconfiguration friction:Switching from Asian-sourced prostaglandin intermediates to European-manufactured peptide alternatives demands new supplier qualification audits and stability testing matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyelash Enhancing Agents Market |
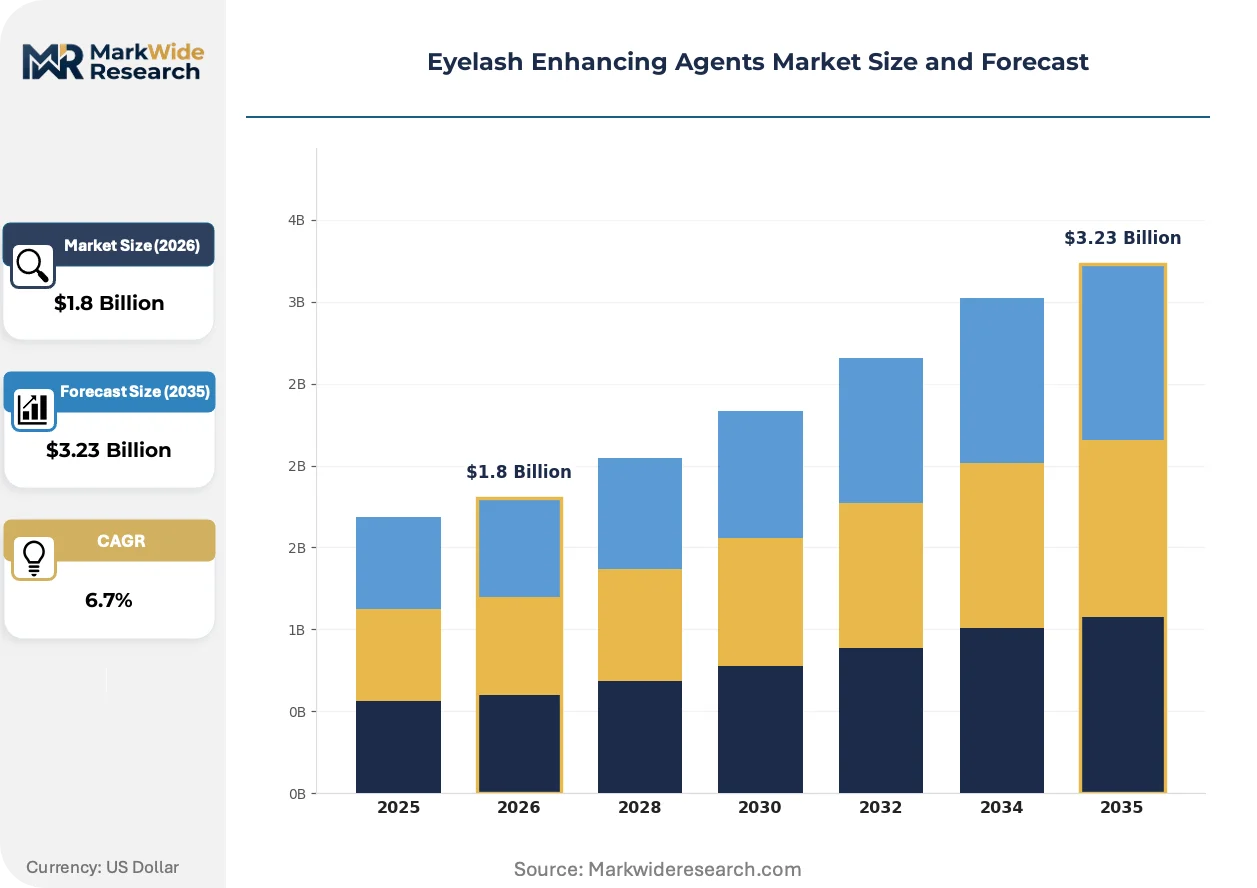
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Mascaras, Primers, Oils Application: Cosmetic, Therapeutic, Daily Care, Professional Use End User: Women, Men, Salons, Retail Stores Distribution Channel: Online, Offline, Specialty Stores, Supermarkets |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., AbbVie Inc., Shiseido Company, Limited, Grande Cosmetics, LLC, Procter & Gamble, RevitaLash Cosmetics, Athena Cosmetics, Inc., Skin Research Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyelash Enhancing Agents Market Emerging Trajectories
Biotechnology-derived actives are displacing synthetic chemistry across premium lash serum formulations, compressing the historical gap between cosmetic efficacy claims and clinically measurable outcomes.
Peptide-biotin hybrid molecules are unifying follicle stimulation with structural reinforcement in single-active designs. Prestige cosmetic houses in France and the United States are adopting these hybrids at pilot scale for 2025 launches. The technology is unifying previously separate conditioning and growth product categories into multifunctional serums that command higher per-unit pricing.
EMA's REACH substance evaluation roadmap is tightening data requirements for cosmetic peptides imported into the European Union. Manufacturers must submit extended one-generation reproductive toxicity studies for novel actives, extending registration timelines by 18-24 months. Smaller formulators lacking in-house toxicology teams are outsourcing dossier preparation to specialized contract research organizations in Switzerland and Germany.
Subscription-based replenishment is displacing traditional retail purchasing for daily-use lash serums. Direct-to-consumer brands are capturing recurring revenue through algorithm-driven shipment timing, while specialty beauty retailers respond with membership programs offering professional consultation access. The behavioral shift is most pronounced in urban United States markets where dermatologist-validated claims drive premium willingness-to-pay.
Eyelash Enhancing Agents Market Segmentation
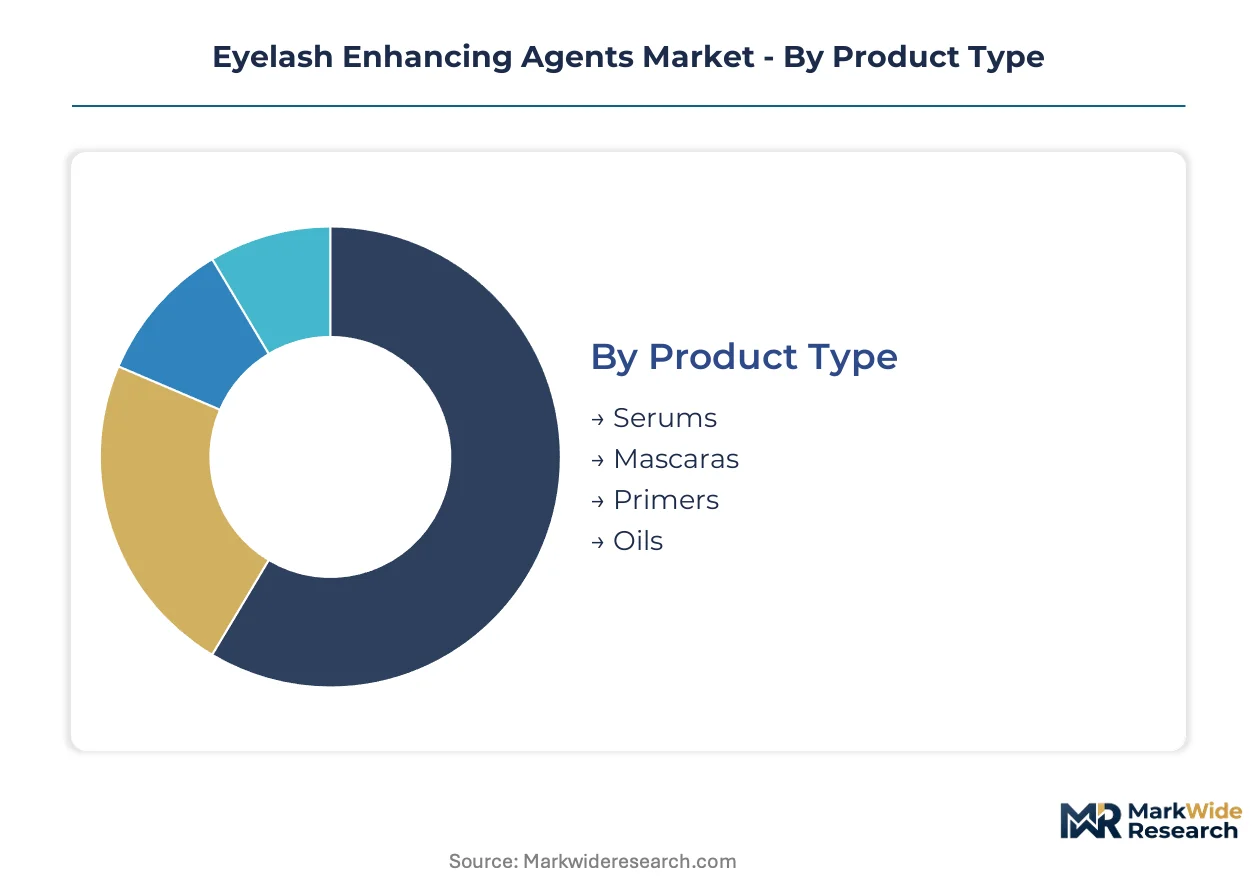
Segmentation in eyelash enhancing agents determines formulation concentration, regulatory pathway, and channel economics. Product type dictates active ingredient selection and pricing architecture, while application scope separates cosmetic claims from therapeutic validation requirements.
Product Type:
Replacement cycles vary dramatically across formats, with daily-use serums demanding quarterly replenishment versus annual mascara purchases that drive different margin structures.
- Serums:Liquid formulations with 0.01% to 0.15% active concentration of prostaglandin derivatives or peptides, packaged in brush-applicator vials for nightly follicle application. Demand concentrates in the United States through dermatologist partnerships and direct-to-consumer subscriptions, where clinical validation commands premium positioning.
- Mascaras:Pigmented wax-oil emulsions incorporating conditioning additives like panthenol or biotin for daytime lash coating and visual enhancement. Volume clusters in mass retail channels across France and Germany, pressured by clean-label reformulation mandates under the EU Green Deal.
- Primers:Pre-mascara conditioning bases with keratin-binding polymers designed to improve adhesion and reduce breakage during cosmetic removal.
- Oils:Anhydrous botanical or mineral oil blends marketed for overnight conditioning, typically lacking follicle-stimulating actives and competing at economy price tiers.
Serums sit at the top of the volume ranking, with primers climbing the fastest as hybrid positioning between treatment and cosmetic gains traction.
Application:
Cost tier separation runs deepest here, with therapeutic-grade manufacturing absorbing validation expenses that mass cosmetic channels cannot sustain.
- Cosmetic:Appearance-focused formulations emphasizing visible lengthening and volumizing without clinical efficacy claims. Demand concentrates in online direct-to-consumer platforms across the United States, where algorithm-driven personalization drives subscription attachment.
- Therapeutic:Prescription-grade or physician-dispensed products for post-chemotherapy restoration, alopecia, or trichotillomania, requiring FDA or EMA safety dossiers. Volume clusters in oncology-dermatology partnership programs at major United States medical centers, where reimbursement pathways and clinical trust create defensible margins.
- Daily Care:Maintenance-oriented formulations positioned between cosmetic and therapeutic, typically sold through specialty beauty retailers with consultation services.
- Professional Use:Salon-dispensed serums applied by licensed estheticians under physician protocols, bypassing retail margin extraction in California and New York regulatory environments.
Therapeutic commands the highest per-unit pricing, with professional use expanding most quickly as supervision requirements tighten.
End User:
Customer type determines packaging format, marketing channel, and the balance between clinical credibility and lifestyle aspiration in positioning.
- Women:Primary consumer base across all product tiers, with segmentation by age cohort driving formulation texture and applicator design preferences. Demand concentrates in urban United States markets for subscription serums, while European purchasing favors pharmacy-channel validation.
- Men:Emerging segment with specialized marketing emphasizing subtle enhancement and grooming integration rather than dramatic transformation claims.
- Salons:Licensed service providers purchasing professional-grade formats for in-treatment application and retail resale to clientele.
- Retail Stores:Multi-brand beauty retailers and pharmacy chains stocking mass-market and masstige tiers with high inventory turnover requirements.
Women represent the volume anchor, with men gaining share fastest as gender-neutral grooming positioning expands.
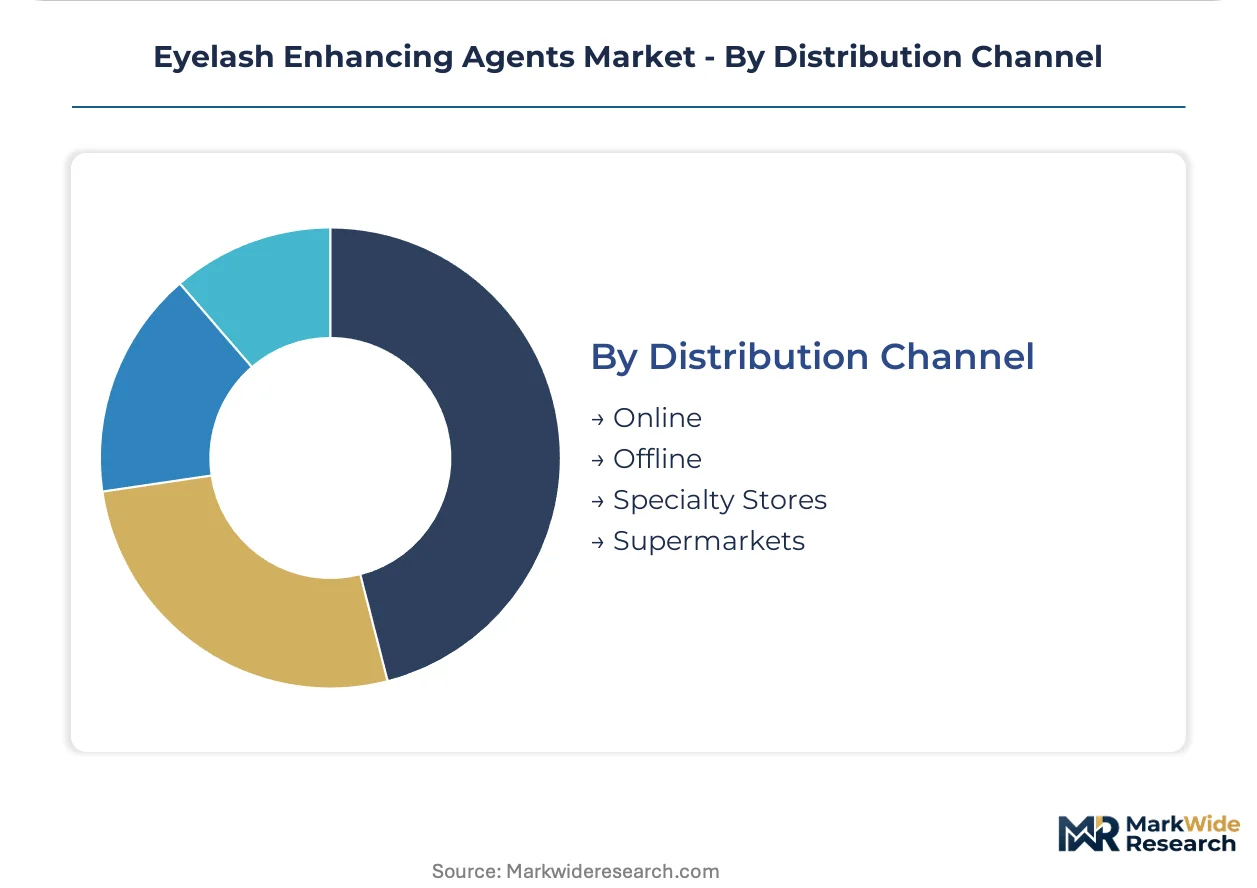
Distribution Channel:
Margin structure and customer acquisition economics diverge sharply between digital-native and physical retail pathways.
- Online:Brand-owned websites and marketplace platforms enabling subscription replenishment, algorithmic personalization, and direct consumer data capture. Demand concentrates in the United States, where DTC infrastructure and dermatologist influencer partnerships compress customer acquisition costs.
- Offline:Department stores and pharmacy chains providing tactile product experience and immediate fulfillment, dominant in European markets with stronger physical retail traditions.
- Specialty Stores:Beauty-focused retailers like Sephora and Ulta offering professional consultation, sample programs, and loyalty membership tiers.
- Supermarkets:Mass-market penetration for economy-tier mascaras and conditioning oils with impulse-purchase placement and high volume, low margin economics.
Online leads in value growth rate, with specialty stores retaining the highest per-transaction margins through service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The eyelash enhancing agents industry traces its commercial origins to the United States, where prostaglandin-derived therapeutics first received FDA approval and direct-to-consumer subscription models pioneered modern distribution economics.
United States
Dermatologist partnerships and oncology center dispensing programs drive therapeutic-grade serum demand. FDA drug-device classification scrutiny shapes over-the-counter formulation boundaries. Los Angeles and New York City host the densest concentrations of licensed estheticians dispensing physician-supervised professional treatments.
France
Prestige cosmetic houses anchor clean-label peptide R&D investment. ANSM enforces REACH-aligned safety dossier requirements for novel actives entering the market. Paris-based formulation laboratories pioneer biodegradable conditioning bases that comply with EU Green Deal mandates.
Germany
Pharmacy-channel validation preferences concentrate demand for clinically tested daily care formulations. ECHA substance evaluation protocols extend registration timelines for imported cosmetic peptides. Frankfurt and Munich serve as contract research organization hubs supporting toxicology dossier preparation.
Japan
Hybrid positioning between cosmetic and quasi-drug categories creates regulatory complexity for growth claims. PMDA oversight of follicle-stimulating actives requires distinct safety substantiation from pure cosmetic channels. Tokyo metropolitan area dominates domestic brand headquarters and specialty retail distribution.
South Korea
Advanced peptide synthesis capabilities support biotechnology-derived active ingredient manufacturing. MFDS cosmetic safety standards influence regional formulation export competitiveness. Seoul Capital Area clusters biotech startups developing next-generation keratin-stimulating molecules.
Eyelash Enhancing Agents Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the eyelash enhancing agents sector. Integrated beauty conglomerates with captive R&D pipelines face nimble direct-to-consumer specialists leveraging outsourced manufacturing and algorithmic customer acquisition. The market structures around three archetypes: prescription-grade therapeutic heritage players, prestige cosmetic houses with dermatologist validation networks, and digital-native subscription brands. Competitive moves concentrate on clean-label reformulation races and professional channel expansion under physician supervision protocols.
Within the integrated beauty conglomerate tier, L'Oréal S.A. and The Estée Lauder Companies Inc. occupy positions defined by global regulatory affairs infrastructure and controlled clinical testing capabilities. AbbVie Inc. represents the prescription-grade therapeutic archetype, anchoring physician trust channels that mass-market entrants struggle to replicate. These three entities exemplify how compliance investment functions as competitive moat in an environment of tightening ingredient disclosure requirements and reclassification risk.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| AbbVie Inc. |
| Shiseido Company, Limited |
| Grande Cosmetics, LLC |
| Procter & Gamble |
| RevitaLash Cosmetics |
| Athena Cosmetics, Inc. |
| Skin Research Laboratories |
| Others |
Supply Flow & Price Mechanics
Peptide synthesis technology transitions are compressing cost structures for active ingredient production while simultaneously redistributing supply concentration away from Chinese contract manufacturers toward European and South Korean biotech specialists. This dual shift tightens margin pressure on legacy prostaglandin-dependent formulators while rewarding early adopters of biotechnology-derived alternatives with pricing flexibility in premium tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the eyelash enhancing agents sector, with FDA-validated therapeutic grades commanding substantial premiums over cosmetic serums and mass-market mascaras. Price differentiation rests on clinical validation depth and dermatologist endorsement density, with subscription-based direct-to-consumer models showing lowest price sensitivity among urban United States buyers. Cost compression in the standard tier is intensifying because clean-label reformulation under EU Green Deal mandates absorbs R&D overhead without commensurate pricing power recovery.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for finished serum formulations reaching dermatology practices and specialty retailers. Active pharmaceutical ingredient manufacturing draws from China, India, and South Korea, with prostaglandin analog intermediates clustering among Chinese chemical specialists and peptide alternatives emerging from South Korean biotechnology firms. Single-source vulnerability concentrates in bimatoprost precursor supply, where customs clearance volatility disrupts just-in-time production schedules. Distribution runs through licensed esthetician channels in California and New York, bypassing traditional wholesale margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eyelash enhancing agents market compounds steadily through recurring subscription revenue attachment and therapeutic validation barriers that protect incumbent positioning. Post-chemotherapy restoration protocols and clean-label peptide transitions provide durable growth vectors resistant to cyclical compression.
For Market Incumbents: Deploy regulatory affairs infrastructure as a defensive moat by accelerating FDA safety dossier preparation for peptide-based reformulations ahead of potential prostaglandin reclassification. Secure captive supply agreements with South Korean biotechnology manufacturers to reduce dependency on Chinese API intermediates exposed to geopolitical logistics friction. Channel control through dermatologist partnership programs in oncology centers protects margin structures against direct-to-consumer price erosion. For New Entrants and Emerging Players: Biotechnology-derived peptide-biotin hybrid molecules offer white-space entry between mass cosmetic and prescription therapeutic positioning, with professional salon dispensing under physician supervision representing the most penetrable channel in California and New York regulatory environments. Target men as an emerging segment with gender-neutral grooming positioning that avoids saturated female demographic competition. Algorithm-driven subscription replenishment with dermatologist influencer partnerships provides the most efficient customer acquisition architecture for capital-constrained entrants. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier formulators lacking in-house toxicology teams but possessing validated peptide stability data, as EMA registration timelines stretch cash runways and create distressed acquisition opportunities. Long-term viability over a five-to-ten-year window favors entities with backward integration into peptide synthesis or exclusive biotechnology licensing arrangements. Monitor FDA drug-device classification proceedings for over-the-counter prostaglandin serums as the critical inflection signal determining mass-market distribution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Peptide Reformulation | EU Green Deal compliance secures market access across REACH-aligned jurisdictions. |
| Dermatologist Partnership Programs | Oncology center dispensing creates defensible therapeutic-grade margin structures. |
| Subscription Infrastructure Buildout | Algorithm-driven replenishment locks recurring revenue and compresses customer acquisition costs. |
| Professional Salon Channel Expansion | Licensed esthetician dispensing under physician supervision bypasses retail margin extraction. |
| Biotechnology Licensing Agreements | Exclusive peptide synthesis partnerships reduce prostaglandin API supply concentration risk. |
Methodological Framework
Coverage spans the United States, France, Germany, Japan, and South Korea, with primary inputs from each market combining structured interviews with formulation chemists, regulatory affairs directors at cosmetic houses, dermatologists in oncology-dermatology partnership programs, licensed estheticians in California and New York, and procurement managers at specialty beauty retailers. Secondary validation draws from FDA 510(k) filings, EMA REACH substance evaluation roadmaps, ANSM safety dossier databases, and MFDS cosmetic ingredient standards. Bottom-up demand modeling triangulates against top-down market sizing across serum, mascara, primer, and oil product categories.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, with segmentation modeling incorporating product type, application scope, end user demographics, and distribution channel economics. CAGRs derive from fitted growth curves adjusted for regulatory timeline risks and supply chain reconfiguration friction. Forecast inputs include peptide synthesis capacity expansion timelines, EMA centralized procedure harmonization progress, and direct-to-consumer subscription penetration rates in urban United States markets.
The model holds under stable regulatory classification of over-the-counter serums and sustained EU Green Deal implementation timelines; deviation in FDA drug-device reclassification or REACH substance evaluation acceleration would shift therapeutic-cosmetic boundary economics substantially. Forecasts reflect documented assumptions regarding clean-label R&D investment cycles and biotechnology manufacturing scale-up trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Makeup Emulsion Market