
 Xerosis Market | 2026-2036
Xerosis Market Size, Share, and Industry Trends Forecast 2026-2036
Xerosis Market Outlook
A widening R&D-to-manufacturing scale divergence between multinational incumbents and mid-size dermatology specialists is bifurcating competitive economics in the xerosis treatment landscape. Unilever leverages its mass-market distribution infrastructure to sustain volume leadership in everyday moisturizers. Beiersdorf AG anchors its position through concentrated innovation in barrier-repair formulations. Johnson & Johnson competes across both clinical and consumer channels with differentiated pediatric and adult portfolios.
Xerosis denotes pathologically dry skin resulting from impaired barrier function, reduced ceramide levels, or diminished sebum production, typically manifesting as pruritus, fissuring, and scaling that demands lipid-replenishing intervention. The condition drives commercial demand across emollient and moisturizer categories where occlusive and humectant mechanisms restore stratum corneum integrity. Emollients and moisturizers together occupy the dominant value pool given their daily-use frequency and broad accessibility through retail and pharmacy channels. Topical delivery dominates volume flows, though transdermal innovations are gaining share where sustained-release ceramide complexes command premium positioning. Dermatology clinics and home care settings split the patient journey, with clinics capturing initial diagnosis and prescription-grade introductions while home care sustains long-term adherence and repurchase cycles.
The FDA oversees topical drug-cosmetic boundary classifications that determine whether xerosis products require pre-market approval or qualify as over-the-counter skincare, directly shaping formulation investment and label claims. EPA and state-level environmental regulations constrain preservative selections and packaging sustainability profiles, forcing reformulation cycles across US-manufactured portfolios. EMA and REACH compliance in Europe adds parallel certification burdens for multinational suppliers operating across jurisdictions. Stakeholders must monitor evolving FDA monograph updates and state chemical disclosure laws to preempt compliance-driven product redesigns and channel restrictions.
Market Dynamics
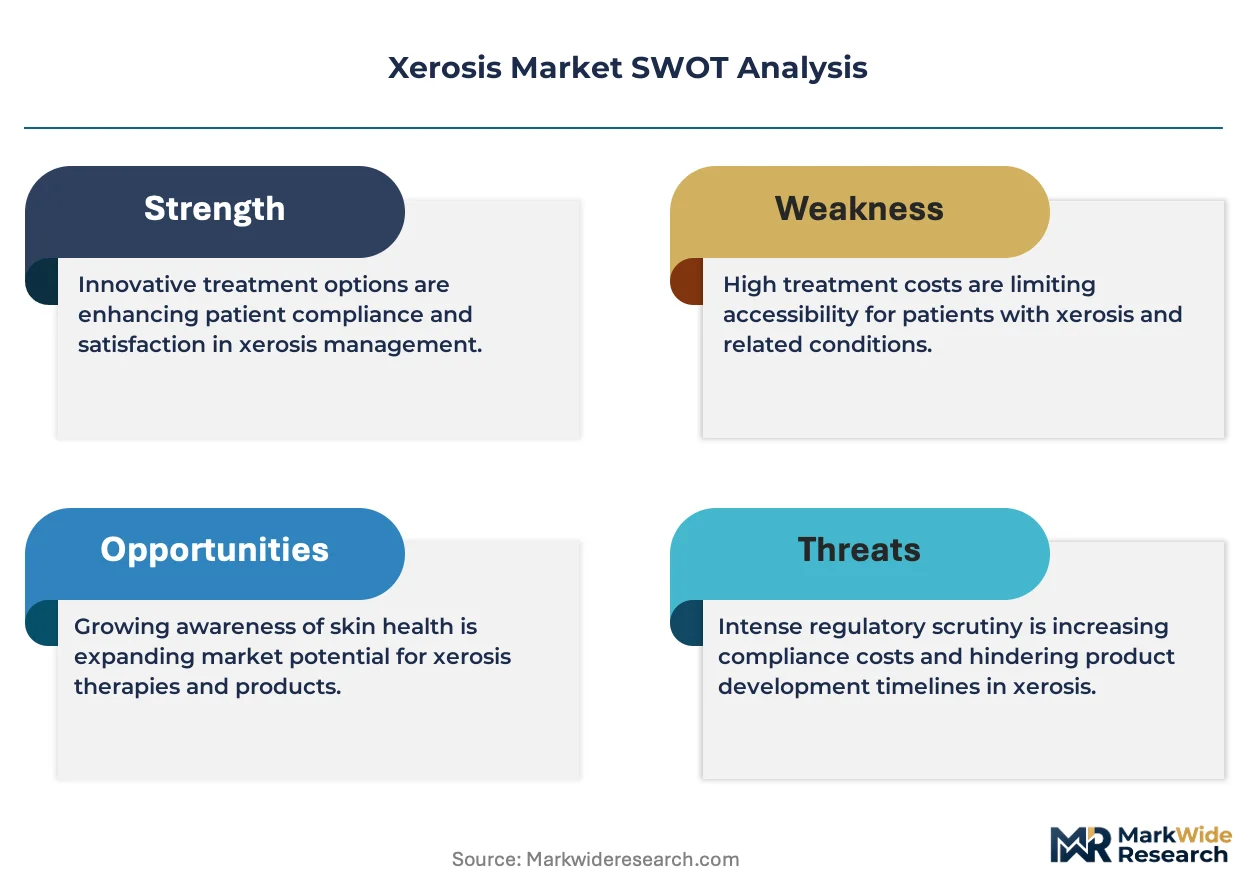
The Xerosis Market is bifurcating along a clinical-consumer boundary where FDA monograph revisions and dermatology clinic consolidation are compressing formulation timelines for mass-market entrants while elevating barrier-repair science as the central competitive differentiator.
Growth Catalysts
- EMA barrier-repair guidelines:European regulatory clarity on ceramide-complex efficacy is accelerating prescription-to-OTC migration pathways for mid-tier manufacturers seeking dual-channel positioning.
- Direct-to-consumer telehealth platforms:Virtual dermatology consultations in the United States are collapsing patient acquisition costs and expanding addressable reach beyond traditional pharmacy footprints.
- Sustained-release transdermal delivery:Novel encapsulation technologies for ceramide complexes are extending dosing intervals and commanding premium shelf positioning in dermatology clinics.
Market Restraints
- Petrochemical feedstock volatility:Occlusive base materials including petrolatum and mineral oil face input cost swings that compress margin structures for everyday moisturizer portfolios.
- Single-source ceramide suppliers:Concentrated production of bio-identical ceramide-3 in Japanese and Korean specialty chemical facilities creates supply vulnerability for barrier-repair formulators.
- FDA cosmetic-drug boundary uncertainty:Pending monograph updates for anti-itch claims impose reformulation risk and label restriction exposure across OTC xerosis portfolios.
Strategic Opportunities
- Pediatric atopic dermatitis adjacency:Unmet need in infant and toddler xerosis management presents white-space expansion for gentle, fragrance-free formulations with pediatrician endorsement pathways.
- Subscription-based replenishment models:Automated home delivery for chronic-condition patients is capturing lifetime value and reducing pharmacy switching behavior.
- EPA Safer Choice certification leverage:Federal environmental preferential procurement programs are opening institutional channels including nursing homes and hospital discharge protocols.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in stratum corneum lipid biology and transdermal penetration science commands premium compensation and constrains R&D throughput for mid-size players.
- Clinical validation timeline compression:Accelerated FDA monograph cycles demand faster TEWL (transepidermal water loss) study completion, straining contract research organization capacity and extending time-to-market for novel actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xerosis Market |
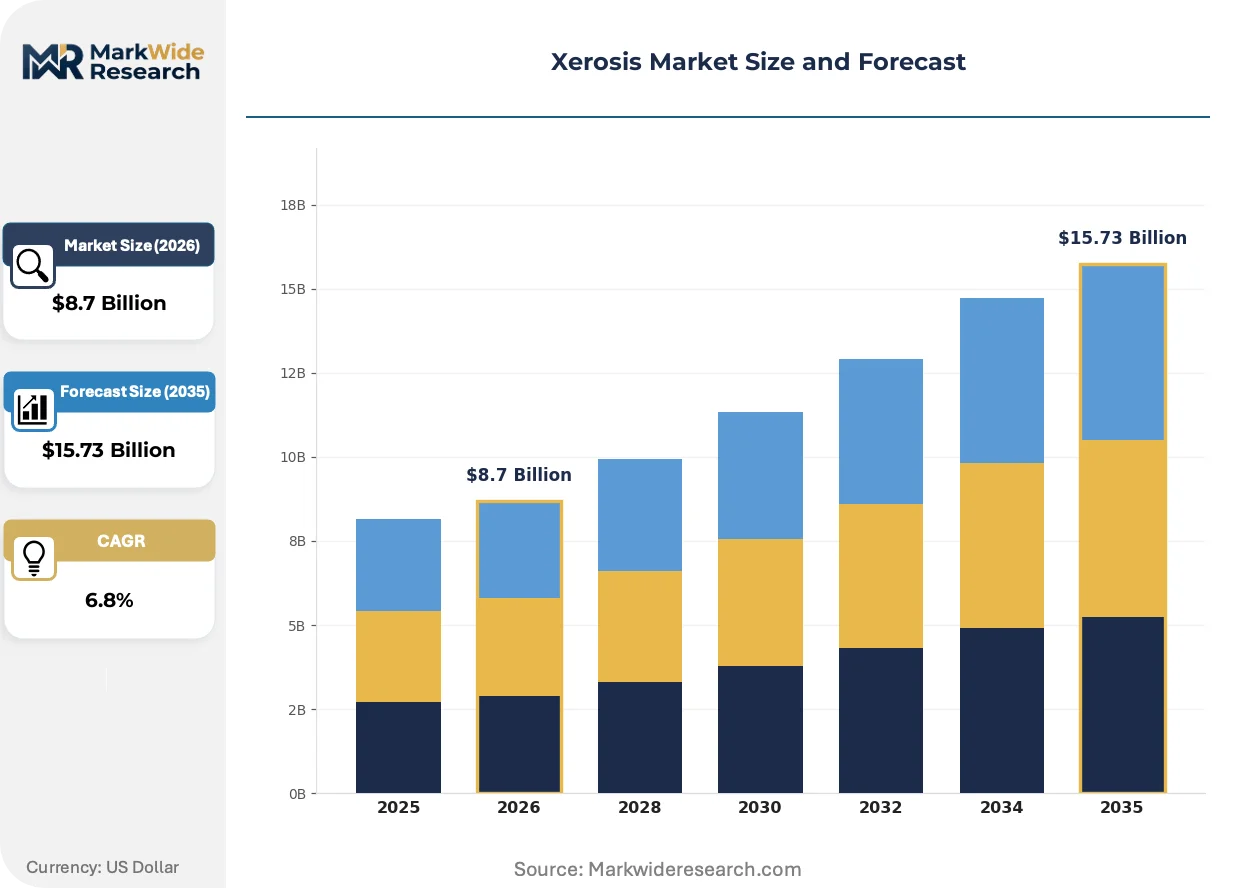
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Moisturizers, Creams, Ointments Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Hospitals, Dermatology Clinics, Home Care, Pharmacies Application: Skin Care, Eye Treatment, Nutrition, Pediatric Care |
| Companies Covered | Unilever, Beiersdorf AG, Johnson & Johnson, GlaxoSmithKline, Galderma, Procter & Gamble, L’Oréal, Pfizer Inc., Kenvue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xerosis Market Strategic Shifts
Biomimetic lipid technology and microbiome-targeted interventions are displacing conventional humectant-centric approaches, while regulatory pressure on preservative systems and packaging sustainability is forcing concurrent reformulation across multiple vector dimensions.
Multi-lamellar vesicle encapsulation of ceramide-cholesterol-free fatty acid ratios is decomposing the traditional emulsion stability paradigm that dominated moisturizer chemistry for three decades. Dermatology clinics in Germany and Switzerland are adopting these systems for severe xerosis and ichthyosis management where conventional petrolatum-based occlusives proved insufficient. The technology is decomposing price-band stratification by enabling single-formulation coverage across mild, moderate, and severe patient presentations.
REACH Annex XVII restrictions on formaldehyde-releasing preservatives are compelling European manufacturers to accelerate phenoxyethanol-free and benzoate-alternative preservation systems. The industrial consequence extends beyond Europe as multinational portfolios standardize on globally compliant preservative matrices to avoid SKU proliferation. North American private-label suppliers serving mass retail are most affected, responding through accelerated stability testing investments and supplier qualification programs for novel preservation technologies.
Patient self-diagnosis via smartphone-enabled skin analysis applications is fragmenting the traditional dermatologist-referral pathway that historically governed prescription-grade product introduction. Amazon and specialized telehealth platforms are capturing these digitally-empowered consumers with algorithmic product matching that bypasses pharmacy consultation. This behavioral shift is most visible in the United States and United Kingdom where direct-to-consumer advertising regulations permit aggressive digital acquisition strategies.
Xerosis Market Segmentation
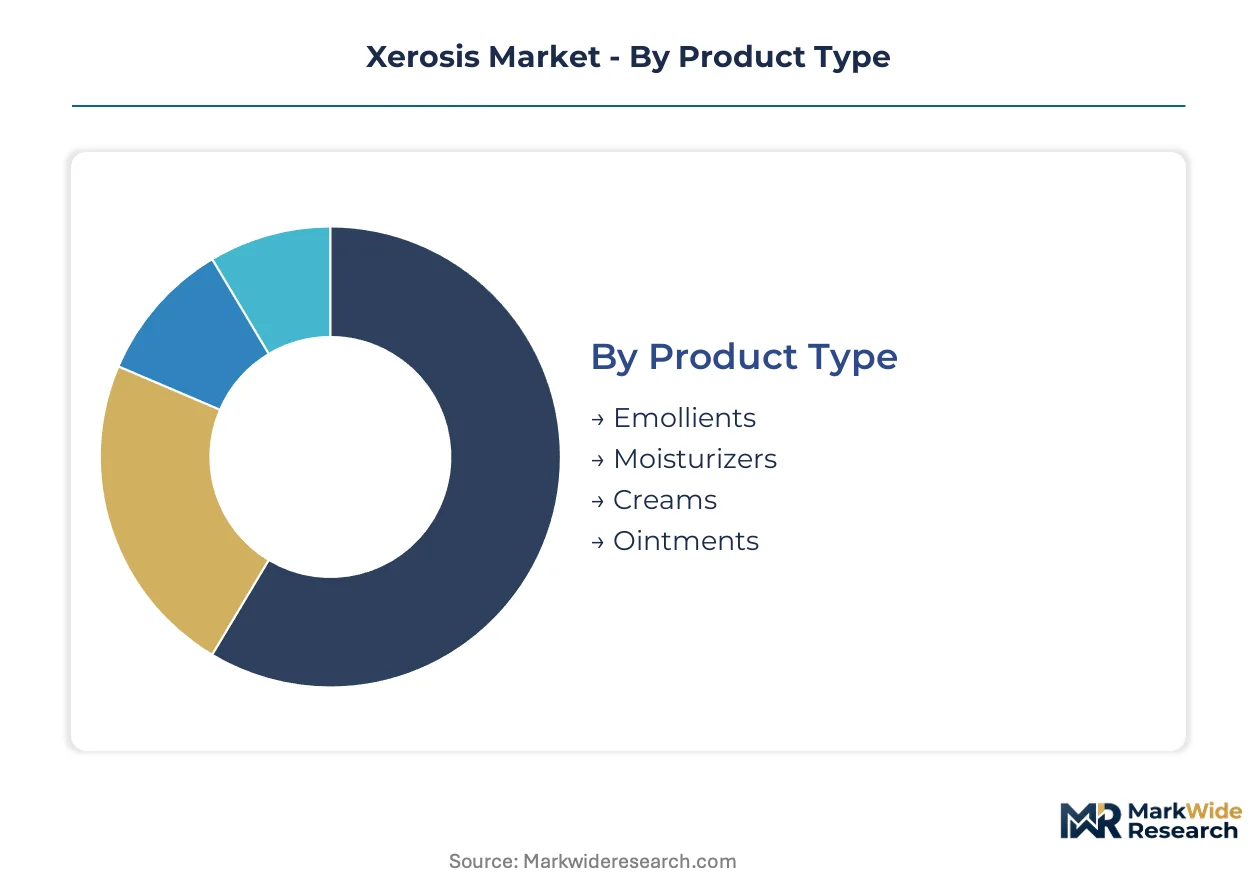
Xerosis treatment markets fragment across product physics, delivery technology, and care setting economics. Understanding segment boundaries clarifies where formulation investments concentrate versus where channel access determines commercial success.
Product Type:
Emollients and moisturizers anchor domestic consumption in the United States and Germany, while cream and ointment exports flow heavily toward Asia-Pacific markets seeking prescription-grade formulations.
- Emollients:Lipid-rich formulations containing petrolatum, lanolin, or plant-derived oils that occlude transepidermal water loss. United States retail pharmacy chains capture the bulk of volume through private-label and branded everyday moisturizers, though FDA monograph uncertainty on anti-itch claims constrains label expansion.
- Moisturizers:Humectant-centric products incorporating glycerin, hyaluronic acid, or urea to attract and bind water within the stratum corneum. German and Swiss dermatology clinics drive premium positioning for ceramide-complex variants, with EMA barrier-repair guidelines accelerating prescription-to-OTC migration for mid-tier manufacturers.
- Creams:Oil-in-water emulsions offering lighter texture and faster absorption for daytime use.
- Ointments:Water-in-oil systems providing maximum occlusion for severe xerosis and ichthyosis management.
Moisturizers command the established base. The steepest expansion runs through emollients as barrier-repair science elevates lipid-centric formulations above conventional humectant approaches.
Delivery Mode:
Cost tier stratification separates high-investment transdermal platforms from commoditized topical tubes, with oral and injectable routes occupying narrow clinical niches where skin barrier compromise precludes surface application.
- Topical:Direct skin application via creams, lotions, gels, and ointments representing the volume foundation. United States mass retail and pharmacy channels dominate, though Japanese and Korean innovation in sustained-release encapsulation is capturing premium positioning in dermatology clinics.
- Transdermal:Advanced delivery systems utilizing multi-lamellar vesicles or microneedle arrays for controlled ceramide release. Swiss and German hospital networks are adopting these for severe presentations where conventional occlusives fail, with patent-protected formulations commanding three-to-five-fold price multiples over standard emulsions.
- Oral:Systemic lipid supplementation and essential fatty acid formulations addressing xerosis secondary to nutritional deficiency.
- Injectable:Biologic interventions for xerosis associated with autoimmune or metabolic disorders, limited to hospital settings.
Topical delivery commands the established base. The steepest expansion runs through transdermal systems as encapsulation technology extends dosing intervals and justifies premium reimbursement.
End User:
Customer type determines purchasing authority and price elasticity, with institutional procurement in hospitals and clinics favoring contract-negotiated volumes while home care and pharmacy channels reward brand recognition and repeat purchase loyalty.
- Dermatology Clinics:Specialized settings where initial diagnosis, severity grading, and prescription-grade product introduction occur. United States clinic consolidation is compressing vendor lists and favoring suppliers with pediatric-adult portfolio breadth.
- Home Care:Long-term adherence and replenishment setting where subscription models and telehealth platforms are capturing lifetime value. German and United Kingdom direct-to-consumer channels show fastest adoption of algorithmic skin analysis tools that bypass traditional pharmacy consultation.
- Hospitals:Acute intervention and discharge protocol settings where EPA Safer Choice certification opens institutional procurement.
- Pharmacies:Traditional retail access point for OTC moisturizers and emollients, facing share erosion from Amazon and specialized telehealth platforms.
Pharmacies command the established base. The steepest expansion runs through home care as automated replenishment and virtual consultation collapse patient acquisition costs.
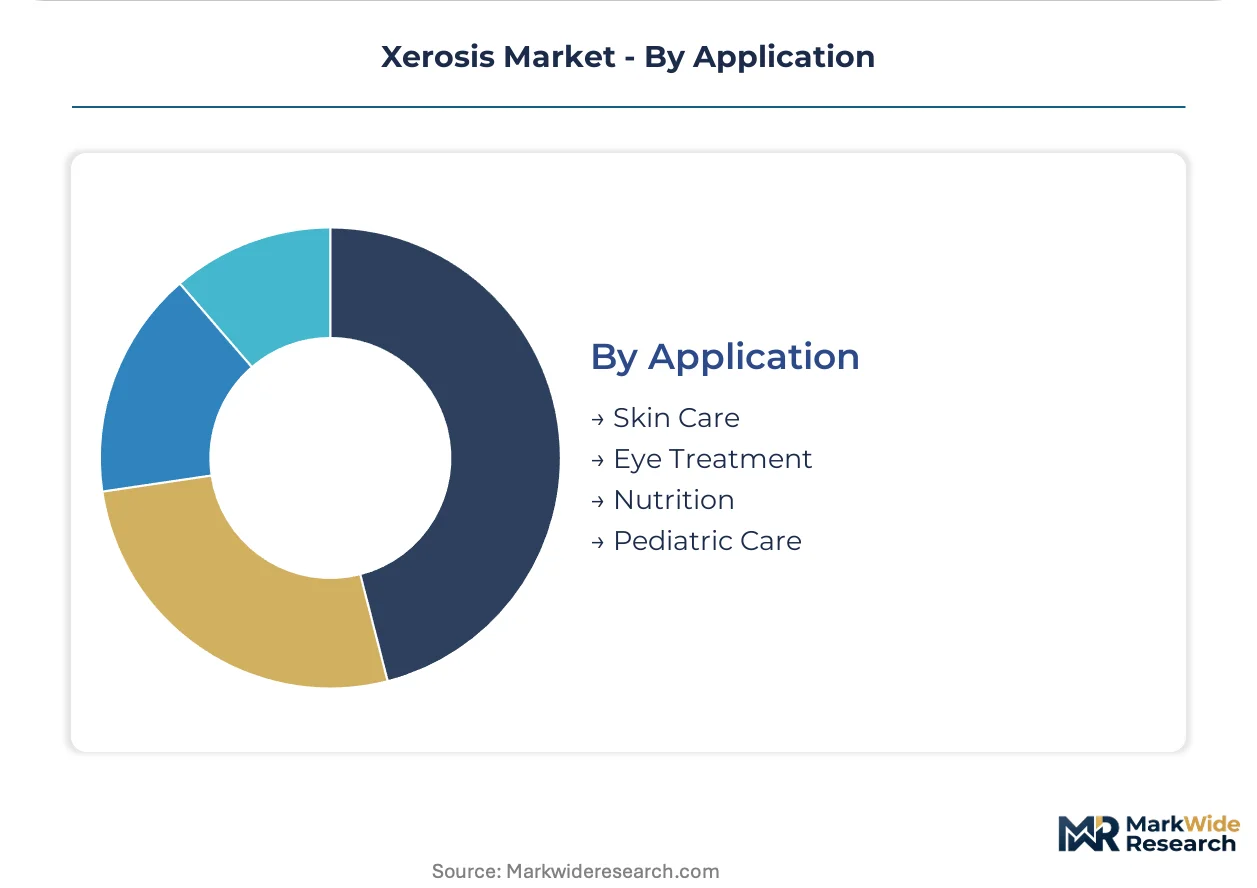
Application:
Maturity gradients separate saturated facial skin care from emerging pediatric and nutritional adjacencies, with eye treatment occupying a narrow premium tier where delicate skin physiology demands specialized formulation.
- Skin Care:Broad facial and body applications encompassing daily moisturization and barrier maintenance. United States aging demographics and direct-to-consumer channel expansion amplify category penetration, though petrochemical feedstock volatility compresses margin structures for mass-market petrolatum-based portfolios.
- Pediatric Care:Infant and toddler xerosis management requiring fragrance-free, hypoallergenic formulations with pediatrician endorsement pathways. Unmet need in atopic dermatitis adjacency presents white-space expansion as parents seek alternatives to steroid-first protocols.
- Eye Treatment:Specialized periorbital formulations addressing delicate skin with reduced sebaceous density.
- Nutrition:Systemic approaches targeting xerosis secondary to essential fatty acid deficiency or malabsorption disorders.
Skin care commands the established base. The steepest expansion runs through pediatric care as fragrance-free, barrier-repair formulations capture parent preference for gentle intervention protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between clinical-channel dominance in German-speaking Europe and direct-to-consumer velocity in the United States, while Asian markets concentrate demand around prescription-grade barrier-repair formulations.
United States
Aging demographics and telehealth platform proliferation are expanding addressable reach beyond traditional pharmacy footprints. FDA monograph uncertainty on anti-itch claims imposes reformulation risk across OTC portfolios. The Northeast corridor concentrates dermatology clinic consolidation activity where vendor lists are compressing.
Germany
EMA barrier-repair guidelines are accelerating prescription-to-OTC migration pathways for mid-tier manufacturers. REACH Annex XVII restrictions on formaldehyde-releasing preservatives compel phenoxyethanol-free preservation system adoption. Bavaria hosts specialized dermatology networks adopting multi-lamellar vesicle encapsulation for severe xerosis management.
Japan
Single-source ceramide-3 production from specialty chemical facilities creates supply vulnerability for regional formulators. METI oversight of cosmetic functional claims shapes investment in sustained-release transdermal delivery research. The Kanto region around Tokyo anchors innovation in encapsulation technologies commanding premium clinic positioning.
Switzerland
Swissmedic regulatory clarity supports early adoption of advanced barrier-repair systems for ichthyosis management where conventional occlusives fail. Hospital networks in Zurich and Geneva are capturing three-to-five-fold price multiples for patent-protected transdermal formulations. The Lake Geneva cluster concentrates contract research organization capacity for TEWL study completion.
United Kingdom
Direct-to-consumer channel expansion is fragmenting the traditional dermatologist-referral pathway through smartphone-enabled skin analysis applications. MHRA alignment with EMA guidelines reduces regulatory friction for continental manufacturers. London and Southeast England concentrate algorithmic product matching platforms bypassing pharmacy consultation.
Xerosis Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational consumer goods conglomerates leveraging mass-market distribution infrastructure against mid-size dermatology specialists competing on barrier-repair science. The structure bifurcates along a clinical-consumer boundary where formulation investment timelines diverge. Two archetypes dominate: mass-market volume leaders sustaining everyday moisturizer penetration, and clinical-channel specialists capturing premium positioning through prescription-grade introductions. Competitive moves concentrate on portfolio diversification across pediatric-adult segments and strategic partnerships with telehealth platforms collapsing patient acquisition costs.
Within the integrated multinational tier, Unilever and Johnson & Johnson occupy positions exemplifying mass-market distribution leverage and dual-channel clinical-consumer breadth respectively. Beiersdorf AG represents the concentrated innovation archetype, anchoring competitive positioning through barrier-repair formulation science. These three entities collectively illustrate how scale, clinical credibility, and specialized R&D investment define distinct competitive vectors in the xerosis treatment landscape.
| Leading Market Players |
|---|
| Unilever |
| Beiersdorf AG |
| Johnson & Johnson |
| GlaxoSmithKline |
| Galderma |
| Procter & Gamble |
| L'Oréal |
| Pfizer Inc. |
| Kenvue |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for ceramide-3 feedstock in Japanese specialty chemical facilities concentrate pricing power with single-source suppliers, while petrochemical volatility in occlusive base materials compresses margin structures for mass-market formulators unable to pass through input cost swings.
Pricing Analysis
Long-term offtake contracts dominate procurement for bio-identical ceramide complexes, insulating premium barrier-repair formulators from spot-market volatility while mass-market petrolatum-based portfolios absorb petrochemical feedstock swings through compressed margins. Price differentiation rests on EMA barrier-repair certification tier and pediatric formulation endorsement, with German dermatology clinics least sensitive and United States private-label retail most responsive to shelf-price competition. Cost compression in everyday moisturizers intensifies as Amazon algorithmic matching erodes brand premium capture.
Supply Chain Analysis
Just-in-time inventory strategies prevail for preservative systems and packaging components, though strategic stockpiling of ceramide-3 concentrates from Japanese and Korean facilities has emerged among Swiss and German formulators seeking supply security. Raw material dependencies center on petrolatum derivatives, bio-identical ceramide-3, and phenoxyethanol-alternative preservation technologies. Single-source vulnerability in East Asian ceramide production creates structural risk. Distribution runs through dermatology clinic consignment, pharmacy wholesale, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA monograph revisions on anti-itch claims and EMA barrier-repair guideline clarity are accelerating prescription-to-OTC migration, creating high-growth disruption as formulation science separates premium clinical positioning from commoditized mass-market penetration.
For Market Incumbents: Compound portfolio breadth across pediatric-adult segments to defend against telehealth platform disintermediation, while deepening backward integration into ceramide-3 supply through Korean and Japanese offtake partnerships to mitigate single-source concentration risk. For New Entrants and Emerging Players: Lead with fragrance-free pediatric atopic dermatitis adjacencies where parent demand for steroid-alternative protocols outpaces incumbent innovation cycles, deploying subscription-based replenishment models to capture lifetime value ahead of pharmacy channel erosion. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dermatology clinic vendor list compression in the United States Northeast corridor and German-speaking Europe favors scaled suppliers with dual-channel clinical-consumer breadth. Target mid-tier barrier-repair specialists with EMA-cleared prescription-to-OTC pathways. The signal to watch is FDA monograph finalization timing on anti-itch claim restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | Fragrance-free, hypoallergenic portfolios capture parent preference in atopic dermatitis adjacency. |
| Ceramide Supply Security Investment | Long-term offtake contracts with Japanese and Korean specialty chemical facilities reduce single-source vulnerability. |
| Telehealth Platform Partnership | Virtual dermatology consultations collapse patient acquisition costs beyond traditional pharmacy footprints. |
| EPA Safer Choice Certification | Federal environmental preferential procurement opens nursing home and hospital discharge protocols. |
| Multi-lamellar Vesicle Scale-Up | Advanced encapsulation technology commands three-to-five-fold price multiples in Swiss and German clinics. |
Study Parameters
A spread of perspectives from formulation chemists at barrier-repair specialists, procurement directors at United States dermatology clinic chains, regulatory affairs leads navigating FDA cosmetic-drug boundaries, and telehealth platform product managers converged on the working assumptions. Secondary validation drew from FDA monograph dockets, EMA barrier-repair guideline documents, REACH Annex XVII preservative restriction updates, and customs records tracking ceramide-3 trade flows. Bottom-up patient-volume modeling and top-down category spend analysis triangulated market sizing.
Segmentation dimensions modeled span product physics (emollient, moisturizer, cream, ointment), delivery technology (topical, transdermal, oral, injectable), care setting economics (dermatology clinic, home care, hospital, pharmacy), and application type (skin care, pediatric care, eye treatment, nutrition). CAGRs were derived from patient population growth, channel shift velocity, and pricing trajectory assumptions across the projection horizon. Forecast inputs incorporated petrochemical feedstock volatility indices and TEWL study completion timelines at Swiss and German contract research organizations.
The analysis sits within stated boundaries; outcomes outside sustained FDA monograph clarity, stable East Asian ceramide supply, and continued telehealth platform reimbursement would require recalibration. Forecasts reflect documented assumptions on patient diagnosis rates and channel migration patterns. Revision becomes warranted when regulatory restriction severity or supply concentration thresholds cross instability bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market