
 Skin Lightening Products Market | 2026-2036
Skin Lightening Products Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Lightening Products Market Intelligence
Subscription-based replenishment programs for serum regimens is expanding how brands lock in recurring revenue from hyperpigmentation treatment users. L'Oréal S.A. leverages its dermatological science heritage to anchor premium positioning in melasma control formulations. Himalaya Global Holdings Ltd. competes through Ayurvedic ingredient differentiation in mass-market lotions across South Asian pharmacy channels. Shiseido Co., Ltd. dominates professional-grade capsule and gel portfolios distributed through Japanese beauty salons.
Skin lightening products comprise topical and ingestible formulations designed to inhibit melanin synthesis through active agents such as hydroquinone, kojic acid, arbutin, and vitamin C derivatives, typically manufactured via emulsification, encapsulation, or lyophilization processes for dermal penetration optimization. These products serve commercial purposes spanning cosmetic aesthetic improvement and clinically supervised hyperpigmentation management. Creams retain the largest volume share due to lower per-unit cost and broader pharmacy distribution, while serums command premium positioning through higher active concentrations and direct-to-consumer online retailer channels. Hydroquinone-based technology faces structural decline in regulated markets as alpha arbutin and vitamin C alternatives capture reformulation investment from manufacturers seeking compliance flexibility.
FDA oversees over-the-counter hydroquinone concentration limits in the United States, while REACH and the EU Green Deal restrict certain whitening actives across European formulations, collectively forcing R&D migration toward botanical and peptide-based alternatives. India's CDSCO and BIS frameworks govern cosmetic safety claims and ingredient disclosure standards that shape product registration timelines for multinational entrants. Stakeholders must monitor regulatory divergence between permissive Asian markets and tightening Western chemical restrictions when allocating formulation development budgets and geographic launch sequencing.
Market Dynamics
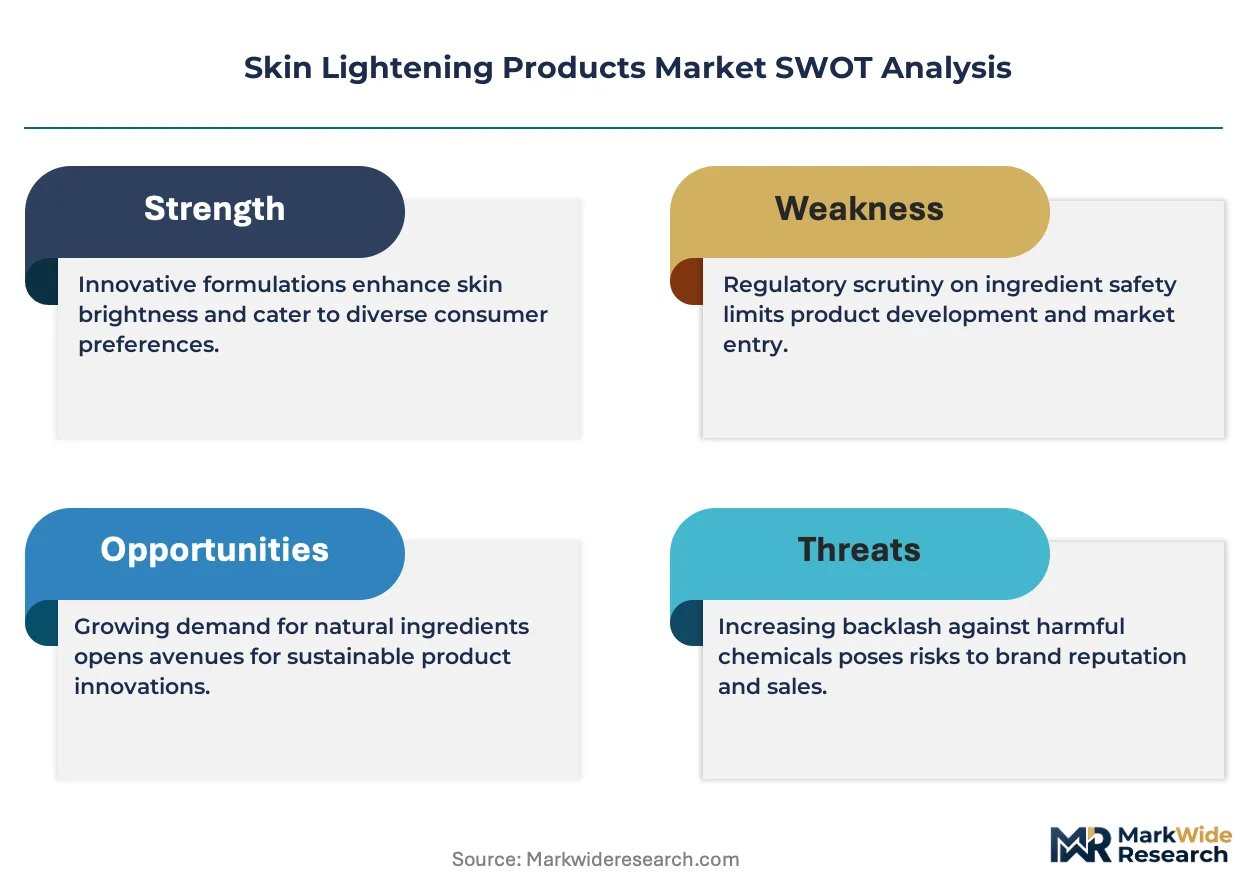
REACH chemical restrictions and parallel FDA scrutiny are forcing wholesale reformulation away from hydroquinone toward botanical peptides and stabilized vitamin C derivatives, compressing R&D timelines and supplier qualification windows for manufacturers serving Western markets.
Growth Catalysts
- Professional channel expansion:Dermatology clinics in India and Japan are adding physician-staffed pigmentation centers, creating institutional demand for prescription-grade arbutin protocols and post-procedure maintenance kits.
- CDSCO registration streamlining:India's cosmetic safety framework now permits parallel filing for ayurvedic-derived actives, accelerating market entry timelines for botanical formulations against synthetic alternatives.
- Encapsulation technology maturation:Liposome and niosome delivery systems are improving dermal penetration of unstable actives, extending shelf life and enabling higher-concentration serum launches through direct-to-consumer channels.
Market Restraints
- Raw material concentration:Kojic acid fermentation capacity clusters in Chinese and Japanese suppliers, exposing formulation houses to input volatility and qualification bottlenecks during supply shocks.
- Regulatory fragmentation:Divergent hydroquinone limits between FDA, REACH, and CDSCO force parallel inventory SKUs, inflating working capital requirements and compliance overhead.
- Peptide synthesis cost structure:Solid-phase peptide manufacturing for melanin-inhibiting sequences runs 3-4x above botanical extraction costs, capping mass-market penetration despite superior efficacy profiles.
Strategic Opportunities
- Subscription replenishment models:Serum regimen auto-delivery programs are locking in 12-18 month customer lifecycles, shifting unit economics toward recurring revenue and reducing customer acquisition cost burdens.
- Men's grooming vertical:Post-inflammatory hyperpigmentation from shaving trauma represents an underserved application, with pharmacy chains in urban India piloting dedicated men's brightening aisles.
- EU Green Deal alignment:Biodegradable packaging mandates and bio-based active sourcing incentives are creating first-mover advantages for brands with vertically integrated botanical supply chains.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in melanin biochemistry and encapsulation engineering concentrates in Japanese and Swiss cosmetic science programs, constraining talent pipelines for mid-tier manufacturers.
- Stability testing timelines:Accelerated aging protocols for vitamin C derivatives require 18-24 month validation cycles, delaying product launches and compressing patent exclusivity windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Lightening Products Market |
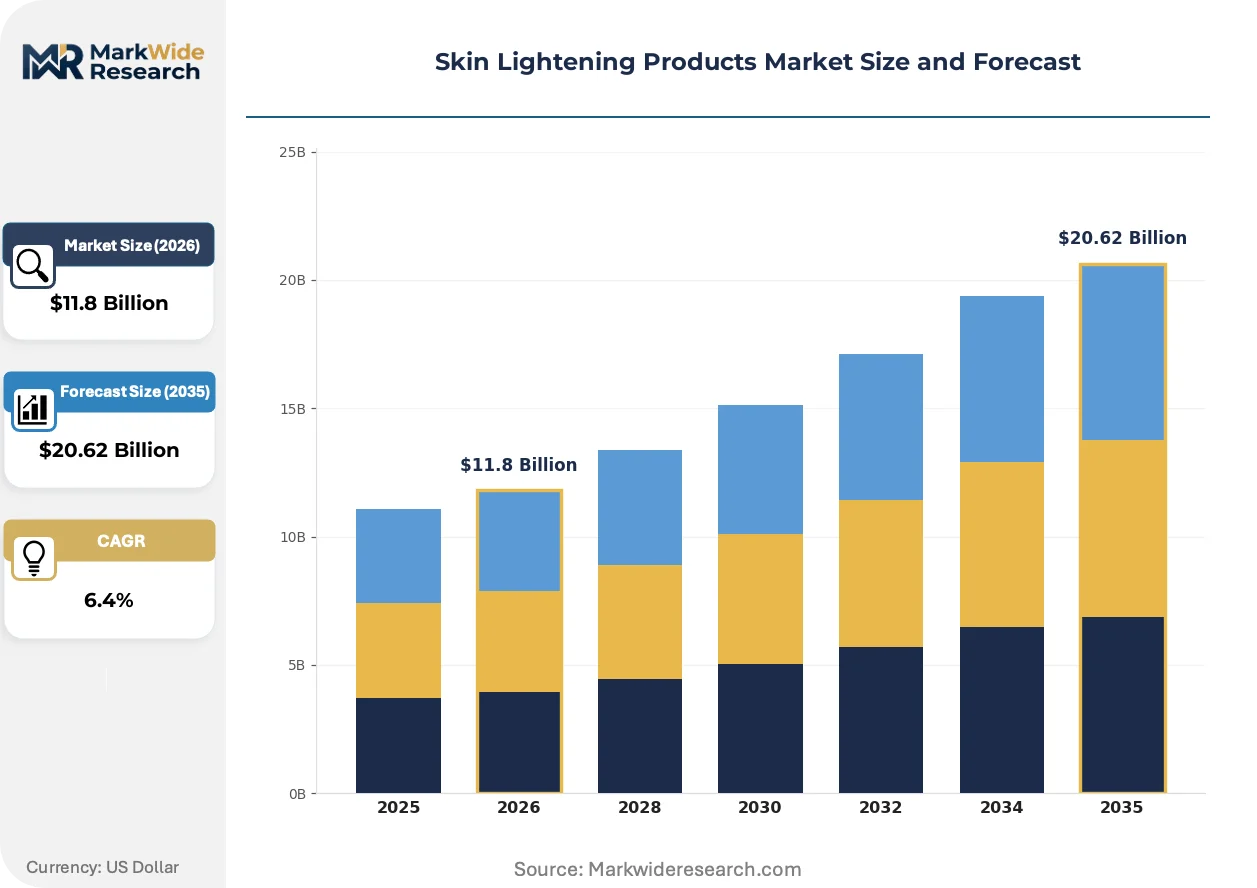
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Serums, Lotions, Capsules, Gels Technology: Hydroquinone, Kojic Acid, Arbutin, Vitamin C, Alpha Arbutin Application: Hyperpigmentation Treatment, Freckle Reduction, Melasma Control, Age Spot Removal, Sun Damage Repair End User: Dermatology Clinics, Beauty Salons, Pharmacies, Online Retailers, Specialty Stores |
| Companies Covered | Unilever PLC, Beiersdorf AG, L'Oréal S.A., Himalaya Global Holdings Ltd., Avon Products, Inc., Procter & Gamble, Shiseido Co., Ltd., Kao Corporation, Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Lightening Products Market Strategic Shifts & Innovations
Formulation science is pivoting toward biomimetic peptide architectures and fermentation-derived actives as legacy chemical pathways face regulatory headwinds, while distribution models fragment between professional clinic channels and algorithm-driven direct-to-consumer platforms.
AI-driven skin analysis applications are automating personalized regimen matching based on Fitzpatrick typing and localized hyperpigmentation mapping, with telemedicine platforms in India and Brazil integrating these tools into pre-consultation workflows. Dermatology chains are licensing this technology to reduce in-person screening burdens. The automation is compressing the traditional consultation-to-purchase funnel from weeks to minutes, favoring brands with integrated diagnostic-retail ecosystems.
REACH authorization requirements for skin-brightening actives are tightening substance volume thresholds and mandating extended safety dossiers for hydroquinone alternatives, forcing manufacturers to maintain dual formulation portfolios. ECHA's 2024 updated guidance on endocrine-disrupting screening has extended registration timelines for arbutin derivatives by 8-14 months. European mass-market brands are responding by accelerating botanical peptide development programs to circumvent chemical authorization pathways entirely.
Pharmacy-led professional advice models are displacing traditional beauty counter consultations across India's tier-one cities, with trained pharmacists recommending ingredient-specific protocols rather than brand-loyal purchases. Apollo Pharmacy and MedPlus chains have deployed certified skin advisors in 340+ locations, shifting volume toward private-label and clinician-endorsed formulations. This channel migration is most pronounced in Mumbai, Delhi, and Bangalore, where insurance-linked wellness spending is converging with cosmetic skincare purchasing.
Skin Lightening Products Market Segmentation
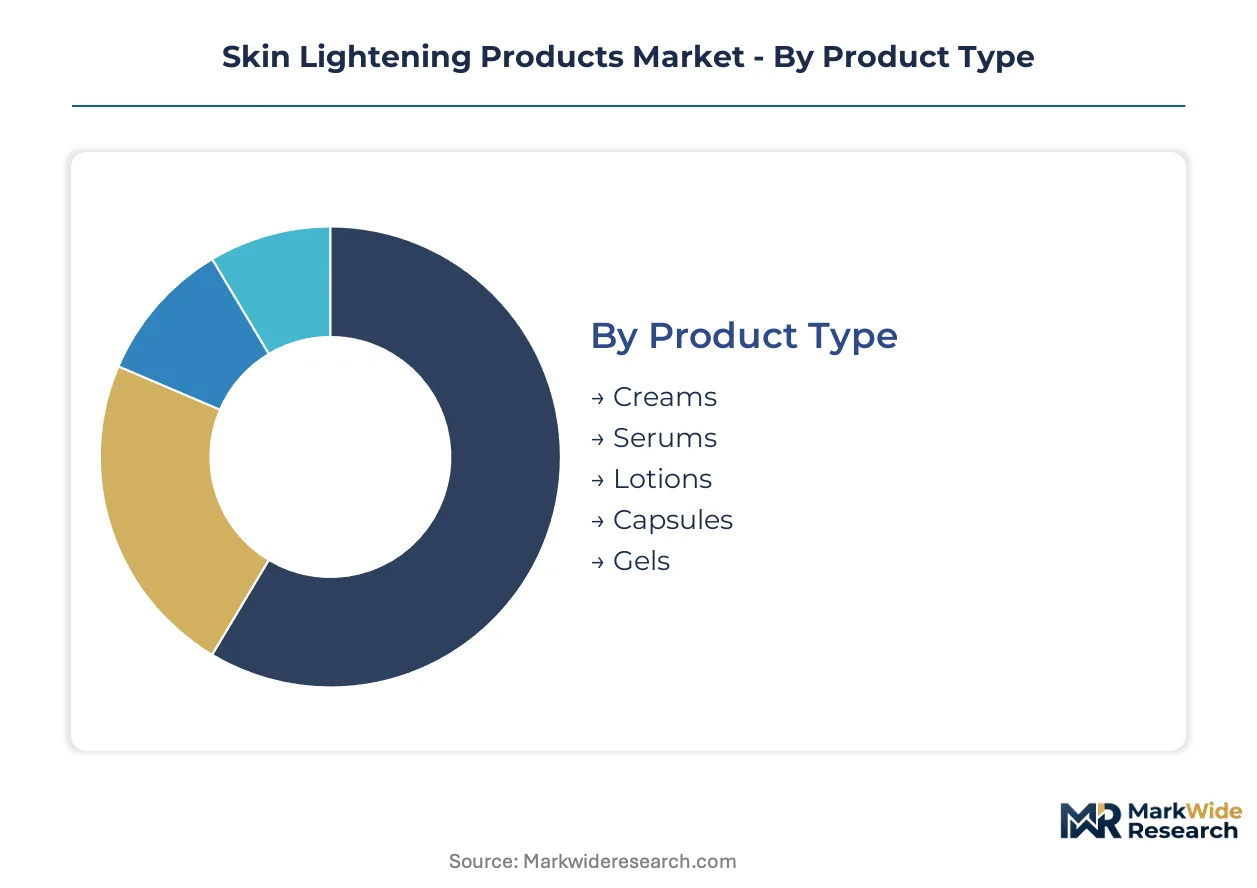
Product differentiation in skin lightening follows distinct consumption patterns across formulation formats, active technologies, and channel access. Manufacturers align R&D investment with regulatory tolerance thresholds and professional versus retail distribution economics.
Product Type:
Production capacity clusters around emulsion-based formats due to established manufacturing infrastructure and lower per-unit processing costs.
- Creams:Oil-in-water emulsions with 2-5% active concentrations dominate pharmacy shelf space. Demand concentrates in India's tier-one cities where Apollo Pharmacy and MedPlus chains drive volume through trained skin advisor consultations. Lower per-unit costs and broader distribution networks sustain mass-market penetration despite slower dermal absorption rates.
- Serums:Water-based formulations with 10-20% active loads command premium positioning through direct-to-consumer channels. Japanese beauty salons in Tokyo and Osaka distribute professional-grade capsule and gel portfolios, while subscription replenishment programs lock in 12-18 month customer lifecycles. Higher concentrations require stabilized encapsulation technology, extending R&D timelines.
- Lotions:Lightweight fluid emulsions target body-area applications with lower viscosity requirements. Himalaya Global Holdings Ltd. competes through Ayurvedic ingredient differentiation in mass-market formats across South Asian pharmacy channels.
- Capsules:Single-dose encapsulation systems preserve active stability in oxygen-sensitive formulations. Professional clinic protocols in dermatology settings favor precise dosing control.
- Gels:Hydro-alcoholic matrices suit oily skin applications and post-procedure protocols. Post-inflammatory hyperpigmentation from shaving trauma drives pilot programs in urban India's men's grooming vertical.
Creams absorb the bulk of installed capacity; serums are expanding most quickly.
Technology:
Active ingredient selection now pivots on regulatory authorization pathways rather than efficacy alone.
- Hydroquinone:Synthetic melanin synthesis inhibitor faces structural decline in regulated markets. FDA concentration limits and REACH authorization requirements force parallel inventory SKUs and inflate compliance overhead for manufacturers serving Western markets.
- Kojic Acid:Fermentation-derived tyrosinase inhibitor from Aspergillus oryzae cultures. Raw material capacity clusters in Chinese and Japanese suppliers, exposing formulation houses to input volatility during supply shocks.
- Arbutin:Hydroquinone glycoside from bearberry extract with reduced cytotoxicity profile. ECHA's updated endocrine-disrupting screening guidance has extended registration timelines by 8-14 months.
- Vitamin C:Ascorbic acid derivatives require 18-24 month accelerated aging validation cycles, delaying launches and compressing patent exclusivity windows. Liposome delivery systems improve dermal penetration of unstable actives.
- Alpha Arbutin:Synthetic arbutin analog with enhanced stability and lower melanocyte toxicity. European mass-market brands accelerate development programs to circumvent chemical authorization pathways entirely.
Vitamin C derivatives capture the steepest expansion trajectory; hydroquinone contracts in regulated jurisdictions.
Application:
Clinical indication severity determines channel access and pricing architecture across consumer and professional segments.
- Hyperpigmentation Treatment:Post-inflammatory and post-traumatic melanin deposition management. AI-driven skin analysis applications automate personalized regimen matching based on Fitzpatrick typing in Indian and Brazilian telemedicine platforms.
- Freckle Reduction:Ephelis control for cosmetic aesthetic improvement. Direct-to-consumer online retailers dominate distribution through algorithm-driven personalization.
- Melasma Control:Hormonally triggered dermal melanosis requiring physician supervision. L'Oréal S.A. leverages dermatological science heritage to anchor premium positioning in this category.
- Age Spot Removal:Solar lentigines treatment for mature skin demographics. Pharmacy chains deploy certified skin advisors to displace traditional beauty counter consultations.
- Sun Damage Repair:Photoaging reversal combining depigmentation with barrier repair. Encapsulation technology maturation enables higher-concentration launches through professional channels.
Melasma control commands premium pricing; hyperpigmentation treatment spans the broadest addressable base.
End User:
Channel fragmentation between institutional and retail access shapes formulation specifications and compliance requirements.
- Dermatology Clinics:Physician-staffed pigmentation centers in India and Japan create institutional demand for prescription-grade protocols. Post-procedure maintenance kits extend treatment revenue cycles.
- Beauty Salons:Japanese beauty salons distribute professional-grade portfolios with trained aesthetician consultation. Shiseido Co., Ltd. dominates this channel through capsule and gel formats.
- Pharmacies:India's CDSCO registration streamlining permits parallel filing for ayurvedic-derived actives, accelerating botanical formulation entry against synthetic alternatives.
- Online Retailers:Direct-to-consumer platforms compress the consultation-to-purchase funnel from weeks to minutes through integrated diagnostic-retail ecosystems.
- Specialty Stores:Curated retail environments with trained staff support premium positioning and ingredient education for complex regimen adherence.
Pharmacies absorb the bulk of volume throughput; online retailers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of skin lightening actives clusters in Japanese fermentation facilities and Chinese extraction plants, while consumption concentrates in India's urban pharmacy corridors and Japan's aesthetic clinic networks. This geographic split shapes regulatory compliance strategies and supply chain risk profiles across formulation houses.
India
Apollo Pharmacy and MedPlus chains deploy certified skin advisors across 340-plus locations in Mumbai, Delhi, and Bangalore, driving volume for kojic acid and arbutin-based formulations. CDSCO registration streamlining now permits parallel filing for ayurvedic-derived actives, accelerating botanical entry timelines against synthetic alternatives. Maharashtra's pharmaceutical manufacturing belt supplies encapsulated active ingredients to domestic formulators.
Japan
Tokyo and Osaka beauty salons distribute professional-grade capsule and gel portfolios through trained aesthetician consultation networks. METI oversees cosmetic safety standards that shape encapsulation technology investment for unstable vitamin C derivatives. Shiseido Co., Ltd. anchors the Kanto region's dominance in salon-channel professional products.
United States
FDA concentration limits on over-the-counter hydroquinone force reformulation toward botanical peptides and stabilized vitamin C derivatives. Direct-to-consumer online retailers compress the consultation-to-purchase funnel through AI-driven skin analysis integration. California-based formulation houses lead R&D migration away from legacy chemical pathways.
Germany
REACH authorization requirements and ECHA's 2024 endocrine-disrupting screening guidance extend registration timelines for arbutin derivatives by 8-14 months. EU Green Deal alignment creates first-mover advantages for brands with vertically integrated botanical supply chains. Bavarian cosmetic science programs concentrate specialized expertise in melanin biochemistry.
China
Kojic acid fermentation capacity clusters in Chinese suppliers, exposing formulation houses to input volatility during supply shocks. NMPA governs cosmetic safety claims and ingredient disclosure standards for multinational entrants. Yangtze River Delta manufacturing hubs supply raw materials to regional formulation houses.
Skin Lightening Products Market Key Industry Players
Capital-heavy producers with captive fermentation and extraction facilities compete with asset-light brands that outsource active ingredient synthesis to contract manufacturers. The market structures around three tiers: multinational conglomerates with dermatological science heritage, regional Ayurvedic and botanical specialists, and professional-grade salon-channel operators. Strategic moves concentrate on subscription-based replenishment program rollout and clinic-channel partnership expansion to lock in recurring revenue streams.
Within the multinational tier, L'Oréal S.A. and Unilever PLC exemplify the dermatological science positioning that anchors premium melasma control formulations. Shiseido Co., Ltd. occupies the professional-grade vector through Japanese salon-channel dominance. Himalaya Global Holdings Ltd. represents the Ayurvedic differentiation archetype competing through mass-market pharmacy penetration across South Asian markets.
| Leading Market Players |
|---|
| Unilever PLC |
| Beiersdorf AG |
| L'Oréal S.A. |
| Himalaya Global Holdings Ltd. |
| Avon Products, Inc. |
| Procter & Gamble |
| Shiseido Co., Ltd. |
| Kao Corporation |
| Estée Lauder Companies Inc. |
| Others |
Cost & Logistics Intelligence
Formulation chemists specializing in melanin biochemistry and encapsulation engineering concentrate in Japanese and Swiss cosmetic science programs, creating labor-cost differentials that widen pricing-tier spreads between premium professional-grade serums and mass-market pharmacy creams.
Pricing Analysis
Margin tightening in mass-market tiers reflects CDSCO registration streamlining that accelerates ayurvedic-derived active entry against synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates subscription-based serum regimens from pharmacy-chain creams and salon-distributed capsules. Price differentiation rests on certification grade and brand premium anchored in dermatological science heritage. Cost-down pressure on economy lotions accelerates because raw material concentration in Chinese kojic acid fermentation exposes formulators to input volatility.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Japanese suppliers of kojic acid fermentation capacity and Indian manufacturers of encapsulated active ingredients. Raw material dependencies include Aspergillus oryzae cultures for tyrosinase inhibitors, bearberry extract for arbutin derivatives, and stabilized ascorbic acid precursors. Supply chain risk centers on regulatory fragmentation forcing parallel inventory SKUs across FDA, REACH, and CDSCO jurisdictions. Distribution runs through pharmacy-led professional advice models in India's tier-one cities and direct-to-consumer online retailers with AI-driven diagnostic integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization requirements and ECHA's endocrine-disrupting screening guidance create a cost-of-compliance story where extended registration timelines for arbutin derivatives erect barrier-to-entry moats favoring manufacturers with vertically integrated botanical supply chains.
For Market Incumbents: Cement clinic-channel partnerships through post-procedure maintenance kit protocols that extend treatment revenue cycles. Lock in recurring revenue streams via subscription replenishment programs for serum regimens, defending against asset-light direct-to-consumer entrants with algorithm-driven personalization capabilities. Prioritize R&D investment in liposome and niosome delivery systems to maintain encapsulation technology leadership. For New Entrants and Emerging Players: Enter via men's grooming verticals targeting post-inflammatory hyperpigmentation from shaving trauma, where urban India's pharmacy chains pilot dedicated brightening aisles with minimal incumbent saturation. Exploit CDSCO parallel filing pathways for ayurvedic-derived actives to accelerate market entry timelines against synthetic alternatives. Deploy telemedicine-integrated diagnostic tools to compress consultation-to-purchase funnels. For Investors and Strategic Acquirers: Re-rating potential sits with regional Ayurvedic specialists given CDSCO registration streamlining and EU Green Deal alignment incentives for bio-based active sourcing. Long-term viability favors manufacturers with captive fermentation and extraction facilities over outsourced synthesis models. Watch ECHA substance volume threshold adjustments as inflection indicators for botanical peptide development program returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Supply | EU Green Deal alignment creates first-mover advantages for brands with in-house extraction of ayurvedic actives. |
| Subscription Replenishment Program Launch | Auto-delivery serum regimens lock in 12-18 month customer lifecycles and reduce acquisition cost burdens. |
| Clinic-Channel Partnership Expansion | Physician-staffed pigmentation centers in India and Japan create institutional demand for prescription-grade protocols. |
| Encapsulation Technology Investment | Liposome delivery systems improve dermal penetration of unstable vitamin C derivatives for higher-concentration launches. |
| Men's Grooming Vertical Entry | Post-inflammatory hyperpigmentation from shaving trauma represents underserved application in urban Indian pharmacy chains. |
Research Approach
Multi-period observation of CDSCO registration timelines, REACH authorization pathways, and encapsulation technology maturation anchored the trend analysis, supplemented by interviews with formulation chemists, dermatology clinic directors, pharmacy chain category managers, and cosmetic regulatory affairs leads. Secondary validation drew from ECHA guidance documents, FDA concentration limit rulings, BIS cosmetic safety standards, and customs records of active ingredient trade flows. Bottom-up and top-down triangulation cross-checked volume estimates against installed fermentation capacity and pharmacy distribution throughput.
Input-output matrices modeled demand across product type, active technology, clinical application, and channel access dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis incorporating regulatory migration timelines and professional channel expansion rates. Industry-specific forecast inputs included CDSCO ayurvedic filing velocity and ECHA endocrine-disrupting screening protocol adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance bans or kojic acid supply disruptions. Forecasts reflect assumptions about regulatory divergence persistence and encapsulation technology diffusion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market