
 UV Nail Gel Polish Market | 2026-2036
UV Nail Gel Polish Market Size, Share, and Industry Trends Forecast 2026-2036
UV Nail Gel Polish Market Insights
Hema-free photoinitiator chemistry is expanding as salon chains and distributors phase out high-sensitization raw materials. Bio Seaweed Gel leverages plant-derived resin systems to differentiate its positioning among clean-beauty retailers. OPI sustains broad salon distribution through professional education programs and technician certification networks. Gelish anchors the premium home-use segment with LED-curable systems that reduce cure times below traditional UV lamp requirements.
UV nail gel polish comprises oligomer-resin formulations photopolymerized by ultraviolet or LED light exposure, typically containing acrylate monomers, photoinitiators such as TPO or HMPP, and pigment dispersions that cure to a hard, glossy film within 30–60 seconds under 365–405 nm wavelength lamps. Color Gel occupies the largest revenue pool due to repeat purchase frequency and seasonal shade rotation, while Builder Gel represents the fastest-expanding category as nail extension services grow in professional channels. Distribution through Online Stores is capturing incremental share as direct-to-consumer brands bypass traditional beauty supply intermediaries.
REACH restrictions on methacrylate monomer concentrations and emerging FDA scrutiny of photoinitiator safety profiles are elevating compliance costs for reformulation cycles across European and North American suppliers. China's GB standards for cosmetic safety and SAMR labeling requirements shape export readiness for Foshan-based manufacturers serving cross-border e-commerce channels. Stakeholders must monitor regulatory divergence between photoinitiator approval lists in Europe, the United States, and Asia, as formulation harmonization failures could fragment supply chain efficiency and force regional SKU proliferation.
Market Dynamics
Photoinitiator chemistry substitution is restructuring formulation priorities across professional and retail channels, as regulatory pressure on methacrylate sensitization forces suppliers to rebuild resin systems around Hema-free alternatives.
Growth Catalysts
- REACH methacrylate restrictions:European ECHA classifications on high-sensitization monomers are accelerating reformulation investments, opening market share for compliant resin suppliers.
- LED lamp penetration:Nail salons are replacing legacy UV curing equipment with 365–405 nm LED systems, reducing client exposure times and expanding service throughput capacity.
- Foshan manufacturing clusters:Concentrated production in Guangdong Province supplies cost-competitive base resins to cross-border e-commerce platforms serving North American and European direct-to-consumer brands.
Market Restraints
- Photoinitiator input volatility:TPO and HMPP supply concentrates among Chinese specialty chemical producers, exposing formulators to freight cost swings and customs processing delays.
- Builder gel technical ceiling:Current oligomer viscosity limits constrain extension length durability beyond 21-day wear cycles, capping service pricing power in premium salon tiers.
- FDA cosmetic ingredient review friction:Evolving scrutiny of acrylate safety profiles is extending new product notification timelines, delaying North American launch windows.
Strategic Opportunities
- India salon channel underpenetration:Organized nail service chains remain nascent in Mumbai and Bangalore, presenting first-mover positioning for professional education-backed distribution.
- Plant-derived resin convergence:Bio-based oligomer chemistry combined with low-energy LED curing is creating certification pathways for clean-beauty retail placement.
- SAMR cross-border labeling alignment:China's streamlined cosmetic import documentation is reducing compliance friction for Foshan exporters targeting domestic e-commerce live-streaming channels.
Industry Challenges
- Nail technician certification gaps:Inconsistent state-level licensing requirements across the United States create liability exposure for salon chains standardizing gel application protocols.
- Reformulation capex intensity:Hema-free photoinitiator validation requires parallel stability testing and lamp compatibility verification, stretching R&D budgets for mid-tier suppliers.
- ISO 22716 GMP integration:Cosmetic good manufacturing practice certification demands cleanroom retrofitting that smaller Guangdong producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Nail Gel Polish Market |
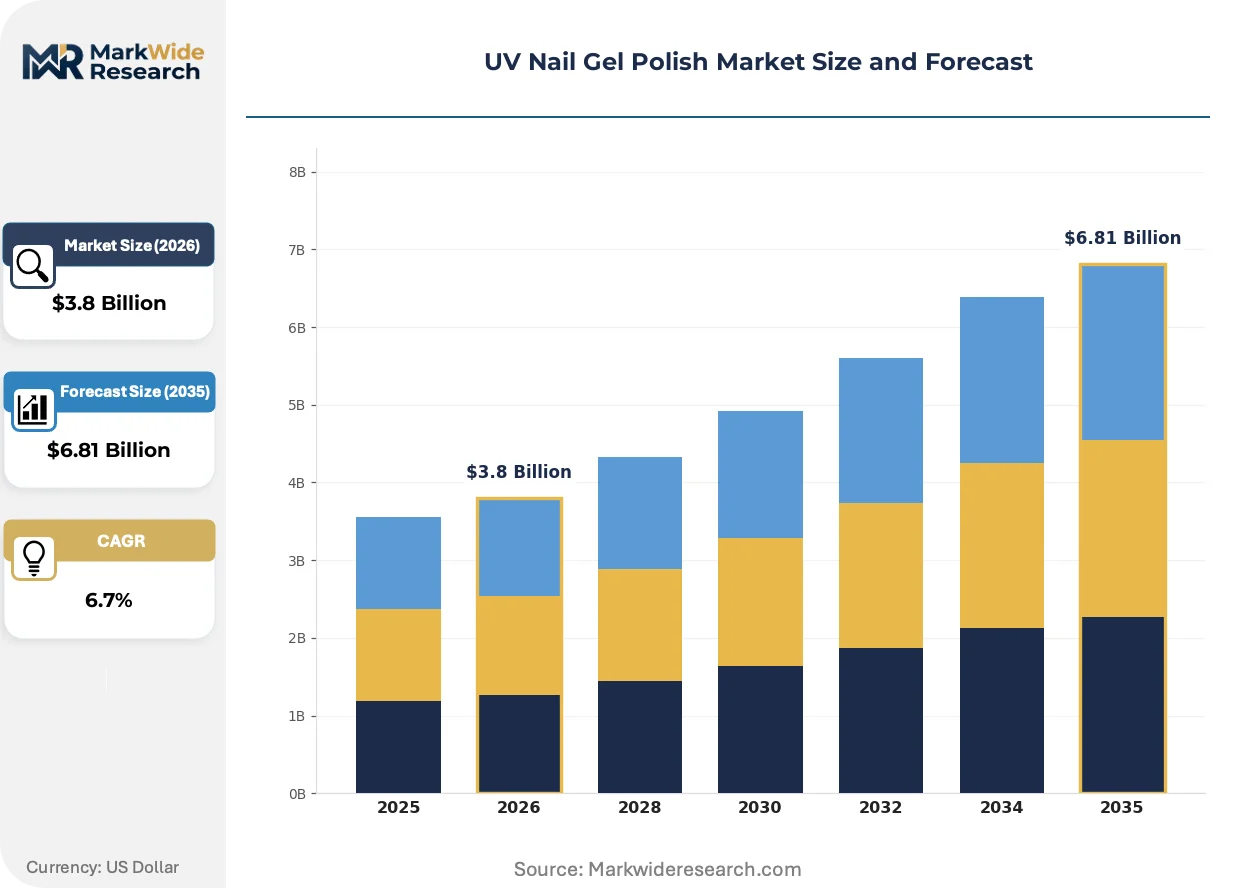
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Builder Gel, Top Coat, Base Coat, Color Gel End User: Salons, Home Users, Professionals, Nail Technicians Application: Manicure, Pedicure, Nail Art, Acrylic Nails Distribution Channel: Online Stores, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Hanyinails (Foshan Hanyi Cosmetics), S&L Beauty, The GelBottle Inc, Bio Seaweed Gel, DND (Daisy Nail Design), CND (Creative Nail Design), CNC International, Gelish, OPI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Nail Gel Polish Market Trends and Innovations
Formulation science and curing hardware are converging to compress service times while regulatory chemistry restrictions are fragmenting legacy supply relationships. These forces are reshaping competitive positioning across professional and retail channels.
Hybrid photoinitiator blends combining TPO-L and BAPO derivatives are absorbing market share from single-component systems by enabling broader lamp compatibility and faster through-cure at reduced energy density. Professional salon chains in Germany and South Korea are adopting these formulations to standardize results across mixed LED-UV equipment fleets. The technology is absorbing technician training costs previously required for lamp-specific application techniques.
ECHA REACH restrictions on methacrylate monomer concentrations are forcing European formulators to validate alternative oligomer backbones, compressing product development cycles and elevating raw material qualification expenses. Suppliers serving the professional channel are responding by regionalizing formulation SKUs rather than pursuing universal compliance recipes. Color gel lines face the steepest reformulation burden due to pigment-photoinitiator interaction complexity.
Direct-to-consumer brands are bypassing beauty supply intermediaries through proprietary e-commerce storefronts and social commerce live-streaming, disintermediating traditional distributor relationships that previously controlled salon product access. This channel shift concentrates marketing spend on platform algorithm optimization rather than field sales force maintenance. The pattern is most visible in China, where domestic platforms enable same-city fulfillment from Foshan production zones to individual nail artists.
UV Nail Gel Polish Market Segmentation
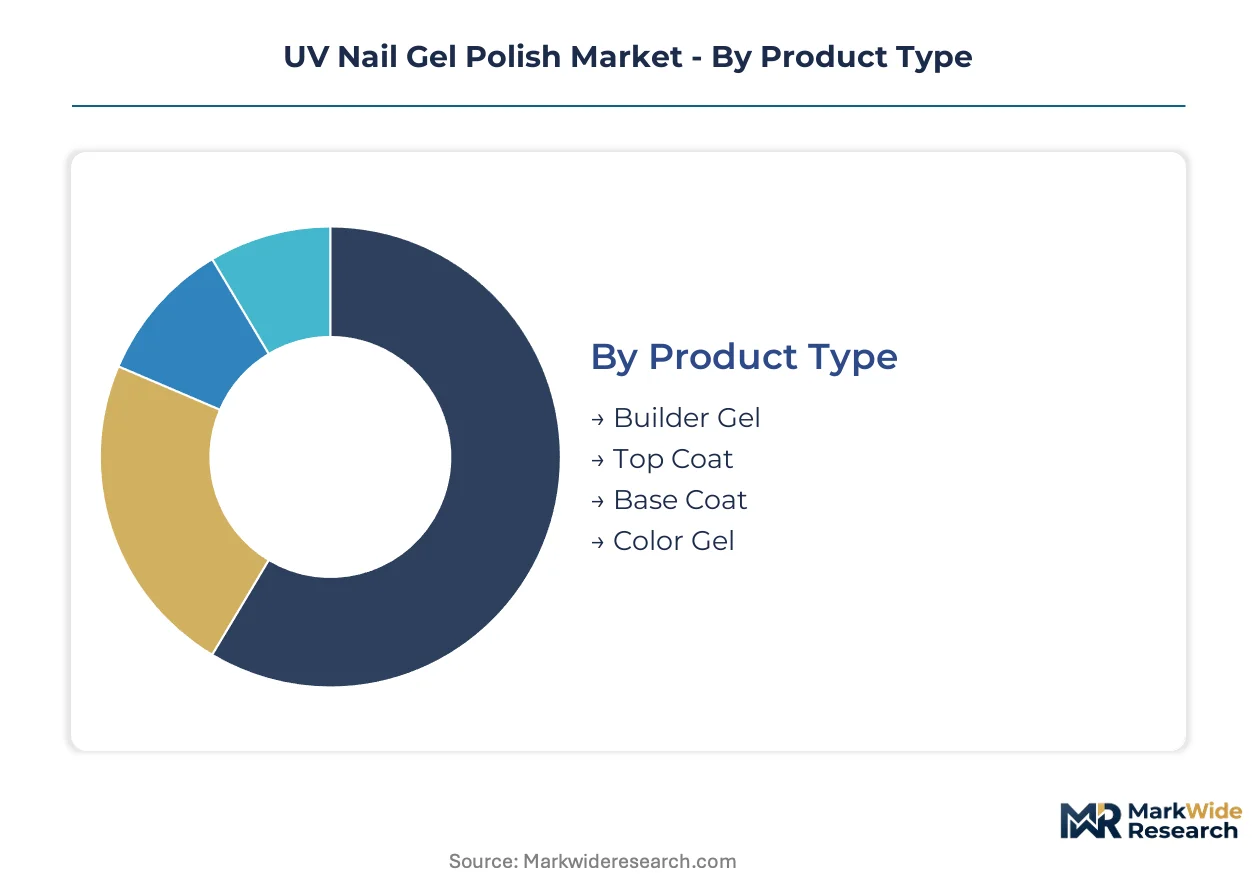
Segmentation in UV nail gel polish reveals how formulation chemistry, curing hardware requirements, and channel access create distinct competitive battlegrounds. Each dimension carries different margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Standalone formulations dominate professional service menus while embedded-system products integrate into multi-step protocols with specific lamp requirements.
- Color Gel:Pigment-dispersed oligomer systems cure to glossy, opaque films in 30–60 seconds under 365–405 nm lamps. Demand concentrates in seasonal shade rotation cycles at North American salon chains, where repeat purchase frequency sustains inventory turns. ECHA REACH methacrylate restrictions are forcing reformulation of pigment-photoinitiator interactions.
- Builder Gel:High-viscosity oligomer resins enable nail extension sculpting with structural durability targets. German and South Korean professional chains are absorbing these formulations fastest as LED lamp standardization reduces cure variability. Current viscosity ceilings constrain extension length beyond 21-day wear cycles.
- Top Coat:Low-viscosity sealant formulations provide scratch-resistant gloss layers with enhanced photoinitiator loadings for rapid surface cure.
- Base Coat:Adhesion-promoting resin systems incorporate acidic functional monomers for keratin substrate bonding prior to color application.
Volume placements concentrate in Color Gel; the faster expansion belongs to Builder Gel.
End User:
Cost-tier stratification separates premium professional certification requirements from mass-market accessibility.
- Salons:Licensed service establishments purchasing bulk formulations through beauty supply distributors with technician training attachments. Mumbai and Bangalore organized chains remain underpenetrated, presenting first-mover positioning for education-backed distribution.
- Nail Technicians:Independent contractors sourcing professional-grade systems through direct-to-consumer platforms. Foshan manufacturing clusters supply cost-competitive base resins to cross-border e-commerce serving this segment in North America and Europe.
- Home Users:Retail-format consumers acquiring LED-curable kits with simplified application protocols.
- Professionals:Encompassing spa operators and hospitality service providers with standardized procurement contracts.
Procurement scale favors Salons; the steepest channel shift is occurring among Nail Technicians.
Application:
Service-duration economics vary sharply between quick-turn maintenance procedures and labor-intensive artistic applications.
- Manicure:Core hand-nail services representing the highest procedure frequency in professional channel throughput. LED lamp penetration is compressing service times and expanding salon capacity utilization across German and South Korean chains.
- Nail Art:Decorative techniques requiring layered gel applications with precision curing between steps. China's domestic nail art culture drives concentrated demand through Foshan and Guangzhou manufacturing clusters serving both domestic and export channels.
- Pedicure:Foot-nail services with extended cure time tolerances due to lower throughput pressure.
- Acrylic Nails:Hybrid extension systems combining polymer powder with gel overlay techniques.
Manicure claims the highest procedure volume; Nail Art is gaining share fastest through social commerce amplification.
Distribution Channel:
Geographic concentration of manufacturing clusters dictates fulfillment efficiency across channel archetypes.
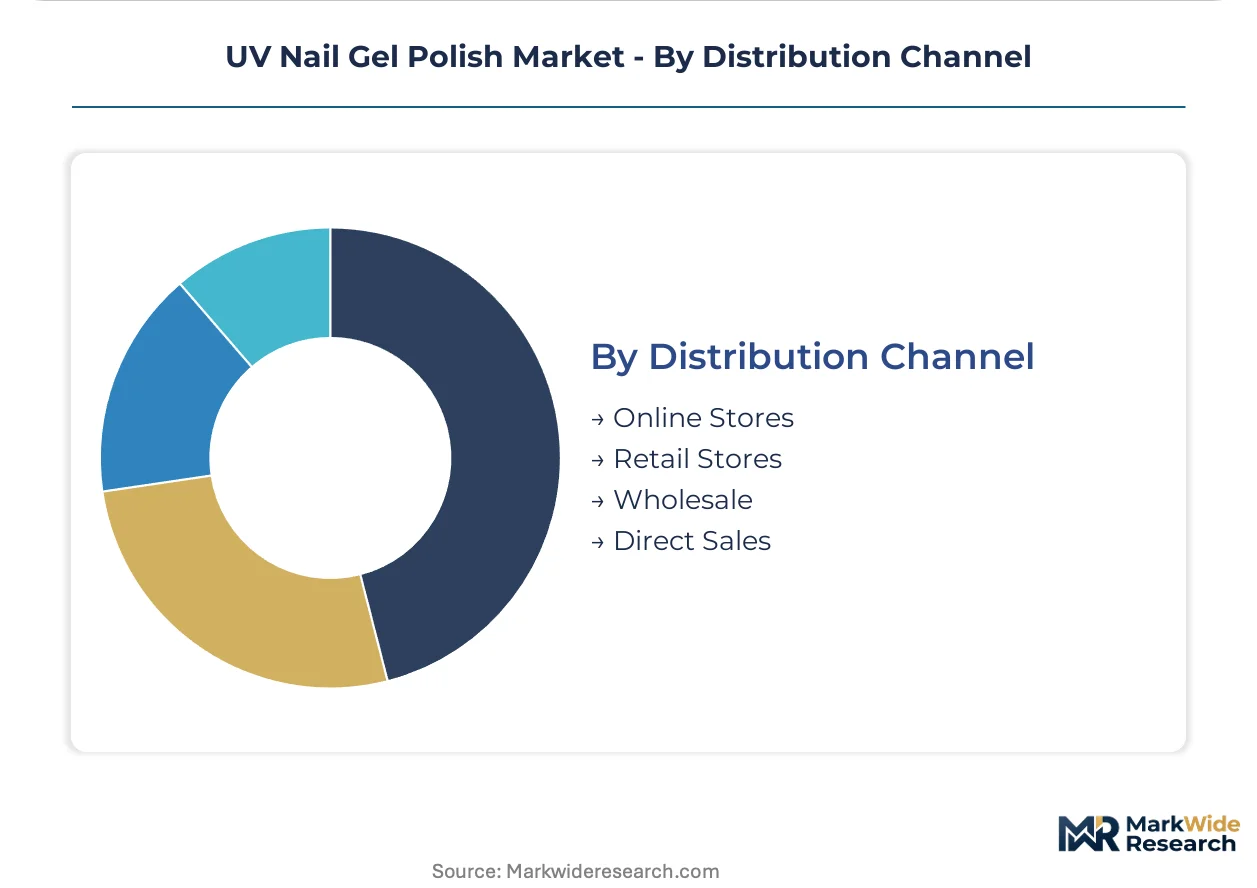
- Online Stores:Direct-to-consumer platforms bypassing traditional beauty supply intermediaries with algorithm-optimized customer acquisition. China's SAMR streamlined import documentation is reducing compliance friction for Foshan exporters targeting domestic e-commerce live-streaming.
- Wholesale:Bulk supply relationships serving salon chains with volume pricing and field education support. Traditional distributor relationships here face disintermediation pressure from proprietary brand storefronts.
- Retail Stores:Mass-market shelf placement requiring consumer-friendly kit packaging and simplified LED lamp bundling.
- Direct Sales:Technician-to-technician network marketing with certification-linked product access.
Wholesale retains the largest transaction value; Online Stores are climbing the fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing capacity for UV nail gel polish base resins, while professional service demand clusters in Germany, South Korea, and the United States. Regulatory divergence between ECHA REACH methacrylate restrictions, FDA cosmetic ingredient reviews, and China's SAMR labeling requirements is fragmenting formulation standards across export destinations.
China
Foshan and Guangzhou manufacturing clusters supply cost-competitive oligomer resins to cross-border e-commerce platforms serving North American and European direct-to-consumer brands. SAMR streamlined cosmetic import documentation is reducing compliance friction for exporters targeting domestic live-streaming commerce channels. Guangdong Province producers face ISO 22716 GMP certification costs that smaller fabricators struggle to finance.
Germany
Professional salon chains in Berlin and Munich are adopting hybrid photoinitiator blends to standardize results across mixed LED-UV equipment fleets. ECHA REACH restrictions on methacrylate monomer concentrations are forcing reformulation of color gel pigment-photoinitiator interactions. Bavaria-based distributors are regionalizing SKU portfolios rather than pursuing universal compliance recipes.
South Korea
Seoul Capital Area nail service chains are absorbing builder gel formulations fastest as LED lamp standardization reduces cure variability. MFDS cosmetic safety standards shape import requirements for professional-grade systems. Busan-Ulsan logistics hubs facilitate distribution to Japanese and Southeast Asian salon channels.
United States
Organized salon chains in California and New York Metro are expanding gel service menus while navigating inconsistent state-level technician licensing requirements. FDA evolving scrutiny of acrylate safety profiles is extending new product notification timelines. Pacific Northwest direct-to-consumer brands are bypassing traditional beauty supply intermediaries through proprietary e-commerce storefronts.
India
Organized nail service chains remain nascent in Mumbai and Bangalore, presenting first-mover positioning for professional education-backed distribution. BIS cosmetic standards are emerging as reference points for import quality assurance. Maharashtra and Karnataka urban centers concentrate early adopter demand among independent nail technicians sourcing through cross-border platforms.
UV Nail Gel Polish Market Competitive Landscape
Reformulation investment dominates the current landscape as suppliers rebuild resin systems around Hema-free photoinitiator alternatives. The vendor base spans multinational salon distributors, specialized clean-beauty formulators, and vertically integrated Chinese manufacturers. Three archetypes define positioning: professional certification-backed brands, plant-derived resin specialists, and scale-driven base resin suppliers. Competitive moves concentrate on geographic expansion into underpenetrated salon channels and technology licensing for LED-curable system compatibility.
Among North American salon distributors, OPI and CND occupy positions anchored by professional education programs and technician certification networks. Bio Seaweed Gel exemplifies the clean-beauty specialist archetype through plant-derived resin differentiation. Chinese manufacturers including Hanyinails sit within the scale-driven tier supplying cost-competitive base formulations to cross-border e-commerce channels.
| Leading Market Players |
|---|
| Hanyinails (Foshan Hanyi Cosmetics) |
| S&L Beauty |
| The GelBottle Inc |
| Bio Seaweed Gel |
| DND (Daisy Nail Design) |
| CND (Creative Nail Design) |
| CNC International |
| Gelish |
| OPI |
| Others |
Pricing and Supply Chain Analysis
Organized salon chains in Germany and South Korea concentrate procurement volume, locking in contract-based pricing structures that reward certification-backed suppliers with multi-year offtake agreements while squeezing spot-market formulators.
Pricing Analysis
Volume placements through wholesale distributors command standard-tier margins, while premium-tier pricing attaches to LED-curable systems with technician certification bundling. Price differentiation hinges on ECHA REACH compliance grade and lamp compatibility breadth. Pricing pressure stems from Foshan manufacturing clusters flooding cross-border e-commerce with unbranded base resins. Home users exhibit highest price sensitivity; professional salon chains prioritize formulation stability over unit cost.
Supply Chain Analysis
Regional distribution centers in Busan-Ulsan and Rotterdam handle hub-and-spoke fulfillment to salon chains across Asia-Pacific and Europe. Oligomer resin production concentrates in China, Germany, and South Korea. Formulation chemistry draws from TPO photoinitiators, acrylate monomers, and pigment dispersions. Single-source vulnerability runs through Chinese specialty chemical producers for photoinitiator inputs. Distribution runs through beauty supply intermediaries facing disintermediation from direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED lamp standardization is displacing legacy UV curing hardware, compressing service times while forcing parallel reformulation investments across photoinitiator chemistry.
For Market Incumbents: Anchor market position through backward integration into Hema-free photoinitiator supply and captive technician certification networks. Defend against cross-border e-commerce disintermediation by locking salon chains into exclusive LED system bundling. Prioritize ISO 22716 GMP certification investment to filter mid-tier competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer storefronts targeting independent nail technicians in Mumbai and Bangalore with cost-competitive base gel kits. Exploit underpenetrated organized salon channels in India through education-backed distribution partnerships. Position around plant-derived resin differentiation for clean-beauty retail placement. For Investors and Strategic Acquirers: The window for entry favors vertically integrated formulators with captive LED hardware compatibility testing. Long-term viability rests on regulatory chemistry adaptation capacity rather than brand equity alone. Watch ECHA REACH methacrylate restriction expansion as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hema-Free Formulation Transition | ECHA REACH compliance opens market share for validated resin suppliers in Europe. |
| LED Lamp Hardware Bundling | Gelish and OPI use certification networks to lock salon chains into proprietary curing systems. |
| Cross-Border E-Commerce Launch | Foshan manufacturers bypass beauty supply intermediaries through platform algorithm optimization. |
| Plant-Derived Resin Certification | Bio Seaweed Gel leverages clean-beauty credentials for premium retail channel access. |
| Technician Education Network Expansion | CND and OPI defend wholesale relationships through field training and state licensing alignment. |
Research Methodology
Document review covered customs trade records, ECHA REACH substance registrations, and FDA cosmetic ingredient filings, complemented by interviews with nail salon chain procurement directors, Foshan manufacturing cluster technical managers, beauty supply distributor category buyers, and LED lamp equipment engineers. Secondary validation drew from SAMR cosmetic import documentation, MFDS safety standards, and professional nail technician certification body curricula. Bottom-up volume estimates triangulated against top-down market sizing.
Segmentation-level outputs across product type, end user, application, and distribution channel fed into a unified analytical framework over the projection horizon. CAGRs derived from regression against lamp penetration rates and reformulation investment cycles. Industry-specific inputs included photoinitiator chemistry substitution timelines and LED curing hardware replacement frequencies.
Regulatory divergence between ECHA, FDA, and SAMR, photoinitiator supply concentration risk, and salon channel disintermediation velocity are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions on compliance cost pass-through and hardware standardization adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market