
 Chemicals for Cosmetics and Toiletries Market | 2026-2036
Chemicals for Cosmetics and Toiletries Market Size, Share, and Industry Trends Forecast 2026-2036
Chemicals for Cosmetics and Toiletries Market Outlook
Specialty chemical distribution through integrated direct-to-brand channels is reshaping how raw materials reach cosmetics manufacturers. BASF SE leverages its global technical service network to sustain long-term supply agreements with multinational formulators. Croda International Plc differentiates through biotechnology-derived actives that command premium positioning in skin care. Evonik Industries AG anchors its presence through silicone alternatives that compete on performance in hair conditioning applications.
Chemicals for cosmetics and toiletries comprise functional ingredients including emollients, surfactants, preservatives, and colorants formulated at specified active concentrations, pH ranges, and microbiological purity grades for topical consumer products. These substances deliver cleansing, conditioning, protection, or aesthetic modification in finished personal care goods. Emollients capture the largest margin pool as brands prioritize sensorial texture and barrier repair claims. Surfactants face structural pressure from sulfate-free and mild cleansing trends that favor amino-acid-based and glucoside chemistries. Preservatives remain a contested segment where clean-label positioning conflicts with broad-spectrum antimicrobial efficacy requirements.
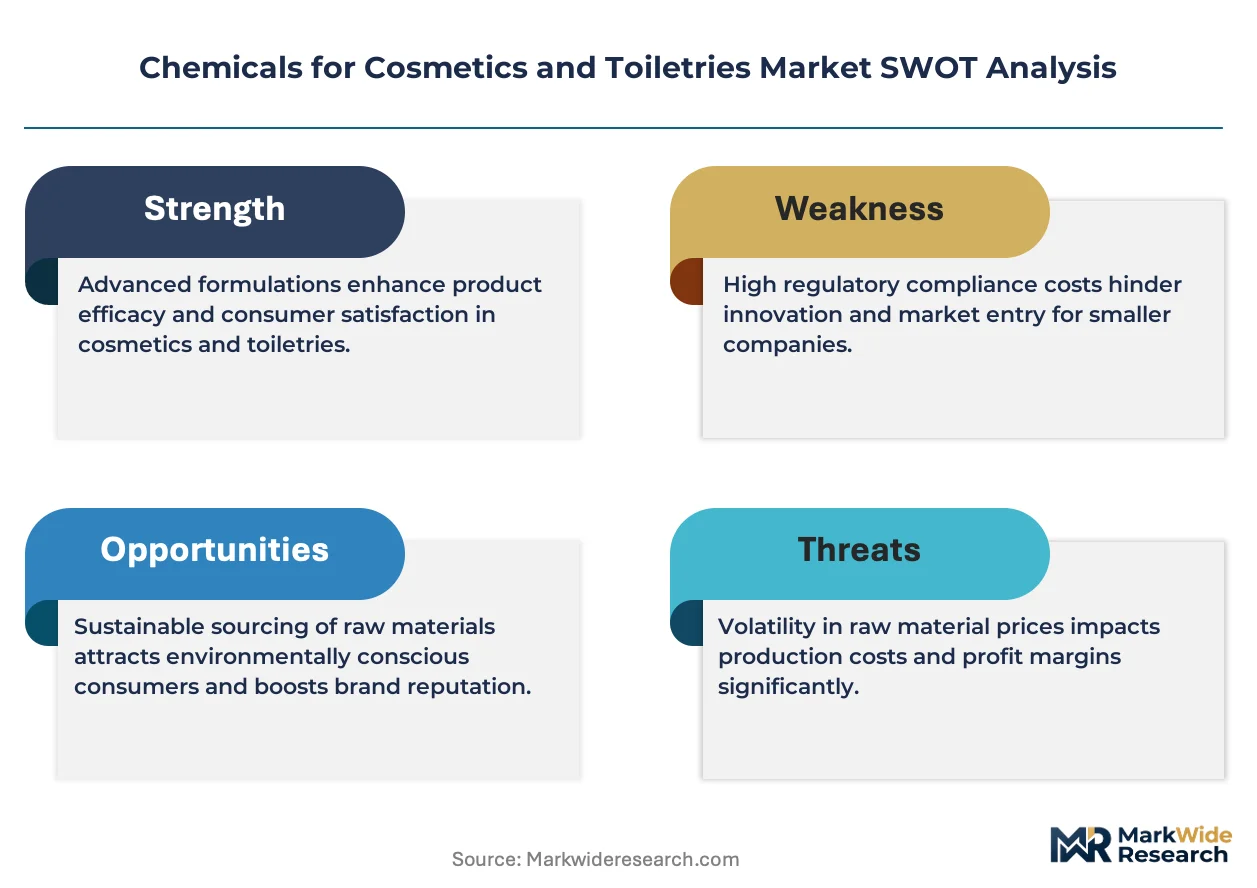
Regulators including ECHA under REACH, the FDA through cosmetic ingredient safety guidance, and China's NMPA with updated cosmetics supervision regulations each tighten disclosure and safety assessment protocols. Formulators must navigate divergent substance restriction lists that complicate global SKU rationalization. Stakeholders should monitor how biotech-derived ingredient classifications evolve under existing chemical regulatory frameworks versus emerging natural certification standards.
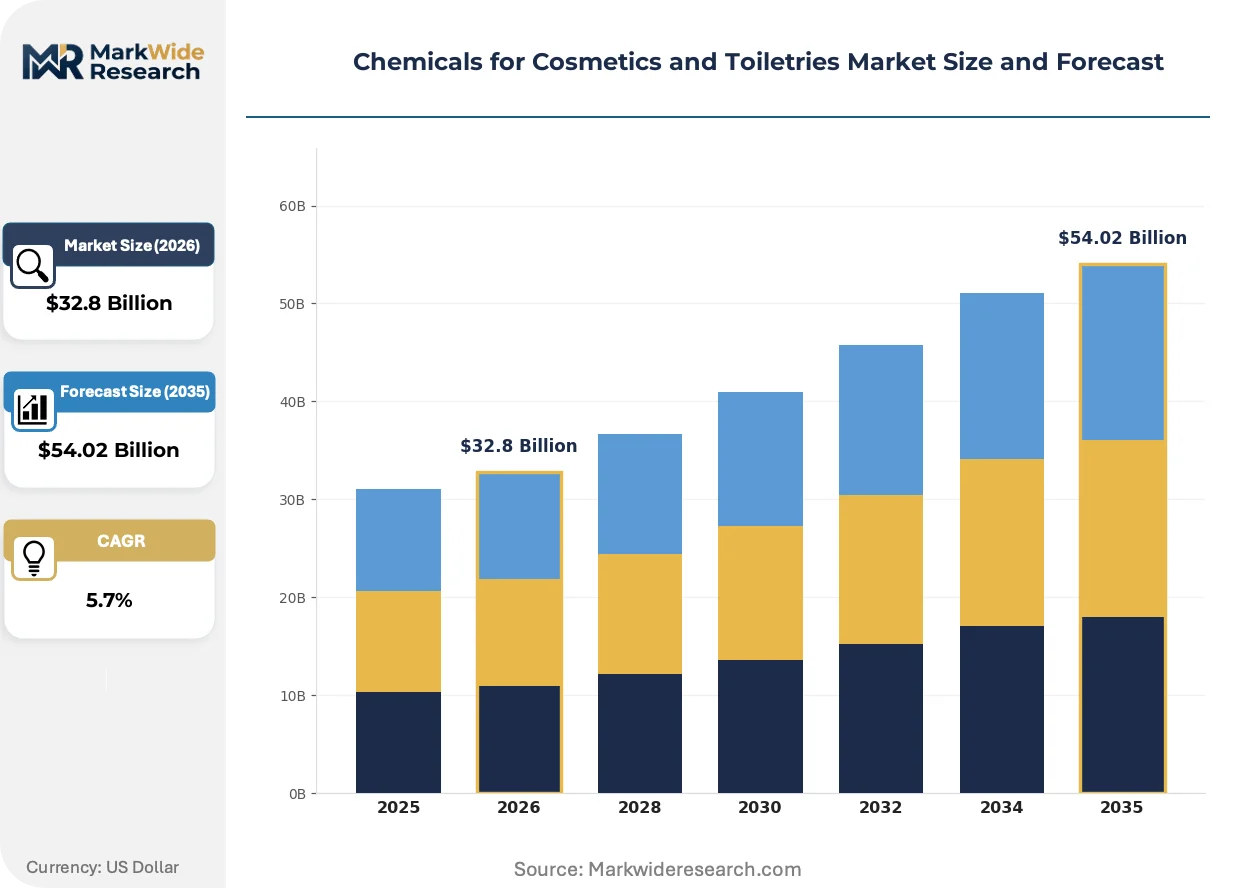
Market Dynamics
Specialty surfactant demand is bifurcating between premium K-beauty formulations and mass-market sulfate-free replacements, forcing raw material suppliers to maintain dual R&D tracks with incompatible scale economics.
Growth Catalysts
- EU Green Deal bio-based mandates:Formulators in Germany and France accelerate emollient substitution toward plant-derived esters and fermented oils to meet 2030 carbon intensity targets.
- South Korean skin care premiumization:Domestic beauty conglomerates expand R&D budgets for ceramide complexes and peptide actives, pulling specialty chemical imports from Japan and Switzerland.
- China's NMPA cosmetics supervision regulations:Streamlined safety assessment protocols for domestically sourced ingredients reduce time-to-market for local formulators versus imported alternatives.
Market Restraints
- Palm kernel oil price volatility:Surfactant feedstock costs swing with Indonesian and Malaysian export policy shifts, compressing margin visibility for mid-tier producers.
- REACH substance restriction complexity:ECHA's evolving SVHC candidate list forces European formulators to maintain parallel formulation databases, raising compliance overhead.
- Silicone substitution technical ceiling:Bio-based alternatives in hair conditioning applications fail to match thermal stability and spreadability benchmarks set by dimethicone copolyols.
Strategic Opportunities
- India's underpenetrated color cosmetics segment:Domestic brands scaling manufacturing capacity create first-mover demand for pigment dispersions and film-forming polymers previously imported.
- Biotechnology-fermentation convergence:Microbial production of squalane and hyaluronic acid enables supply security independent of shark liver or rooster comb extraction constraints.
- Direct-to-brand distribution platforms:Specialty chemical distributors bypassing traditional regional agents capture margin from multinationals consolidating supplier bases in Southeast Asia.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in natural preservation systems and microbiome-compatible actives concentrates at a handful of European and Japanese technical institutes.
- Clean-label certification timeline compression:Brands demand COSMOS and ECOCERT documentation within 12-month product development cycles versus historical 24-36 month windows.
- Legacy ERP integration with batch traceability:Small and mid-sized manufacturers struggle to retrofit manufacturing execution systems for blockchain-enabled ingredient provenance tracking demanded by retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemicals for Cosmetics and Toiletries Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Surfactants, Preservatives, Colorants Application: Skin Care, Hair Care, Oral Care, Make-Up Ingredient Source: Natural, Synthetic, Organic, Inorganic Formulation Type: Liquid, Cream, Powder, Gel |
| Companies Covered | BASF SE, Dow, Evonik Industries AG, Croda International Plc, Ashland Inc., Givaudan, Clariant, Solvay, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemicals for Cosmetics and Toiletries Market Strategic Shifts
Biotechnology-derived actives and fermentation platforms are compressing traditional extraction supply chains while regulatory disclosure requirements reshape how formulators validate safety claims.
Bio-fermented squalane and hyaluronic acid production is collapsing the cost structure of marine and animal-derived equivalents. Korean and Chinese skin care brands have adopted microbial routes at commercial scale since 2022. The technology is collapsing premium pricing tiers that previously separated pharmaceutical-grade from cosmetic-grade material specifications.
REACH Annex XIV authorization requirements and the EU Green Deal's chemical sustainability targets are tightening disclosure obligations for preservative systems and fragrance allergens. Formulators must now submit full substance dossiers for mixtures previously treated as confidential compositions. European mid-sized brands are responding by consolidating supplier relationships with integrated chemical companies possessing in-house regulatory affairs capabilities.
Ingredient provenance verification has become a non-negotiable procurement criterion for North American clean beauty retailers. Third-party blockchain platforms are displacing paper-based chain-of-custody documentation. This shift is most visible in California and New York, where Sephora and Ulta Beauty have mandated batch-level traceability for all naturals-derived inputs by 2025.
Chemicals for Cosmetics and Toiletries Market Segmentation
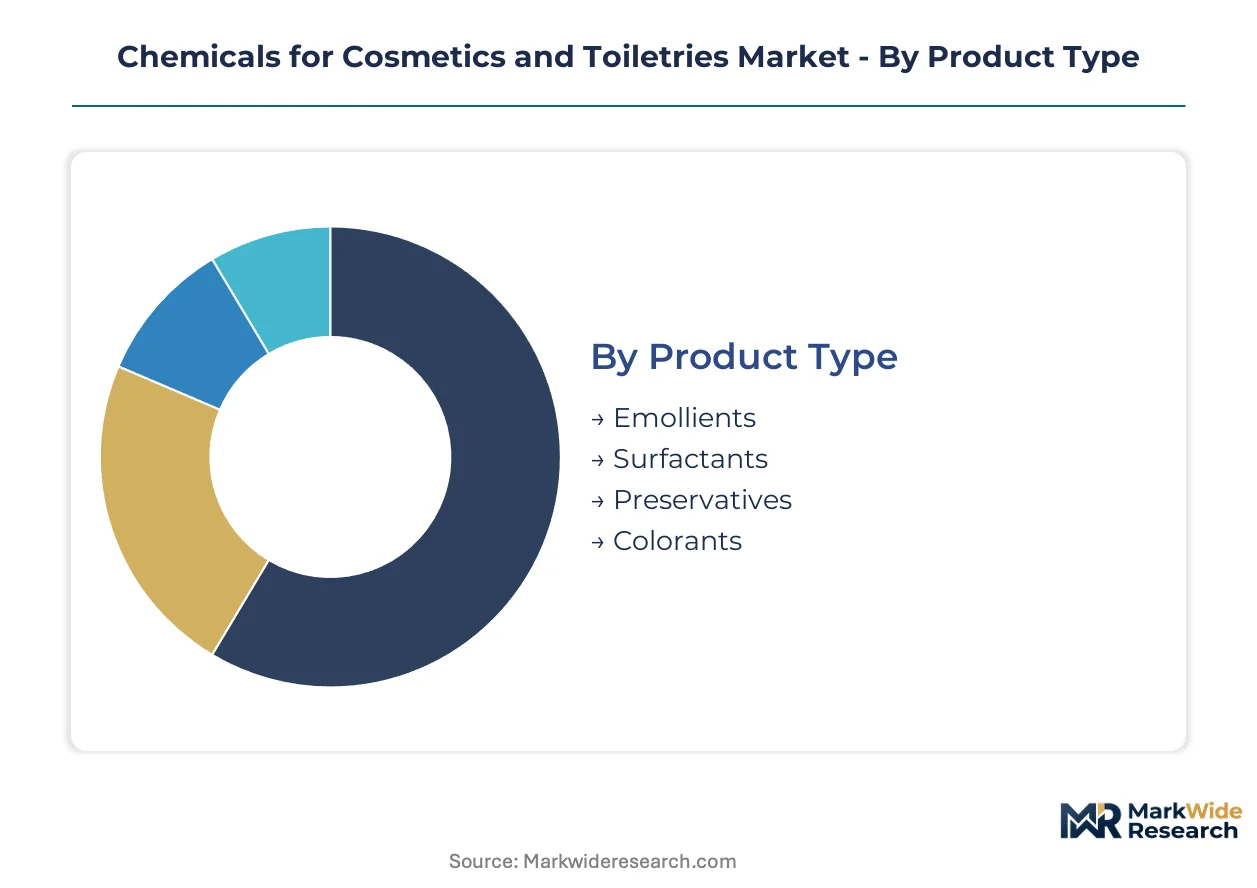
Chemicals for cosmetics and toiletries segment across four intersecting dimensions that determine formulation architecture, regulatory pathway, and margin structure. Each category carries distinct procurement patterns and technical service requirements from specialty chemical suppliers.
Product Type:
Mature emollient chemistries coexist with emerging surfactant alternatives as brands navigate clean-label positioning against performance benchmarks.
- Emollients:Lipid-based esters, fatty alcohols, and hydrocarbon oils soften skin and enhance barrier function at specified spreadability indices. Korean and Japanese skin care brands drive demand for fermented squalane and ceramide complexes that command technical service support from suppliers.
- Surfactants:Surface-active agents reduce interfacial tension for cleansing, foaming, and emulsification applications. Amino-acid-based and alkyl polyglucoside chemistries displace sulfates in European and North American sulfate-free formulations, though scale economics lag petroleum-derived alternatives.
- Preservatives:Antimicrobial systems including parabens, phenoxyethanol, and organic acids prevent microbial contamination in aqueous formulations. ECHA's evolving SVHC candidate list and clean-label marketing pressures compress the viable preservative toolkit for global brands.
- Colorants:Pigments and dyes provide aesthetic modification in decorative cosmetics at specified purity and heavy metal limits. REACH Annex XVII restrictions on chromium and nickel compounds force reformulation cycles for eye and lip products sold in Europe.
Emollients handle the majority of throughput; surfactants are climbing the fastest on share as sulfate-free conversion accelerates across mass-market hair care.
Application:
Volume concentration varies sharply across personal care categories, with skin care commanding premium ingredient specifications and oral care enforcing the tightest pharmaceutical-grade compliance.
- Skin Care:Moisturizers, serums, and treatment products incorporate actives at concentrations requiring stability testing and microbiological challenge studies. China's domestic beauty brands scale R&D budgets for local ceramide and peptide sourcing, reducing import dependency.
- Hair Care:Shampoos, conditioners, and styling products balance cleansing efficacy with conditioning performance. Silicone alternatives from Evonik and Dow compete on thermal stability benchmarks set by dimethicone copolyols in professional salon channels.
- Oral Care:Toothpastes and mouthwashes require pharmaceutical-grade excipients with documented safety dossiers. FDA and NMPA both mandate separate drug-versus-cosmetic classification reviews for whitening actives and therapeutic claims.
- Make-Up:Color cosmetics demand pigment dispersions, film-forming polymers, and volatile silicones with defined particle size distributions. India's underpenetrated color cosmetics segment creates first-mover demand for dispersion technologies previously imported from Europe and Japan.
Skin care captures the steepest margin expansion; make-up is expanding most quickly as India's manufacturing base scales.
Ingredient Source:
Certification requirements and supply security concerns are compressing the traditional natural-synthetic dichotomy into a more complex sourcing matrix.
- Natural:Plant-derived extracts, oils, and butters sourced with documented chain-of-custody. COSMOS and ECOCERT certification timelines have compressed from historical 24-36 month windows to 12-month cycles demanded by clean beauty retailers.
- Synthetic:Petrochemical-derived ingredients including silicones, synthetic esters, and petroleum jelly offer batch-to-batch consistency and scale economics. EU Green Deal bio-based mandates are accelerating substitution pressure in Germany and France.
- Organic:Certified organic ingredients meeting USDA NOP or EU 2018/848 standards with prohibited substance lists and conversion period requirements. Supply concentration in specific agricultural regions creates weather and geopolitical exposure.
- Inorganic:Mineral-based ingredients including titanium dioxide, zinc oxide, and silicates used as pigments, UV filters, and rheology modifiers. REACH authorization requirements for nano-form titanium dioxide have forced particle size disclosure and safety dossier updates.
Synthetic materials handle the majority of throughput; natural ingredients are gaining share fastest as blockchain-enabled provenance tracking becomes mandatory for North American clean beauty retailers.
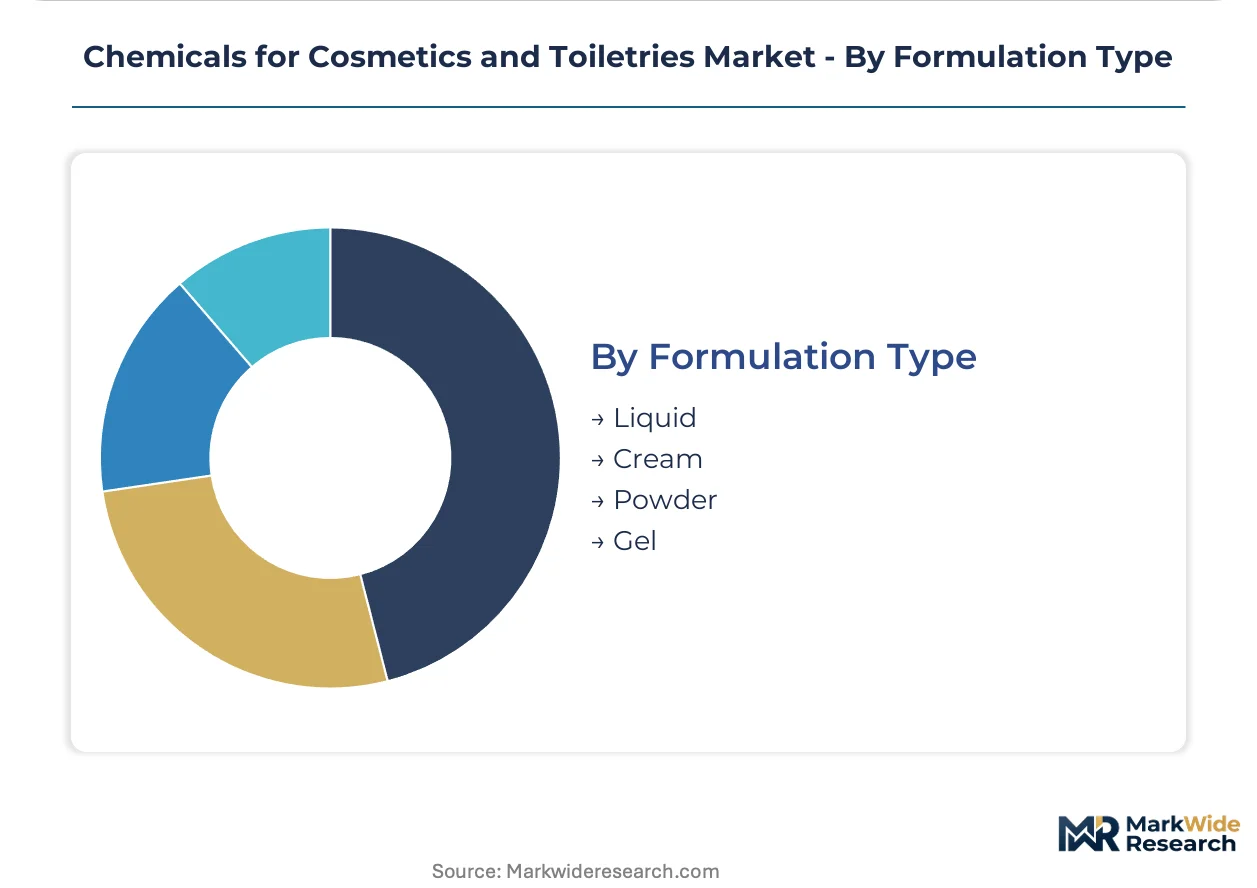
Formulation Type:
Delivery system selection determines preservative load, packaging compatibility, and manufacturing capital requirements for cosmetics manufacturers.
- Liquid:Fluid formulations including toners, serums, and cleansers requiring aqueous-phase preservation and viscosity control. Water activity reduction and hurdle technology approaches are displacing traditional preservative cocktails in clean-label launches.
- Cream:Oil-in-water or water-in-oil emulsions with structured rheology for skin feel and stability. Emulsifier selection increasingly favors glucoside-based and lecithin-derived systems over ethoxylated chemistries facing ethylene oxide residual concerns.
- Powder:Dry formulations including loose pigments, setting powders, and dry shampoo with extended shelf stability. Powder processing requires specialized milling, blending, and contamination control equipment with higher capital intensity than liquid manufacturing.
- Gel:Semisolid systems with three-dimensional polymer networks providing unique texture and delivery characteristics. Carbomer and natural gum alternatives compete on clarity, suspension capability, and electrolyte tolerance in acid and active-containing formulations.
Liquid formulations handle the majority of throughput; gel systems are expanding most quickly as Korean skin care texture innovation diffuses globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker throughput anchors European feedstock flows for specialty surfactant and emollient production. This infrastructure underwrites the region's formulation chemistry capacity.
United States
California's clean beauty retailers mandate blockchain-enabled ingredient provenance tracking by 2025, pulling preservative and natural extract sourcing toward domestic distributors. FDA cosmetic ingredient safety guidance tightens disclosure protocols for fragrance allergens. The New Jersey-Philadelphia chemical corridor concentrates emollient manufacturing for East Coast personal care formulators.
Germany
EU Green Deal bio-based mandates accelerate plant-derived ester substitution in skin care formulations ahead of 2030 carbon targets. ECHA's REACH Annex XIV authorization requirements force preservative system dossier updates. The Rhine-Ruhr industrial cluster houses integrated chemical companies with in-house regulatory affairs capabilities serving multinational cosmetics brands.
China
Domestic beauty brands scale R&D budgets for local ceramide and peptide sourcing, reducing import dependency on Japanese and Swiss suppliers. NMPA cosmetics supervision regulations streamline safety assessment protocols for domestically sourced ingredients. Shanghai's Yangtze River Delta concentration anchors fermentation-based squalane and hyaluronic acid production capacity.
South Korea
Premium skin care conglomerates drive specialty surfactant demand for K-beauty formulations with complex texture engineering. MFDS cosmetic safety regulations align with international disclosure standards while preserving domestic testing protocols. Seoul Capital Area R&D centers concentrate peptide active and ceramide complex development for export markets.
India
Underpenetrated color cosmetics manufacturing creates first-mover demand for pigment dispersions and film-forming polymers. BIS cosmetic ingredient standards formalize quality benchmarks for domestic and imported raw materials. Maharashtra's Mumbai-Pune industrial belt concentrates contract manufacturing capacity serving emerging domestic beauty brands.
Chemicals for Cosmetics and Toiletries Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios but deeper technical service penetration. The vendor base organizes around three archetypes: integrated chemical conglomerates with global regulatory affairs capabilities, biotechnology-focused active ingredient developers, and regional distributors building direct-to-brand channels. Consolidation pressure favors scale players with in-house fermentation capacity and REACH dossier ownership. Geographic expansion and portfolio diversification toward bio-based emollients represent dominant competitive vectors.
Among integrated chemical conglomerates, BASF SE and Evonik Industries AG exemplify the platform archetype with broad formulation chemistry portfolios and technical service networks. Croda International Plc occupies a position within the biotechnology-derived actives tier, representing specialty suppliers competing on premium positioning rather than commodity scale. These three anchors illustrate the structural divergence between volume-driven surfactant and emollient producers and niche active ingredient developers serving premium skin care channels.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Evonik Industries AG |
| Croda International Plc |
| Ashland Inc. |
| Givaudan |
| Clariant |
| Solvay |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
Indonesian and Malaysian palm kernel oil concentration anchors surfactant feedstock pricing, directing margin capture toward integrated emollient producers with captive esterification capacity and technical service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived actives from petroleum-based emollients and commodity surfactants. Price differentiation hinges on COSMOS certification grade and volume scale commitments. Cost compression in standard-tier surfactants is intensifying because amino-acid-based chemistries lag petroleum-derived alternatives on scale economics. Mass-market formulators exhibit highest price sensitivity; premium K-beauty brands demonstrate lowest sensitivity due to R&D budget insulation.
Supply Chain Analysis
Tariff exposure between Southeast Asian feedstock suppliers and European formulators dominates supply chain risk planning for specialty chemical distributors. Raw material flows concentrate in Indonesia, Malaysia, and China for palm-derived feedstocks and fermentation substrates. The sector draws from rooster comb extraction, shark liver sourcing, and petrochemical cracking as legacy input dependencies. Single-source vulnerability in hyaluronic acid extraction creates procurement contingency requirements. Distribution runs through integrated direct-to-brand channels displacing traditional regional agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where REACH dossier ownership and fermentation platform scale create switching costs that entrench incumbent positions against commodity substitution.
For Market Incumbents: Harden regulatory affairs capabilities to absorb ECHA SVHC list evolution and consolidate supplier relationships with mid-sized European brands lacking in-house compliance infrastructure. Deepen backward integration into fermentation capacity for squalane and hyaluronic acid to secure supply independence from marine and animal extraction constraints. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated color cosmetics segment where domestic manufacturing scale-up creates first-mover demand for pigment dispersions and film-forming polymers. Target direct-to-brand distribution platforms in Southeast Asia where multinational supplier base consolidation opens margin capture opportunities for agile regional distributors. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-focused active ingredient developers with commercial-scale fermentation capacity and existing COSMOS certification infrastructure. Long-term viability favors platforms with regulatory entrenchment in REACH Annex XIV authorization pathways. The signal to watch is NMPA streamlined safety assessment adoption rates for domestically sourced ingredients in China.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Croda and Evonik anchor supply security for bio-derived squalane independent of shark liver extraction constraints. |
| REACH Dossier Ownership Consolidation | BASF leverages in-house regulatory affairs capabilities to capture mid-tier European brand supplier relationships. |
| Direct-to-Brand Distribution Platform Buildout | Specialty chemical distributors bypass traditional regional agents to capture margin in Southeast Asia consolidation. |
| COSMOS Certification Infrastructure Investment | Clean beauty retailer mandates from Sephora and Ulta Beauty compress documentation timelines to 12-month cycles. |
| Long-term Supply Agreement Structuring | Integrated chemical conglomerates lock in multinational formulator relationships through technical service bundling. |
Study Parameters
Operator-level perspectives from formulation chemists, procurement leads at cosmetics manufacturers, technical R&D directors at specialty chemical suppliers, and distribution channel partners anchored the qualitative base. Secondary validation drew from ECHA REACH substance databases, NMPA cosmetics supervision filings, customs trade data for palm kernel oil flows, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up ingredient demand modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing across regulatory acceleration and feedstock price volatility cases bounded the projection range. The analytical framework segmented by product type, application, ingredient source, and formulation type across the analysis window. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand curves incorporated EU Green Deal bio-based mandate compliance timelines and K-beauty premiumization rates as industry-specific inputs.
Stress conditions across Indonesian export policy shifts, ECHA SVHC list expansion velocity, and NMPA domestic sourcing incentive intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fermentation platform scale-up rates and clean beauty retailer certification mandate adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market