
 Dead Sea Mud Cosmetics Market | 2026-2036
Dead Sea Mud Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Dead Sea Mud Cosmetics Market Analysis
Clinical-grade mineral concentration is reorganizing competitive tiers in Dead Sea mud cosmetics. AHAVA, Inc. leverages its integrated supply chain from Jordan Valley extraction to finished goods. Sea of Spa Natural Cosmetics Ltd. anchors its position through specialized therapeutic formulations. Biscol Investments Ltd. differentiates via premium channel control in European specialty retail.
Dead Sea mud cosmetics comprise mineral-rich sedimentary formulations containing magnesium, calcium, potassium, and bromide compounds extracted from the Dead Sea basin, processed into topical products for skin barrier repair and anti-inflammatory applications. Facial masks command the largest revenue pool due to higher per-unit pricing and repeat purchase frequency, while therapeutic use applications demonstrate the fastest volume trajectory driven by clinical endorsement. Body scrubs occupy a mature position with stable margins, whereas sachet packaging captures emerging demand through travel-retail and sampling channels.
Israel's Ministry of Health regulates mineral content disclosures and therapeutic claims, while the EU Cosmetics Regulation (EC) No 1223/2009 governs market access across European distribution channels. The US FDA oversees cosmetic labeling and safety substantiation for products entering American retail and professional spa markets. Stakeholders must monitor evolving clean beauty certification requirements and traceability mandates that will determine which extraction and formulation practices retain commercial viability.
Market Dynamics
Clinical validation protocols are restructuring competitive tiers in Dead Sea mud cosmetics, as dermatology clinics and premium wellness resorts demand mineral concentration certifications that exceed standard cosmetic labeling requirements.
Growth Catalysts
- Therapeutic Endorsement:Dermatology clinics in the United States now prescribe Dead Sea mud protocols for psoriasis and eczema management, creating institutional demand that bypasses retail channel volatility.
- REACH Compliance:The EU Cosmetics Regulation (EC) No 1223/2009 mandates traceable mineral sourcing, favoring extraction operations with documented Jordan Valley provenance and laboratory-verified compound profiles.
- Biomimetic Formulation:Advances in liposomal encapsulation technology are extending mineral bioavailability in topical applications, enabling 24-hour sustained-release masks that command premium positioning.
Market Restraints
- Input Cost Volatility:Dead Sea water levels are declining at measurable rates, concentrating extraction operations at northern basin sites and raising raw material procurement costs for sedimentary mineral feedstock.
- Supply Concentration Risk:Over 80 percent of cosmetic-grade mud processing capacity clusters within 50 kilometers of Ein Gedi, creating single-point vulnerability to regional geopolitical disruption or environmental events.
- Substitution Threat:Himalayan pink salt scrubs and volcanic ash masks from Iceland are capturing price-sensitive segments with comparable mineral claims and lower logistics costs to European distribution hubs.
Strategic Opportunities
- Travel-Retail Channel:Sachet packaging formats sized under 100 milliliters are penetrating duty-free corridors at Frankfurt, Dubai, and Singapore airports, capturing impulse purchases from long-haul passengers.
- Clean Beauty Certification:EWG Verified and COSMOS-standard designations are unlocking shelf placement at Sephora and Ulta Beauty, with mineral transparency scoring becoming a primary filter for millennial and Gen Z buyers.
- Men's Grooming Pivot:Unisex clay cleansers and post-shave mineral balms are expanding addressable demand beyond the traditional female-skincare core, with barbershop channels in London and New York testing professional-size formats.
Industry Challenges
- Compliance Timeline Compression:Israel's Ministry of Health is tightening heavy metal testing intervals from annual to quarterly cycles, forcing smaller extraction cooperatives to consolidate or exit.
- Formulation Talent Scarcity:Cosmetic chemists with Dead Sea mineral stabilization expertise command premium compensation, as the intersection of geochemistry and dermatological safety remains a narrow specialty.
- Legacy System Integration:ERP platforms at established manufacturers lack lot-level traceability modules required by EU Cosmetics Regulation Article 16, necessitating expensive middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dead Sea Mud Cosmetics Market |
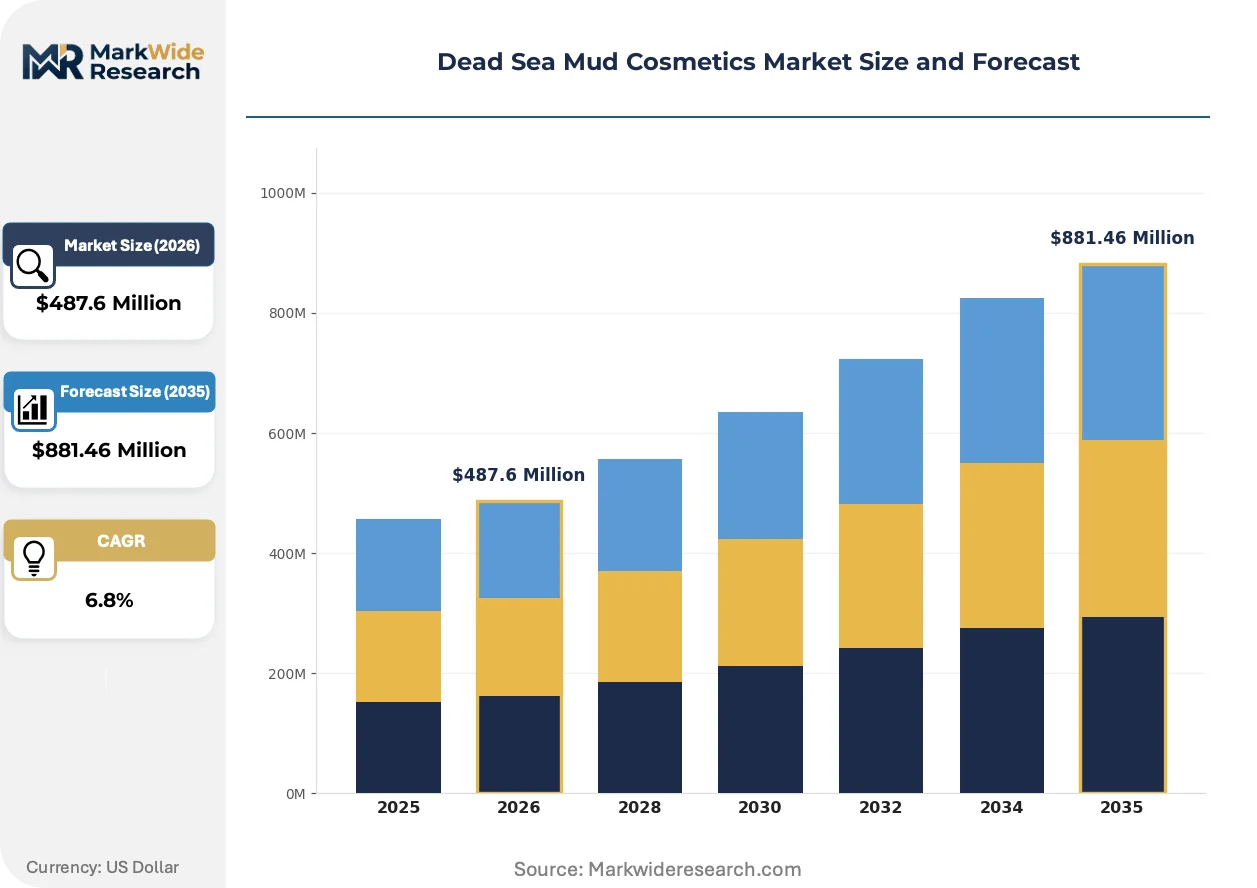
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Masks, Body Scrubs, Soaps, Moisturizers Application: Skincare, Haircare, Spa Treatments, Therapeutic Use Packaging Type: Tubs, Jars, Sachets, Pumps Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | AVANI Supreme Inc., Biscol Investments Ltd., AHAVA, Inc., SABON, HB Health, Aroma Dead Sea Spa and Cosmetics LTD, Asutra, Sea of Spa Natural Cosmetics Ltd., Kawar Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dead Sea Mud Cosmetics Market Emerging Trajectories
Biotechnology-enabled mineral preservation and blockchain-verified provenance systems are converging to redefine product differentiation in Dead Sea mud cosmetics, compressing the gap between artisan extraction claims and laboratory-substantiated efficacy.
Encapsulated mineral delivery is bifurcating the formulation landscape. Liposome-encased magnesium and calcium compounds now enable dermal penetration depths previously unreachable with raw mud suspensions. Premium spa chains in Germany and Switzerland are adopting these technologies at accelerated procurement cycles. The technology is bifurcating the market into clinical-grade certified tiers and commodity mask segments with diverging margin structures.
REACH substance evaluation protocols are tightening disclosure requirements for bromide and strontium concentrations in rinse-off cosmetics. Manufacturers must now submit updated safety dossiers for existing formulations, with dossier preparation costs exceeding 50,000 euros per SKU. Facial mask categories with therapeutic positioning face the steepest compliance burden, prompting several mid-tier brands to retreat to basic cleansing claims.
Certification-driven purchasing is displacing ingredient-list comparison as the primary selection heuristic among professional buyers. Spa procurement directors now require EWG Verified or COSMOS Organic documentation before contract consideration, filtering out suppliers lacking third-party audit infrastructure. This behavioral shift is most visible in Nordic markets, where municipal wellness centers operate under public procurement rules mandating environmental certification thresholds.
Dead Sea Mud Cosmetics Market Segmentation
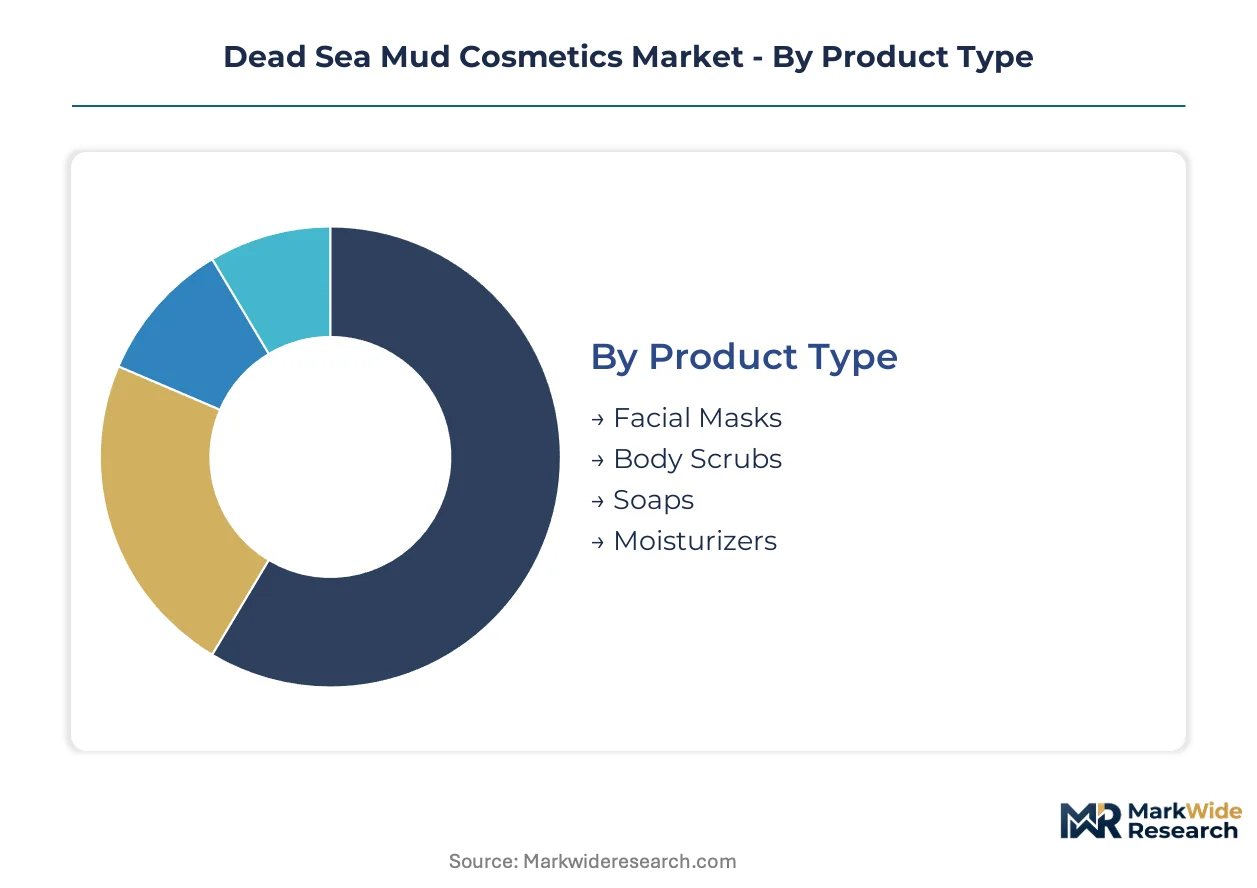
Segmentation in Dead Sea mud cosmetics reveals how mineral concentration grades and packaging formats map to distinct channel economics. Each dimension exposes margin structures and compliance burdens that determine which formulations achieve scalable distribution.
Product Type:
Channel-mix patterns diverge sharply across product formats, with premium spa protocols favoring professional-size containers while retail channels drive single-use sachet volumes.
- Facial Masks:Concentrated mineral suspensions with 15-20% Dead Sea mud content command the highest per-unit pricing in dermatology clinic channels. German wellness resorts and US medi-spas now require batch-specific mineral certification before procurement, filtering out unverified suppliers.
- Body Scrubs:Coarse sedimentary formulations blended with salt or sugar carriers occupy mature retail positioning with stable replenishment cycles. Shelf placement at Sephora and Ulta Beauty now hinges on EWG Verified status rather than ingredient claims alone.
- Soaps:Saponified bases with 5-8% mineral inclusion target price-sensitive daily-use segments through supermarket and pharmacy channels.
- Moisturizers:Emulsion-stabilized mineral complexes with extended-release properties penetrate professional spa back-bar and direct-to-consumer subscription formats.
By volume, facial masks lead. By growth pace, therapeutic-grade moisturizers are gaining share fastest.
Application:
Cost tiers stratify across application types, with clinical-grade therapeutic protocols commanding 3-4x the formulation investment of basic cleansing applications.
- Therapeutic Use:Psoriasis and eczema protocols prescribed by US dermatology clinics require FDA-compliant safety substantiation and documented mineral bioavailability studies. Institutional procurement bypasses retail margin compression entirely.
- Spa Treatments:Full-body mud wraps and hydrotherapy applications at premium resorts in Switzerland and Austria demand COSMOS Organic certification for contract eligibility under municipal procurement rules.
- Skincare:Daily facial cleansing and anti-aging routines concentrate volume through e-commerce and specialty retail, with influencer endorsement driving trial conversion.
- Haircare:Scalp detoxification and mineral-conditioning treatments occupy emerging positioning, with barbershop channels in London and New York testing professional formats.
Therapeutic use generates the highest margins per application. Skincare delivers the steepest volume expansion trajectory.
Packaging Type:
Volume scale inversely correlates with unit margins across packaging formats, with bulk professional tubs subsidizing sachet development costs for travel-retail penetration.
- Sachets:Single-serve 15-30ml foil pouches sized under 100 milliliters capture impulse purchases at Frankfurt, Dubai, and Singapore duty-free corridors. Airline amenity partnerships with Emirates and Lufthansa drive brand trial among long-haul passengers.
- Jars:Glass or PET containers with 50-200ml capacity dominate premium specialty retail and pharmacy channels, with weighted-base designs signaling quality positioning.
- Tubs:Professional-size 500ml-1 liter containers supply spa back-bars and dermatology clinic treatment rooms, with pump-dispense variants reducing contamination risk.
- Pumps:Airless dispenser systems for liquid mud cleansers and mineral toners target hygiene-conscious consumers in direct-to-consumer and pharmacy channels.
Jars lead by installed revenue base. Sachets are climbing the fastest as travel retail recovers and sampling programs expand.
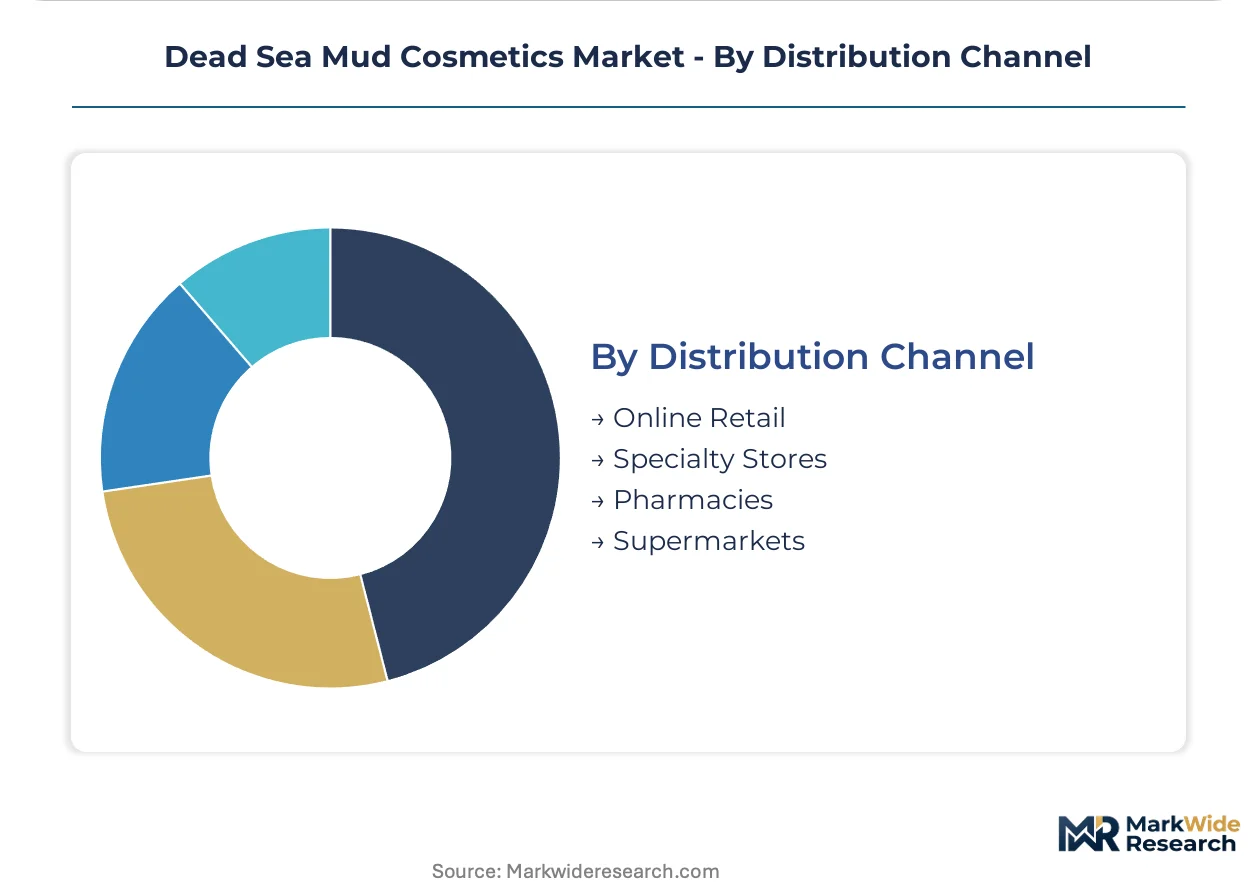
Distribution Channel:
Customer type determines channel viability, with professional buyers requiring certification documentation that consumer-facing channels rarely demand.
- Specialty Stores:Curated assortments at Sephora, Ulta Beauty, and European perfumeries now filter for COSMOS Organic or EWG Verified documentation before shelf placement, with mineral transparency scoring as a primary millennial purchase heuristic.
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription replenishment and educational content delivery, with TikTok and Instagram driving discovery among Gen Z buyers.
- Pharmacies:Boots, CVS, and Walgreens channels emphasize therapeutic positioning and dermatologist endorsement, with pharmacist recommendation influencing trial.
- Supermarkets:Mass-market placement at Tesco, Carrefour, and Kroger targets price-sensitive daily-use segments with basic cleansing claims and promotional pricing.
Specialty stores dominate premium tier revenue. Online retail is expanding most quickly as subscription models and social commerce mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German wellness resorts absorb premium pricing for certified mineral formulations, while US mass-market buyers gravitate toward promotional pricing on basic cleansing claims.
United States
Dermatology clinics in New York and Los Angeles now prescribe Dead Sea mud protocols for psoriasis management, creating institutional demand insulated from retail volatility. The FDA oversees cosmetic labeling and safety substantiation for products entering American retail and professional spa markets. Clinical-grade procurement concentrates in Miami and Scottsdale medi-spa clusters where mineral certification requirements exceed standard cosmetic thresholds.
Germany
Premium spa and wellness resorts in Bavaria and Baden-Württemberg expand proprietary Dead Sea treatment protocols with batch-specific mineral documentation. The EU Cosmetics Regulation (EC) No 1223/2009 mandates traceable mineral sourcing, favoring extraction operations with documented Jordan Valley provenance. Frankfurt airport duty-free corridors drive sachet packaging demand among long-haul passengers connecting to Middle Eastern destinations.
Israel
Domestic manufacturers leverage integrated supply chains from Jordan Valley extraction to finished goods, with Ein Gedi processing clusters supplying over 80 percent of cosmetic-grade mud capacity. The Ministry of Health maintains strict cosmetic safety standards governing mineral concentration claims and has tightened heavy metal testing intervals to quarterly cycles. Tel Aviv and Jerusalem serve as formulation R&D hubs where cosmetic chemists with mineral stabilization expertise command premium compensation.
United Kingdom
London barbershop channels test professional-size mineral balms and post-shave treatments, expanding addressable demand beyond traditional female-skincare core. Boots pharmacy chains emphasize therapeutic positioning with dermatologist endorsement influencing trial conversion. The Southeast England retail corridor filters for COSMOS Organic or EWG Verified documentation before shelf placement at specialty beauty retailers.
Switzerland
Premium resorts in Zurich and Geneva lake regions demand COSMOS Organic certification for contract eligibility under municipal wellness center procurement rules. Swissmedic maintains pharmaceutical-grade oversight expectations that exceed baseline EU cosmetic requirements. Alpine spa chains adopt liposomal encapsulation technologies at accelerated procurement cycles, bifurcating procurement into clinical-grade and commodity segments.
Dead Sea Mud Cosmetics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Integrated extraction-to-retail operators command mineral provenance verification capabilities that command premium positioning, while contract manufacturers compete on formulation flexibility and volume scale. The vendor base clusters around three strategic archetypes: Jordan Valley-integrated heritage brands, European specialty retail channel specialists, and private-label formulators serving pharmacy and supermarket tiers. Dominant competitive moves include backward integration into captive extraction assets and certification infrastructure investments that unlock professional spa and dermatology clinic procurement.
Within the heritage-integrated tier, AHAVA, Inc. and Sea of Spa Natural Cosmetics Ltd. anchor positions through Jordan Valley supply chain control. Biscol Investments Ltd. exemplifies the European channel specialist archetype, occupying positioning in premium specialty retail. AVANI Supreme Inc. represents the North American market-facing segment with spa-direct and travel-retail penetration.
| Leading Market Players |
|---|
| AVANI Supreme Inc. |
| Biscol Investments Ltd. |
| AHAVA, Inc. |
| SABON |
| HB Health |
| Aroma Dead Sea Spa and Cosmetics LTD |
| Asutra |
| Sea of Spa Natural Cosmetics Ltd. |
| Kawar Cosmetics |
| Others |
Supply Flow & Price Mechanics
Himalayan pink salt and Icelandic volcanic ash substitution is compressing price premiums in European retail channels while simultaneously shifting procurement geography toward lower-cost logistics hubs and forcing Dead Sea operators to emphasize certification-driven differentiation.
Pricing Analysis
After-sales service contracts for professional spa equipment and replenishment subscriptions now generate lifetime value multiples exceeding initial product margins. Three-tier pricing structure across clinical-grade certified, premium cosmetic, and mass-market economy levels stratifies the market, with mineral concentration documentation and EWG Verified status as primary differentiation drivers. Pricing pressure stems from declining Dead Sea water levels concentrating extraction costs at northern basin sites. Mass-market supermarket buyers exhibit highest price sensitivity, while German wellness resorts and US dermatology clinics absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Israel and Jordan anchor cosmetic-grade mud extraction, with Ein Gedi processing clusters supplying the majority of sedimentary mineral feedstock. Formulation draws from magnesium, calcium, potassium, and bromide compounds, with liposomal encapsulation technology increasingly sourced from Swiss and German specialty chemical suppliers. Single-source vulnerability concentrates risk within 50 kilometers of Ein Gedi, exposing operations to regional disruption or environmental events. Distribution runs through professional spa back-bars, specialty retail channels, and expanding direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from professional spa service contracts and direct-to-consumer replenishment subscriptions is expanding faster than one-time product sales, reframing the market as a service-attach opportunity with embedded retention economics.
For Market Incumbents: Compound defensive positioning through captive extraction asset consolidation in Jordan Valley sites and accelerated EWG Verified certification infrastructure to lock out mid-tier competitors. Icelandic volcanic ash and Himalayan salt substitutes threaten price-sensitive European retail tiers, making backward integration into documented provenance systems the critical lever for margin defense. For New Entrants and Emerging Players: Lead with unisex men's grooming formulations targeting London and New York barbershop channels, where professional-size mineral balms remain underpenetrated relative to female-skincare saturation. Travel-retail sachet formats at Dubai and Singapore duty-free corridors offer the most penetrable white space, with airline amenity partnerships providing low-cost brand trial mechanics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors extraction-integrated heritage brands with certification infrastructure already deployed. Long-term viability over the coming decade hinges on water level management and regulatory compliance scalability. Watch for quarterly heavy metal testing interval tightening by Israel's Ministry of Health as the inflection signal forcing smaller cooperative exits and creating acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Extraction Asset Consolidation | Jordan Valley site control secures documented provenance required by EU Cosmetics Regulation REACH compliance. |
| EWG Verified Certification Investment | Third-party audit infrastructure unlocks Sephora and Ulta Beauty shelf placement filtering protocols. |
| Liposomal Encapsulation R&D Partnership | Swiss and German biotechnology collaboration enables 24-hour sustained-release premium positioning. |
| Travel-Retail Sachet Channel Expansion | Frankfurt, Dubai, and Singapore duty-free penetration captures impulse purchases from long-haul passengers. |
| Men's Grooming Format Development | London and New York barbershop testing expands addressable demand beyond traditional female-skincare core. |
Methodological Framework
A spread of perspectives from extraction cooperative managers, cosmetic formulation chemists, spa procurement directors, and specialty retail category buyers converged on the working assumptions underlying demand elasticity estimates. Primary fieldwork combined structured interviews with secondary validation against EU Cosmetics Regulation submission databases, Israel Ministry of Health safety filings, customs trade records, and spa industry procurement surveys. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, packaging format, and distribution channel dimensions.
Segmentation dimensions modeled include mineral concentration grade, therapeutic versus cosmetic positioning, professional versus retail channel mix, and geographic regulatory cluster across the projection horizon. CAGRs were derived from installed base growth, replacement cycle analysis, and pricing trajectory assumptions. Industry-specific forecast inputs incorporated Dead Sea water level monitoring data and quarterly heavy metal testing compliance cost escalations.
The analysis sits within stated boundaries; outcomes outside sustained clinical endorsement by US dermatology clinics and stable REACH substance evaluation protocols would require recalibration. Forecasts reflect documented assumptions regarding mineral bioavailability study completion rates and spa procurement certification mandate adoption curves. Recalibration cycles align with material shifts in EU regulatory disclosure requirements and Dead Sea basin hydrological monitoring data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Hair Gloss Market