
 European Fragrances Microencapsulation Market | 2026-2036
European Fragrances Microencapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
European Fragrances Microencapsulation Market Intelligence
The capability gap in developing cost-effective, biodegradable shell materials is rotating competitive advantage towards specialized chemical firms. BASF SE leverages its vast polymer science portfolio to lead in sustainable material innovation. Givaudan SA differentiates through its deep expertise in fragrance composition and sensory panel validation for encapsulated scents. Smaller specialists like MikroCaps doo compete by offering highly customized encapsulation services for niche fine fragrance and cosmetic applications.
Fragrances microencapsulation entraps volatile aroma compounds within a stable, microscopic shell, often using spray drying or coacervation. Its primary commercial purpose is to enable the controlled, triggered release of scent over time, prolonging fragrance life in consumer goods. The home care application segment, particularly fabric softeners and laundry detergents, drives volume demand. In terms of technology, coacervation remains a premium choice for fine fragrances, while spray drying dominates mass-market personal care products.
European chemical regulations, specifically REACH and the CLP Regulation, govern the substances used in both the fragrance core and the capsule shell. These frameworks mandate rigorous safety assessments and clear consumer labeling for potential allergens, directly influencing material selection for all manufacturers in the region. Stakeholders must now balance the technical challenge of creating effective, sustainable encapsulation systems with evolving consumer expectations for ingredient transparency.
Market Dynamics
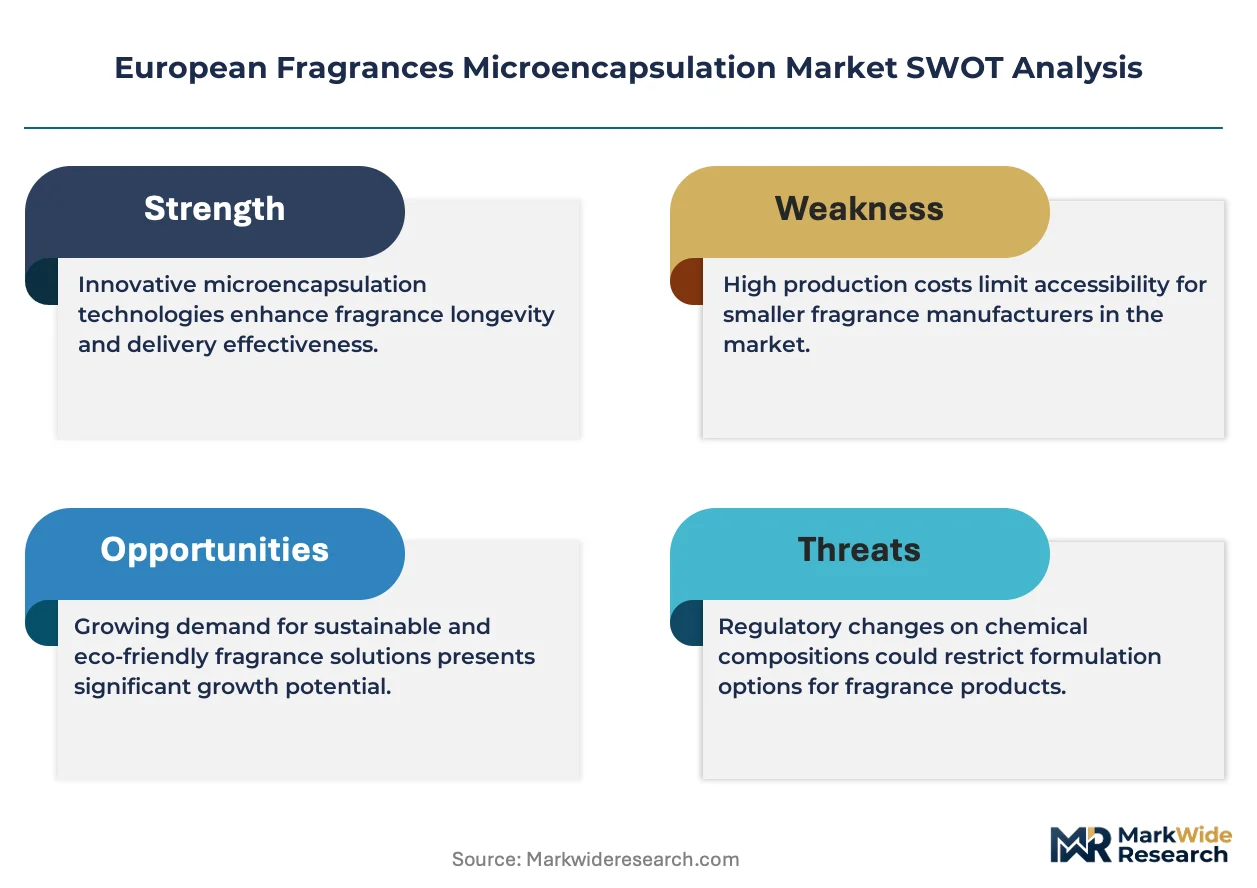
The dual pressure of regulatory mandates like the EU Green Deal and consumer demand for eco-friendly products is the central force in the European market. This compels innovation in biodegradable shell materials for fragrance microcapsules, defining technical and competitive hurdles.
Growth Catalysts
- Home Care Sector Demand:The pronounced need for long-lasting scent release in fabric softeners and laundry detergents, particularly concentrated liquid formats, continues to drive volume growth across Europe.
- EU Green Deal Incentives:European policy frameworks are encouraging research into bio-based and biodegradable polymers, creating a tailwind for sustainable encapsulation technologies that can replace traditional plastics.
- German Manufacturing Ecosystem:Germany’s concentration of advanced chemical production and major consumer goods companies provides a dense innovation and offtake hub for new microencapsulation technologies.
Market Restraints
- Biodegradable Material Costs:The higher price of sustainable shell materials compared to conventional melamine-formaldehyde or acrylic polymers creates a significant cost barrier for mass-market product formulations.
- Performance Trade-offs:Current biodegradable capsules often exhibit lower stability and fragrance retention during storage and washing cycles compared to their non-biodegradable counterparts, limiting their application.
- REACH Compliance Complexity:Navigating the European Chemicals Agency (ECHA) registration and authorization process under REACH for new shell polymers is a time-consuming and expensive hurdle for innovators.
Strategic Opportunities
- Active and Sportswear Textiles:Untapped potential exists in treating performance textiles with encapsulated fragrances that release upon friction or moisture, offering odor-masking benefits for athletes.
- Triggered Release Mechanisms:Developing novel capsules that respond to specific triggers beyond simple friction, such as pH changes or specific enzymes, opens new avenues in personal and cosmetic care.
- Eastern European Market Penetration:Expanding into markets like Poland and the Czech Republic, where the consumer goods sector is growing, offers a new volume frontier for established encapsulation technologies.
Industry Challenges
- Polymer Science Expertise Gap:A shortage of chemists with dual expertise in both fragrance chemistry and advanced polymer synthesis for biodegradable systems hinders rapid product development.
- Allergen Labeling Scrutiny:Adhering to increasingly strict CLP Regulation requirements for labeling potential fragrance allergens, even when encapsulated, complicates formulation and packaging for consumer-facing goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Fragrances Microencapsulation Market |
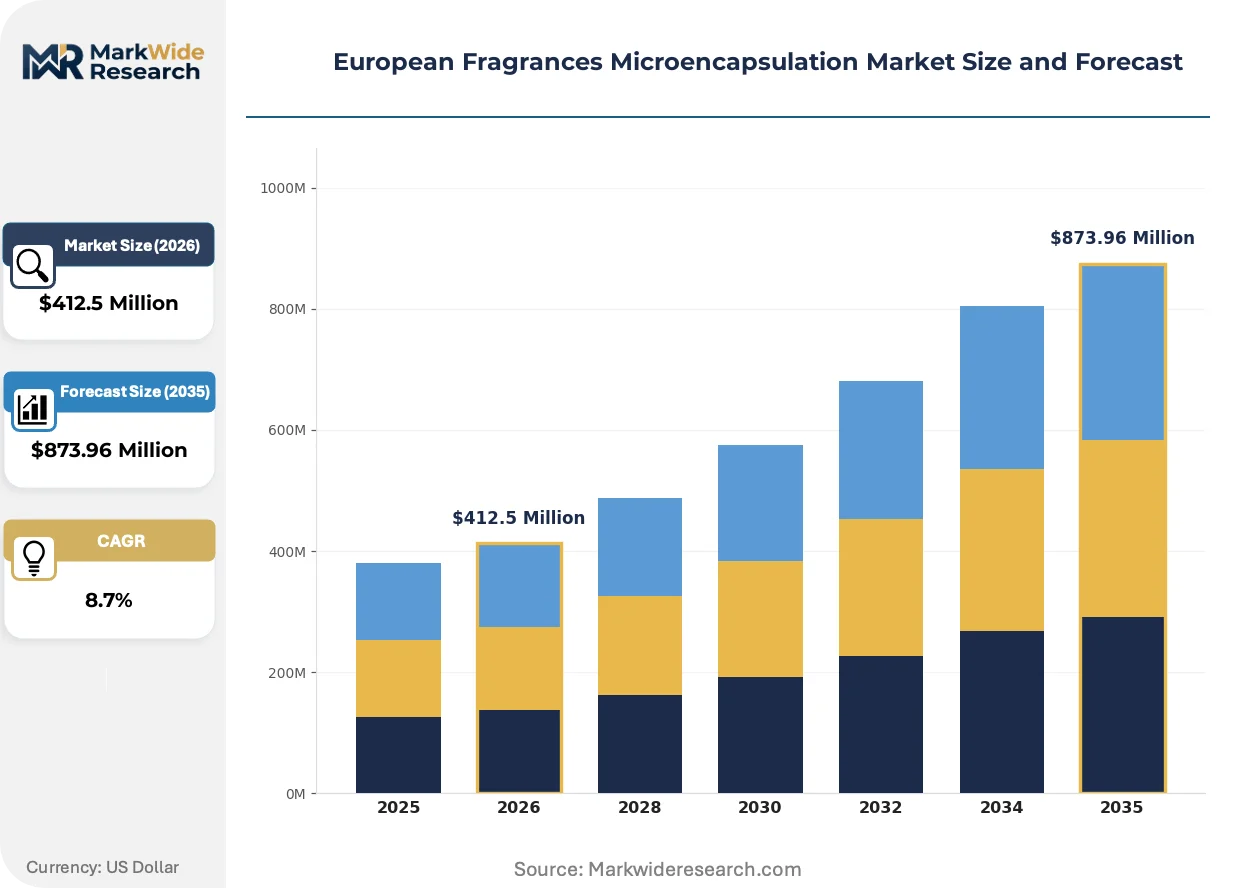
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Synthetic Aromatics, Natural Extracts, Aroma Chemicals, Botanical Concentrates Technology: Coacervation, Spray Drying, Interfacial Polymerization, Fluidized Bed Coating, Extrusion Application: Personal Care, Home Care, Fine Fragrances, Industrial Odor Control, Air Fresheners End User: Cosmetic Manufacturers, Detergent Makers, Perfume Houses, Cleaning Product Firms, Soap Producers |
| Companies Covered | Firmenich SA, DSM-Firmenich, Givaudan SA, Evonik Industries AG, BASF SE, Symrise AG, Croda International Plc, MikroCaps doo, International Flavors & Fragrances Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Fragrances Microencapsulation Market Strategic Shifts & Innovations
A fundamental shift toward sustainable materials is defining the innovation trajectory in European fragrance microencapsulation. This pivot influences everything from raw material selection to the very mechanisms of scent release, balancing eco-credentials with functional efficacy.
Biodegradable shell materials, often derived from polysaccharides or lignin, are designed to replace traditional microplastics in rinse-off applications. Home care and cosmetic brands are adopting these materials, particularly in products targeting eco-conscious consumers in Western Europe. This adoption is bifurcating the market into premium, green-certified products and cost-sensitive, traditional formulations.
The European Commission's ongoing work under the EU Green Deal, including potential restrictions on intentionally added microplastics, is a primary regulatory driver. This is forcing manufacturers to accelerate their transition away from non-degradable polymer shells, like melamine formaldehyde, used in many laundry products. The fabric care segment is most affected, responding by reformulating products and investing heavily in validation for new, compliant encapsulation systems.
Consumer preference for "clean labels" and ingredient transparency is altering purchasing decisions for home and personal care products. This disrupts the traditional model where fragrance ingredients were opaque, pushing brands to disclose not just the scent but also the nature of the delivery system. This trend is most visible in the German and French markets, where consumer advocacy groups and retail standards demand greater clarity.
European Fragrances Microencapsulation Market Segmentation
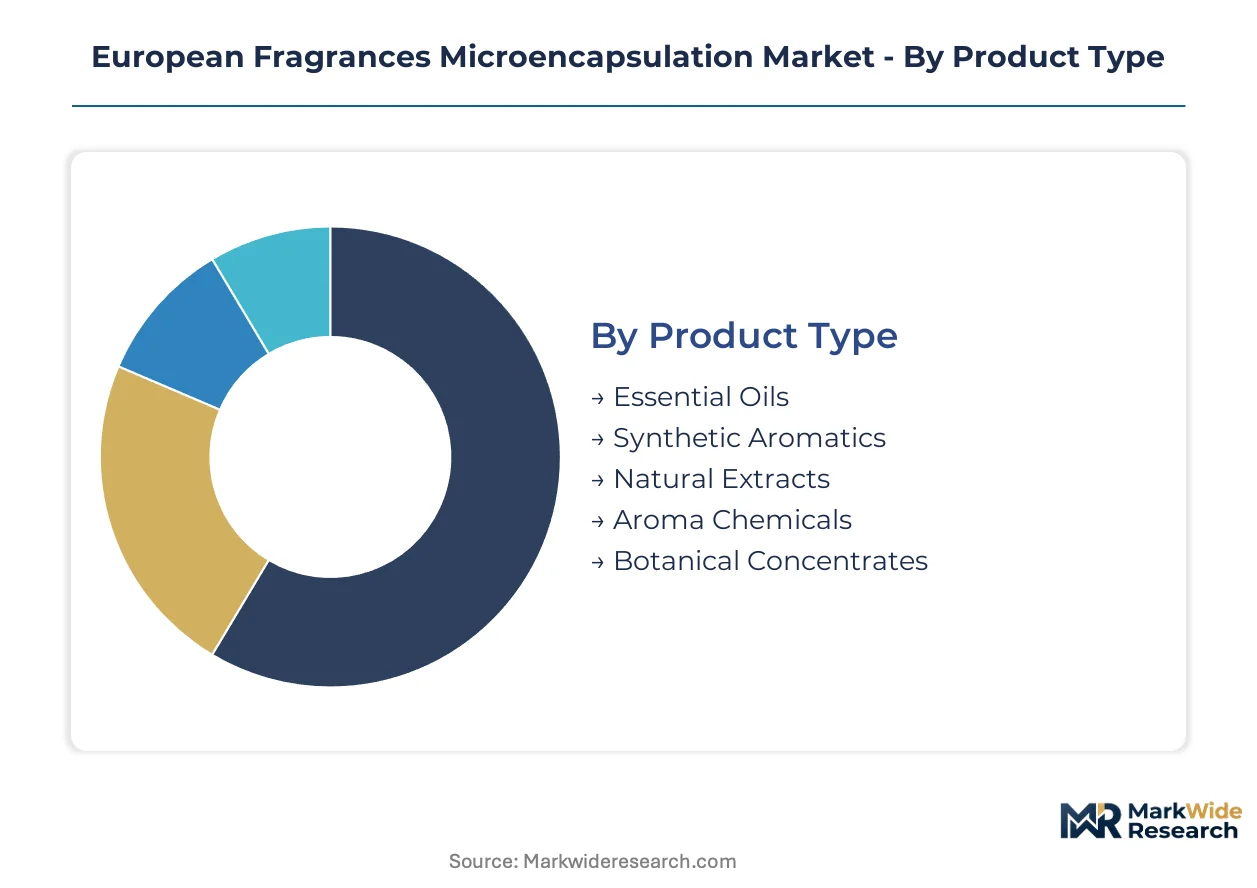
Understanding the European fragrances microencapsulation market through detailed segmentation reveals how diverse product types, technologies, applications, and end-users interact to shape demand and innovation. This granular analysis provides insights into the specific performance requirements and regulatory pressures influencing each market dimension.
Product Type:
Regulatory frameworks in Europe differentiate product types based on their origin and chemical profile, influencing material selection for encapsulation.
- Synthetic Aromatics:These are chemically synthesized fragrance compounds, offering consistent profiles and cost-effectiveness, widely used in high-volume home care products like laundry detergents due to their stability in harsh conditions across Europe.
- Essential Oils:Derived directly from plants, these natural extracts are favored in premium fine fragrances and cosmetic applications, particularly in eco-conscious markets like Germany and France, where clean label demand is high.
- Natural Extracts:These are concentrated plant-derived compounds, increasingly adopted in personal care products and eco-certified formulations across the European Union for their perceived natural benefits.
- Aroma Chemicals:Individual isolated chemical components, used to construct precise and complex fragrance profiles in various European consumer goods.
- Botanical Concentrates:Highly potent extracts from plant materials, often utilized in specialized luxury cosmetic and niche fine fragrance applications.
Established volume favors Synthetic Aromatics; emerging adoption favors Essential Oils.
Technology:
Different encapsulation technologies offer distinct release profiles and cost structures, catering to varied performance requirements across Europe.
- Spray Drying:This is a cost-effective, high-throughput process that creates microcapsules through rapid solvent evaporation, predominantly used for mass-market home care products such as liquid and powder detergents in Europe.
- Coacervation:A sophisticated technique forming multi-layered polymer shells around fragrance oil, preferred for fine fragrances and premium personal care items requiring sustained, controlled release and protection of delicate aroma compounds.
- Interfacial Polymerization:This method forms robust polymer shells at the interface of two immiscible phases, suitable for demanding industrial applications needing enhanced chemical resistance.
- Fluidized Bed Coating:Provides uniform coating for larger particle sizes, finding application in specialized European industrial and textile encapsulation.
- Extrusion:Creates larger capsules or fibers, employed in specific industrial odor control and textile treatment applications across the region.
Spray Drying dominates mass-market applications; coacervation offers premium performance.
Application:
The end-use application dictates the required release characteristics and shell material properties for encapsulated fragrances in the European market.
- Home Care:This segment drives significant volume demand, particularly in fabric softeners and concentrated liquid detergents, where long-lasting scent release is a primary consumer expectation across European households.
- Personal Care:Includes products like shampoos, conditioners, and body washes, where encapsulated fragrances provide triggered release upon friction or moisture, enhancing the sensory experience for European consumers.
- Fine Fragrances:A high-value segment utilizing advanced encapsulation for extended scent longevity and protection of volatile notes in luxury perfumes.
- Industrial Odor Control:Niche applications for neutralizing persistent malodors in commercial and industrial settings throughout Europe.
- Air Fresheners:Employs encapsulated scents for controlled and prolonged fragrance release in various European air care products.
Home Care represents the largest volume segment; Personal Care represents the fastest-growing trajectory.
End User:
The specialized needs of various end-user industries shape the demand for fragrance microencapsulation solutions across Europe.
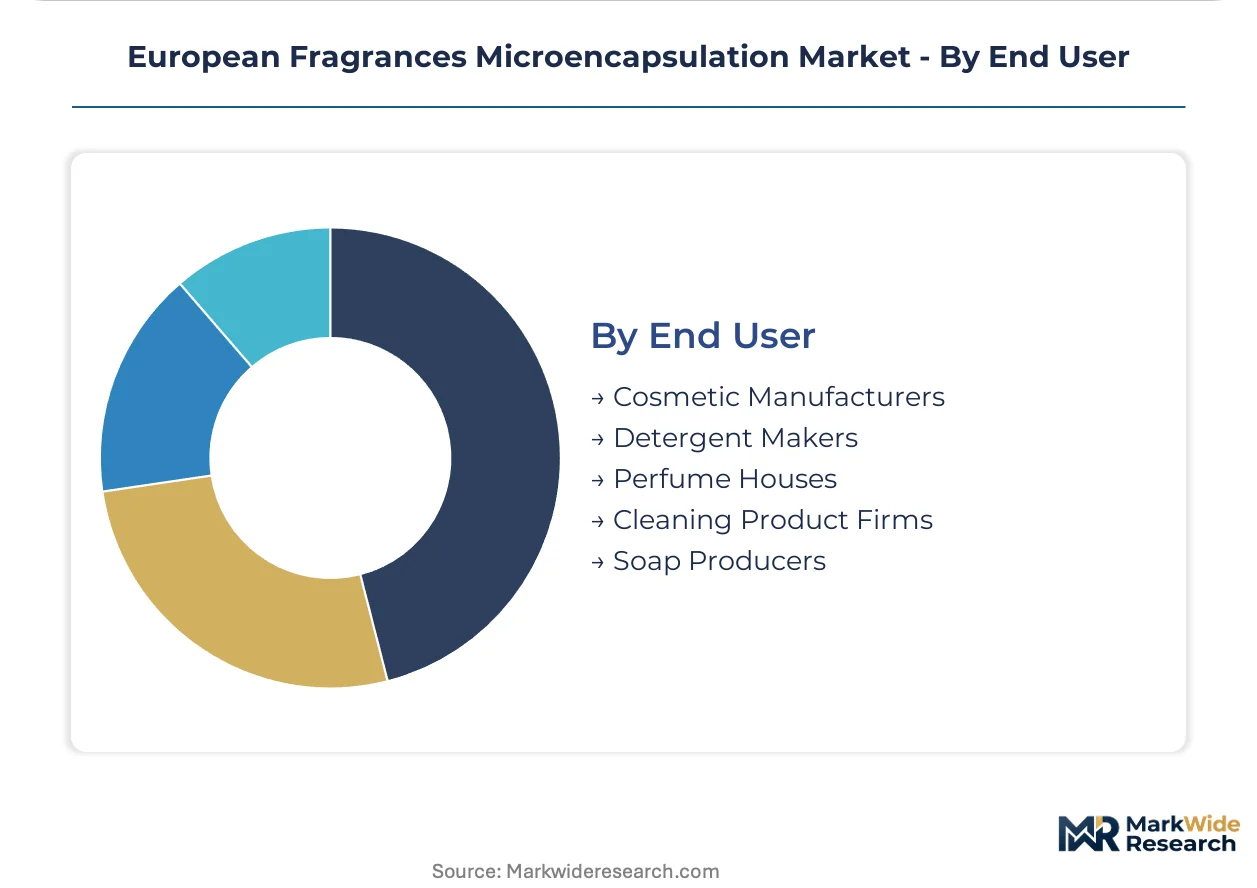
- Detergent Makers:These are primary consumers for high-volume, cost-effective encapsulated fragrances, crucial for enhancing the long-lasting scent performance of laundry products in the European market.
- Cosmetic Manufacturers:Seek innovative encapsulation for skin and hair care products, focusing on ingredient stability, targeted delivery, and a superior sensory experience for consumers.
- Perfume Houses:Require bespoke encapsulation solutions for their premium and luxury fragrance lines, ensuring scent integrity and extended wear.
- Cleaning Product Firms:Utilize encapsulated scents to deliver extended freshness and mask odors in a wide range of household and institutional cleaning products throughout Europe.
- Soap Producers:Integrate microcapsules to provide a lasting fragrance experience in both bar and liquid soap formulations for the European consumer base.
Detergent Makers drive substantial demand; Cosmetic Manufacturers pursue sophisticated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for fragrance microencapsulation in Europe shows distinct regional variations. Western European nations prioritize premium, natural ingredients for personal care, while Eastern European markets focus on cost-effective solutions for mass-market home care. This divergence influences material selection and technological adoption across the continent.
Germany
Germany’s advanced chemical production and robust consumer goods manufacturing drive demand for sustainable encapsulated fragrances. The EU Green Deal significantly influences material innovation, pushing for biodegradable shell development. Chemical clusters in the Rhine-Main region actively develop new bio-based polymers for fragrance delivery systems.
France
France exhibits strong demand for microencapsulation in its world-renowned fine fragrance and luxury cosmetic sectors. The CLP Regulation mandates stringent allergen labeling, influencing formulation choices for encapsulated scents. Grasse, the historical heart of perfumery, continues to innovate in coacervation techniques for delicate aroma compounds.
United Kingdom
United Kingdom demand is substantial in the home care and personal care segments, driven by consumer expectations for extended fragrance longevity. REACH compliance governs the safe use of encapsulated substances in consumer products. Northwest England, with its concentration of detergent manufacturers, focuses on optimizing spray drying for mass-market applications.
Poland
Poland’s expanding consumer goods sector generates increasing demand for cost-effective encapsulated fragrances in detergents and personal care items. EU directives on microplastics are prompting manufacturers to explore compliant shell materials. Major FMCG production hubs around Warsaw and Łódź are integrating established spray drying technologies.
Italy
Italy shows significant uptake in premium personal care and home care, emphasizing sophisticated fragrance profiles and aesthetic product appeal. The EU Green Deal encourages research into sustainable encapsulation solutions for cosmetic applications. Lombardy, a hub for cosmetic manufacturers, explores novel triggered release mechanisms for enhanced sensory experiences.
European Fragrances Microencapsulation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the European fragrance microencapsulation market. The market structure reveals a tiered landscape, with large chemical conglomerates offering diverse polymer science portfolios alongside dedicated fragrance houses. Strategic archetypes include material science innovators, sensory experience specialists, and niche custom solution providers. Companies pursue competitive advantage through strategic partnerships for technology co-development and portfolio diversification into bio-based materials.
Within the integrated leader tier, BASF SE, a German-based chemical company, represents a material science innovator, leveraging its vast polymer expertise. Givaudan SA, a Swiss-based company, exemplifies the sensory experience specialist archetype, focusing on fragrance composition and consumer validation. MikroCaps doo, a specialist firm, occupies a position offering highly customized encapsulation services for niche fine fragrance applications. These firms anchor different segments of the market, from mass-market home care to high-value luxury cosmetics.
| Leading Market Players |
|---|
| Firmenich SA |
| DSM-Firmenich |
| Givaudan SA |
| Evonik Industries AG |
| BASF SE |
| Symrise AG |
| Croda International Plc |
| MikroCaps doo |
| International Flavors & Fragrances Inc. |
| Others |
Cost & Logistics Intelligence
Biodegradable polymer adoption in fragrance microencapsulation simultaneously reshapes supply geography and pricing economics, displacing traditional materials. This shift mandates new sourcing strategies for raw materials and influences final product cost structures across Europe.
Pricing Analysis
Value derived from specialized formulation support drives premium pricing for bespoke microencapsulation services, while the dominant model remains per-unit transactional, often with contract-based long-term offtake agreements for large-volume buyers. Price differentiation stems from the quality grade of shell materials and the level of customization required for specific fragrance profiles. Pricing softness affects mass-market applications due to the higher cost of biodegradable materials compared to conventional options, with detergent makers exhibiting high price sensitivity. Perfume houses, conversely, prioritize performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialized polymers supports continuous production for key clients, balancing just-in-time delivery for standard components. Geographic supply concentrates in Germany, Switzerland, and France, reflecting advanced chemical production and fragrance expertise. Raw material dependencies include bio-based polymers like polysaccharides and lignin, alongside synthetic fragrance compounds. Regulatory restrictions from the EU Green Deal's microplastics focus pose a structural risk for material sourcing, while distribution runs directly from specialized chemical and fragrance manufacturers to consumer goods companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European fragrances microencapsulation market presents a defensive moat story, primarily due to regulatory entrenchment from frameworks like REACH and the EU Green Deal. These regulations create significant barriers to entry for new materials and technologies.
For Market Incumbents: Consolidate expertise in sustainable polymer science through targeted R&D investments, specifically for biodegradable shell materials. This defends against the threat of emerging bio-based polymer innovators and strengthens compliance with strict EU microplastics regulations. Protecting intellectual property around novel encapsulation systems is a critical lever for long-term competitive advantage.
For New Entrants and Emerging Players: Custom formulation services for niche cosmetic brands represent a significant service-layer gap where incumbents under-serve. The fine fragrances and specialized personal care segments are most penetrable for tailored solutions. A go-to-market angle focused on rapid prototyping and co-development with small, eco-conscious brands can establish early market presence.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized chemical firms or ingredient suppliers that have received private equity investment, offering compelling acquisition targets. Sustainable encapsulation technologies hold long-term viability due to persistent regulatory tailwinds. Watch for successful commercialization of novel, cost-effective biodegradable capsules as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Polymer R&D | This initiative ensures compliance with EU Green Deal mandates and creates proprietary, sustainable shell materials. |
| Formulate Triggered Release Systems | Developing advanced release mechanisms enhances product performance and broadens application scope in personal care. |
| Expand Eastern European Production | Capacity expansion in growing consumer goods markets like Poland reduces logistics costs and increases regional reach. |
| Secure Key Raw Material Supply | Long-term agreements for biodegradable polymer feedstocks mitigate supply chain volatility and ensure material availability. |
| Obtain Eco-Certifications | Achieving recognized environmental certifications validates product sustainability claims for eco-conscious European consumers. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, regulatory affairs specialists, and fragrance formulators converged on the working assumptions. Primary interview data was validated through secondary research, drawing from ECHA filings, industry association reports, and EU Commission documents. Bottom-up and top-down triangulation ensured data consistency.
The forecast framework modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory compliance across the analysis window. Compound annual growth rates were derived from historical trends and projected market shifts. Biodegradable material adoption rates and regulatory implementation timelines served as key forecast inputs.
Forecasts assume regulatory continuity in European regimes like the EU Green Deal; material policy shifts would require re-modeling. Revision becomes warranted when unexpected acceleration of the EU microplastics ban or cost-effective biodegradable polymer breakthroughs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market