
 Methylisothiazolinone Market | 2026-2036
Methylisothiazolinone Market Size, Share, and Industry Trends Forecast 2026-2036
Methylisothiazolinone Market Analytics
Multi-source procurement for biocide actives is broadening as formulators reduce concentration risk in methylisothiazolinone supply. Lonza Group leverages its Swiss manufacturing base to sustain high-purity cosmetic-grade output. Dow Chemical Company anchors North American supply through integrated chlor-alkali feedstock access. BASF SE competes on backward integration into key amine intermediates.
Methylisothiazolinone is a heterocyclic organic compound with the formula C4H5NOS, functioning as a broad-spectrum biocide effective against bacteria, fungi, and algae at concentrations typically below 15 parts per million. Industrial grade material dominates volume shipments to paints and coatings producers, where in-can preservation requirements are less stringent than skin-contact applications. Cosmetic grade commands premium positioning due to EU Annex V concentration limits and the multi-step purification needed for personal care compliance. The wholesale distribution channel occupies the largest margin pool by capturing formulation houses and contract manufacturers who lack direct supplier relationships.
REACH Annex V restrictions and the EU Biocidal Products Regulation shape product registration costs and allowable end-use concentrations across European markets. The US EPA Office of Pesticide Programs maintains separate registration pathways for antimicrobial pesticide applications, creating a bifurcated compliance landscape. China's MEE oversees environmental release thresholds for biocide manufacturing facilities under GB standards. Stakeholders must monitor pending dermatological safety reviews that could trigger additional concentration caps or labeling requirements without advance notice.
Market Dynamics
REACH Annex V concentration caps on leave-on cosmetics are forcing formulators to rebuild preservation systems around reduced MIT loadings, compressing margins for cosmetic-grade producers while industrial-grade suppliers capture volume growth in paints and coatings.
Growth Catalysts
- Water-based coating expansion:Architectural paint manufacturers in Germany's chemical corridor are converting solvent systems to aqueous formulations, requiring robust in-can biocide protection that MIT delivers at sub-15 ppm thresholds.
- EMA dermatological review timelines:Accelerated safety assessments for preservative alternatives are compressing registration windows for MIT-based systems, rewarding early-mover formulators with provisional market access.
- Amine intermediate backward integration:Specialty chemical producers securing captive supply of 3-mercaptopropionic acid and methylamine precursors are insulating margin structures from feedstock volatility.
Market Restraints
- Chlor-alkali feedstock concentration:North American MIT production depends on integrated caustic soda and chlorine supply chains concentrated along the US Gulf Coast, exposing buyers to hurricane-related disruption.
- EU Biocidal Products Regulation reauthorization costs:Active substance renewal fees for methylisothiazolinone under BPR Article 17 are prohibiting smaller formulators from maintaining European market access.
- Phenoxyethanol substitution in rinse-off products:Personal care brands are reformulating shampoos and body washes away from isothiazolinone blends toward alternative preservation systems with lower dermatological incident rates.
Strategic Opportunities
- India's BIS cosmetic standard harmonization:Pending alignment of preservative concentration limits with EU Annex V creates first-mover positioning for MIT suppliers establishing local technical service infrastructure.
- Marine coating biocide convergence:MIT is integrating with zinc pyrithione and copper-based antifouling systems in shipyard applications, opening volume channels outside traditional personal care and architectural markets.
- China GB standard environmental release thresholds:MEE enforcement of stricter biocide manufacturing effluent limits is advantaging producers with advanced wastewater treatment capabilities over commodity competitors.
Industry Challenges
- Multi-step purification capex intensity:Cosmetic-grade MIT production requires dedicated distillation and crystallization trains that demand 18-24 month installation timelines, constraining rapid capacity response to demand spikes.
- Cross-contamination control in toll manufacturing:Contract producers running both industrial-grade and cosmetic-grade MIT campaigns face validation burdens that extend batch turnaround times and compress asset utilization.
- REACH dossier substance identity disputes:ECHA evaluation of reaction mass compositions versus pure MIT registrations is creating uncertainty over existing authorization portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methylisothiazolinone Market |
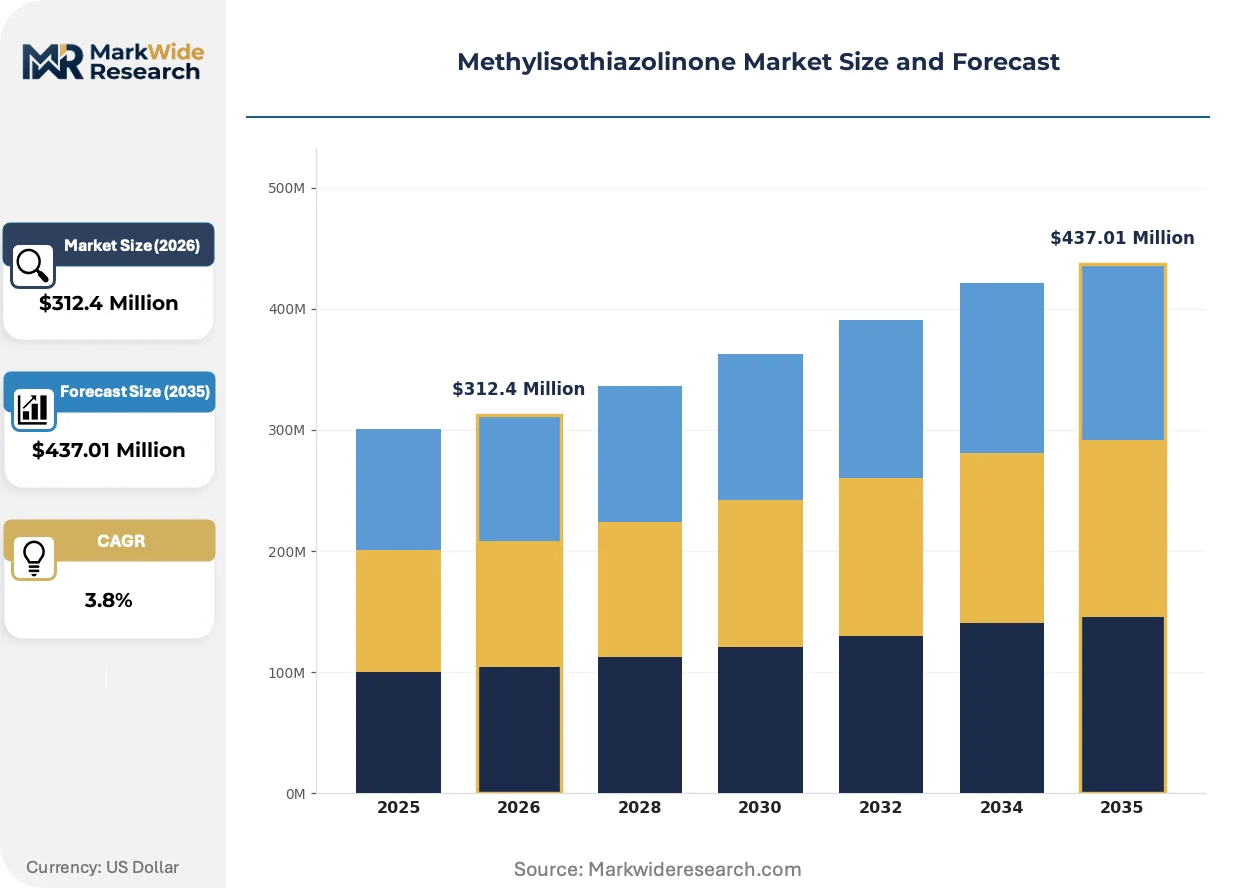
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Biocide, Preservative Application: Personal Care Products, Household Cleaners, Paints, Coatings End User: Manufacturers, Retailers, Distributors, Laboratories Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Lonza Group, Dow Chemical Company, DuPont, BASF SE, Clariant AG, Sharon Laboratories, Santa Cruz Biotechnology, Promchem, Spectrum Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methylisothiazolinone Market Evolving Landscape
Preservation system architecture is fragmenting as formulators balance biocidal efficacy against dermatological safety profiles, with technology investment concentrating on purification advances and regulatory pre-positioning.
Continuous crystallization technology is integrating into cosmetic-grade MIT production lines, replacing batch-wise isolation with steady-state purification that reduces solvent consumption and particulate contamination. German specialty chemical producers along the Ludwigshafen corridor are retrofitting existing amine synthesis assets with these systems to secure Annex V compliance without greenfield investment. This process intensification is compressing capital requirements for high-purity output while tightening specifications that commodity producers cannot match.
REACH restriction proposals on isothiazolinone mixtures in leave-on products are triggering reformulation cascades across European personal care supply chains, with downstream brands accelerating qualification of MIT-free preservation systems. The industrial consequence is a bifurcated demand profile where cosmetic-grade volumes stagnate while industrial-grade shipments to paints and adhesives expand. Germany's formulators are responding by segmenting production campaigns and pursuing dual-site registration strategies to isolate regulatory risk.
Direct procurement relationships between personal care end-users and biocide active suppliers are displacing traditional wholesale distribution channels for high-volume accounts. Multinational cosmetics houses in France and the United Kingdom are establishing annual contracting frameworks with MIT producers that bypass regional distributors, capturing margin pools previously held by formulation intermediaries. This channel compression is most visible in the premium skin-care segment, where supply security and batch traceability command priority over transactional flexibility.
Methylisothiazolinone Market Segmentation
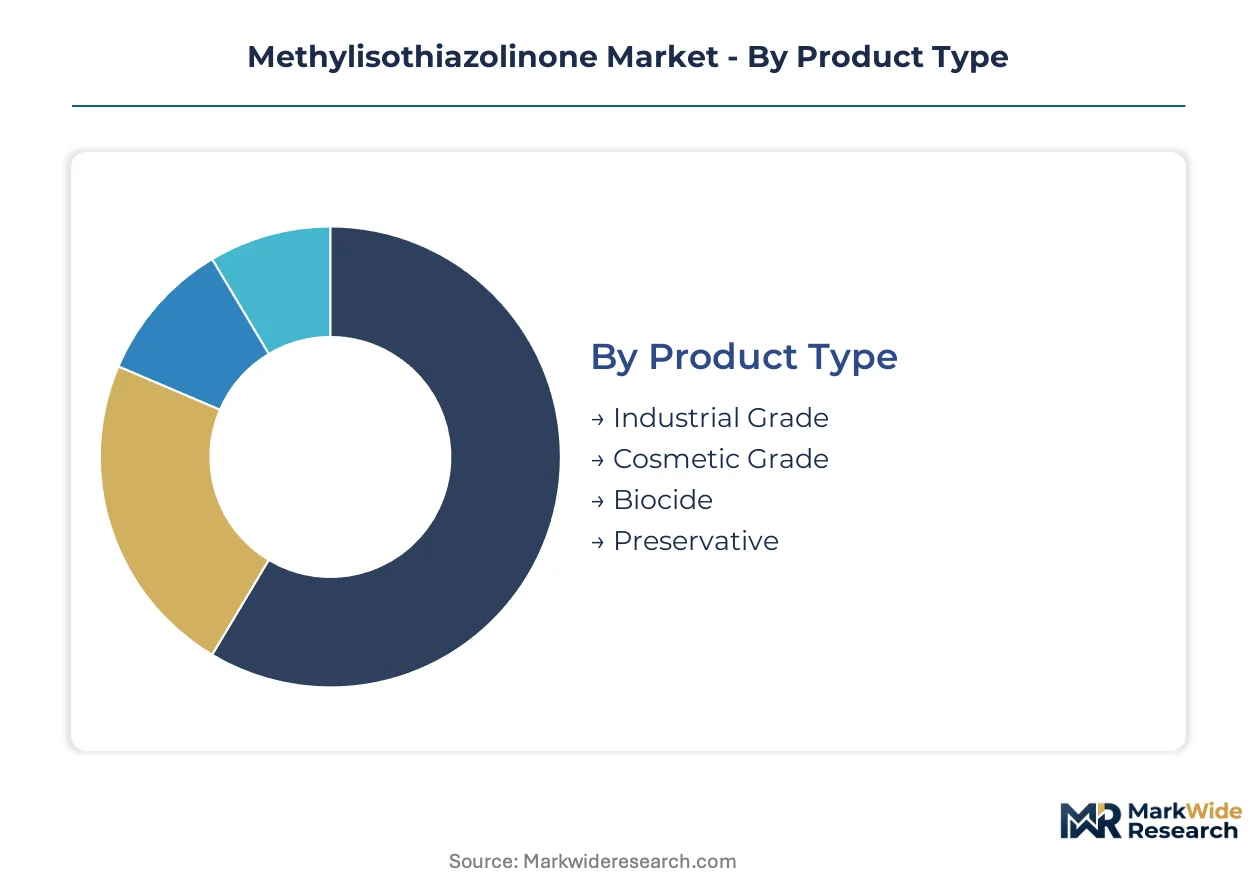
Methylisothiazolinone supply chains bifurcate sharply between high-volume industrial applications and premium cosmetic-grade specifications. Segmentation discipline determines margin capture, regulatory exposure, and backward integration requirements for producers navigating REACH concentration caps.
Product Type:
Volume shipments dominate tonnage flows while cosmetic-grade purification commands premium positioning.
- Industrial Grade:Lower-purity material with residual sulfur content and broader particle size distribution serves paints, adhesives, and metalworking fluids. Demand concentrates in Germany's Ludwigshafen chemical corridor where architectural coating manufacturers convert solvent systems to water-based formulations requiring sub-15 ppm biocide protection.
- Cosmetic Grade:Multi-step distillation and crystallization yields material meeting EU Annex V concentration limits for leave-on products. German and Swiss producers leverage continuous purification technology to secure personal care compliance without greenfield investment, though REACH restriction proposals are compressing addressable market scope.
- Biocide:EPA-registered antimicrobial concentrates for industrial water treatment and oilfield applications.
- Preservative:Pre-formulated blends with methylchloroisothiazolinone for rinse-off personal care products.
Today's leader: Industrial Grade. Tomorrow's challenger: Cosmetic Grade.
Application:
End-use concentration shapes procurement scale, technical service intensity, and substitution vulnerability.
- Personal Care Products:Skin creams, lotions, and wet wipes drive cosmetic-grade demand. EMA dermatological safety reviews and phenoxyethanol substitution trends are forcing reformulation cascades across European supply chains, stagnating volume while elevating compliance costs.
- Paints:Architectural and industrial coatings represent the fastest-expanding application as aqueous formulations proliferate. Germany's coating manufacturers along the Rhine corridor anchor regional demand with integrated supply relationships.
- Household Cleaners:Surface disinfectants and laundry additives utilize industrial-grade material with less stringent purity requirements.
- Coatings:Marine antifouling systems integrating MIT with zinc pyrithione are opening volume channels outside traditional markets.
Personal Care Products retains margin leadership. Paints offers the steepest expansion trajectory.
End User:
Procurement sophistication varies across direct manufacturers, intermediaries, and specification authorities.
- Manufacturers:Personal care and coating formulators with captive technical staff drive direct supplier relationships, bypassing wholesale channels for annual contracting frameworks.
- Distributors:Regional chemical distributors capture margin pools from mid-tier formulators lacking supplier scale.
- Retailers:Private-label personal care brands with limited R&D capacity rely on toll manufacturers for preservation system design.
- Laboratories:Contract testing facilities and regulatory consultants support BPR dossier preparation and dermatological safety documentation.
Manufacturers control specification authority. Distributors face channel compression from direct procurement trends.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and supply security priorities.
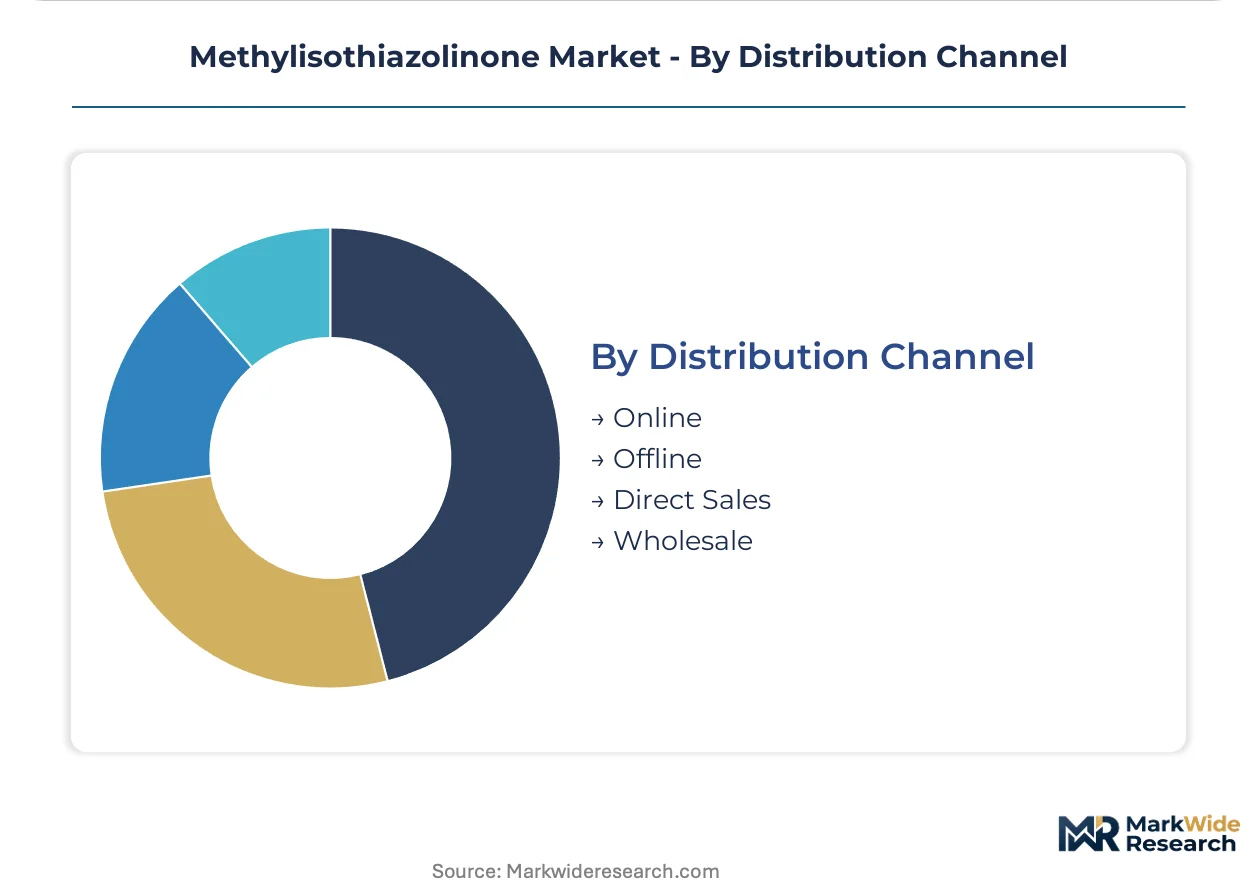
- Wholesale:Regional distributors aggregate fragmented demand from small formulators and compounders, though multinational cosmetics houses are displacing this channel for high-volume accounts.
- Direct Sales:Annual frameworks between MIT producers and personal care end-users capture traceability and batch security premiums in the premium skin-care segment.
- Offline:Traditional chemical distribution through established regional networks dominates industrial-grade shipments.
- Online:Digital procurement platforms serve spot-market purchases and specialty biocide sampling programs.
Wholesale retains volume leadership. Direct Sales is gaining share fastest among premium cosmetic-grade accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen's chemical corridor anchors methylisothiazolinone production capacity in Europe, with REACH Annex V concentration caps driving reformulation demand across personal care supply chains. Germany's integrated chlor-alkali infrastructure and Switzerland's high-purity manufacturing base concentrate supply-side capabilities.
Germany
Architectural coating manufacturers along the Rhine corridor are converting solvent-based systems to water-based formulations requiring sub-15 ppm biocide protection. ECHA's REACH Annex V restrictions on leave-on cosmetics are forcing domestic formulators to rebuild preservation systems around reduced MIT loadings. The Ludwigshafen-Leverkusen industrial cluster hosts specialty biocide production facilities serving both personal care and industrial coating end-users.
Switzerland
Swissmedic oversight of cosmetic-grade biocide purity standards creates a regulatory moat for high-specification producers serving premium skin-care brands. The country's pharmaceutical manufacturing heritage translates into advanced multi-step purification capabilities for Annex V-compliant material. Basel's chemical industry hub concentrates technical service infrastructure supporting direct procurement relationships with multinational cosmetics houses.
United States
EPA Office of Pesticide Programs registration pathways for antimicrobial pesticide applications sustain demand from industrial water treatment and oilfield biocide markets. Gulf Coast chlor-alkali concentration exposes MIT production to hurricane-related supply disruptions. Texas and Louisiana host integrated caustic soda and chlorine supply chains feeding regional biocide manufacturing.
China
MEE enforcement of GB standard environmental release thresholds is advantaging producers with advanced wastewater treatment over commodity competitors. Yangtze River Delta coating manufacturers are expanding aqueous formulation capacity requiring in-can preservation systems. Shanghai's chemical industry corridor is consolidating specialty biocide production under stricter effluent compliance regimes.
India
BIS cosmetic standard harmonization with EU Annex V concentration limits is creating first-mover positioning opportunities for MIT suppliers establishing local technical service infrastructure. Maharashtra's personal care manufacturing belt is absorbing reformulation demand as domestic brands upgrade preservation systems. Mumbai-Pune industrial corridor formulators are qualifying reduced-loading biocide blends ahead of anticipated regulatory alignment.
Methylisothiazolinone Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and feedstock integration depth. The market structures around three tiers: integrated petrochemical giants with captive chlor-alkali supply, Swiss and German specialty chemical producers with cosmetic-grade purification assets, and regional toll manufacturers serving industrial-grade demand. Strategic moves concentrate on backward integration into amine intermediates and dual-site registration strategies to isolate REACH regulatory risk.
Within the integrated chemical major tier, Lonza Group, Dow Chemical Company, and BASF SE exemplify contrasting geographic and capability positioning. Lonza's Swiss manufacturing base represents the high-purity cosmetic-grade archetype with advanced distillation and crystallization infrastructure. Dow's North American presence anchors industrial-grade volume production through integrated Gulf Coast feedstock access. BASF's German operations occupy the backward-integrated position with captive amine intermediate supply insulating margin structures from feedstock volatility.
| Leading Market Players |
|---|
| Lonza Group |
| Dow Chemical Company |
| DuPont |
| BASF SE |
| Clariant AG |
| Sharon Laboratories |
| Santa Cruz Biotechnology |
| Promchem |
| Spectrum Chemical |
| Others |
Value Network & Pricing Analysis
Family-owned German specialty chemical producers anchor cosmetic-grade methylisothiazolinone supply, translating captive chlor-alkali infrastructure into pricing discipline that resists commodity erosion. Their backward integration into amine intermediates insulates margin structures from feedstock volatility while REACH compliance costs create entry barriers that sustain premium capture.
Pricing Analysis
Chlor-alkali feedstock pass-through mechanics dominate pricing architecture for industrial-grade material, with caustic soda and chlorine cost movements transmitting directly to coating industry buyers within 30-60 day contract windows. Three-tier pricing structure across cosmetic-grade, industrial-grade, and biocide-concentrate levels separates EU Annex V-compliant purification from commodity in-can preservation. Pricing pressure stems from phenoxyethanol substitution in rinse-off personal care, compressing cosmetic-grade premiums. Small formulators exhibit highest price sensitivity due to BPR reauthorization cost burdens, while multinational cosmetics houses prioritize supply security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with US Gulf Coast chlor-alkali concentration, where hurricane exposure threatens North American MIT production continuity. Supply concentrates in Germany, Switzerland, and China, with Ludwigshafen and Basel hosting high-purity purification assets and Yangtze River Delta facilities serving industrial-grade demand. Raw material dependencies encompass 3-mercaptopropionic acid, methylamine precursors, and caustic soda feedstocks. Tariff exposure on Chinese biocide imports creates structural risk for European formulators. Distribution runs through direct annual frameworks for premium cosmetic accounts and regional wholesale channels for industrial-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU REACH compliance costs exceed India's pending BIS harmonization burden, creating margin expansion potential for early movers establishing Mumbai-Pune technical infrastructure.
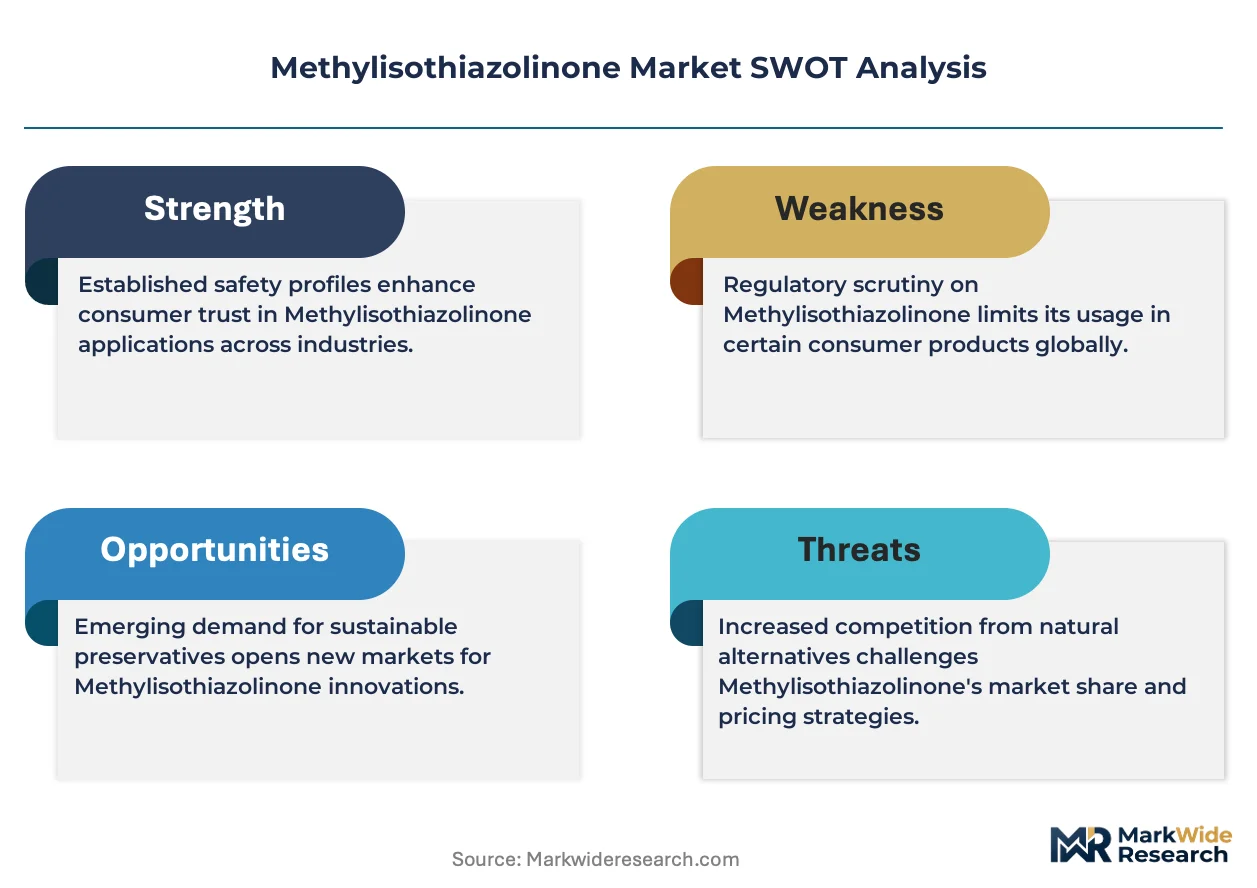
For Market Incumbents: Anticipate EMA dermatological review outcomes by pre-qualifying reduced-loading preservation systems and segmenting production campaigns across dual-site registrations. Backward integration into 3-mercaptopropionic acid supply anchors margin defense against specialty chemical entrants. Certification investment in continuous crystallization technology sustains Annex V compliance without greenfield capex exposure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cosmetic-grade material creates white-space opportunity for mid-tier producers qualifying industrial-grade output for emerging market personal care. India's BIS cosmetic standard harmonization offers the most penetrable regulatory entry point. Marine coating biocide convergence with zinc pyrithione systems provides volume traction outside saturated personal care channels. Technical service partnerships with Mumbai-Pune formulators accelerate local qualification timelines. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing amine synthesis assets are the most active acquirer in this space, seeking cosmetic-grade purification capabilities to complete biocide portfolios. Long-term viability hinges on regulatory pre-positioning rather than commodity scale. Acquisition targets center on Swiss and German toll manufacturers with validated continuous crystallization trains. The signal to watch is ECHA substance identity dispute resolution, which could invalidate existing REACH dossiers and compress authorization values overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Intermediates | Captive supply of methylamine precursors insulates BASF and Lonza from feedstock volatility in Ludwigshafen and Basel corridors. |
| Continuous Crystallization Technology Deployment | German producers retrofit existing assets to secure EU Annex V compliance without 18-24 month greenfield installation timelines. |
| Dual-Site Registration Strategy | Formulators segment production campaigns across Switzerland and Germany to isolate REACH regulatory risk from single-jurisdiction exposure. |
| Direct Procurement Framework Expansion | Multinational cosmetics houses in France and the United Kingdom bypass wholesale channels to capture traceability premiums in premium skin-care. |
| Marine Coating Biocide Convergence | MIT integration with zinc pyrithione in shipyard applications opens volume channels outside traditional personal care and architectural markets. |
Research Methodology
Bottom-up personal care and coating demand modeling reconciled against top-down chlor-alkali and amine intermediate supply tracking forms the analytical core of this study. Primary interviews with plant managers at German and Swiss specialty chemical facilities, procurement leads at downstream coating OEMs, and regulatory affairs directors navigating BPR dossier preparation were validated against secondary sources including ECHA registration databases, Cefic biocide industry reports, and customs trade flow data. This triangulation approach ensures demand signals from formulation houses align with verified production capacity and feedstock availability.
Historical trendline analysis of methylisothiazolinone shipment volumes by grade tier and end-use industry established baseline growth patterns across the projection horizon. The forecast framework models segmentation dimensions encompassing cosmetic-grade versus industrial-grade purity levels, personal care versus paints versus marine coating applications, and direct sales versus wholesale distribution channels. CAGRs were derived from regression analysis of aqueous coating formulation adoption rates and REACH restriction implementation timelines. Industry-specific inputs include EMA dermatological review acceleration schedules and India's BIS harmonization progress indicators.
The model assumes a particular technology adoption path where continuous crystallization displaces batch-wise purification; alternative pathways for membrane-based separation would alter the outlook for capital requirements and compliance timelines. Forecasts reflect assumptions regarding REACH Annex V concentration stability and phenoxyethanol substitution elasticity that could revise demand trajectories if regulatory or consumer preference shifts accelerate. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Anti-Aging Products Market