
 South America Cosmeceuticals Market | 2026-2036
South America Cosmeceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cosmeceuticals Market Analytics
The capital-intensity gap between mass-market formulators and clinical-grade manufacturers is collapsing as Brazilian consumers demand pharmacy-validated efficacy claims. Natura &Co leverages its Amazonian botanical supply chain to dominate premium botanical ingredient positioning. Grupo Boticário anchors its portfolio through specialized dermocosmetic lines distributed via pharmacy channels. L'Oréal competes by extending dermatological research partnerships with São Paulo-based skin research institutes.
Cosmeceuticals comprise topically applied formulations containing biologically active ingredients at concentrations sufficient to exert measurable physiological effects on skin structure or function, typically manufactured through cold-process emulsification to preserve peptide and antioxidant stability. Skincare leads product type revenue as anti-aging serums and sun repair formulations command sustained professional endorsement. Haircare represents the fastest-growing segment as trichology clinics proliferate in urban Brazil and prescribe scalp treatment protocols. The online distribution channel captures expanding margin pools through subscription-based personalized regimens that bypass traditional retail markups.
ANVISA governs cosmetic ingredient safety assessments and product notification requirements, while Brazil's National Health Surveillance Agency collaborates with MERCOSUR technical committees to harmonize regional regulatory standards. REACH-aligned ingredient disclosure protocols from Europe are indirectly shaping formulation transparency expectations among Brazilian professional buyers. Stakeholders must monitor how ANVISA's pending updates to sunscreen active ingredient classifications will reposition UV-protection cosmeceuticals across pharmacy and professional channels.
Market Dynamics
ANVISA's tightening cosmetic ingredient notification timelines are compressing product development cycles, forcing manufacturers to front-load safety documentation and accelerate cold-process formulation investments before market entry.
Growth Catalysts
- Professional channel expansion:Dermatology clinics across São Paulo and Rio de Janeiro are expanding cosmeceutical service menus, creating pull-through demand for pharmacy-distributed clinical-grade formulations.
- MERCOSUR harmonization:Brazil's National Health Surveillance Agency collaborates with regional technical committees to align cosmetic safety standards, reducing cross-border registration friction for multi-country portfolios.
- Peptide stabilization advances:Cold-process emulsification technologies are preserving bioactive ingredient integrity, enabling higher-concentration serums that meet professional efficacy thresholds.
Market Restraints
- Amazonian botanical supply concentration:Premium ingredient sourcing clusters in Brazil's northern rainforest regions, exposing formulators to climate-driven harvest volatility and extraction capacity constraints.
- ANVISA registration timelines:Pending updates to sunscreen active ingredient classifications are freezing pipeline decisions for UV-protection cosmeceuticals, delaying pharmacy channel launches.
- Clinical validation costs:Pharmacy-validated efficacy claims require dermatological testing protocols that mass-market formulators struggle to fund, narrowing competitive entry.
Strategic Opportunities
- Subscription-based personalized regimens:Online distribution channels are capturing margin pools through direct-to-consumer models that bypass traditional retail markups and capture recurring revenue.
- Trichology clinic proliferation:Urban Brazil's expanding scalp treatment protocols are driving haircare cosmeceutical demand in an underpenetrated professional segment.
- REACH-aligned transparency:European ingredient disclosure protocols are reshaping Brazilian professional buyer expectations, creating first-mover advantage for disclosure-leading formulators.
Industry Challenges
- Formulation talent scarcity:Cold-process peptide stabilization and biologically active concentration optimization require specialized cosmetic chemists that São Paulo's talent pool struggles to supply at scale.
- Multi-channel compliance complexity:Simultaneous ANVISA notification for pharmacy, professional, and direct-to-consumer channels demands parallel regulatory workflows that strain smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cosmeceuticals Market |
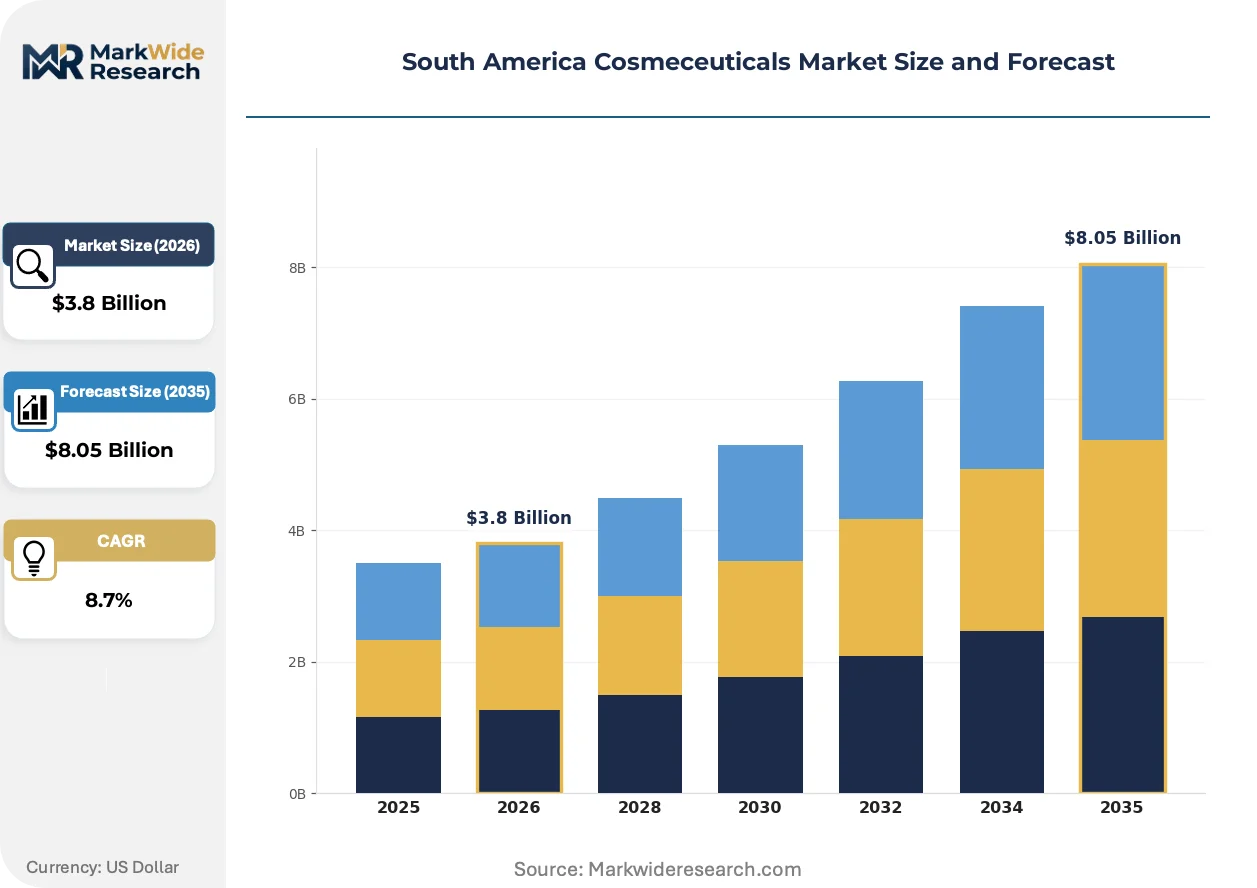
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Nail Care End User: Women, Men, Professionals, Retail Consumers Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Ingredient Type: Botanical, Synthetic, Mineral-Based, Others |
| Companies Covered | Natura &Co, Grupo Boticário, L'Oréal, Unilever, Procter & Gamble, Beiersdorf, Estée Lauder Companies, Shiseido, Johnson & Johnson, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cosmeceuticals Market Evolving Landscape
Cold-process manufacturing capabilities are separating clinical-grade formulators from mass-market competitors, while regulatory transparency requirements and channel fragmentation are reshaping how cosmeceuticals reach Brazilian consumers.
Biologically active peptide formulations are bifurcating the South American cosmeceuticals landscape. These stabilized protein fragments penetrate dermal layers to stimulate collagen synthesis and cellular repair. São Paulo's medical spas and dermatology clinics are adopting high-concentration peptide serums at accelerated pace, demanding cold-process manufacturing that preserves molecular integrity. The technology is bifurcating competitive positioning between manufacturers with in-house emulsification capabilities and those dependent on outsourced production.
ANVISA's pending sunscreen active ingredient reclassification is forcing formulation reformulation across UV-protection portfolios. The regulatory shift will reposition mineral and chemical UV filters into distinct pharmacy and professional channel tiers based on concentration thresholds. Sun repair cosmeceuticals containing reclassified actives face compressed launch timelines as manufacturers race to secure revised notifications before enforcement deadlines.
Subscription-based personalized regimens are displacing traditional retail pharmacy purchases among Brazil's Southeast region consumers. Direct-to-consumer platforms capture patient skin profile data to algorithmically match serum combinations, bypassing the pharmacy markup structure that dominates mass-market distribution. São Paulo's dense network of beauty clinics increasingly prescribes these personalized protocols, creating hybrid professional-digital channel integration that traditional formulators struggle to replicate.
South America Cosmeceuticals Market Segmentation
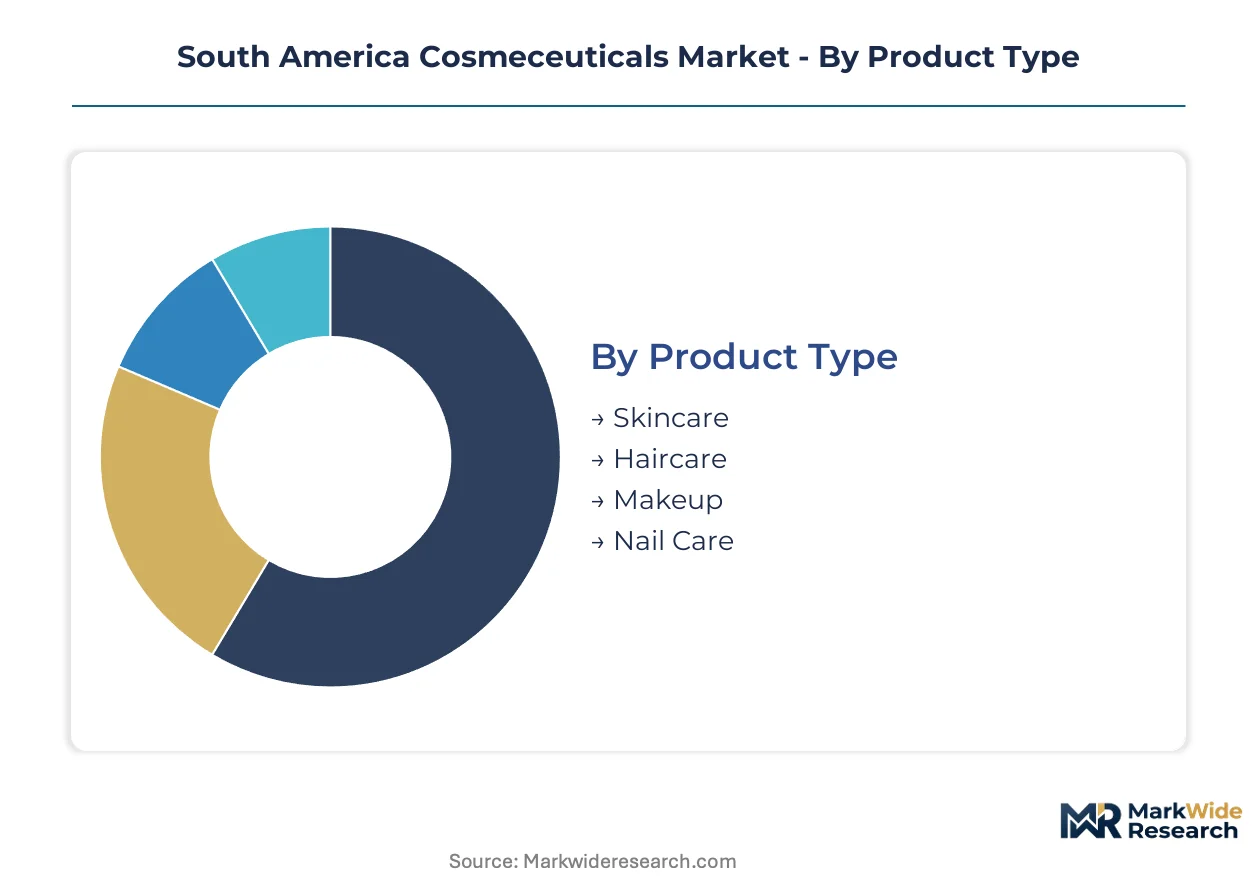
Segmentation across South America's cosmeceuticals market reveals how formulation sophistication and channel access stratify consumer access. Each dimension exposes distinct margin structures and regulatory exposure profiles that manufacturers navigate through specialized positioning.
Product Type:
Domestic manufacturing concentrates in São Paulo's industrial corridor, while premium peptide formulations draw imported active ingredients through specialized distributors. Export-led segments leverage Brazil's Amazonian botanical extraction capacity for international pharmacy channels.
- Skincare:Anti-aging serums and sun repair formulations incorporate stabilized peptides and antioxidants through cold-process emulsification. São Paulo's medical spas and dermatology clinics anchor professional demand for pharmacy-validated efficacy claims. ANVISA's tightening notification timelines compress development cycles for new launches.
- Haircare:Scalp treatment protocols from proliferating trichology clinics drive prescription-grade cosmeceutical demand. Urban Brazil's Southeast region concentrates clinic expansion, with formulations requiring bioactive concentration thresholds that mass-market producers cannot meet.
- Makeup:Hybrid cosmetic-therapeutic products with SPF and skin-conditioning actives occupy pharmacy prestige tiers.
- Nail Care:Cuticle treatments and nail strengthening formulations represent a narrow professional segment with limited clinical validation requirements.
Skincare commands the established base. The steepest expansion runs through Haircare.
End User:
Customer archetypes split between self-directed retail purchasers and protocol-driven professional patients, with distinct price elasticity and repurchase pattern profiles.
- Women:The core demographic across all channels, with Southeast Brazil's dense urban corridors driving subscription-based personalized regimen adoption. Direct-to-consumer platforms algorithmically match serum combinations to individual skin profiles.
- Men:An underpenetrated segment with accelerating professional channel uptake as male-focused trichology and dermatology services expand.
- Professionals:Dermatologists, trichologists, and medical aestheticians prescribing clinic-dispensed formulations with concentration thresholds exceeding retail limits.
- Retail Consumers:Pharmacy and supermarket purchasers seeking mass-market dermocosmetic lines without clinical consultation requirements.
Women anchor volume concentration. Professionals deliver the highest margin capture per transaction.
Distribution Channel:
Channel selection determines regulatory workflow complexity and margin retention, with ANVISA notification requirements varying across pharmacy, professional, and direct-to-consumer pathways.
- Online:Subscription-based personalized regimens bypass traditional retail markups and capture recurring revenue through patient skin profile data. São Paulo's beauty clinics increasingly prescribe these hybrid professional-digital protocols.
- Supermarkets:Mass-market dermocosmetic lines with limited bioactive concentrations and simplified efficacy claims.
- Pharmacies:Clinical-grade formulations requiring ANVISA notification and professional endorsement, concentrated in Brazil's Southeast region.
- Specialty Stores:Premium positioning with trained staff consultation, bridging retail accessibility and professional credibility.
Pharmacies maintain the revenue base. Online channels are climbing the fastest.
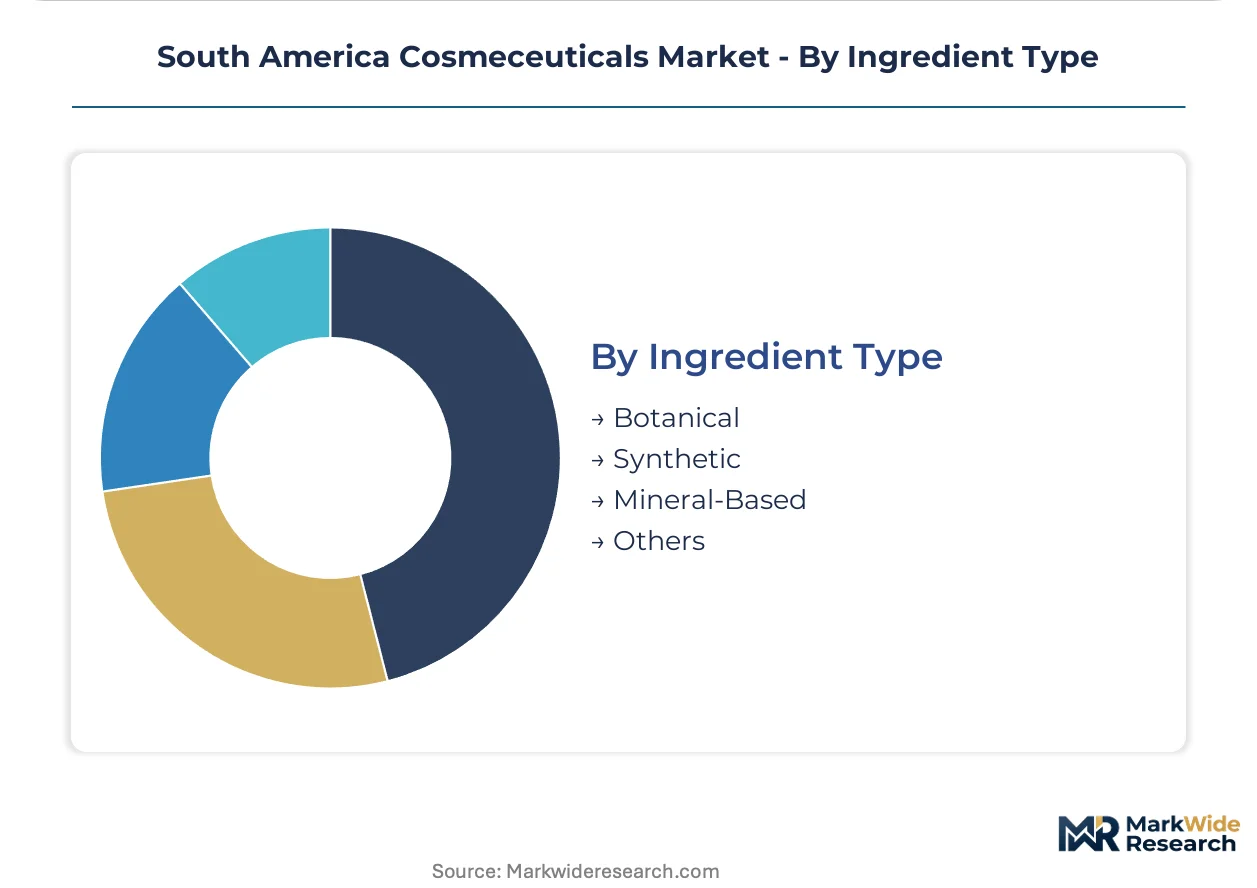
Ingredient Type:
Sourcing geography and extraction methodology determine supply security and formulation positioning, with climate volatility and regulatory transparency shaping procurement decisions.
- Botanical:Amazonian plant extracts from northern rainforest regions supply premium positioning, though climate-driven harvest volatility and extraction capacity constraints expose formulators to supply interruption. Natura &Co's captive supply chain dominates this segment.
- Synthetic:Laboratory-engineered peptides and stabilized actives enable precise concentration control and batch consistency for professional-grade formulations.
- Mineral-Based:Zinc oxide and titanium dioxide UV filters face pending ANVISA reclassification that will reposition products across pharmacy and professional tiers.
- Others:Biotechnologically derived ingredients including fermented extracts and enzymatic processing outputs.
Botanical ingredients anchor premium differentiation. Synthetic actives are gaining share fastest through supply security advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy channel premiums in Brazil's Southeast command 40-60% markups over mass-market equivalents in Colombia and Peru, creating a pricing-power asymmetry that concentrates manufacturer investment in São Paulo's industrial corridor.
Brazil
São Paulo's medical spas and dermatology clinics anchor professional channel demand for clinical-grade peptide serums. ANVISA's tightening cosmetic ingredient notification timelines compress product development cycles for domestic formulators. The Southeast region concentrates pharmacy-distributed dermocosmetic sales, with Rio de Janeiro's beauty clinics expanding cosmeceutical service menus.
Argentina
Buenos Aires trichology clinics drive prescription-grade scalp treatment demand in an underpenetrated professional segment. The country's national pharmaceutical regulator enforces MERCOSUR-aligned cosmetic safety standards that reduce cross-border registration friction with Brazil. Córdoba's industrial zone hosts emerging contract manufacturers serving Andean markets.
Chile
Santiago's pharmacy chains capture premium positioning through trained staff consultation models bridging retail and professional credibility. The country's national health authority maintains stringent cosmetic ingredient disclosure protocols that shape formulation transparency expectations. Valparaíso's port infrastructure facilitates import of stabilized peptide actives for domestic compounding.
Colombia
Bogotá's direct-to-consumer platforms expand subscription-based personalized regimen adoption among urban consumers. The national food and drug surveillance institute (INVIMA) governs cosmetic product registration with timelines shorter than ANVISA's Brazilian requirements. Medellín's emerging beauty clinic networks prescribe hybrid professional-digital protocols.
Peru
Lima's pharmacy channels remain concentrated in mass-market dermocosmetic distribution with limited clinical-grade penetration. The country's national health authority (DIGEMID) administers cosmetic safety assessments with resource constraints that delay premium product market entry. Arequipa's regional distribution hubs channel imported formulations to southern Andean markets.
South America Cosmeceuticals Market Competitive Landscape
Concentration sits with vertically integrated domestic conglomerates possessing captive botanical supply chains and pharmacy channel control. Market structure exhibits tiered competition: Amazonian-sourced premium botanicals, synthetic peptide clinical-grade specialists, and mass-market dermocosmetic formulators. Strategic moves center on cold-process manufacturing capacity expansion and direct-to-consumer platform development to bypass traditional retail markups.
Within the domestic conglomerate tier, Natura &Co and Grupo Boticário exemplify vertically integrated positioning through Amazonian botanical supply chain control. L'Oréal occupies a position as the multinational research-intensive archetype leveraging dermatological institute partnerships. These three anchors represent distinct competitive vectors: captive raw material security, pharmacy channel density, and clinical validation infrastructure.
| Leading Market Players |
|---|
| Natura &Co |
| Grupo Boticário |
| L'Oréal |
| Unilever |
| Procter & Gamble |
| Beiersdorf |
| Estée Lauder Companies |
| Shiseido |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Cold-process manufacturing scale economies in São Paulo's industrial corridor compress unit costs for peptide stabilization while simultaneously erecting price floors that exclude mass-market formulators lacking equivalent emulsification capacity. This scale-concentration dynamic concentrates margin capture among clinical-grade manufacturers while forcing smaller competitors toward commodity positioning or exit.
Pricing Analysis
The customization-premium spread between subscription-based personalized regimens and standard pharmacy-distributed formulations spans three distinct tiers: clinic-prescribed algorithmic serum combinations commanding maximum margin, pharmacy-validated dermocosmetic lines occupying mid-tier positioning, and mass-market supermarket offerings at price floors. Price differentiation rests on bioactive concentration thresholds and ANVISA notification status rather than brand equity alone. Cost compression in the mass-market tier intensifies as Grupo Boticário and Natura &Co leverage captive supply chains to undercut independent formulators. Retail consumers in Brazil's Northeast and Amazon regions exhibit highest price sensitivity, while São Paulo's medical spa patients demonstrate minimal elasticity for professional-endorsed protocols.
Supply Chain Analysis
Amazonian botanical extraction capacity in Brazil's northern rainforest states creates a single-source chokepoint for premium ingredient positioning, exposing Natura &Co's competitors to harvest volatility and climate-driven supply interruption. Synthetic peptide actives draw from specialized distributors in Switzerland and South Korea, with cold-process emulsification equipment sourced predominantly from Germany and Japan. Tariff exposure on imported stabilization technology compounds input cost pressure for domestic manufacturers lacking backward integration into equipment procurement. Distribution runs through pharmacy channel gatekeepers in São Paulo and Rio de Janeiro, with direct-to-consumer platforms eroding traditional retail markups through subscription-based patient data capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
São Paulo's talent pool for cold-process cosmetic chemists remains critically thin relative to manufacturer expansion plans, creating a capability bottleneck that will determine competitive survival across the analysis window.
For Market Incumbents: Shield peptide formulation portfolios through accelerated cold-process capacity additions in São Paulo's industrial corridor before ANVISA's sunscreen reclassification freezes pipeline decisions. Deepen backward integration into Amazonian botanical extraction to neutralize climate-driven supply volatility threatening premium positioning. Channel control through exclusive pharmacy distribution agreements remains essential as direct-to-consumer platforms erode traditional retail markups. For New Entrants and Emerging Players: Anchor in male-focused trichology services across urban Brazil's Southeast corridor, where scalp treatment protocols remain underpenetrated relative to skincare saturation. Target subscription-based personalized regimens through hybrid professional-digital channel integration that incumbent formulators struggle to replicate. Go-to-market execution should emphasize algorithmic skin profile matching prescribed through São Paulo's expanding beauty clinic networks. For Investors and Strategic Acquirers: Cold-process manufacturing specialists with in-house emulsification capabilities represent the priority acquisition archetype, given formulation talent scarcity and technology bifurcation separating clinical-grade from mass-market competitors. Long-term viability hinges on regulatory navigation capacity across ANVISA's tightening notification timelines and MERCOSUR harmonization protocols. Monitor ANVISA's pending sunscreen active ingredient reclassification as the critical inflection signal repositioning UV-protection portfolios across channel tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Process Manufacturing Scale-Up | In-house emulsification capacity preserves peptide integrity and excludes outsourced competitors from professional channels. |
| Amazonian Supply Chain Integration | Captive botanical extraction neutralizes climate volatility threatening premium ingredient positioning for non-integrated formulators. |
| Direct-to-Consumer Platform Launch | Subscription-based personalized regimens bypass pharmacy markups and capture recurring revenue through patient skin profile data. |
| Trichology Clinic Partnership Network | Urban Brazil's expanding scalp treatment protocols create white-space demand in an underpenetrated professional segment. |
| ANVISA Notification Acceleration | Front-loaded safety documentation compresses product development cycles before pending sunscreen reclassification enforcement deadlines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, MERCOSUR technical committee harmonization protocols, and São Paulo state industrial development records. Primary interviews engaged cosmetic chemists at cold-process manufacturers, pharmacy channel procurement managers, dermatology clinic operators, and trichology service directors across Brazil's Southeast region. Secondary validation drew from customs data on peptide active ingredient imports, pharmaceutical distribution audit trails, and subscription platform user analytics. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Segmentation dimensions modeled include product type, end user archetype, distribution channel pathway, and ingredient sourcing geography across the projection horizon. CAGRs were derived through trend extrapolation of professional channel expansion rates and direct-to-consumer platform adoption curves, cross-referenced against ANVISA notification timeline compression effects. Industry-specific forecast inputs incorporated trichology clinic proliferation rates in urban Brazil and cold-process equipment installation data from São Paulo's industrial corridor.
Decision-makers should treat outputs as directional under assumptions of sustained ANVISA regulatory trajectory and MERCOSUR harmonization progress; material deviation in sunscreen reclassification timing or botanical harvest volatility would warrant model refresh. Practitioners should keep alternative scenarios live as peptide stabilization technology costs and subscription platform competitive dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Minoxidil Market