
 Coffee Processing Machine Market | 2026-2036
Coffee Processing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Processing Machine Market Outlook
Modular roasting-to-brewing configurations is realigning how commercial buyers evaluate capital outlays. De'Longhi S.p.A. leverages its dual-channel presence across home and hospitality segments to sustain pricing power. Breville Group Limited anchors its growth in premium semi-automatic grinding units for café operators. Jura Elektroapparate AG differentiates through integrated digital brewing platforms that reduce operator training costs.
Coffee processing machines encompass equipment that transforms green coffee beans into finished beverage products through thermal roasting, particle-size reduction, extraction under pressure, and portion-controlled packaging. Industrial-grade roasting drums operate at batch temperatures between 180°C and 230°C, while precision grinding units achieve particle distributions calibrated for espresso, drip, or cold-brew methods. Brewing equipment commands the largest installed base among product types, though packaging systems capture disproportionate margin pools through automated valve-sealing and nitrogen-flushing technologies. Within application segments, specialty shops are outpacing commercial establishments in equipment upgrade frequency as single-origin menus proliferate.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in cold-brew processing lines, while FDA food-contact material standards govern packaging system components destined for the United States. BIS certification requirements in India affect import eligibility for grinding and roasting equipment entering that market. Stakeholders must weigh energy-efficiency compliance costs against the operational savings from next-generation heat-recovery roasting systems.
Market Dynamics
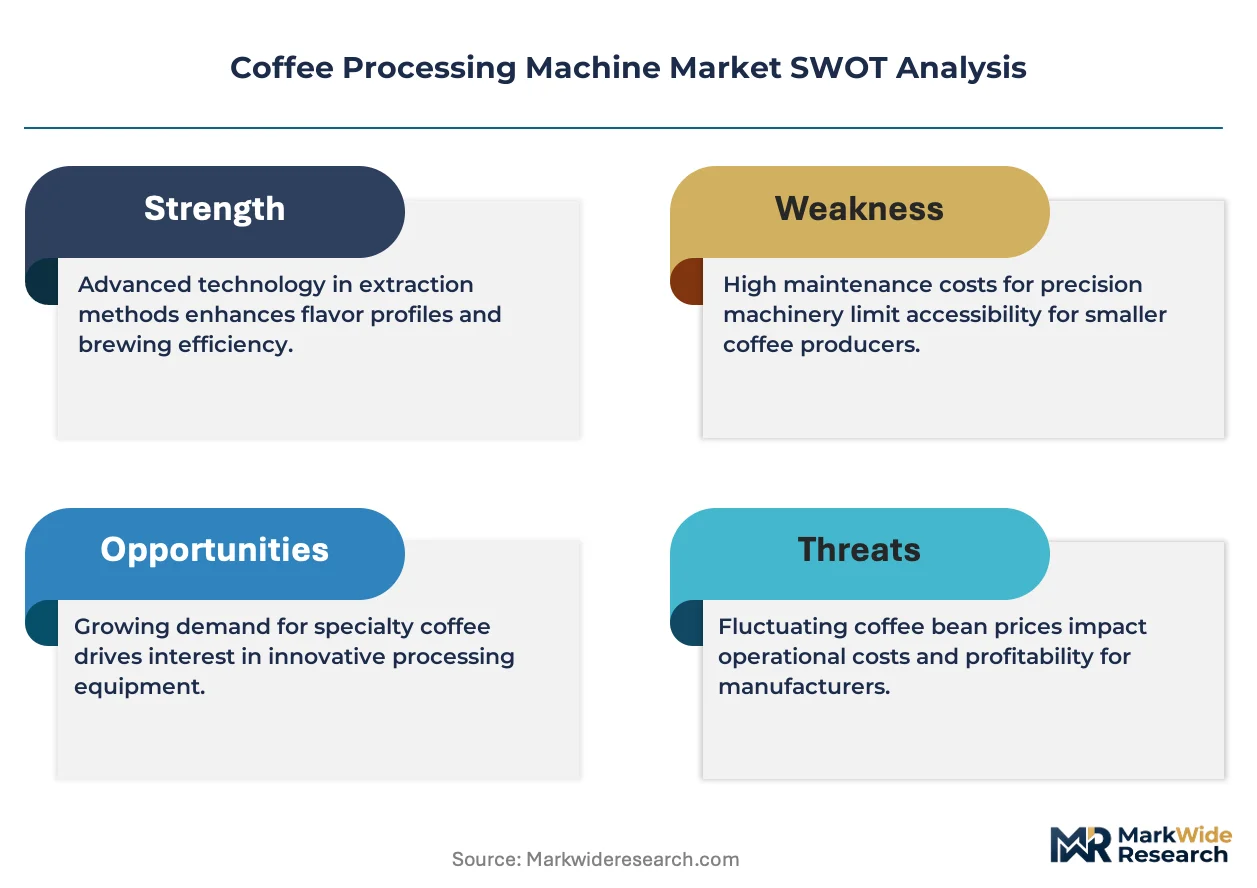
EU Green Deal energy-efficiency mandates and F-Gas Regulation constraints are forcing manufacturers to abandon gas-fired roasting architectures in favor of electric heat-recovery systems, compressing equipment replacement cycles across European processing facilities.
Growth Catalysts
- Specialty café roasting mandates:Single-origin menu proliferation drives in-house drum installation at premium chains, accelerating batch-size customization demand.
- Brazil dual-demand surge:Domestic consumption expansion and export-oriented processing investments create parallel equipment procurement channels.
- CE marking harmonization:Unified EU conformity assessment reduces cross-border certification friction for roasting system vendors.
Market Restraints
- Stainless steel input volatility:Roasting drum and grinding burr fabrication faces nickel alloy price swings that compress OEM margin predictability.
- Italian component concentration:Precision burner assemblies and control systems source predominantly from Lombardy-based suppliers, creating single-point vulnerability.
- Refrigerant transition friction:F-Gas Regulation phase-down timelines outpace cold-brew line engineering cycles, delaying equipment certification.
Strategic Opportunities
- Indian BIS certification pathway:Grinding and roasting equipment import eligibility gaps create first-mover advantage for pre-certified European vendors.
- Modular roasting-to-brewing integration:Configurable footprints allow specialty operators to scale capacity without facility relocation.
- Heat-recovery technology convergence:Thermal oxidizer integration with roasting exhaust systems enables compliance-plus-efficiency dual positioning.
Industry Challenges
- Roast profile engineering talent scarcity:Equipment operators lack thermodynamic optimization skills for electric drum calibration.
- Legacy gas infrastructure stranded asset risk:Commercial kitchens face write-down pressure when retrofitting for electric systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Processing Machine Market |
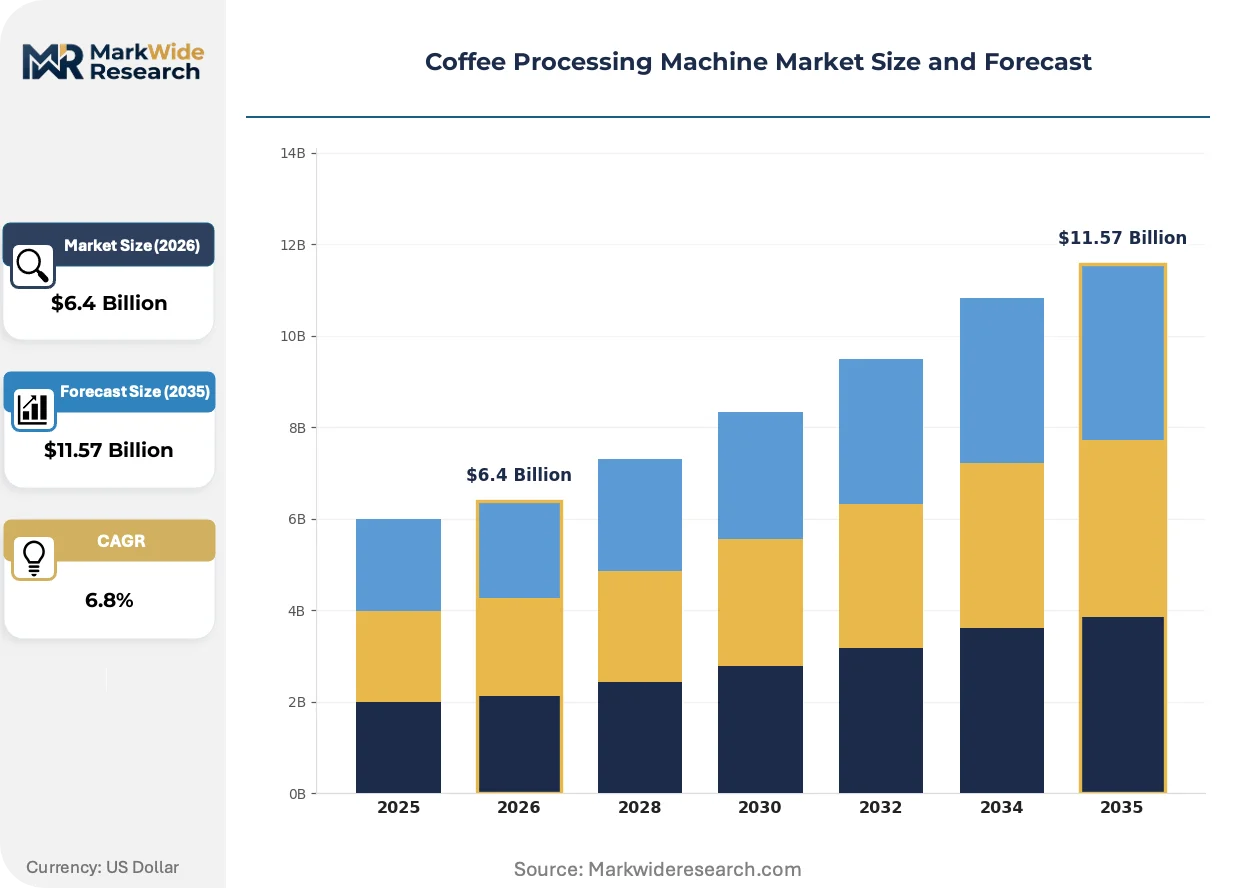
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roasting Machines, Grinding Units, Brewing Equipment, Packaging Systems Application: Commercial Establishments, Home Use, Cafés, Specialty Shops Technology: Automatic, Semi-Automatic, Manual, Digital End User: Restaurants, Coffee Shops, Manufacturers, Retailers |
| Companies Covered | De'Longhi S.p.A., Breville Group Limited, Jura Elektroapparate AG, Rancilio Group S.r.l., La Marzocco S.r.l., Bunn-O-Matic Corporation, Hamilton Beach Brands Holding Company, Gaggia S.p.A., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Processing Machine Market Strategic Shifts
Digital brewing platforms and automated roast profiling are compressing operator training requirements while elevating consistency thresholds. Equipment vendors now compete on software integration depth rather than mechanical specifications alone.
Predictive maintenance algorithms embedded in roasting control systems are expanding into mid-capacity commercial installations. Regional roasting cooperatives in Colombia and Kenya adopt cloud-connected drum monitors to synchronize batch curves across distributed facilities. This telemetry infrastructure is expanding into subscription-based service models that unbundle hardware from operational support.
F-Gas Regulation refrigerant phase-down mandates are accelerating cold-brew processing line redesigns toward CO₂-based extraction or ambient brewing architectures. Equipment manufacturers serving EU-bound exports must engineer dual-certification pathways for legacy and next-generation cooling circuits. Cold-brew packaging system vendors face compressed development timelines as 2027 quota reductions approach.
Specialty coffee chains now specify equipment through direct vendor relationships rather than distributor intermediaries. Roasting system procurement teams at Blue Bottle, Intelligentsia, and Stumptown negotiate factory-floor customization that bypasses standard dealer inventories. This channel disintermediation concentrates in North American urban markets where equipment financing aligns with real estate lease structures.
Coffee Processing Machine Market Segmentation
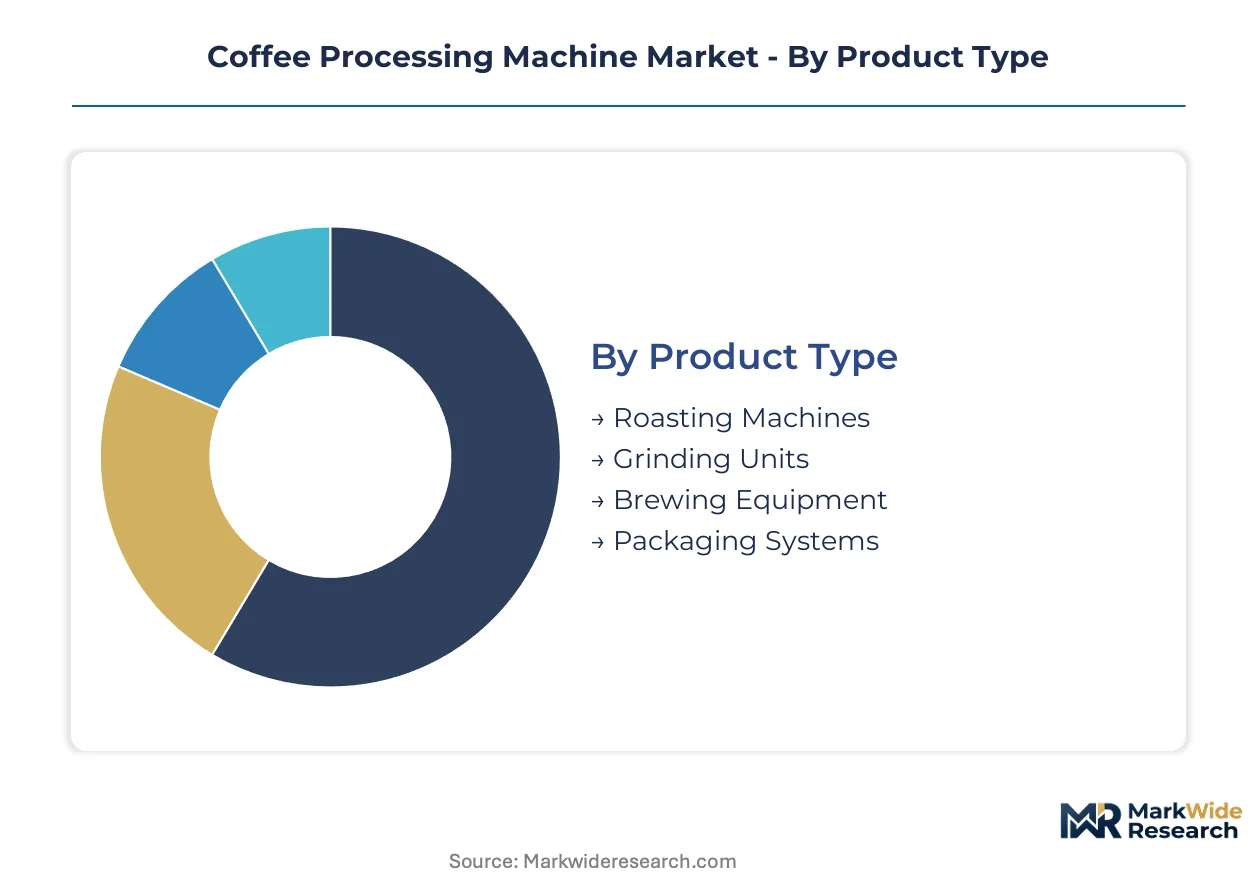
Segmentation in coffee processing machines determines capital allocation strategies across vastly different operational scales. Equipment specifications diverge sharply between high-throughput industrial installations and precision-focused specialty configurations. Understanding these boundaries clarifies where technology investments concentrate and which segments command premium pricing power.
Product Type:
Capital-intensity varies dramatically across equipment categories, with roasting machines demanding the highest upfront outlays for thermal systems and emissions controls. Grinding units require precision engineering investment, while brewing equipment spreads costs across broader unit volumes.
- Roasting Machines:Industrial drum roasters operate at batch temperatures between 180°C and 230°C with thermal oxidizer integration for emissions compliance. Demand concentrates in Brazil where domestic consumption expansion and export-oriented processing investments create parallel procurement channels for both electric heat-recovery systems and legacy gas-fired architectures.
- Grinding Units:Precision burr assemblies achieve particle distributions calibrated for espresso, drip, or cold-brew extraction methods. Specialty shops in North American urban markets drive specification customization through direct vendor relationships that bypass standard dealer inventories.
- Brewing Equipment:Commands the largest installed base among product types, spanning from single-serve pod systems to multi-group espresso platforms.
- Packaging Systems:Automated valve-sealing and nitrogen-flushing technologies capture disproportionate margin pools despite smaller unit volumes.
Roasting machines absorb the bulk of installed capacity; packaging systems are expanding most quickly through automation upgrades.
Application:
Customer operational models dictate equipment selection, with volume throughput requirements separating commercial-scale installations from precision-focused configurations.
- Commercial Establishments:High-throughput batch processing with standardized roast profiles and minimal operator intervention. Hotels and institutional foodservice in Germany and Italy anchor replacement demand as EU Green Deal mandates accelerate equipment refresh cycles.
- Specialty Shops:Single-origin menu proliferation drives in-house drum installation with batch-size customization. Blue Bottle, Intelligentsia, and Stumptown negotiate factory-floor specifications that align equipment financing with real estate lease structures.
- Home Use:Compact footprint requirements with simplified user interfaces dominate residential specifications.
- Cafés:Mid-capacity configurations balancing throughput consistency with menu versatility.
Commercial establishments retain the deepest installed base; specialty shops are climbing the fastest through chain expansion and equipment upgrade frequency.
Technology:
Automation depth determines operator skill requirements and consistency thresholds across installation scales.
- Automatic:Fully integrated roast profiling and brewing parameter control with minimal manual intervention. Cloud-connected drum monitors enable regional roasting cooperatives in Colombia and Kenya to synchronize batch curves across distributed facilities.
- Digital:Embedded predictive maintenance algorithms and telemetry infrastructure expanding into subscription-based service models that unbundle hardware from operational support.
- Semi-Automatic:Operator-controlled dosing with automated extraction timing for mid-tier café applications.
- Manual:Lever-operated espresso and hand-crank grinding for ritual-focused consumption contexts.
Automatic systems dominate new capital deployment; digital platforms are gaining share fastest through software integration depth.
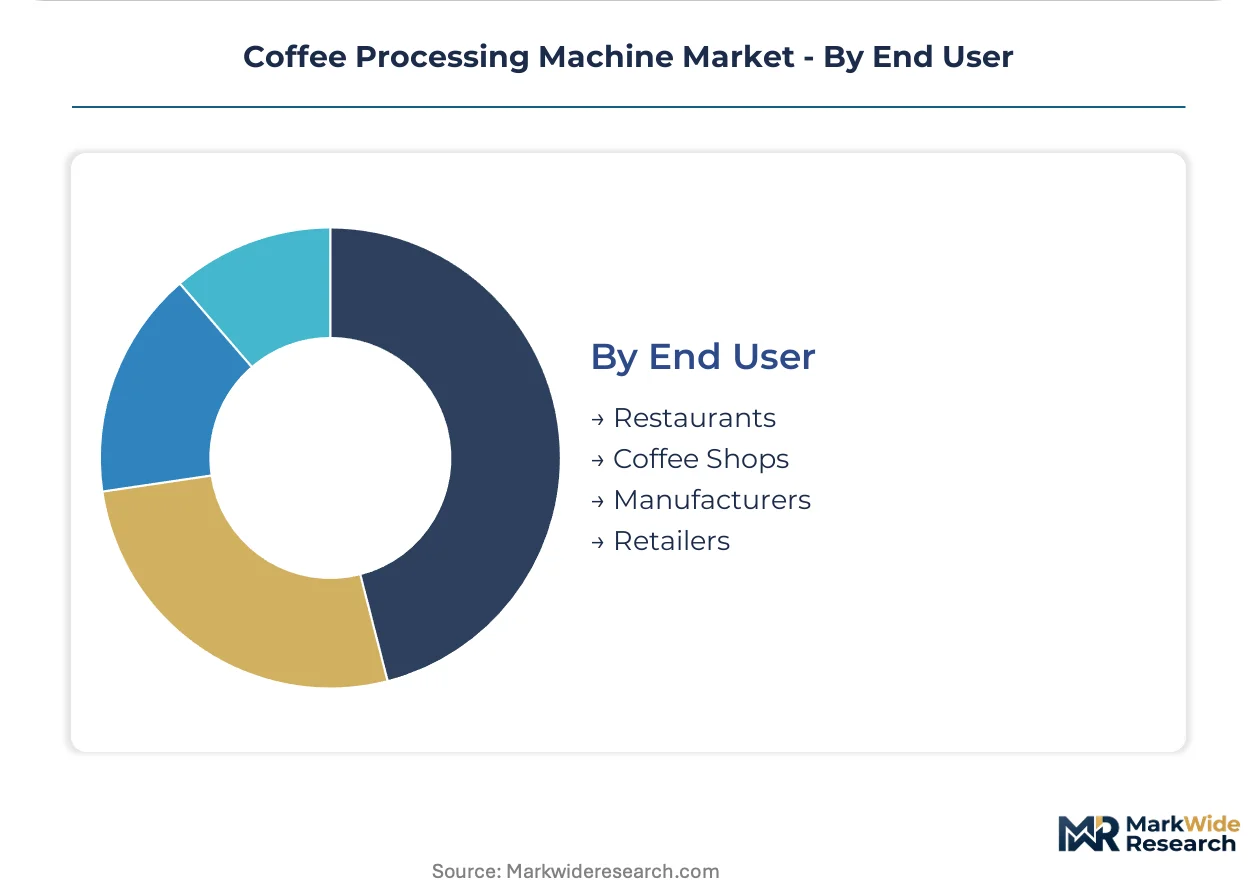
End User:
Procurement authority and financing structures vary sharply across buyer categories, influencing vendor sales approaches and service bundling.
- Manufacturers:Integrated processing lines spanning green bean intake through packaged finished goods. Large-scale roasting operations in Vietnam and Indonesia anchor demand for continuous drum configurations with heat-recovery integration.
- Coffee Shops:Front-of-house brewing equipment with back-of-house roasting capability for premium positioning. Direct vendor relationships now supersede distributor intermediaries in North American urban markets.
- Restaurants:Compact brewing systems with rapid recovery times for beverage menu integration.
- Retailers:Private-label processing investments and in-store demonstration equipment.
Manufacturers command the largest equipment footprint; coffee shops are expanding most quickly through specialty chain proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate Brazilian roasting equipment manufacturing in Amazonas state, while Vietnam's processing zones attract export-oriented green bean investments. Equipment procurement patterns diverge sharply between established consumption markets and emerging production hubs.
Brazil
Domestic café chain expansion and soluble coffee export investments drive parallel equipment procurement channels. ANVISA food-contact material standards govern packaging system imports from European vendors. São Paulo state anchors industrial roasting drum fabrication, with Campinas emerging as a precision grinding assembly cluster serving both local and Argentine buyers.
United States
Specialty chain direct procurement bypasses distributor networks in urban coastal markets. FDA food-contact material standards regulate valve-sealing and nitrogen-flushing packaging components. Seattle and Portland roasting cooperatives deploy cloud-connected drum monitors to synchronize batch profiles across multi-site operations.
Germany
EU Green Deal mandates accelerate commercial kitchen equipment replacement cycles in institutional foodservice. ECHA REACH compliance constrains coating chemistries for roasting drum interiors. Hamburg and Bremen port cities concentrate green bean import logistics, triggering co-located processing investments with heat-recovery system integration.
Vietnam
Robusta processing capacity expansion drives continuous drum configuration demand at export scale. The country's national standards body certifies grinding equipment for ASEAN market re-export eligibility. Dak Lak province's Central Highlands cluster attracts roasting infrastructure investment from soluble coffee manufacturers seeking proximity to raw material sources.
India
BIS certification requirements create import eligibility barriers for European roasting system vendors. FSSAI food safety standards govern brewing equipment materials in hospitality applications. Karnataka's Bangalore-Tumkur corridor hosts emerging specialty café chains specifying semi-automatic grinding units with localized service support.
Coffee Processing Machine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct value capture layers. The vendor base stratifies into three tiers: integrated appliance conglomerates with home-hospitality dual-channel presence, mid-cap roasting specialists serving commercial installations, and precision component fabricators supplying burr assemblies and burner systems. Consolidation pressure concentrates at the mid-tier, where scale advantages in heat-recovery engineering separate sustainable competitors from acquisition targets. Strategic moves center on backward integration into control system software and geographic expansion through CE marking harmonization.
Among Italian-based specialists, De'Longhi S.p.A. and Rancilio Group S.r.l. exemplify the dual-channel archetype spanning residential and commercial segments. Swiss-incorporated Jura Elektroapparate AG occupies a position within the premium automatic tier, representing the software-integrated competitive vector. These three entities anchor distinct strategic postures without overlapping core positioning.
| Leading Market Players |
|---|
| De'Longhi S.p.A. |
| Breville Group Limited |
| Jura Elektroapparate AG |
| Rancilio Group S.r.l. |
| La Marzocco S.r.l. |
| Bunn-O-Matic Corporation |
| Hamilton Beach Brands Holding Company |
| Gaggia S.p.A. |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Specialty café chains with direct vendor procurement relationships command price-setting leverage that favors contract-based long-term offtake over spot market transactions. Their equipment financing alignment with real estate lease structures compresses negotiation cycles and rewards suppliers offering predictable total cost of ownership.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to roasting drum orders from Lombardy-based control system suppliers, while spot inventory of standard grinding burr assemblies trades at modest discounts. The dominant pricing structure runs contract-based with volume-tiered escalators, where CE certification grade and customization level drive price differentiation. Cost compression in mid-cap electric heat-recovery systems is intensifying because nickel alloy input volatility erodes OEM margin buffers. Commercial establishments exhibit highest price sensitivity due to standardized procurement protocols, while specialty shops prioritize specification control over unit economics.
Supply Chain Analysis
CE marking qualification gates European market access for roasting system vendors, creating certification backlog bottlenecks for non-harmonized suppliers. Manufacturing concentrates in Italy for precision burner assemblies, Germany for thermal oxidizer integration, and Brazil for export-oriented drum fabrication serving Argentine buyers. Raw material dependencies center on nickel-chrome alloys for roasting chambers, ceramic burr substrates for grinding units, and fluoropolymer coatings for food-contact surfaces. Single-source vulnerability concentrates in Lombardy-based control system suppliers. Distribution runs through factory-direct relationships for specialty chains and dealer networks for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around heat-recovery engineering capabilities, with EU Green Deal compliance costs forcing acquisition of mid-tier roasting specialists lacking electric system portfolios.
For Market Incumbents: Hedge against stranded gas infrastructure asset risk by accelerating backward integration into control system software and securing captive supply of nickel alloy inputs from Brazilian foundries. Thermal oxidizer integration expertise represents the priority defensive lever against emerging pure-play electric specialists. For New Entrants and Emerging Players: BIS certification in India opens a window for European vendors to capture first-mover advantage in grinding equipment import eligibility gaps. Target Karnataka's Bangalore-Tumkur corridor specialty café chains with semi-automatic units bundled with localized service support, bypassing established dealer hierarchies through direct lease-aligned financing. For Investors and Strategic Acquirers: The window for entry favors mid-cap roasting specialists with incomplete heat-recovery portfolios but established CE marking pathways. Long-term viability hinges on software-integrated control system assets rather than mechanical fabrication scale. Watch for F-Gas Regulation quota reduction acceleration as inflection signal for cold-brew line equipment distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Systems | Software-integrated roasting platforms reduce operator training costs for Jura Elektroapparate AG positioning. |
| CE Marking Harmonization Expansion | Unified conformity assessment reduces cross-border certification friction for De'Longhi S.p.A. vendor networks. |
| Heat-Recovery Technology Licensing | Thermal oxidizer integration enables compliance-plus-efficiency dual positioning against legacy gas architectures. |
| Direct-to-Specialty-Chain Distribution | Factory-floor customization bypasses dealer inventories for Blue Bottle and Intelligentsia procurement teams. |
| Modular Roasting-to-Brewing Platform Launch | Configurable footprints allow Stumptown operators to scale capacity without facility relocation costs. |
Study Parameters
Document review covered SEC filings from Breville Group Limited and De'Longhi S.p.A., EU ECHA REACH regulatory databases, and ANVISA food-contact material standards, complemented by interviews with roasting equipment plant engineers, specialty café procurement directors, and aftermarket service heads. Secondary validation drew from customs trade data for nickel alloy imports, F-Gas Regulation implementation timelines, and BIS certification registries. Bottom-up equipment unit estimates triangulated against top-down market value reconstructions across the projection horizon.
Historical shipment patterns from Brazilian roasting drum fabricators cross-referenced against panel input from European thermal oxidizer integrators anchored the analytical framework. Segmentation dimensions modeled include product type, application tier, automation depth, and regional regulatory cluster. CAGRs derived from slope-consistency tests against input cost trajectories and substitution elasticity parameters for electric versus gas-fired architectures.
The model assumes a particular technology adoption path favoring electric heat-recovery roasting systems; alternative pathways for gas-fired architecture persistence with carbon offset bundling would alter the outlook. Forecasts reflect assumptions about EU Green Deal implementation velocity and nickel alloy price mean-reversion. A model refresh is warranted upon material change in F-Gas Regulation phase-down timelines or Brazilian domestic consumption expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Oceania Commercial Ice Machine Market