
 Food Waste Composting Machine Market | 2026-2036
Food Waste Composting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Food Waste Composting Machine Market Foresight
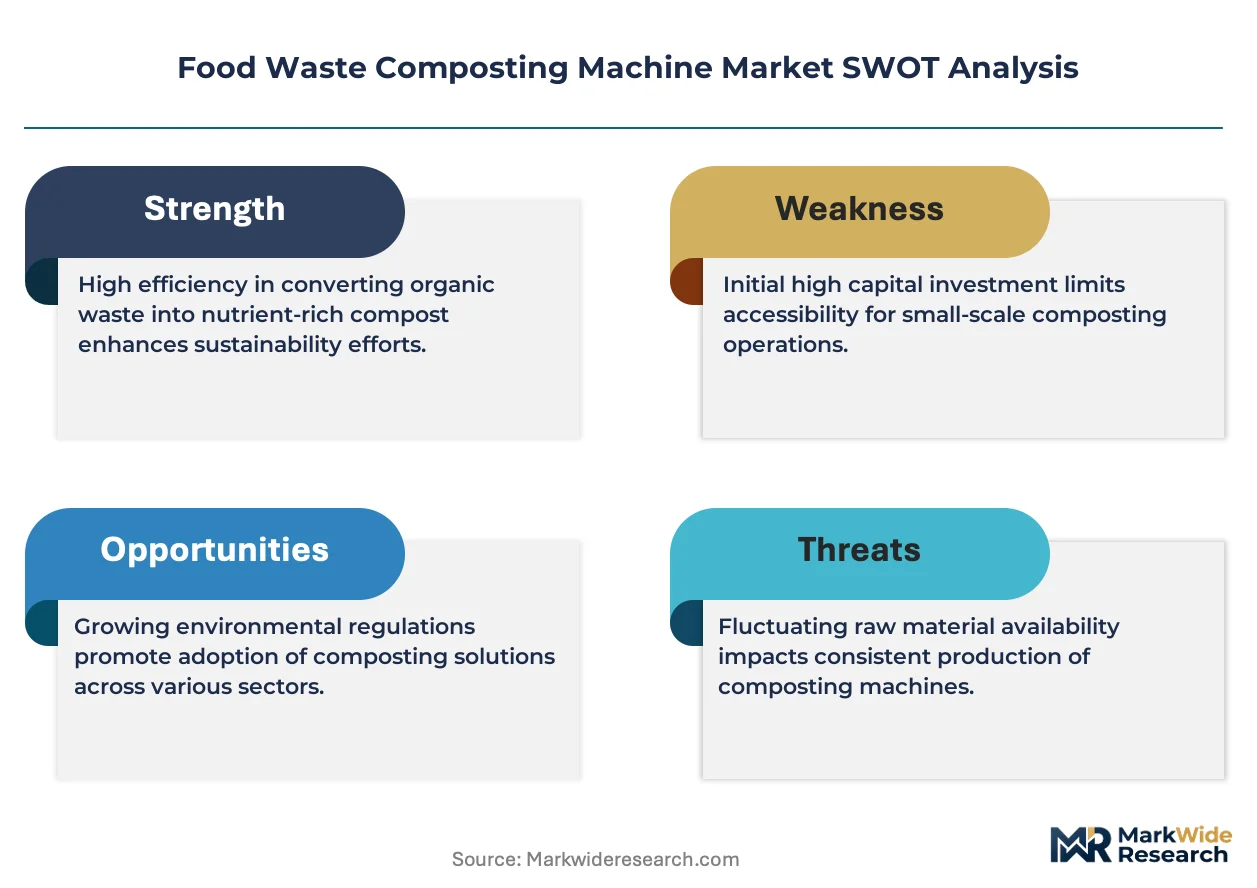
The split between premium in-vessel systems and commodity batch units is hardening as commercial kitchens demand odor-controlled, accelerated-cycle machines while price-sensitive municipal buyers prioritize throughput over precision. ALFA Engineering Solutions leverages its aerobic decomposition expertise to dominate European institutional contracts. Sms Hydrotech Pvt Ltd anchors the Indian market with continuous composters engineered for tropical humidity. TECNO COSTRUZIONI SRL competes on Italian-built mechanical shredding integration that reduces pre-processing labor.
Food waste composting machines are electromechanical or fully automated systems that accelerate organic decomposition through controlled aeration, temperature management, and moisture regulation, typically processing between fifty kilograms and several tons of waste daily. These units serve the core industrial purpose of converting putrescible waste into stabilized humus or soil amendment, eliminating landfill methane emissions and reducing haulage volumes. Continuous composters capture the largest installed base due to their suitability for high-volume food processing units and municipal waste management facilities with steady input streams. In-vessel composters represent the fastest-expanding category as the hospitality sector and educational institutions prioritize enclosed, space-efficient designs that eliminate vector attraction and meet strict local health codes. Aerobic decomposition technology leads unit shipments, though thermophilic composting commands premium pricing for pathogen-reduction certification required by agricultural enterprises.
The EPA's Food Recovery Hierarchy and state-level organic waste bans in California, Massachusetts, and Vermont directly shape demand by mandating diversion timelines and compliance reporting. The EU Waste Framework Directive and F-Gas Regulation on refrigerant-based odor control systems constrain equipment design while accelerating replacement cycles. China's GB standards for compost quality and MEE enforcement of municipal organic waste mandates create a dual compliance threshold for market entry. Stakeholders must monitor how fragmentation between national certification regimes affects cross-border equipment certification costs and aftermarket service scalability.
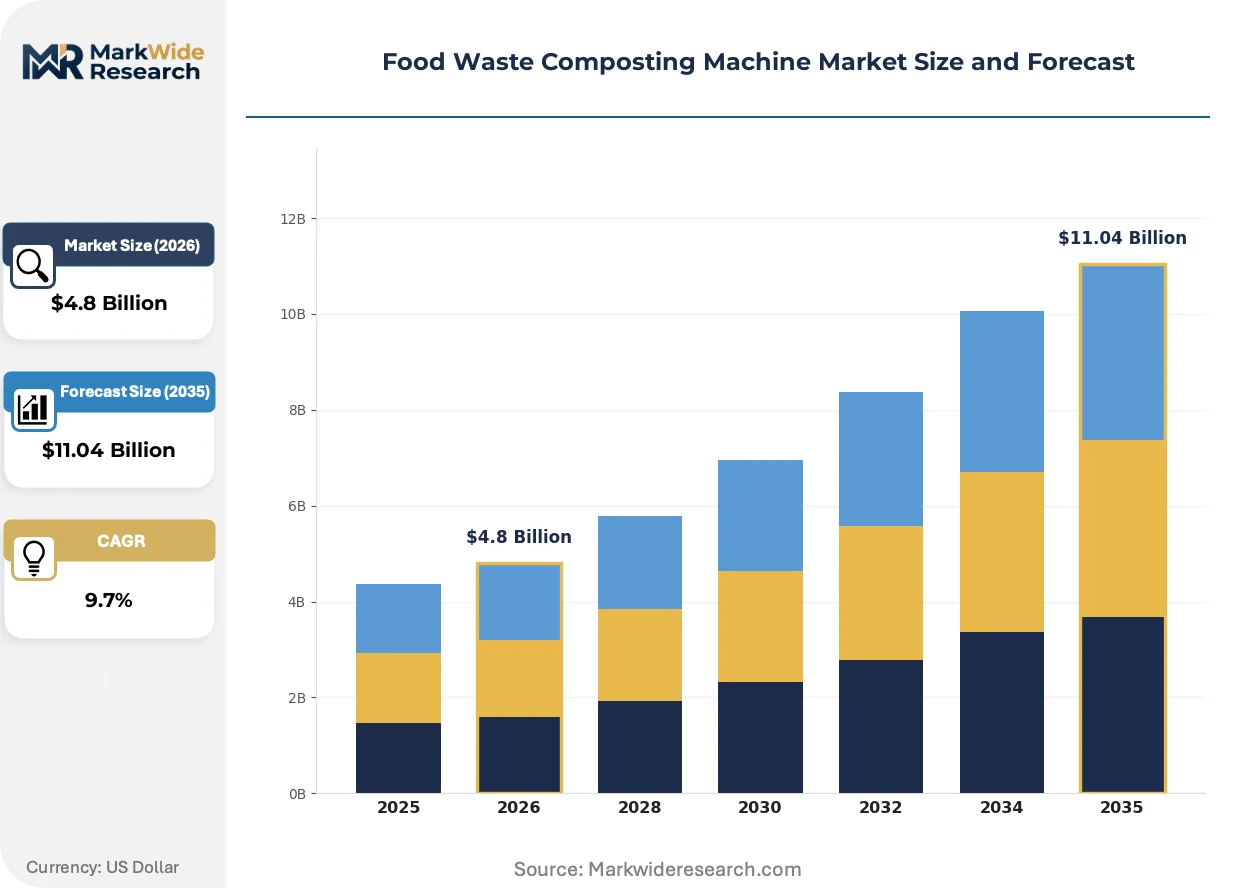
Market Dynamics
The Food Waste Composting Machine Market is bifurcating sharply between premium in-vessel systems and commodity batch units as commercial kitchens demand odor-controlled, accelerated-cycle machines while price-sensitive municipal buyers prioritize throughput over precision. This split is reshaping R&D allocation and channel strategies across manufacturers.
Growth Catalysts
- EU Waste Framework Directive landfill diversion targets:Municipal waste management departments across Germany are expanding procurement of in-vessel systems to meet mandatory organic waste diversion timelines, creating sustained institutional demand for enclosed, high-throughput units.
- Thermophilic composting adoption:South Korea's commercial kitchen sector is displacing slower batch methods with thermophilic systems that achieve pathogen reduction certification required by agricultural offtake agreements.
- China's eastern coastal provinces:Local authorities in Shanghai, Jiangsu, and Zhejiang mandate on-site organic waste processing for large residential complexes, concentrating equipment demand in high-density urban corridors with strict enforcement protocols.
Market Restraints
- Stainless steel and corrosion-resistant alloy input costs:Volatility in nickel and chromium prices compresses margins for manufacturers of continuous composters requiring acid-resistant drum construction, particularly affecting mid-tier suppliers without long-term supply agreements.
- F-Gas Regulation refrigerant constraints:The EU's phasedown of hydrofluorocarbon-based cooling systems for odor control forces redesign cycles and accelerates equipment obsolescence for existing installed base, raising compliance costs for cross-border vendors.
- Biogas anaerobic digestion substitution:Large-scale food processors in Northern Europe increasingly divert organic waste streams to biogas facilities with higher energy recovery yields, constraining addressable market for composting-only equipment in industrial segments.
Strategic Opportunities
- India's tropical humidity engineering gap:Continuous composters optimized for high-moisture, high-temperature climates remain underpenetrated outside Kerala and Tamil Nadu, with northern states lacking localized technical service networks.
- Sensor-integrated predictive maintenance convergence:IoT-enabled moisture and temperature monitoring combined with machine learning algorithms enables remote diagnostics and subscription-based service models, opening recurring revenue streams for OEMs.
- California SB 1383 enforcement expansion:The state's organic waste reduction mandates are cascading to smaller generators previously exempt, extending addressable market to mid-size hospitality and healthcare facilities requiring compact in-vessel solutions.
Industry Challenges
- Electromechanical technician scarcity:Installation and maintenance of automated aeration and temperature control systems requires hybrid skill sets spanning mechanical engineering and PLC programming, with training pipelines lagging equipment deployment in emerging markets.
- Cross-border certification fragmentation:Divergent national standards for compost quality, electrical safety, and emissions testing create redundant testing costs and delay market entry, particularly for European manufacturers targeting Asian procurement tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Waste Composting Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Composters, Continuous Composters, In-vessel Composters, Aerated Static Pile Composters, Tumbler Composters Technology: Aerobic Decomposition, Anaerobic Digestion, Vermicomposting, Thermophilic Composting, Mechanical Shredding Application: Residential Complexes, Educational Institutions, Commercial Kitchens, Municipal Waste Management, Food Processing Units End User: Waste Management Companies, Hospitality Sector, Agricultural Enterprises, Local Authorities |
| Companies Covered | ALFA Engineering Solutions, Sms Hydrotech Pvt Ltd, TECNO COSTRUZIONI SRL, TOPMAKE ENVIRONMENT GROUP CO.,LTD, Aakaar Industries, EARTH CARE EQUIPMENTS PVT. LTD, DCC Group, GEME, Bincrusher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Waste Composting Machine Market Shifts & Advancements
Electrification of core decomposition functions is compressing cycle times and enabling precision control previously unattainable with passive aeration. Three convergent developments are redefining equipment architecture and buyer value propositions.
Electrohydraulic shredder-preprocessor integration is electrifying the front-end of composting workflows by replacing batch-fed manual loading with continuous, sensor-guided particle size reduction. High-volume food processing units in the Netherlands and Denmark are adopting these systems to eliminate pre-sorting labor and accelerate thermophilic phase initiation. This convergence is compressing total processing cycles from fourteen days to under seventy-two hours for homogeneous organic streams.
The F-Gas Regulation's refrigerant phase-down is forcing odor control system redesign across European-manufactured equipment. Manufacturers are pivoting to activated carbon and biofilter alternatives, raising unit costs but eliminating compliance risk and service complexity for municipal buyers. Italian and German vendors are most exposed given their historical reliance on closed-loop cooling for enclosed in-vessel designs.
Leasing and equipment-as-a-service models are displacing capital purchase in North American commercial kitchen segments. Foodservice management companies operating multi-site contracts prefer bundled maintenance and consumable supply agreements that transfer operational risk to OEMs. This shift is most visible in California and Massachusetts where organic waste ban compliance deadlines create urgency and budget constraints simultaneously.
Food Waste Composting Machine Market Segmentation
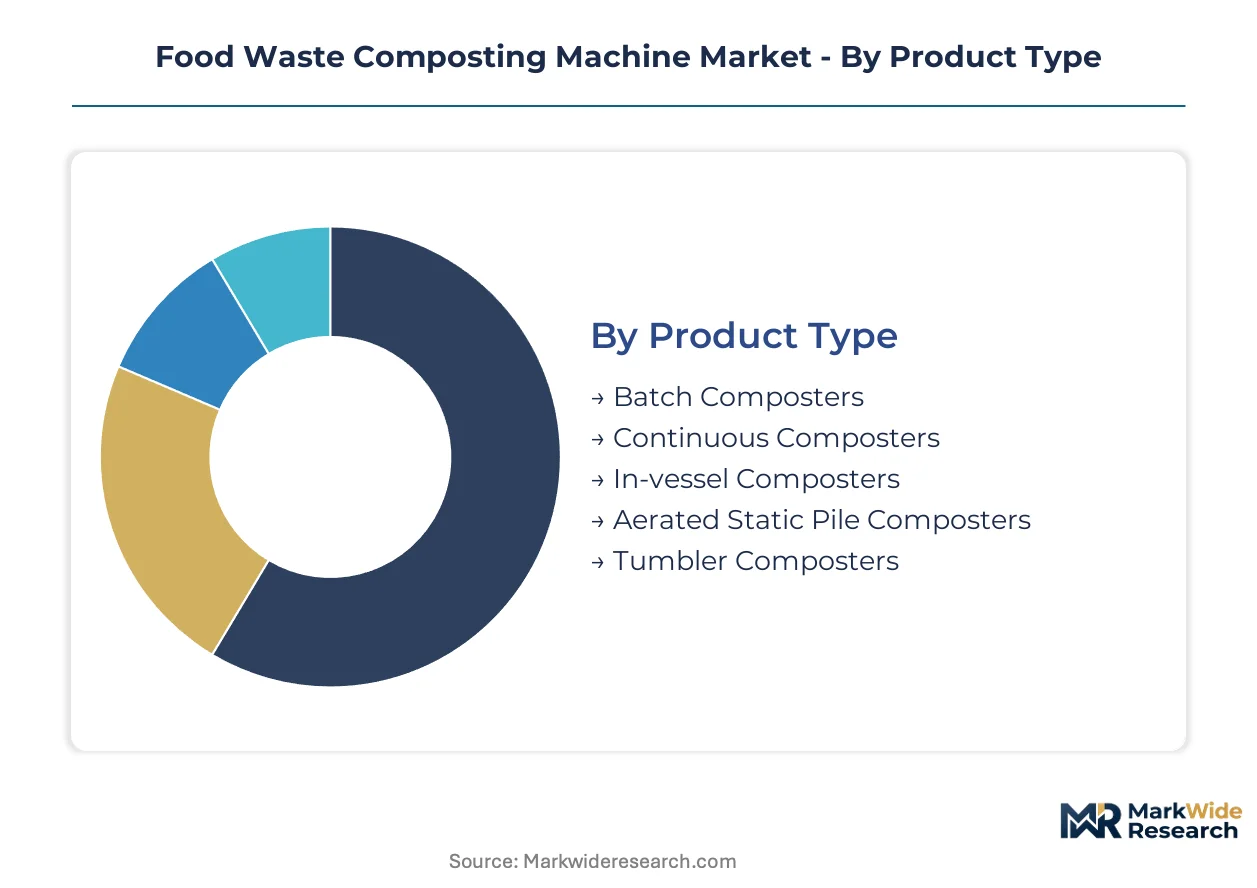
Equipment selection in the Food Waste Composting Machine Market hinges on waste stream volume consistency, space constraints, and regulatory compliance tier. Buyers weigh capital recovery periods against operational labor requirements and odor control mandates.
Product Type:
Procurement patterns diverge sharply between municipal buyers prioritizing throughput and commercial operators demanding accelerated cycle precision.
- Continuous Composters:These systems process waste through rotating drums or conveyor-fed chambers with automated aeration and moisture control, enabling steady-state operation for facilities with predictable daily input. Demand concentrates in Germany's municipal waste departments under EU Waste Framework Directive landfill diversion timelines, where 24/7 operation justifies higher capital outlay.
- In-vessel Composters:Fully enclosed units with integrated temperature and odor management systems occupy minimal footprint while eliminating vector attraction risks. South Korea's commercial kitchen sector favors these for pathogen reduction certification required by agricultural offtake agreements, displacing slower batch alternatives.
- Batch Composters:Simpler drum or bin designs process discrete waste loads on fixed cycles, appealing to price-sensitive buyers with intermittent waste streams.
- Aerated Static Pile Composters:Open or covered windrow systems with forced aeration suit large-scale food processing units with ample land availability.
- Tumbler Composters:Manual or motorized rotating drums serve small-scale residential and educational applications with limited daily waste volumes.
Continuous composters lead on scale; in-vessel composters lead on momentum.
Technology:
Technology selection tracks end-use certification requirements and climate adaptation needs.
- Aerobic Decomposition:Oxygen-driven microbial breakdown through forced aeration dominates unit shipments across temperate climates, with equipment optimized for controlled temperature and moisture parameters.
- Thermophilic Composting:High-temperature aerobic processes achieving sustained heat above 55 degrees Celsius for pathogen destruction command premium pricing from agricultural enterprises requiring sanitized output for crop application.
- Anaerobic Digestion:Oxygen-excluded biogas generation captures energy value but requires separate digestate composting stages, limiting pure composting equipment demand.
- Vermicomposting:Earthworm-mediated decomposition produces fine-grade castings for specialty soil amendment markets with strict quality specifications.
- Mechanical Shredding:Pre-processing particle size reduction accelerates subsequent biological phases, with Italian-built integration systems reducing labor inputs.
Aerobic decomposition dominates installed base; thermophilic composting climbs the fastest on certification premiums.
Application:
Application-driven demand reflects divergent enforcement intensity and space availability across buyer categories.
- Municipal Waste Management:City and county facilities processing mixed organic streams from residential and commercial sources require high-throughput continuous systems with contamination tolerance. Germany's landfill diversion procurement waves anchor this segment's volume.
- Commercial Kitchens:Restaurants, hotels, and institutional foodservice operations prioritize compact in-vessel designs with odor control for dense urban placement, with South Korea's sector leading thermophilic adoption.
- Residential Complexes:Large multi-unit buildings in China's eastern coastal provinces face mandatory on-site processing requirements, driving demand for space-efficient automated units.
- Educational Institutions:Schools and universities combine waste processing with sustainability curriculum, favoring visible batch or tumbler systems.
- Food Processing Units:Manufacturing facilities with homogeneous organic byproduct streams achieve fastest cycle times through integrated shredder-composter combinations.
Municipal waste management leads on scale; commercial kitchens lead on momentum.
End User:
End-user procurement authority determines specification stringency and service contract structure.
- Waste Management Companies:Private and public operators with long-term municipal contracts specify equipment for durability and throughput, with German procurement tenders setting regional standards.
- Local Authorities:Government entities with direct operational responsibility favor enclosed systems meeting strict health codes, particularly in China's enforcement-heavy eastern provinces.
- Hospitality Sector:Hotel and restaurant chains under California SB 1383 compliance pressure seek leasing models bundling equipment and service to transfer operational risk.
- Agricultural Enterprises:Farms and cooperatives purchasing compost output demand thermophilic-certified equipment guaranteeing pathogen elimination for food safety compliance.
Waste management companies lead on scale; hospitality sector leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal procurement waves contrast with India's tropical humidity engineering gap, revealing how regulatory enforcement intensity and climate adaptation requirements reshape equipment specifications across geographies.
United States
California's SB 1383 enforcement cascade and Massachusetts organic waste bans drive mid-size hospitality and healthcare procurement. EPA Food Recovery Hierarchy compliance deadlines compress capital recovery timelines for buyers. Equipment demand concentrates in Los Angeles and Boston corridors where haulage cost savings justify premium in-vessel systems.
Germany
North Rhine-Westphalia and Bavaria municipal waste departments expand in-vessel procurement under EU Waste Framework Directive landfill diversion targets. F-Gas Regulation refrigerant constraints force odor control system redesigns among domestic manufacturers. Berlin-Brandenburg procurement tenders set throughput standards across Central European institutional buyers.
China
Shanghai, Jiangsu, and Zhejiang authorities mandate on-site organic waste processing for large residential complexes under MEE enforcement protocols. GB standards for compost quality create dual compliance thresholds for market entry. Yangtze River Delta equipment demand concentrates in high-density urban corridors with strict diversion enforcement.
South Korea
Commercial kitchen operators in Seoul Capital Area displace batch methods with thermophilic systems for agricultural offtake certification. MFDS-aligned pathogen reduction requirements command premium pricing from foodservice buyers. Busan-Ulsan manufacturing clusters supply accelerated-cycle equipment optimized for urban space constraints.
India
Kerala and Tamil Nadu continuous composters face underpenetration in northern states lacking localized service networks. BIS certification requirements and tropical humidity engineering gaps constrain vendor expansion. Maharashtra and Karnataka urban local bodies pilot on-site mandates for large residential generators.
Food Waste Composting Machine Market Competitive Landscape
Top-tier vendors anchor premium in-vessel and thermophilic segments, while mid-tier fabricators compete on throughput metrics for municipal procurement. The vendor base stratifies across three archetypes: European engineering specialists with aerobic decomposition expertise, Asia-Pacific scale manufacturers optimized for tropical climates, and Italian mechanical integration houses. Consolidation pressure intensifies as cross-border certification costs favor established players with compliance infrastructure. Strategic moves concentrate on sensor-integrated predictive maintenance convergence and leasing model expansion to capture recurring revenue streams.
Among European engineering specialists, ALFA Engineering Solutions represents the institutional contract archetype with aerobic decomposition system expertise. Sms Hydrotech Pvt Ltd anchors the tropical climate adaptation tier with continuous composter engineering for high-moisture environments. TECNO COSTRUZIONI SRL exemplifies mechanical shredding integration specialization that reduces pre-processing labor inputs. These three occupy distinct positioning vectors—regulatory compliance depth, climate-specific engineering, and front-end automation integration—rather than competing head-to-head on identical specifications.
| Leading Market Players |
|---|
| ALFA Engineering Solutions |
| Sms Hydrotech Pvt Ltd |
| TECNO COSTRUZIONI SRL |
| TOPMAKE ENVIRONMENT GROUP CO.,LTD |
| Aakaar Industries |
| EARTH CARE EQUIPMENTS PVT. LTD |
| DCC Group |
| GEME |
| Bincrusher |
| Others |
Supply & Pricing Matrix
Nickel and chromium price volatility cascades through stainless steel drum fabrication costs, compressing margins for continuous composter manufacturers while forcing tiered pricing stratification between acid-resistant alloy specifications and standard carbon steel alternatives. Municipal procurement tenders in Germany and commercial kitchen contracts in South Korea now explicitly weight corrosion-grade material certifications in total cost of ownership calculations.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for mid-tier batch composters, intensifying cost compression for commodity equipment while thermophilic in-vessel systems command certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates EU F-Gas compliant odor control configurations from activated carbon alternatives and basic passive aeration designs. Price differentiation hinges on pathogen-reduction certification tier and after-sales service bundling. Municipal buyers in India exhibit highest price sensitivity due to decentralized procurement authority, while agricultural enterprises in South Korea absorb premium pricing for MFDS-aligned thermal processing guarantees.
Supply Chain Analysis
CE marking and BIS certification gating concentrates qualified supply among Italian, German, and select Indian fabricators with established testing laboratory relationships. Manufacturing gravity centers on Germany for precision in-vessel engineering, Italy for mechanical shredding integration, and India for tropical-climate continuous drum adaptations. Raw material dependencies span nickel-chromium alloys from South African ore processing, PLC control systems from Japanese automation suppliers, and corrosion-resistant coatings from German chemical specialists. Single-source vulnerability in semiconductor-based temperature controllers creates procurement risk for OEMs lacking multi-vendor qualification. Distribution runs through municipal tender consultants in Europe, foodservice equipment dealers in North America, and direct government contracting channels in China's eastern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in thermophilic certification tiers and sensor-integrated service subscriptions, with electromechanical technician scarcity creating pricing power for OEMs with captive training infrastructure.
For Market Incumbents: Deploy predictive maintenance platform rollouts to capture recurring revenue streams and lock in municipal contract renewals. Biogas anaerobic digestion substitution in Northern Europe threatens pure composting equipment demand, requiring backward integration into digestate post-processing or hybrid system development. ALFA Engineering Solutions and comparable European specialists should deepen aerobic decomposition R&D to maintain institutional contract dominance against Asian cost competition. For New Entrants and Emerging Players: Sensor-integrated remote diagnostics capabilities offer the most penetrable wedge for displacing established service networks in India's northern states. Kerala and Tamil Nadu equipment saturation contrasts with Maharashtra and Karnataka pilot mandates, creating geographic white space for localized technical service investment. California SB 1383 compliance urgency among mid-size hospitality generators favors leasing-model entrants with bundled consumable supply agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with tropical-climate engineering specialists possessing BIS certification and established northern India service infrastructure. Five-to-ten year viability favors vendors with sensor-integrated predictive maintenance convergence and equipment-as-a-service model traction. Watch for MFDS-aligned pathogen certification adoption velocity in South Korea's commercial kitchen sector as inflection indicator for premium tier demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Predictive Maintenance Platform | IoT-enabled remote diagnostics transform OEM economics through subscription recurring revenue in California compliance corridors. |
| Backward Integration into Corrosion-Resistant Alloy Fabrication | In-house drum manufacturing insulates margin from nickel price volatility affecting German continuous composter suppliers. |
| Leasing and Equipment-as-a-Service Model Expansion | Bundled maintenance agreements transfer operational risk from Massachusetts hospitality buyers to OEM balance sheets. |
| Thermophilic Certification Investment | MFDS-aligned pathogen reduction capabilities unlock agricultural offtake premiums in South Korea's foodservice sector. |
| Tropical Climate Engineering Localization | High-moisture continuous composter adaptation captures Maharashtra and Karnataka municipal procurement outside Kerala-Tamil Nadu saturation. |
Research Methodology
Bottom-up municipal and commercial kitchen procurement modeling reconciled against top-down equipment shipment tracking forms the analytical core. Primary interviews with municipal waste department procurement officers, commercial kitchen operations managers, OEM technical sales directors, and aftermarket service technicians combined with secondary validation from EU Waste Framework Directive implementation reports, EPA Food Recovery Hierarchy compliance databases, and China MEE enforcement disclosure filings. Trade flow analysis of stainless steel alloy inputs and PLC controller import records provided supply-side triangulation against demand-side tender documentation.
Input-output matrices mapped waste stream volume distributions across application segments against equipment throughput specifications, with CAGRs derived from regression of historical procurement waves against regulatory deadline enforcement intensity. Segmentation dimensions modeled include product type architecture, thermophilic versus aerobic technology tier, municipal versus commercial application, and end-user procurement authority structure. Forecast inputs incorporated F-Gas Regulation phase-down compliance cost assumptions and India's BIS certification pipeline constraints.
The model holds under sustained regulatory enforcement intensity; deviation in EU landfill diversion timeline extensions or China MEE mandate relaxation would shift equipment replacement cycle assumptions. Forecasts reflect documented procurement patterns and certification infrastructure development trajectories. A model refresh is warranted upon material change in nickel-chromium alloy price volatility or MFDS pathogen certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Brewery Heat Exchanger Market