
 Europe School Furniture Market | 2026-2036
Europe School Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe School Furniture Market Intelligence
Buyer concentration among European public procurement consortia is expanding as municipalities pool purchasing power through framework agreements. Steelcase Inc. leverages its pan-European distribution network to serve these consolidated buyers. MillerKnoll, Inc. anchors its position through R&D intensity in ergonomic seating systems. VS America, Inc. specializes in height-adjustable desk solutions tailored to continental classroom standards.
Europe school furniture encompasses desks, chairs, tables, and storage units engineered for durability, ergonomic support, and compliance with EN 1729 dimensional standards for educational seating. Manufacturers typically employ steel tube framing with laminate or solid wood surfaces, powder-coated for abrasion resistance in high-traffic institutional environments. The wood material segment dominates current procurement volumes across primary and secondary schools, while composite materials represent the fastest-growing category as institutions seek lighter, recyclable alternatives. The vocational training end-user segment commands premium margin pools due to specialized workshop and laboratory furniture requirements.
The EU Green Deal and Ecodesign for Sustainable Products Regulation mandate recycled content thresholds and restrict hazardous substances in furniture sold to public institutions. CE marking under the Construction Products Regulation and national fire safety standards such as Germany's DIN 4102 further shape product compliance burdens. REACH compliance on chemical substances in coatings and adhesives adds testing costs that favor larger manufacturers with dedicated regulatory teams. Stakeholders must monitor evolving ECHA restrictions on flame retardants and anticipate how the EU AI Act might influence smart furniture with embedded occupancy sensors in future procurement cycles.
Market Dynamics
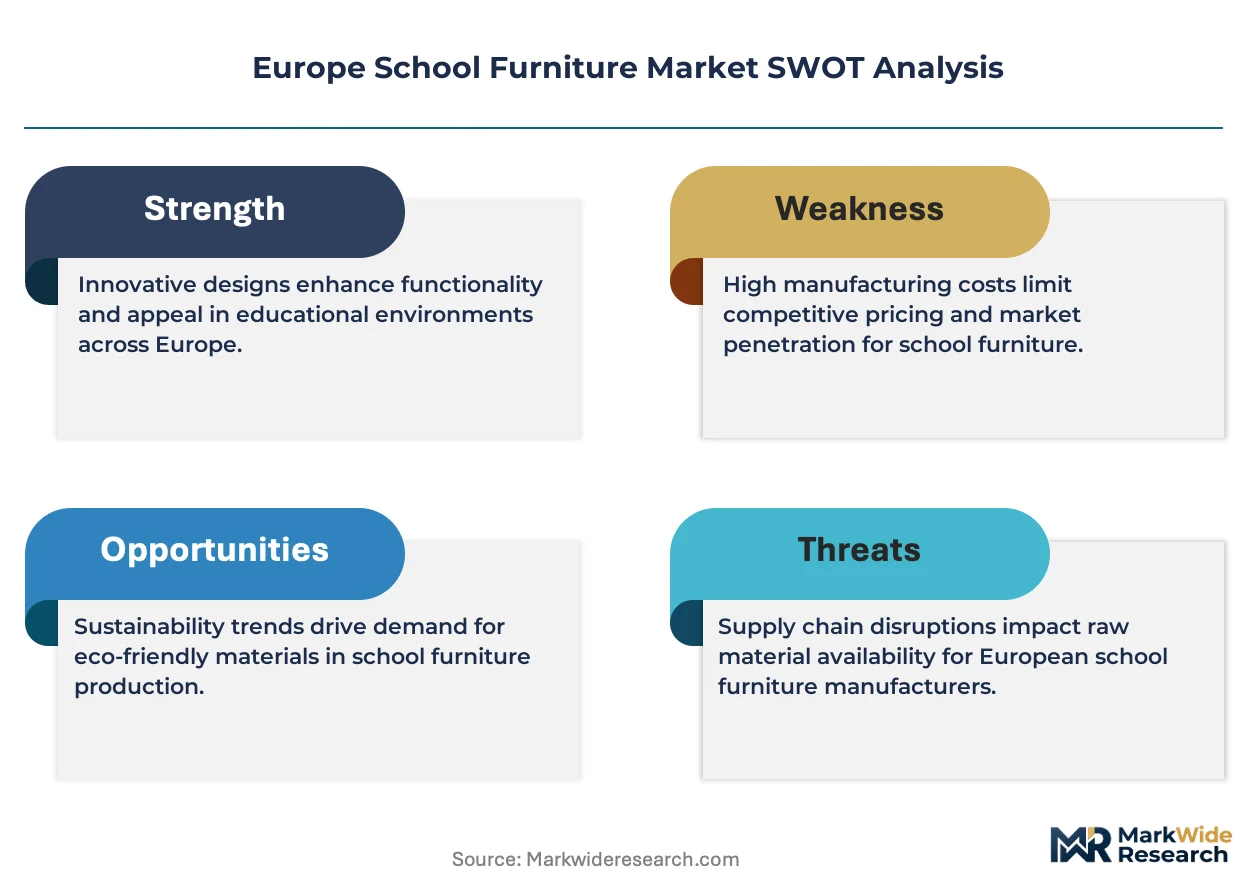
Public procurement consolidation across German federal states and Nordic municipalities is compressing vendor margins while elevating compliance requirements under the EU Green Deal's recycled content mandates.
Growth Catalysts
- EU Green Deal procurement mandates:Public institutions must source furniture meeting Ecodesign for Sustainable Products Regulation thresholds, redirecting volume toward certified manufacturers with established circular supply chains.
- Vocational training expansion:Workshop and laboratory furniture for technical institutes commands premium specifications, with Germany's dual education system driving specialized workstation demand.
- Ergonomic standards adoption:EN 1729 dimensional compliance is modularizing classroom configurations as schools replace fixed-height legacy installations with height-adjustable systems.
Market Restraints
- Steel and engineered wood input volatility:Laminate surface substrates and powder-coated steel tube framing face cost pressure from energy-intensive European manufacturing.
- REACH compliance burden:ECHA restrictions on flame retardants and coating adhesives extend certification timelines, favoring incumbents with dedicated regulatory teams over smaller competitors.
- Consolidated buyer power:Framework agreements pooling municipalities across multiple German Länder compress margin structures and extend payment terms.
Strategic Opportunities
- Eastern European infrastructure modernization:Poland and Romania are deploying EU cohesion funds to replace aging Soviet-era school furniture with ergonomic systems.
- Smart furniture sensor integration:Occupancy monitoring and air quality measurement converge in desk-embedded IoT, anticipating EU AI Act procurement guidelines for connected institutional assets.
- Circular service models:Take-back and refurbishment programs align with CSRD disclosure requirements, creating recurring revenue streams from public sector maintenance budgets.
Industry Challenges
- Skilled installer shortage:Height-adjustable desk deployment requires certified technicians familiar with EN 1729 calibration protocols, constraining rollout velocity.
- Multi-standard certification complexity:CE marking under Construction Products Regulation must align with Germany's DIN 4102 fire safety and national building codes, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe School Furniture Market |
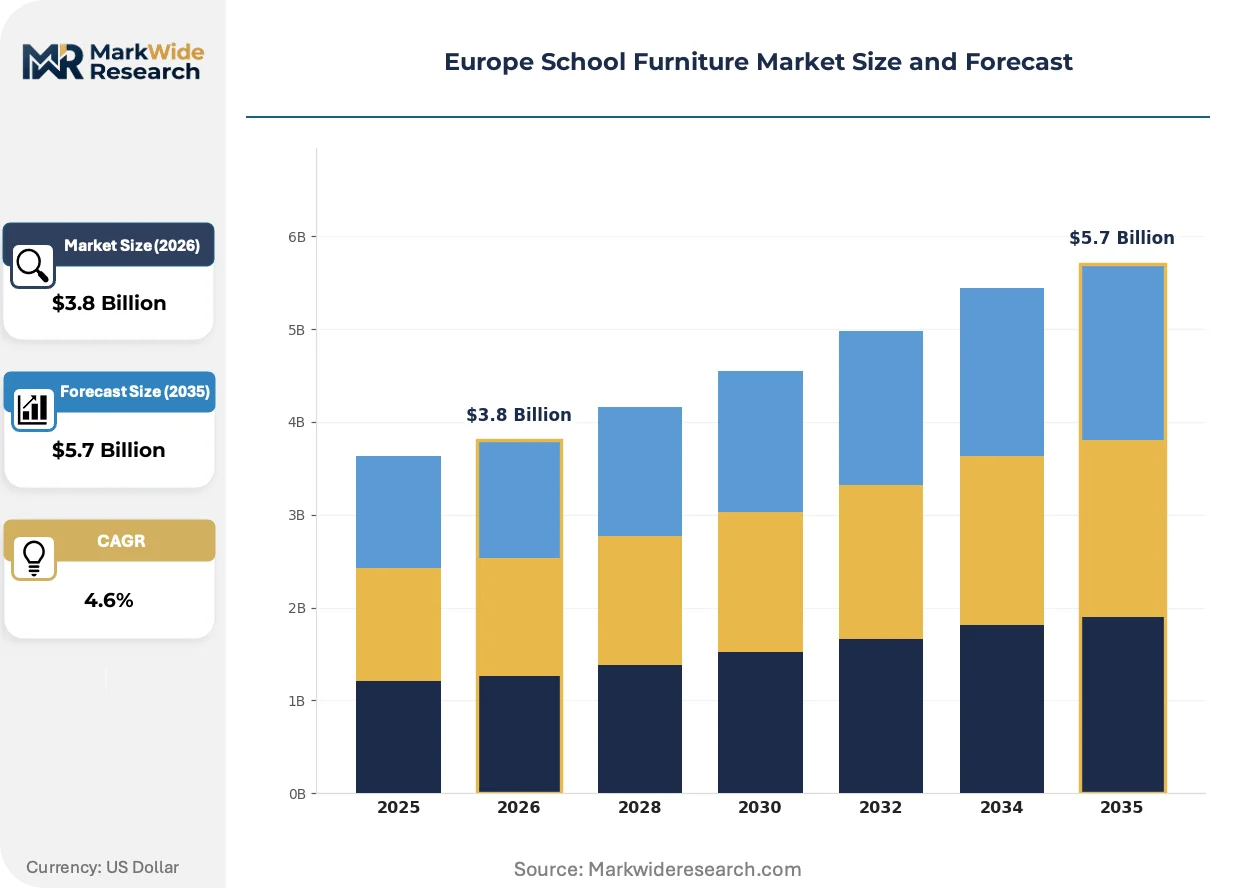
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Wood, Metal, Plastic, Composite End User: Primary Schools, Secondary Schools, Higher Education, Vocational Training Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Steelcase Inc., Hertz Furniture, MillerKnoll, Inc., VS America, Inc., Fleetwood Group, Herman Miller, Inc., KI Furniture, Knoll, Inc., HNI Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe School Furniture Market Strategic Shifts & Innovations
European school furniture is pivoting from static commodity supply toward adaptive systems responding to pedagogical methodology shifts and embedded sustainability verification.
Composite material engineering is modularizing product architectures across vocational and general education segments. Lightweight recyclable alternatives to solid wood and laminate surfaces are gaining specification share in Nordic and German procurement cycles. Manufacturers are compressing logistics costs and enabling flat-pack distribution to decentralized school locations through reduced material density.
REACH chemical restrictions and the EU AI Act are reshaping compliance investment priorities. ECHA's evolving flame retardant limitations require reformulation of coatings and adhesives, extending R&D cycles. Smart furniture with embedded occupancy sensors faces emerging algorithmic transparency requirements, prompting early-mover manufacturers to establish data governance protocols ahead of enforcement timelines.
Framework agreement concentration is altering competitive access patterns. Municipal consortia in Germany, the Netherlands, and Denmark are consolidating purchasing power through multi-year contracts, displacing spot-market transactions. Specialized vendors are establishing dedicated public sector sales functions to navigate extended tender cycles and technical specification compliance.
Europe School Furniture Market Segmentation
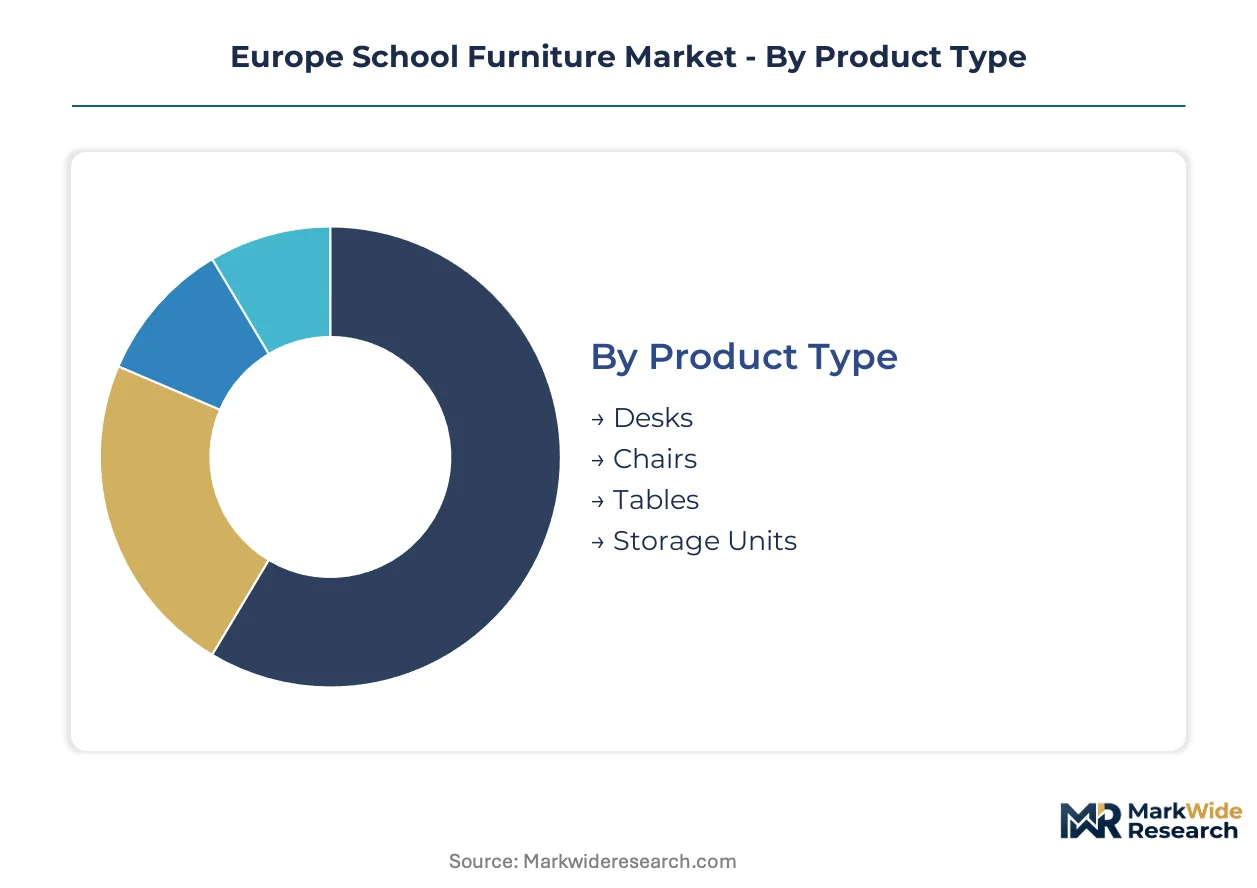
Segmentation in the Europe school furniture market reveals how procurement priorities diverge across institutional tiers and material specifications. Procurement consortia weight durability, compliance certification, and total cost of ownership differently depending on end-user category and distribution pathway.
Product Type:
Capital intensity peaks in storage unit manufacturing, where steel fabrication and powder-coating infrastructure demand the heaviest upfront investment. Seating systems require specialized ergonomic testing equipment but lower fixed asset deployment.
- Desks:Height-adjustable configurations with steel tube framing and laminate surfaces dominate German and Nordic procurement cycles. EN 1729 dimensional compliance drives modular replacement of fixed-height legacy installations in federal state modernization programs.
- Chairs:Ergonomic seating systems integrate polypropylene shells with cantilever steel bases. MillerKnoll and VS America compete on lumbar support adjustability and stackability for space-constrained classrooms.
- Tables:Collaborative learning formats with castor-mounted trapezoidal tops enable rapid classroom reconfiguration. Demand concentrates in Dutch and Danish primary schools adopting flexible pedagogical layouts.
- Storage Units:Steel locker systems and mobile shelving require substantial welding and coating capacity. Workshop-grade storage commands premium specifications in Germany's vocational training institutes.
Most installed capacity flows through desks. Expansion is steepest in chairs as ergonomic standards displace commodity seating.
Material:
Raw material procurement strategies separate cost-competitive volume players from premium specification vendors. Wood sourcing requires sustainable forest certification chains, while composite development demands polymer chemistry expertise.
- Wood:Solid beech and birch plywood with FSC or PEFC certification satisfy EU Green Deal procurement mandates. German federal states specify wood for primary school installations, prioritizing tactile warmth and repairability.
- Metal:Powder-coated steel tube framing provides structural durability for high-traffic institutional environments. Energy-intensive European manufacturing faces input cost pressure from electricity pricing volatility.
- Plastic:Injection-molded polypropylene shells offer lightweight stackability and color customization. Recycled content thresholds under Ecodesign for Sustainable Products Regulation favor vendors with established circular supply chains.
- Composite:Engineered materials combining wood fiber with thermoplastic binders reduce material density for flat-pack logistics. Nordic municipalities specify composites for remote school locations where transport costs dominate.
Wood maintains the largest installed base. Composite materials are gaining share fastest as recyclability specifications tighten.
End User:
Budget authority and procurement sophistication vary sharply across educational tiers. Vocational training institutes command specialized technical specifications, while primary schools prioritize durability and safety certification.
- Primary Schools:Furniture scaled to younger students requires rounded edges, anti-tip stability, and non-toxic finishes. German Länder framework agreements consolidate volume for standardized classroom packages.
- Secondary Schools:Science laboratory benches and art room tables demand chemical-resistant surfaces and integrated services distribution. Poland deploys EU cohesion funds to replace aging Soviet-era installations.
- Higher Education:Lecture hall seating and collaborative learning furniture emphasize technology integration and aesthetic differentiation. Campus procurement teams specify design-forward solutions for student recruitment.
- Vocational Training:Workshop benches, welding stations, and laboratory casework require heavy-duty steel construction and specialized ergonomic adaptations. Germany's dual education system sustains premium demand for certified industrial furniture.
Vocational training captures the highest margin pools. Primary schools represent the largest volume segment.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth. Direct engagement with procurement consortia requires dedicated public sector sales infrastructure.
- Direct Sales:Steelcase and larger manufacturers maintain field teams for framework agreement negotiation and technical specification compliance. Extended tender cycles demand sustained relationship investment.
- Distributors:Regional specialists stock standardized products for rapid fulfillment of smaller municipal orders. Inventory carrying costs favor vendors with pan-European warehouse networks.
- Online Retail:E-procurement platforms serve individual schools with limited purchasing autonomy. Transaction sizes remain constrained by public sector procurement regulations.
- Wholesale:Volume aggregators supply contractor-led new build projects across Eastern European markets. Price competition intensifies as Romanian and Polish construction activity accelerates.
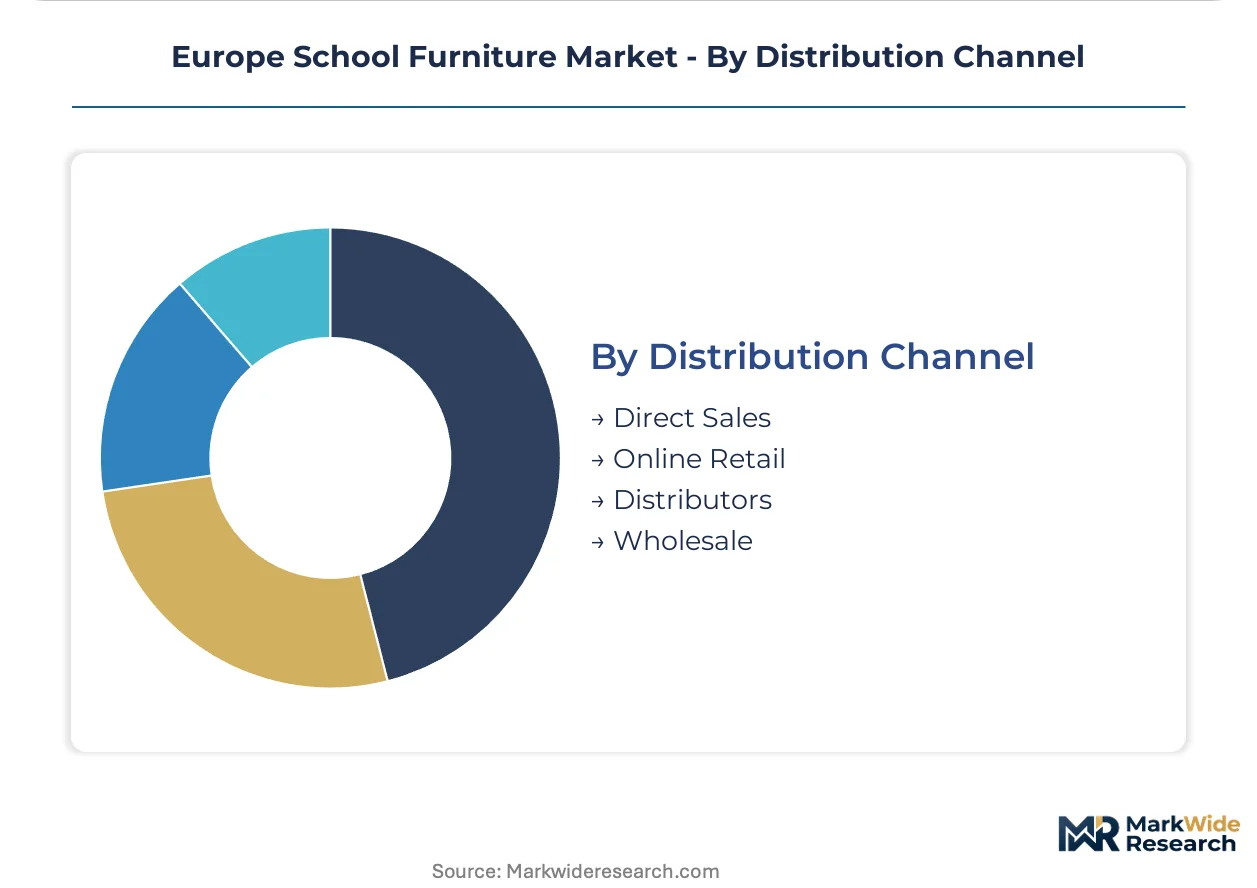
Direct sales channels capture the highest value contracts. Distributor networks are expanding most quickly in Eastern European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys heavier procurement volumes than France, yet both markets operate under divergent federal frameworks that reshape vendor access patterns and compliance timelines.
Germany
Individual federal states (Länder) pool purchasing power through framework agreements for ergonomic furniture modernization. The EU Green Deal mandates recycled content thresholds for public procurement. North Rhine-Westphalia and Bavaria concentrate demand for height-adjustable desk systems in vocational training institutes.
France
Regional education authorities (académies) coordinate replacement of aging primary school installations. ANSM and CNIL guidance shapes data governance for connected furniture pilots. The Île-de-France and Auvergne-Rhône-Alpes clusters drive specification adoption for collaborative learning table formats.
Netherlands
Municipal consortia consolidate procurement for flexible classroom configurations supporting pedagogical innovation. REACH compliance on coating adhesives extends vendor qualification periods. The Randstad region anchors demand for castor-mounted trapezoidal tables in primary education.
Poland
EU cohesion funds finance replacement of Soviet-era school infrastructure with EN 1729-compliant systems. National fire safety standards align with CE marking under Construction Products Regulation. Warsaw and Kraków metropolitan areas concentrate deployment of science laboratory furniture in secondary schools.
Sweden
Nordic municipalities prioritize circular service models with take-back and refurbishment provisions. Ecodesign for Sustainable Products Regulation drives composite material specification for remote school locations. The Stockholm-Uppsala corridor leads adoption of lightweight recyclable alternatives to solid wood surfaces.
Europe School Furniture Market Key Industry Players
North American producers anchor one tier with pan-European distribution infrastructure; German and Austrian specialists hold position through modular engineering depth calibrated to EN 1729 standards. The vendor base separates into three strategic archetypes: scale-driven manufacturers serving consolidated procurement consortia, ergonomic R&D-intensive seating specialists, and regional fabricators capturing spot-market municipal orders. Competitive moves concentrate on framework agreement negotiation capacity and circular supply chain certification under EU Green Deal mandates.
Among North American-based manufacturers, Steelcase Inc. and MillerKnoll, Inc. occupy positions defined by public sector sales infrastructure and ergonomic seating development intensity. VS America, Inc. represents the specialist archetype with concentrated positioning in height-adjustable desk solutions. These three entities exemplify how geographic origin and product-category focus map to distinct competitive access patterns in European institutional procurement.
| Leading Market Players |
|---|
| Steelcase Inc. |
| Hertz Furniture |
| MillerKnoll, Inc. |
| VS America, Inc. |
| Fleetwood Group |
| Herman Miller, Inc. |
| KI Furniture |
| Knoll, Inc. |
| HNI Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between EU Green Deal-compliant systems and legacy commodity furniture manifests in divergent margin structures and sourcing footprints across European procurement tiers. Premium vendors capture pricing power through circular supply chain investments that satisfy Ecodesign for Sustainable Products Regulation thresholds, while commodity producers face margin compression from energy-intensive steel fabrication and laminate substrate costs.
Pricing Analysis
Capacity additions in Eastern European manufacturing hubs are reshaping price floors for standardized desk and seating systems. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominates framework agreement negotiations. Price differentiation hinges on FSC/PEFC certification grade and EN 1729 dimensional compliance tier. Cost compression in the economy tier is intensifying because Polish and Romanian producers leverage EU cohesion fund-backed volume contracts. Primary schools exhibit highest price sensitivity, while vocational training institutes show lowest sensitivity due to specialized workshop furniture requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian engineered wood suppliers serving premium certification tiers. Manufacturing concentration clusters in Germany, Poland, and Romania, with steel tube framing and powder-coating capacity concentrated in the former two. Raw material dependencies include FSC-certified beech plywood, powder-coated steel tubing, and recycled polypropylene feedstock. Supply chain risk centers on REACH compliance delays for coating adhesive reformulations. Distribution runs through pan-European warehouse networks serving consolidated municipal procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe school furniture market represents a late-cycle quality story as ergonomic standards and circular certification displace commodity procurement across German federal state modernization programs.
For Market Incumbents: Acquire circular supply chain assets including FSC-certified forestry operations and regional refurbishment facilities to defend against Eastern European volume competitors. Prioritize EN 1729 calibration technician training programs to constrain rollout velocity for height-adjustable desk competitors. For New Entrants and Emerging Players: Begin with vocational training workshop furniture in Poland and Romania where EU cohesion funds finance Soviet-era replacement. Target secondary school science laboratory segments where chemical-resistant surface specifications create procurement friction for generalist vendors. Establish direct sales teams for framework agreement navigation rather than distributor-dependent models. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance burdens favor dedicated regulatory teams over smaller competitors. Five-to-ten year viability favors manufacturers with backward integration into certified sustainable materials and established take-back service infrastructure. Monitor ECHA flame retardant restriction timelines as inflection indicators for coating reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Forestry | FSC/PEFC chain-of-custody control satisfies EU Green Deal procurement mandates for German federal states. |
| Refurbishment Service Launch | Take-back programs align with CSRD disclosure requirements and capture recurring public maintenance budgets. |
| EN 1729 Calibration Training Expansion | Certified technician networks constrain competitor rollout velocity for height-adjustable desk installations. |
| Smart Furniture Sensor Development | Embedded occupancy monitoring anticipates EU AI Act guidelines for connected institutional assets. |
| Eastern European Manufacturing Footprint | Polish and Romanian production captures EU cohesion fund volume and reduces logistics costs to remote locations. |
Research Approach
Multiple input streams — primary interviews with procurement consortia directors, regulatory compliance officers, and vocational training facility managers; secondary validation through EU tender databases, national fire safety standard filings, and manufacturer sustainability disclosures; plus customs trade data for steel and engineered wood imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed framework agreement negotiators at German Länder level, EN 1729 calibration technicians, and circular service program operators.
Data-stream reconciliation anchored volume and value outputs across product type, material specification, end-user tier, and distribution channel segmentation dimensions. CAGRs were derived from installed base replacement cycles, EU cohesion fund deployment schedules, and ergonomic standards adoption curves. Industry-specific forecast inputs included ECHA regulatory timeline assumptions and German federal state infrastructure modernization program commitments.
Several conditions sit outside the modeled scope, including geopolitical disruption to steel supply, accelerated EU AI Act enforcement timelines, and unanticipated Ecodesign regulation threshold revisions. Forecasts reflect documented assumptions on procurement consolidation velocity and REACH compliance cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Chaises Longue Market
Furniture
Global Folding Furniture Market
Furniture
Entryway Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Back Mount Frames Market
Furniture
North America Home Furniture Market
Furniture
North America Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Contract Furniture and Furnishing Market
Furniture
Contract Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market