
 Vietnam Home Furniture Market | 2026-2036
Vietnam Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Home Furniture Market Analytics
Aftermarket service revenue from furniture repair, reupholstery, and modular reconfiguration is reconfiguring profit pools away from one-time product sales toward lifecycle contracts. An Cuong Wood Working leverages vertical integration from particleboard production to finished cabinetry, capturing margin across multiple stages. Savimex anchors its position through specialized hospitality furniture exports, while Truong Thanh Furniture Corporation dominates domestic retail channels with broad distribution coverage.
Vietnam home furniture encompasses movable and fixed interior furnishings designed for residential dwelling spaces, typically constructed from engineered wood panels, solid timber, metal frames, or synthetic composites with surface treatments meeting moisture-resistance and load-bearing specifications for daily domestic use. Wood material commands the largest share of production value due to Vietnam's integrated timber processing clusters, while modern style segments are expanding fastest among urban first-time buyers seeking space-efficient designs. Metal and glass combinations occupy premium positioning in high-rise apartments, and minimalist styling is gaining traction among developers furnishing standardized condominium units.
The Ministry of Construction sets national building codes and interior fit-out standards that directly shape furniture specification requirements for new residential projects. BIS-equivalent conformity assessment procedures for imported materials, alongside Vietnam's commitments under ASEAN harmonized standards, create compliance thresholds that filter market access for foreign suppliers. Stakeholders must monitor evolving green building certification protocols and local content rules that will determine which material categories and manufacturing locations qualify for public housing procurement contracts.
Market Dynamics
Vietnam's Ministry of Construction tightened formaldehyde emission standards for wood-based panels in 2023, forcing domestic manufacturers to reengineer supply chains around certified engineered timber while import-dependent retailers face compliance bottlenecks at ports.
Growth Catalysts
- Apartment completions in Ho Chi Minh City:Mid-rise residential towers in southern provinces are driving bulk procurement of modular cabinet and sofa systems for first-time urban buyers.
- ASEAN harmonized standards:Vietnam's commitments under regional conformity protocols are reducing technical barriers for cross-border component sourcing from Thai and Malaysian suppliers.
- Engineered timber certification:Tighter emission rules are accelerating factory upgrades to E0-grade particleboard production, locking in quality premiums for compliant domestic producers.
Market Restraints
- Rubberwood input cost volatility:Vietnamese manufacturers depend heavily on domestic plantation timber, exposing margins to weather-driven supply fluctuations and competing industrial demand.
- Import dependency for specialty hardware:Premium hinge, slide, and fastener systems concentrate sourcing from Guangdong suppliers, creating single-geography vulnerability.
- Technical limitation in moisture-resistant coatings:Domestic finishing capabilities lag behind Korean and Japanese standards for tropical climate durability, forcing premium projects to specify imported surface treatments.
Strategic Opportunities
- Central Highlands furniture clusters:Underdeveloped manufacturing capacity in Gia Lai and Dak Lak provinces offers land and labor cost advantages for exporters targeting Australian and Middle Eastern markets.
- Green building certification protocols:Vietnam's emerging LOTUS and EDGE building standards will mandate low-emission interior materials, creating preferential procurement lanes for certified domestic suppliers.
- E-commerce platform integration:Direct-to-consumer channels through Shopee and Lazada are compressing traditional distributor margins while enabling modular reconfiguration services as subscription offerings.
Industry Challenges
- Industrial design talent scarcity:Vietnamese universities produce insufficient CAD-CAM specialists capable of translating European design briefs into production-ready specifications for export orders.
- Compliance timeline compression:Factory recertification under revised Ministry of Construction standards requires 18-24 month capital cycles that strain mid-tier manufacturers without captive financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Home Furniture Market |
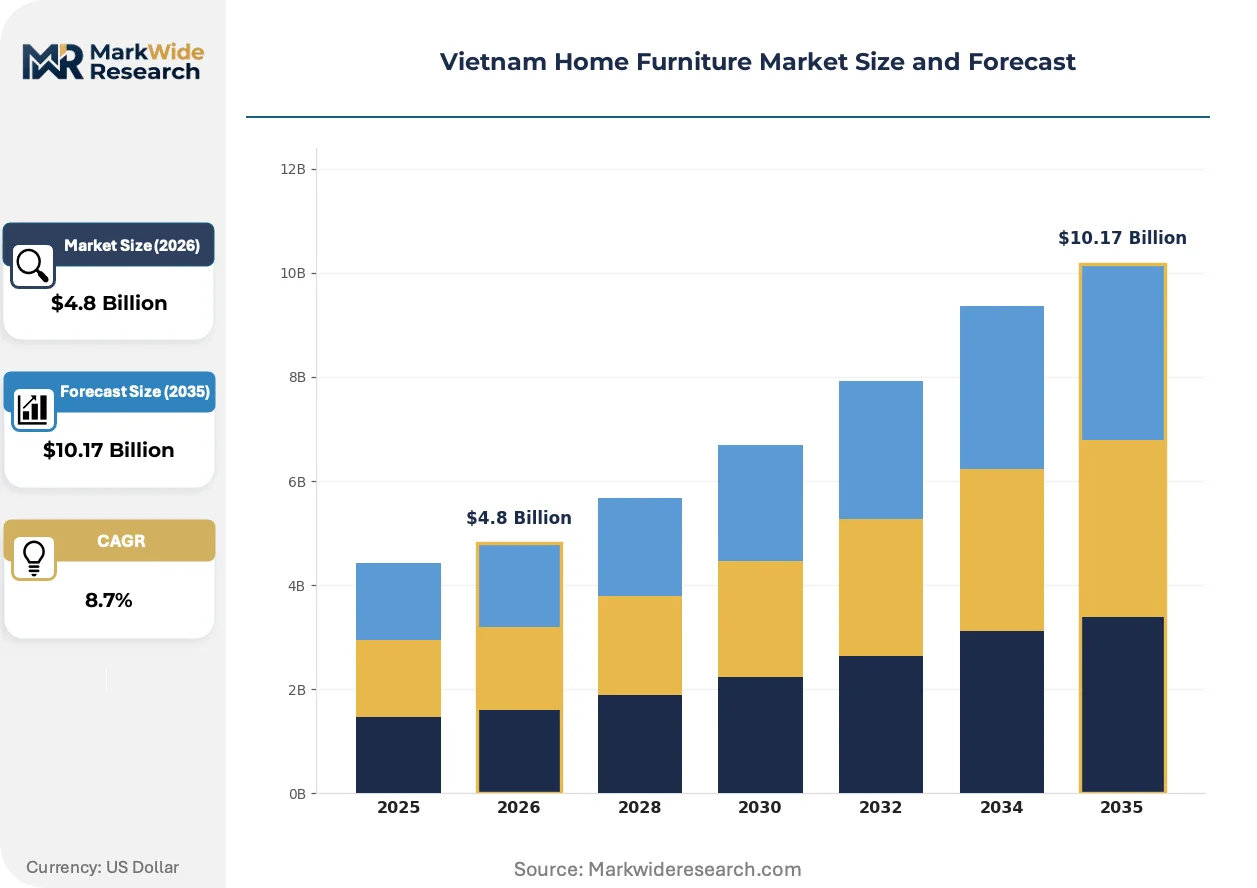
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Chairs, Cabinets Material: Wood, Metal, Plastic, Glass Style: Modern, Traditional, Rustic, Minimalist End User: Households, Offices, Hotels, Retailers |
| Companies Covered | An Cuong Wood Working, Savimex, Truong Thanh Furniture Corporation, Scansia Pacific, Minh Duong Furniture Corporation, AA Corporation, Xuan Hoa Vietnam, Hoa Phat Furniture, Kaiser 1 Furniture Industry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Home Furniture Market Evolving Landscape
Digital manufacturing tools and regulatory compliance automation are compressing product development cycles while reconfiguring how Vietnamese manufacturers interface with international buyers and domestic project developers.
CNC nesting software paired with automated edge banding lines is digitizing production scheduling across Ho Chi Minh City factory clusters, allowing mid-size producers to quote custom dimensions with 72-hour turnaround times that previously required two-week manual workflows. Export-oriented manufacturers serving Australian retailers are adopting these systems fastest, using real-time production dashboards to compress sample-to-shipment intervals.
The Ministry of Construction's 2023 circular on formaldehyde emission limits is forcing particleboard mills to retrofit thermal pressing equipment with continuous emission monitoring systems. Domestic cabinet producers must now source exclusively from certified substrate suppliers, creating a two-tier supply structure where compliant mills capture premium pricing from project developers while uncertified competitors retreat to informal retail channels.
Condominium developers in Hanoi are unbundling furniture procurement from general construction contracts, creating direct specification relationships with modular system suppliers that bypass traditional interior fit-out subcontractors. This disintermediation concentrates purchasing power with Vinhomes and Novaland-scale developers while squeezing margins for independent design-build firms that previously captured furniture markups.
Vietnam Home Furniture Market Segmentation
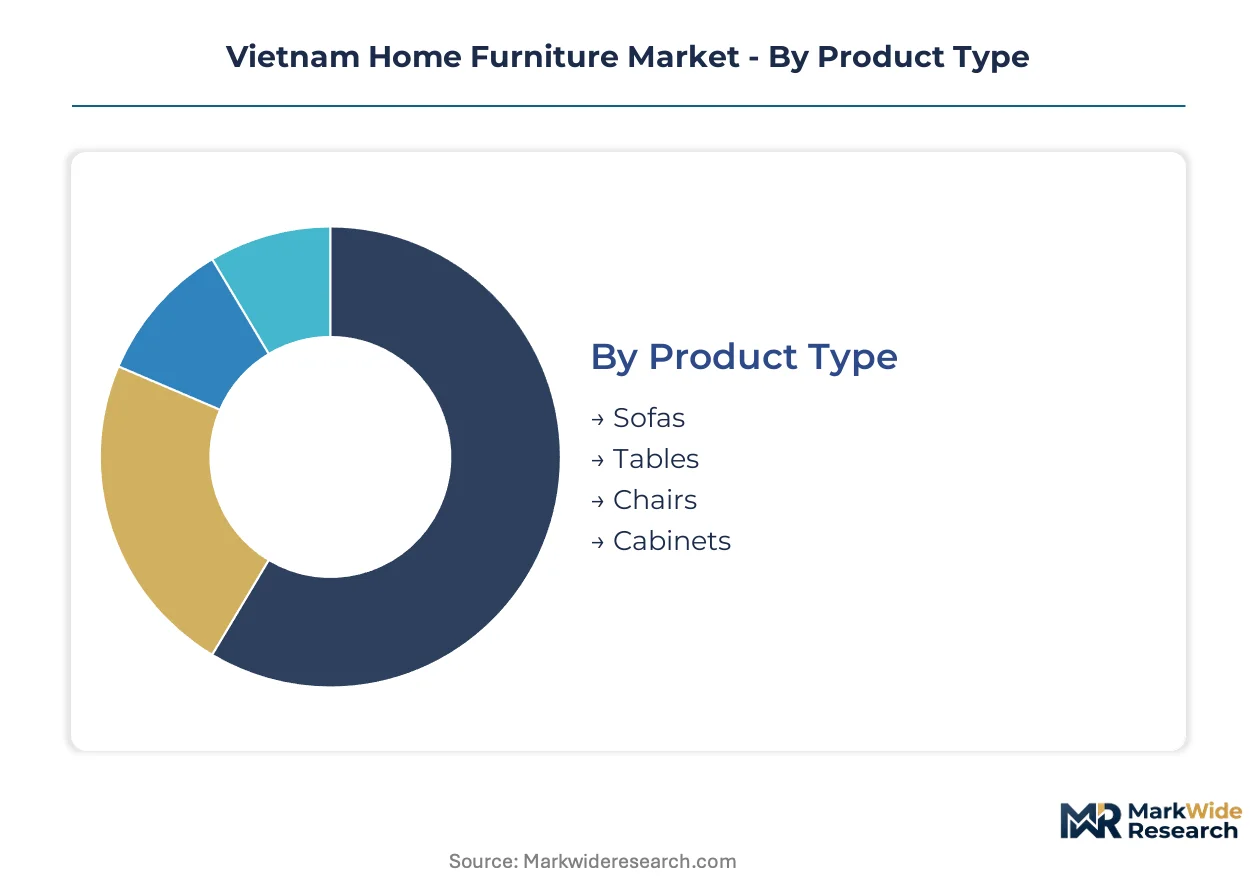
Segmentation in Vietnam's home furniture market determines service contract structures, with modular systems commanding lifecycle revenue streams and fixed installations locking in one-time margins. Material certification tiers and style positioning further stratify procurement channels between project developers and retail distributors.
Product Type:
After-sales service intensity varies sharply across furniture categories, with modular seating and storage systems generating recurring reconfiguration revenue while fixed dining surfaces yield minimal post-sale attachment.
- Sofas:Upholstered seating systems with engineered wood frames and synthetic foam cores dominate living room procurement for urban apartments. Demand concentrates in Ho Chi Minh City's mid-rise towers, where developers specify modular sectional configurations that allow unit-to-unit customization without SKU proliferation.
- Cabinets:Wall-mounted and freestanding storage units constructed from E0-grade particleboard with thermofoil or laminate surfacing. Procurement in Hanoi's condominium projects is accelerating as Vinhomes-scale developers unbundle furniture from general construction contracts, creating direct specification relationships with certified manufacturers.
- Tables:Dining and occasional surfaces combining rubberwood solids with metal or engineered wood substrates.
- Chairs:Seating units spanning dining, accent, and task applications with varied frame materials and upholstery options.
By volume, Cabinets leads. By growth pace, Sofas is ahead.
Material:
Cost tier positioning separates certified engineered timber commanding project premiums from untreated plantation wood serving informal retail channels.
- Wood:Rubberwood plantation timber and E0-certified particleboard account for the dominant production value share, with integrated processing clusters in southern provinces capturing margin across sawmilling through finished goods. Ministry of Construction emission standards are forcing substrate sourcing exclusively from certified mills, creating a two-tier supply structure.
- Metal:Powder-coated steel and aluminum framing systems for premium apartment applications, often combined with glass or engineered wood surfaces. Demand in high-rise Hanoi towers is expanding for space-efficient designs where load-bearing specifications exceed domestic timber capabilities.
- Plastic:Polypropylene and ABS components for cost-driven outdoor and children's furniture segments.
- Glass:Tempered and laminated glazing for tabletops and display surfaces in premium positioning.
Wood commands the largest production share. Metal is climbing the fastest among certified project specifications.
Style:
Application context drives style selection, with developer-furnished condominiums standardizing on space-efficient aesthetics while independent homeowners pursue differentiated finishes.
- Modern:Clean-lined designs with neutral palettes and multi-functional configurations optimized for compact urban footprints. First-time buyers in Ho Chi Minh City are driving the steepest expansion trajectory as apartment sizes shrink and space efficiency becomes non-negotiable.
- Minimalist:Stripped-down forms with concealed hardware and monochromatic finishes. Novaland and comparable developers are specifying this aesthetic for standardized condominium units across southern provinces, creating volume procurement lanes for compliant suppliers.
- Traditional:Ornate detailing and dark wood tones rooted in colonial and regional craft heritage.
- Rustic:Distressed finishes and reclaimed-wood aesthetics targeting vacation property and boutique hospitality segments.
Modern styling leads by project volume. Minimalist is gaining share fastest among developer specifications.
End User:
Customer type determines procurement channel and margin structure, with institutional buyers leveraging direct manufacturer relationships while households route through layered distribution.
- Households:Individual consumers furnishing owner-occupied apartments and landed homes, representing the core demand concentration as urbanization accelerates. Bulk procurement by first-time buyers in southern province residential towers is driving modular cabinet and sofa system volumes.
- Hotels:Hospitality operators sourcing durable, standardized room packages with rapid replacement cycles. Savimex and comparable specialists anchor export positioning through this channel, with Australian and Middle Eastern markets absorbing capacity from Central Highlands clusters.
- Offices:Corporate workspace fit-outs with ergonomic and collaborative furniture specifications.
- Retailers:Furniture dealers and e-commerce platforms intermediating between manufacturers and end consumers.
Households dominate by absolute volume. Hotels is expanding most quickly among export-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Vietnamese sub-markets, with first-time apartment buyers in southern provinces driving volume through mid-tier procurement while Hanoi high-rise developers absorb premium positioning for certified materials.
Southern Key Economic Region
Ho Chi Minh City mid-rise residential towers are accelerating bulk procurement of modular cabinet and sofa systems for urban first-time buyers. The Ministry of Construction's tightened formaldehyde emission standards are forcing substrate sourcing exclusively from certified particleboard mills. Binh Duong and Dong Nai factory clusters are digitizing production scheduling through CNC nesting software, compressing custom-dimension quoting from two weeks to 72 hours.
Red River Delta
Hanoi condominium developers are unbundling furniture procurement from general construction contracts, creating direct specification relationships with modular system suppliers. Vietnam's commitments under ASEAN harmonized standards are reducing technical barriers for cross-border component sourcing from Thai suppliers. Bac Ninh and Hung Yen industrial zones are attracting finishing equipment upgrades to meet tropical climate durability specifications for premium projects.
Central Coast
Da Nang and Quang Nam hospitality developments are driving demand for standardized room packages with rapid replacement cycles. The Ministry of Construction sets national building codes that shape furniture specification requirements for new resort projects. Hoi An craft heritage clusters are pivoting toward boutique hospitality segments with distressed finishes and reclaimed-wood aesthetics.
Central Highlands
Gia Lai and Dak Lak provinces offer underdeveloped manufacturing capacity with land and labor cost advantages for export-oriented producers. Green building certification protocols including Vietnam's emerging LOTUS standards will mandate low-emission interior materials for public housing procurement. Pleiku and Buon Ma Thuot are positioning as alternative production bases targeting Australian and Middle Eastern markets.
Vietnam Home Furniture Market Competitive Landscape
Vertically integrated timber processors and hospitality-focused export specialists split the market into distinct competitive spheres. Domestic retail channel dominance and specialized export positioning represent the two primary strategic archetypes. Competitive moves concentrate on factory recertification under revised emission standards and e-commerce platform integration for direct-to-consumer channels.
Among integrated wood-working specialists, An Cuong Wood Working exemplifies backward integration from particleboard production through finished cabinetry. Savimex occupies a position within the hospitality export tier, while Truong Thanh Furniture Corporation anchors domestic retail channel coverage. These three represent contrasting strategic postures: captive supply control, export market specialization, and broad distribution reach respectively.
| Leading Market Players |
|---|
| An Cuong Wood Working |
| Savimex |
| Truong Thanh Furniture Corporation |
| Scansia Pacific |
| Minh Duong Furniture Corporation |
| AA Corporation |
| Xuan Hoa Vietnam |
| Hoa Phat Furniture |
| Kaiser 1 Furniture Industry |
| Others |
Value Network & Pricing Analysis
Overcapacity in Dong Nai particleboard mills is compressing substrate pricing while simultaneously forcing compliant producers toward premium positioning through Ministry of Construction certification tiers, creating divergent margin trajectories between certified and uncertified supply tiers.
Pricing Analysis
After-sales service revenue from furniture repair, reupholstery, and modular reconfiguration drives lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates E0-certified project specifications from uncertified retail channels, with certification grade and vertical integration status as primary differentiation drivers. Cost compression in the standard tier is intensifying because Binh Duong factory clusters are digitizing production and compressing quoting cycles. First-time apartment buyers in Ho Chi Minh City exhibit highest price sensitivity, while Hanoi condominium developers absorbing certified material premiums show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability from Guangdong specialty hardware suppliers dominates risk exposure for premium hinge, slide, and fastener systems. Vietnam draws from domestic rubberwood plantations, Thai cross-border component flows, and Malaysian engineered timber inputs for substrate supply. Raw material dependencies center on plantation timber, E0-grade particleboard, and imported surface treatment chemicals. Distribution runs through project developer direct specifications, traditional interior fit-out subcontractors, and Shopee-Lazada e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular reconfiguration services are expanding faster than one-time hardware sales, converting furniture procurement into recurring lifecycle contracts with superior margin retention.
For Market Incumbents: Harden compliance positioning by accelerating factory recertification under Ministry of Construction emission standards before the 18-24 month capital cycle closes to mid-tier competitors without captive financing. Deepen backward integration into certified particleboard production to capture substrate premiums and lock out import-dependent retailers facing port compliance bottlenecks. For New Entrants and Emerging Players: Central Highlands underpenetration in Gia Lai and Dak Lak provinces offers land and labor cost advantages for export-oriented production targeting Australian and Middle Eastern markets. White-space exists in hospitality furniture specialization and green building certified supply for emerging LOTUS standards. Direct-to-consumer e-commerce integration through Shopee and Lazada enables subscription-based modular reconfiguration services with compressed distributor margins. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across E0-grade particleboard production and automated finishing equipment upgrades. Long-term viability favors vertically integrated timber processors with captive supply from plantation through certified substrate. The signal to monitor is Ministry of Construction enforcement intensity at ports and factory audit frequency.| Strategic Initiative | Industry Significance |
|---|---|
| Factory Recertification Investment | Ministry of Construction emission standards are filtering market access and concentrating supply among compliant mills. |
| Backward Integration into Particleboard | An Cuong Wood Working exemplifies margin capture across sawmilling through finished cabinetry production. |
| E-commerce Platform Integration | Shopee and Lazada channels compress traditional distributor margins while enabling subscription reconfiguration services. |
| Central Highlands Capacity Expansion | Gia Lai and Dak Lak provinces offer cost advantages for export-oriented production targeting Australian markets. |
| Green Building Certification Alignment | LOTUS and EDGE standards will mandate low-emission interior materials for preferential public housing procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, Ministry of Construction regulatory filings, and ASEAN trade databases through structured interviews with furniture manufacturing executives, condominium procurement directors, and particleboard mill operations managers. Bottom-up demand modeling from apartment completion data and top-down supply validation from factory capacity surveys were cross-referenced for triangulation.
Forecast inputs include product type segmentation across sofas, cabinets, tables, and chairs; material tiers separating certified engineered timber from untreated plantation wood; style positioning spanning modern, minimalist, traditional, and rustic; and end-user channels distinguishing household, hospitality, office, and retail distribution. CAGRs were derived from regression analysis against urbanization rates and residential construction permits across the analysis window, with specific weighting for ASEAN harmonized standards adoption and green building certification penetration.
Macroeconomic conditions sit as an overlay; deviation in residential construction credit availability and rubberwood plantation yields would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Furniture Laminate Market
Furniture
Wood Furniture Market
Furniture
US School Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Europe Furniture Market
Furniture
Pedicure Chair Market
Furniture
Kids and Nursery Furniture Market
Furniture
Japan Furniture Market
Furniture
Piano Stools Market
Furniture
Italy Home Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Japan Home Furniture Market
Furniture
United States Luxury Furniture Market
Furniture
United States Home Furniture Market