
 Mexico Home Furniture Market | 2026-2036
Mexico Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Home Furniture Market Foresight
The gap between premium handcrafted furniture and mass-produced commodity lines is realigning Mexican consumer expectations. Ashley Furniture Industries leverages its North American manufacturing footprint to anchor mid-market sofa and bedroom collections across Mexican retail channels. IKEA competes on flat-pack logistics and cost-engineered wood systems, while Vila Furniture specializes in regionally sourced hardwood designs that dominate artisan-adjacent segments in central Mexico.
Mexico home furniture encompasses movable residential and commercial furnishings constructed from wood, metal, upholstery textiles, and glass composites, typically finished through CNC machining, foam molding, or hand-joinery for functional interior spaces. Wood material segments sustain premium margin pools due to NOM-certified sourcing requirements and extended durability specifications, whereas upholstery leads volume growth as residential customers prioritize comfort-driven living room configurations. Modern style categories are capturing fastest growth in urban condominiums, while traditional designs retain stable demand across rural and heritage-property renovations.
SEMARNAT enforces NOM-001 and NOM-002 forestry standards that restrict uncertified timber in commercial furniture production, directly shaping raw material procurement and export eligibility. PROFECO, Mexico's consumer protection agency, mandates clear labeling of material composition and origin, influencing how manufacturers position wood versus metal and glass product lines. Stakeholders must monitor evolving LGEEPA environmental audits and state-level sustainability incentives that will determine which material and style segments retain cost-competitive production licenses.
Market Dynamics
SEMARNAT's NOM-certified forestry enforcement is compressing raw material sourcing flexibility while concentrating production around Bajío corridor clusters with verified supply chain documentation.
Growth Catalysts
- NOM-001 and NOM-002 Standards:Mandatory certified timber sourcing is locking compliant manufacturers into premium export eligibility and domestic retail shelf access.
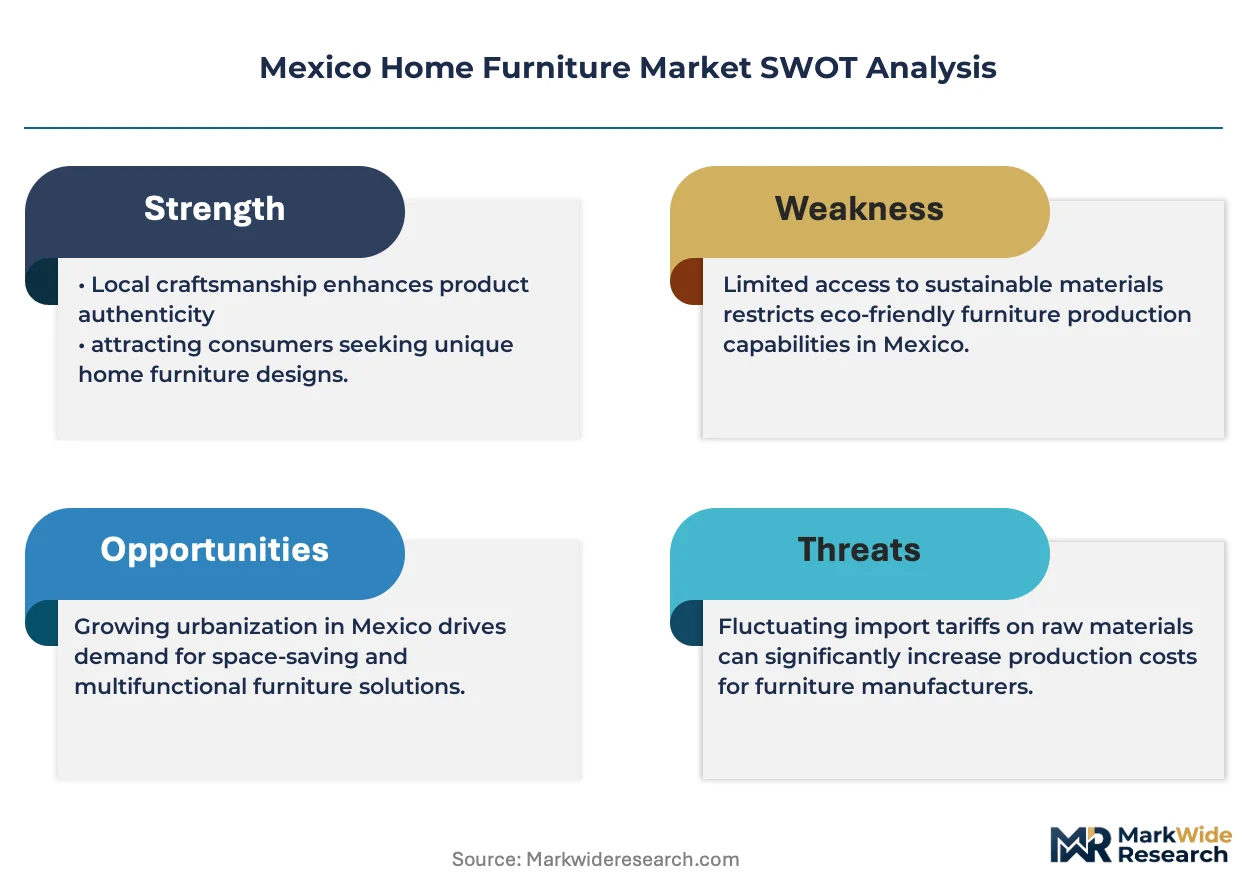
- Urban Residential Density:Mexico City and Guadalajara condominium construction is pulling upholstered furniture demand toward space-optimized modular configurations.
- Leather-Textile Integration:Querétaro and León industrial clusters enable same-day material sourcing for upholstered production runs.
Market Restraints
- Certified Timber Cost Premium:NOM-compliant wood inputs carry sourcing documentation overhead that compresses margin pools for non-integrated producers.
- Bajío Supply Concentration:Seventy percent of certified upholstery-grade leather processing sits within 150 kilometers of León, creating single-point vulnerability.
- Glass Composite Substitution:Tempered glass tabletops and shelving systems are displacing solid wood in entry-level dining and accent furniture.
Strategic Opportunities
- PROFECO Labeling Transparency:Material origin disclosure mandates create first-mover advantage for brands with documented supply chain traceability.
- Quintana Roo Tourism Corridor:Vacation rental property management companies are sourcing bulk hardwearing furniture packages for coastal condominium developments.
- LGEEPA Audit Preparation:State-level environmental compliance incentives reward manufacturers investing in water-based finishing systems ahead of enforcement expansion.
Industry Challenges
- CNC Programming Talent Scarcity:Custom hardwood joinery shops face recruitment gaps for operators capable of translating hand-drawn designs into machine-ready code.
- Foam Certification Timelines:PROFECO fire-resistance labeling for polyurethane cushioning extends product launch cycles by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Home Furniture Market |
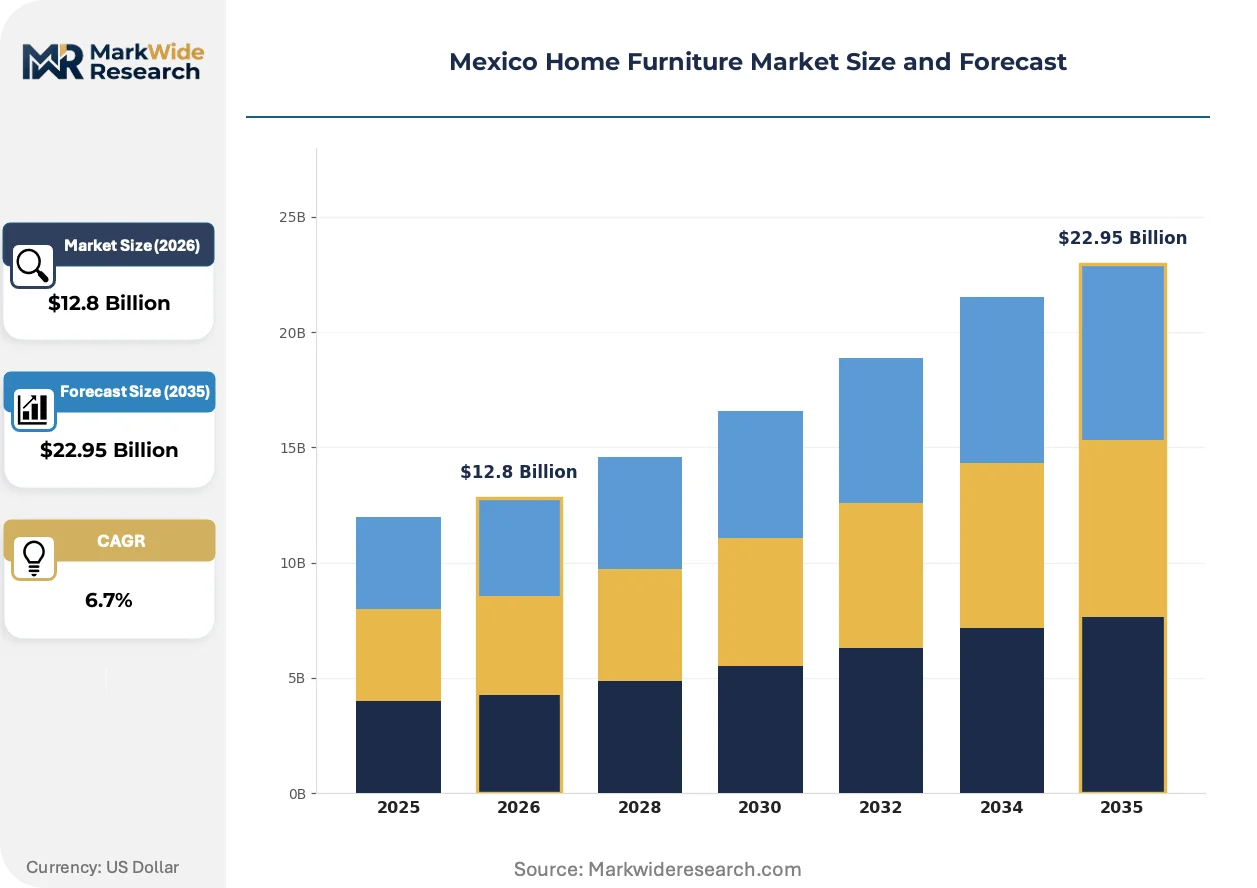
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Chairs, Beds Material: Wood, Metal, Upholstery, Glass Style: Modern, Traditional, Minimalist, Rustic Customer Type: Residential, Commercial, Office, Retail |
| Companies Covered | IKEA, Tempur Sealy International, Ashley Furniture Industries, Crate and Barrel Holdings, Vila Furniture, Living Spaces, Natuzzi S.p.A., American Home Furniture and Mattress, La-Z-Boy Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Home Furniture Market Shifts & Advancements
Digital fabrication workflows and regulatory transparency requirements are compressing traditional craft-to-market timelines while elevating material traceability as a competitive differentiator.
Parametric design software is converging with five-axis CNC machining to enable mass-customized hardwood furniture production at mid-market price points. Guadalajara-based manufacturers are adopting these systems to fulfill architect-specified dimensions without hand-tooling delays. This technology convergence is collapsing the traditional premium-customization cost gap.
SEMARNAT's expanded LGEEPA audit scope is forcing furniture exporters to maintain chain-of-custody documentation from sawmill to finished goods. Manufacturers without integrated forestry holdings must now contract certified suppliers under multi-year volume commitments. Upholstered producers sourcing NOM-certified hardwood frames face the steepest compliance cost escalation.
Residential buyers in Mexico City are prioritizing certified material transparency over traditional brand loyalty when selecting living room investments. Boutique retailers are responding with QR-linked supply chain storytelling that displaces conventional advertising spend. This behavioral pivot is most pronounced among condominium purchasers aged thirty-five to fifty-five in Polanco and Santa Fe districts.
Mexico Home Furniture Market Segmentation
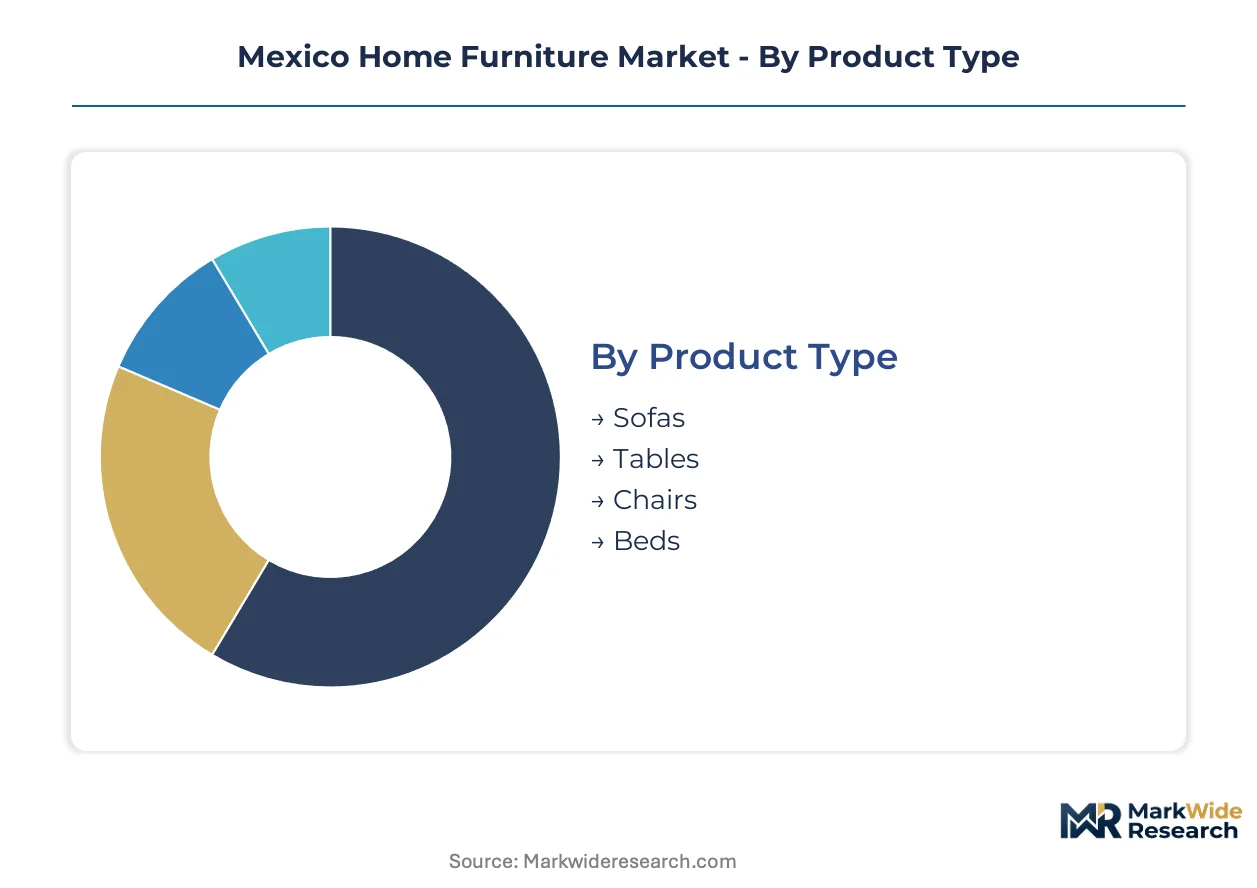
Mexico's home furniture market fragments across four distinct category axes that determine procurement patterns, margin structures, and regulatory exposure. Product type and material composition dominate residential purchasing decisions, while customer type and style orientation shape channel strategy and geographic targeting.
Product Type:
Residential buyers prioritize room-function hierarchy differently based on dwelling size and household formation stage.
- Sofas:Upholstered seating systems with foam-core construction and fabric or leather exteriors anchor living room investments. Demand clusters in Mexico City and Guadalajara condominiums where space-optimized modular configurations accommodate compact floor plans. PROFECO fire-resistance labeling requirements extend launch cycles for polyurethane cushioning variants.
- Tables:Dining and accent surfaces span solid wood, tempered glass, and metal-composite constructions. Glass tabletops are displacing solid wood in entry-level dining segments across Bajío corridor retail channels. SEMARNAT-certified hardwood frames command premium positioning in heritage-property renovations.
- Chairs:Seating units range from ergonomic office designs to hand-joined hardwood dining pieces. Guadalajara manufacturers deploy five-axis CNC machining to fulfill architect-specified custom dimensions without hand-tooling delays.
- Beds:Platform and storage-integrated frames dominate urban residential replacement cycles. Quintana Roo vacation rental operators source bulk hardwearing bed packages for coastal condominium developments.
Sofas lead volumes today; beds are gaining share fastest as condominium construction accelerates bedroom furniture replacement.
Material:
Raw material selection determines NOM compliance burden, export eligibility, and finished goods durability positioning.
- Wood:NOM-001 and NOM-002 certified timber sustains premium margin pools through verified chain-of-custody documentation. Upholstered producers sourcing certified hardwood frames face steepest compliance cost escalation in León and Querétaro clusters.
- Upholstery:Foam, fabric, and leather composite systems drive volume expansion as residential customers prioritize comfort-driven living room configurations. Bajío corridor leather-textile integration enables same-day material sourcing for production runs.
- Metal:Steel and aluminum framing components serve commercial and office segments requiring load-bearing durability. Metal systems bypass SEMARNAT forestry certification entirely, shortening procurement lead times.
- Glass:Tempered and laminated surfaces displace wood in entry-level dining and accent furniture. Glass composite substitution accelerates in mass-market retail channels serving first-time homebuyers.
Upholstery leads volumes today; glass is expanding most quickly as cost-engineered alternatives penetrate entry-tier segments.
Style:
Aesthetic orientation correlates with buyer age cohort, property type, and willingness to pay for certified material transparency.
- Modern:Clean-line geometries with minimal ornamentation capture fastest growth in Mexico City and Guadalajara urban condominiums. Parametric design software convergence with CNC machining collapses premium-customization cost gaps for this segment.
- Traditional:Ornate hardwood joinery and heritage finishes retain stable demand across rural properties and colonial-era renovations. Hand-joinery shops face CNC programming talent scarcity when translating custom designs into machine-ready code.
- Minimalist:Reduced-component designs emphasizing negative space and hidden storage. Polanco and Santa Fe district purchasers aged thirty-five to fifty-five prioritize certified material transparency over brand loyalty for minimalist investments.
- Rustic:Distressed finishes and reclaimed wood aesthetics targeting artisan-adjacent positioning. QR-linked supply chain storytelling displaces conventional advertising spend for rustic segment retailers.
Traditional leads volumes today; modern is climbing the fastest as condominium construction reshapes urban residential inventory.
Customer Type:
End-use application determines order scale, specification complexity, and relationship with PROFECO labeling mandates.
- Residential:Individual household purchasers driving replacement cycles and new dwelling outfitting. Residential buyers in Mexico City prioritize certified material transparency when selecting living room investments.
- Commercial:Hospitality and multi-unit property operators sourcing durable, standardized furniture packages. Quintana Roo tourism corridor vacation rental management companies represent concentrated bulk demand.
- Office:Corporate workspace outfitting emphasizing ergonomic seating and modular storage systems. Office segment procurement concentrates in Guadalajara and Monterrey business districts.
- Retail:Furniture showroom and boutique operators purchasing display fixtures and merchandising systems. Retail channel buyers leverage PROFECO labeling transparency mandates to differentiate private-label offerings.
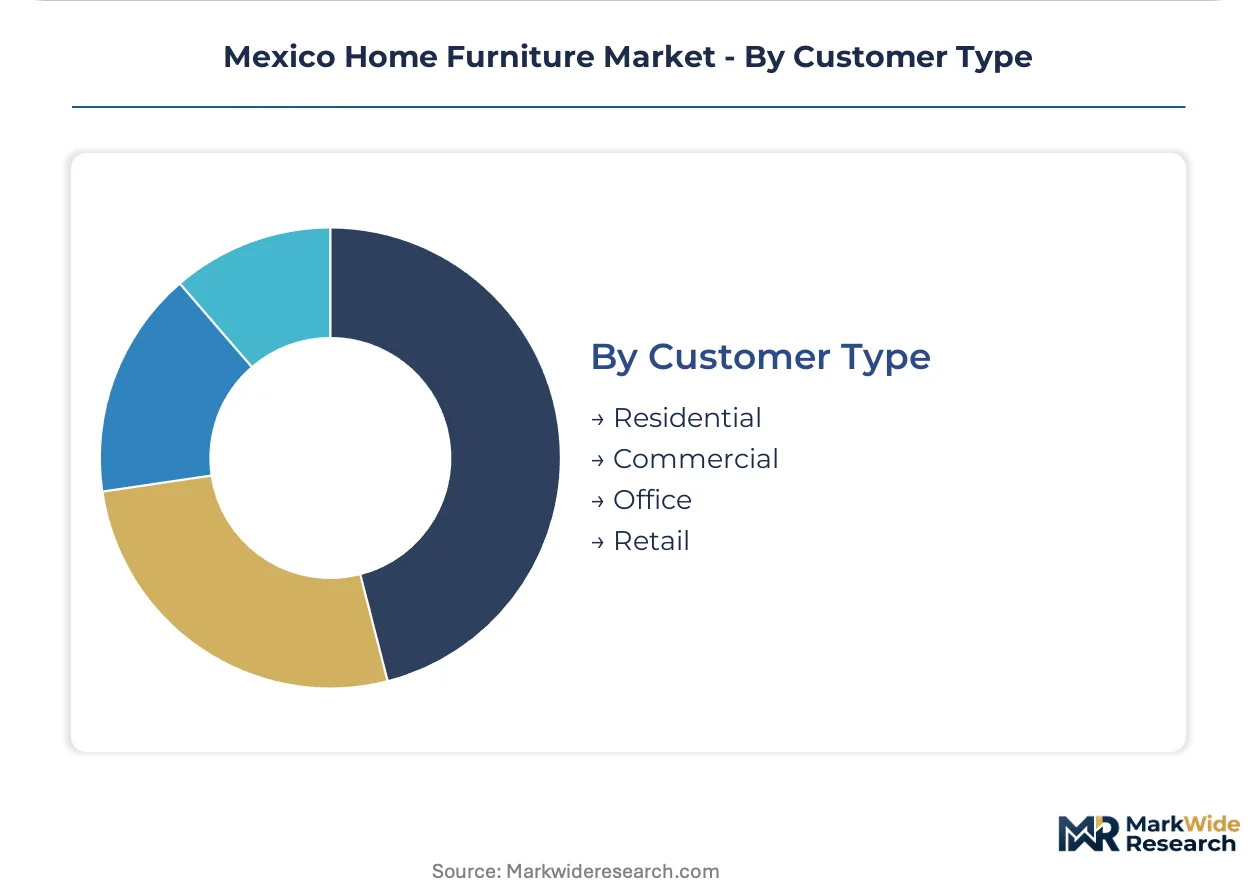
Residential leads volumes today; commercial is gaining share fastest as tourism corridor development accelerates bulk procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan woodworkers and CNC technicians cluster in Mexico's central manufacturing belt, anchoring production capacity for domestic and export markets. This workforce concentration shapes regional competitive dynamics and supply chain configuration.
Mexico City Metro
Condominium construction in Polanco and Santa Fe districts pulls demand for space-optimized modular sofas and minimalist storage beds. SEMARNAT's NOM-certified timber requirements filter retail shelf access, favoring documented supply chains. Urban furniture showrooms concentrate in Cuauhtémoc and Miguel Hidalgo boroughs, serving high-income residential replacement cycles.
Jalisco
Guadalajara's metropolitan area generates architect-specified custom furniture orders requiring five-axis CNC machining capabilities. The state's environmental regulator enforces LGEEPA audit protocols that pressure finishing shops toward water-based coating systems. Parametric design software adoption is collapsing premium-customization cost gaps among mid-market producers in Tlaquepaque and Zapopan industrial zones.
Bajío Region
León and Querétaro host integrated leather-textile supply chains enabling same-day material sourcing for upholstered production runs. PROFECO labeling mandates for fire-resistance certification extend product launch cycles for foam cushioning variants. Seventy percent of certified upholstery-grade leather processing sits within 150 kilometers of León, creating concentrated supplier dependency.
Nuevo León
Monterrey's corporate office construction drives ergonomic seating and modular storage procurement for workspace outfitting. The state's industrial promotion programs incentivize manufacturers investing in SEMARNAT-compliant forestry documentation systems. Metal-framing fabricators bypass timber certification entirely, shortening procurement lead times for commercial segment buyers.
Yucatán Peninsula
Quintana Roo's tourism corridor generates bulk furniture package demand from vacation rental property management companies. Coastal condominium developments in Cancún and Playa del Carmen source hardwearing bed and dining configurations for high-turnover hospitality use. Regional distributors face logistics complexity serving dispersed developments across the peninsula.
Mexico Home Furniture Market Competitive Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light designers relying on contract fabrication networks. The vendor base stratifies across three tiers: multinational retailers with North American distribution networks, regional specialists leveraging Bajío corridor supply integration, and artisan-adjacent workshops serving heritage-property renovations. Strategic moves concentrate on certified supply chain documentation investments and parametric design technology licensing.
Within the multinational retail tier, IKEA and Ashley Furniture Industries exemplify divergent operational models—flat-pack logistics specialization versus integrated manufacturing footprint anchoring. Vila Furniture occupies a position among regionally rooted hardwood specialists. These three anchors illustrate how certification compliance burden and supply chain transparency requirements are reshaping competitive positioning across price tiers.
| Leading Market Players |
|---|
| IKEA |
| Tempur Sealy International |
| Ashley Furniture Industries |
| Crate and Barrel Holdings |
| Vila Furniture |
| Living Spaces |
| Natuzzi S.p.A. |
| American Home Furniture and Mattress |
| La-Z-Boy Incorporated |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps in León and Querétaro anchor upholstered furniture production, their multi-generational capital structures enabling patient investment in NOM-certified timber stockpiles that insulate pricing from spot-market volatility. These ownership patterns concentrate supply discipline within the Bajío corridor while compressing margin flexibility for non-integrated competitors.
Pricing Analysis
Delivery-bundled versus unbundled installation splits Mexican residential furniture transactions, with urban condominium buyers in Mexico City and Guadalajara absorbing white-glove service premiums while Bajío corridor retailers compete on stripped-down price points. Three-tier pricing structure across premium, standard, and economy levels stratifies by NOM-001 certification grade and documented chain-of-custody depth. Cost compression in economy-tier glass-composite dining sets is intensifying because tempered glass imports bypass SEMARNAT forestry documentation entirely. First-time homebuyers in mass-market channels exhibit acute price sensitivity; heritage-property renovators purchasing certified hardwood frames show minimal elasticity.
Supply Chain Analysis
SEMARNAT's domestic-content documentation mandates are reshaping sourcing toward verified Mexican sawmill partnerships and away from informal Central American timber channels. Geographic concentration centers on Guanajuato, Querétaro, and Jalisco for upholstered frame production, with leather finishing clustered within 150 kilometers of León. Raw material dependencies include NOM-certified tropical hardwoods, polyurethane foam systems, and Bajío-processed upholstery-grade leather. Single-source vulnerability pervades the leather-textile corridor, where certified tannery capacity concentrates around a handful of family-owned processors. Distribution runs through Monterrey-based logistics hubs serving northern commercial accounts and Mexico City showroom networks for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's home furniture market functions as a geographic-arbitrage play, with NOM-certified production capacity commanding premium export eligibility into US markets where EPA timber sourcing rules create parallel compliance barriers for Asian competitors.
For Market Incumbents: Lock in multi-year volume commitments with SEMARNAT-certified sawmills before LGEEPA audit expansion tightens supplier availability. Secure CNC programming talent through apprenticeship pipelines with Guadalajara technical institutes to defend against parametric design entrants. These moves counter the threat of asset-light designers leveraging contract fabrication networks to undercut mid-market positioning.
For New Entrants and Emerging Players: Boutique retailers in Polanco and Santa Fe districts offer the most penetrable channel, their QR-linked supply chain storytelling creating shelf access without legacy showroom infrastructure. Target the minimalist segment among thirty-five to fifty-five-year-old condominium purchasers who prioritize certified material transparency over established brand equity. A direct-to-designer go-to-market angle, bypassing traditional retail markup, collapses price-positioning gaps against integrated manufacturers.
For Investors and Strategic Acquirers: Valuations sit cheapest among artisan-adjacent hardwood workshops with documented NOM-002 compliance but underutilized CNC capacity. Long-term viability across the projection horizon hinges on regulatory certification depth rather than brand heritage alone. The signal to watch is PROFECO's expansion of fire-resistance labeling to imported foam components, which would compress launch-cycle advantages for domestic integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber Holdings | Captive NOM-001 supply secures export eligibility and insulates margin from spot-market volatility. |
| Water-Based Finishing System Conversion | LGEEPA audit preparation positions manufacturers for state-level environmental compliance incentives. |
| Parametric Design Software Licensing | Five-axis CNC integration collapses premium-customization cost gaps for architect-specified orders. |
| Quintana Roo Tourism Corridor Partnership | Bulk procurement relationships with vacation rental operators capture commercial segment expansion. |
| QR-Linked Supply Chain Transparency Platform | PROFECO labeling mandates create first-mover advantage with certified material storytelling. |
Research Methodology
Multiple input streams — primary field interviews, customs and trade documentation, and regulatory filing analysis — were reconciled to construct demand and supply estimates. Conversations with furniture manufacturing executives, SEMARNAT compliance officers, Bajío corridor leather processors, and Mexico City showroom operators informed operational assumptions. Secondary validation drew from PROFECO labeling registries, NOM-001 and NOM-002 certification databases, and state-level industrial promotion program disclosures. Bottom-up production capacity tallies were cross-checked against top-down residential construction permit data across the analysis window.
Historical shipment patterns were cross-referenced against panel-based industry input to anchor growth trajectory assumptions. Segmentation modeling incorporated product type, material composition, style orientation, and customer application across the projection horizon. CAGRs were derived from trend extrapolation moderated by regulatory enforcement intensity assumptions. Industry-specific forecast inputs included condominium construction permits in Mexico City and Guadalajara, and LGEEPA audit scope expansion timelines.
Revisions become necessary when SEMARNAT enforcement intensity shifts, certified timber spot prices spike, or PROFECO labeling mandates expand to additional material categories. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and leather-textile corridor concentration risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Luxury Furniture Market
Furniture
France Furniture Market
Furniture
China Home Furniture Market
Furniture
Upholstered Furniture Market
Furniture
High End Furnitures Market
Furniture
Contract Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Bar Stools Market
Furniture
Europe Bamboo Furniture Market
Furniture
Recliner Chair Market
Furniture
Global Home Furniture Market
Furniture
Fireplace Mantels Market
Furniture
India Home Furniture Market
Furniture
Home Furnishings Market
Furniture
Study Carrels Market
Furniture
Global Multifunctional Furniture Market