
 Back Mount Frames Market | 2026-2036
Back Mount Frames Market Size, Share, and Industry Trends Forecast 2026-2036
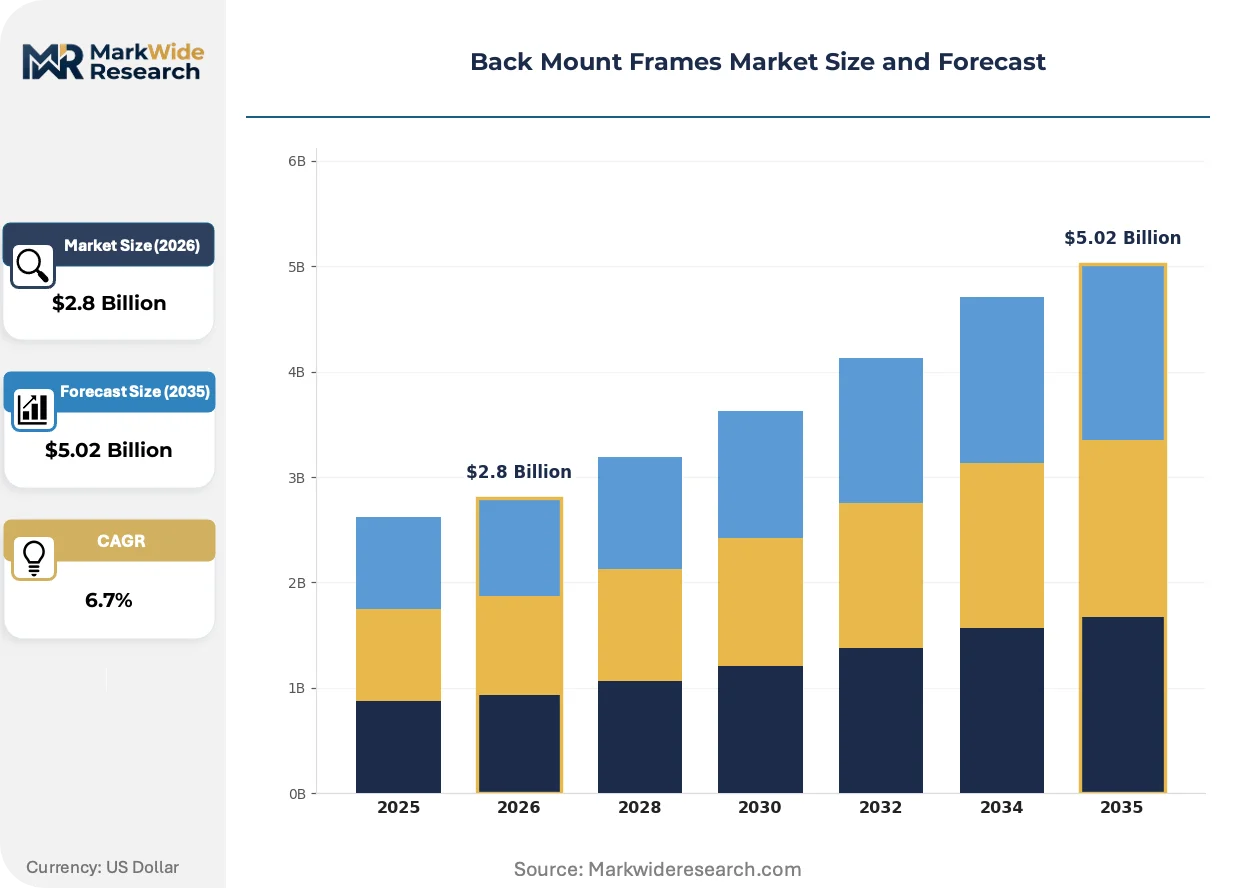
Back Mount Frames Market Outlook
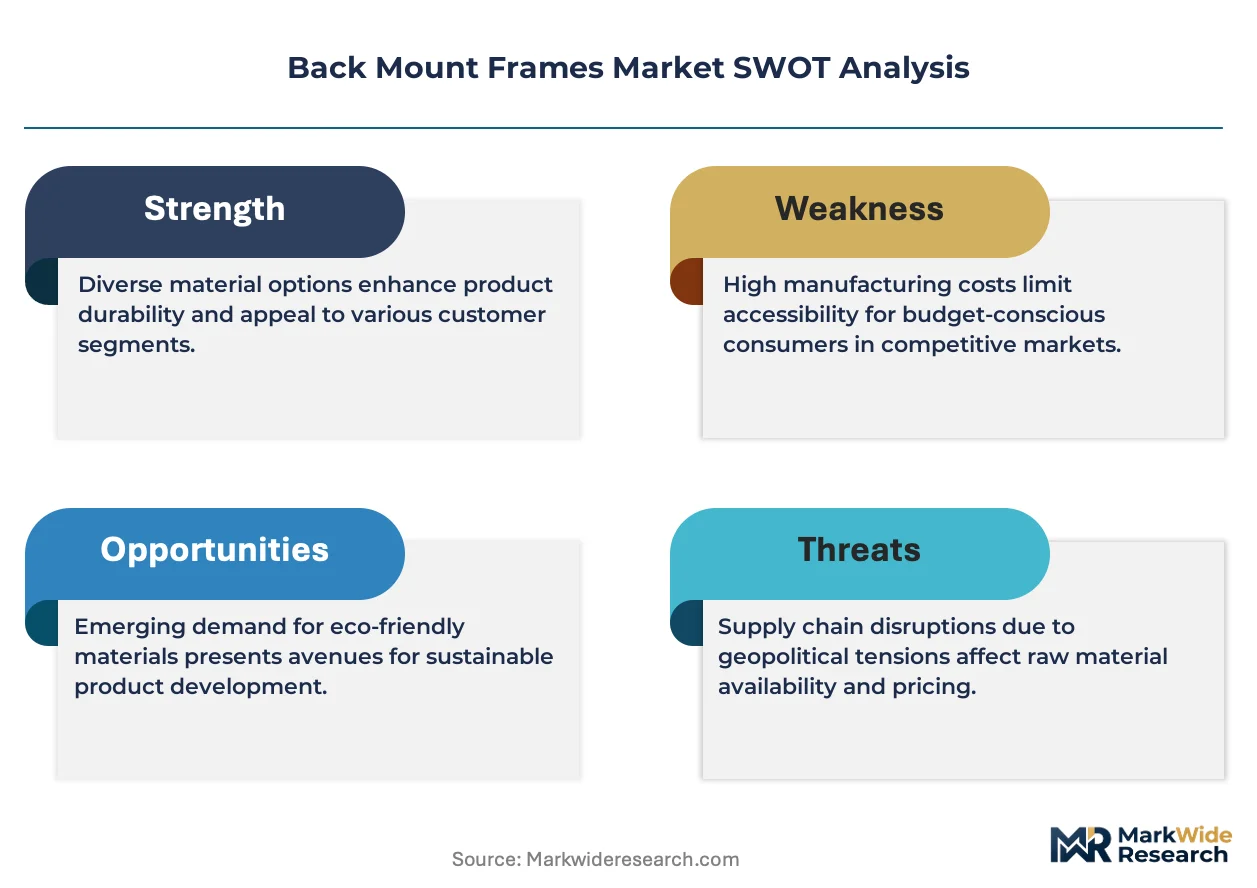
The back mount frames category is recalibrating around a widening gap between premium high-performance frames engineered for harsh industrial environments and commodity-grade plastic units serving cost-sensitive recreational applications. CommScope leverages its vertical integration into aluminum supply chains to sustain margin control across North American telecom deployments. Cabac differentiates through specialized steel-frame configurations that dominate Australian infrastructure projects. Essentra India Private Limited anchors its position with localized composite manufacturing that navigates India's import-duty landscape.
Back mount frames are structural hardware assemblies designed to secure equipment, cables, or components to rear-panel surfaces, typically fabricated from aluminum extrusions or cold-rolled steel with load ratings spanning 50 to 500 kilograms depending on application criticality. Their primary purpose centers on providing vibration-resistant, space-optimized mounting in telecommunications enclosures, medical device housings, and industrial control cabinets where front-access clearance remains constrained. Standard frames maintain volume leadership across mature markets where replacement cycles dominate purchasing patterns, while adjustable frames capture the fastest growth trajectory as modular data center designs proliferate and rack configurations require field-reconfigurable depth settings. Composite materials represent an emerging margin pool as weight-sensitive applications in portable medical equipment and aerospace ground support equipment seek alternatives to traditional metal assemblies.
The US FCC mandates structural integrity certifications for equipment deployed in federal telecommunications infrastructure, directly elevating demand for tested high-performance frame assemblies that withstand seismic and thermal stress protocols. India's BIS enforces dimensional and material standards on imported mounting hardware, creating compliance barriers that favor domestic producers such as ADC India Communications Ltd and Essentra India Private Limited. The EU REACH framework restricts certain chemical treatments in surface coatings, pushing European buyers toward aluminum and composite options over chromated steel variants. Stakeholders must monitor how diverging national certification regimes fragment product portfolios and force regional specialization strategies.
Market Dynamics
Telecommunications infrastructure buildouts in emerging markets are forcing suppliers to recalibrate around modular, field-reconfigurable frame systems that accommodate rapid rack reconfiguration without full replacement cycles.
Growth Catalysts
- Fiber-Optic Network Expansion:India's national broadband initiative and smart city mandates require massive deployment of cable management systems in dense urban corridors.
- RoHS Material Directives:The EU's restrictions on hazardous substances in surface coatings push buyers toward aluminum and composite alternatives over chromated steel variants.
- Seismic Certification Requirements:The US FCC mandates structural integrity testing for federal telecommunications infrastructure, elevating demand for vibration-resistant assemblies.
Market Restraints
- Aluminum Price Volatility:Cold-rolled steel and aluminum extrusion costs fluctuate with energy-intensive smelting operations concentrated in China and Russia.
- Import Duty Barriers:India's BIS dimensional and material standards on mounting hardware create compliance friction that disadvantages foreign suppliers.
- Composite Material Limitations:Load-bearing capacity constraints below 200 kilograms restrict polymer-based frames from heavy industrial cabinet applications.
Strategic Opportunities
- Portable Medical Equipment:Weight-sensitive applications in diagnostic device housings seek alternatives to traditional metal assemblies for mobility-critical deployments.
- Modular Data Center Designs:Adjustable frame configurations capture demand as hyperscale facilities require field-reconfigurable depth settings across changing rack densities.
- China's GB Standards Alignment:Structural safety harmonization creates export pathways for certified manufacturers into Belt and Road infrastructure projects.
Industry Challenges
- Certification Timeline Compression:Diverging national testing regimes for seismic, thermal, and chemical compliance force redundant validation cycles across product portfolios.
- Legacy Rack Integration:Retrofit compatibility with existing 19-inch and 23-inch mounting standards complicates new product development for mixed-generation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Mount Frames Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Frames, Adjustable Frames, High-Performance Frames, Custom Frames Material: Aluminum, Steel, Composite, Plastic Application: Sports, Industrial, Medical, Recreational End User: Athletes, Healthcare Professionals, DIY Enthusiasts, Manufacturers |
| Companies Covered | BOSCOM Communication Solutions, Comtec Cable Accessories Ltd., CommScope, Vlatek Pty Ltd, Strong Link, Cabac, Essentra India Private Limited, ADC India Communications Ltd, Kronect Comunicatii SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Mount Frames Market Strategic Shifts
Material science advances and procurement model evolution are compressing traditional product lifecycles while opening margin pools in specialized application segments previously dominated by generic metal fabrications.
Carbon-fiber-reinforced polymer composites are expanding into aerospace ground support equipment and portable medical housings where weight reduction outweighs premium pricing. Diagnostic equipment manufacturers in North America and Western Europe are specifying these materials for mobile imaging systems. The technology is expanding into adjacent industrial segments previously reserved for aluminum extrusions, compressing the addressable market for conventional metal frames in sub-200-kilogram load categories.
REACH surface-coating restrictions are eliminating hexavalent chromium treatments from European supply chains, forcing steel-frame suppliers to adopt trivalent alternatives or pivot to anodized aluminum. The regulation's industrial consequence extends beyond Europe as multinational OEMs harmonize specifications across regional production footprints. Medical device and telecommunications cabinet manufacturers serving EU markets are now specifying aluminum or composite options in global tender documents regardless of final deployment geography.
Consolidated procurement by hyperscale data center operators is unbundling after-sales service from hardware acquisition, pressuring traditional distribution channels. Direct manufacturer relationships with facility engineering teams are displacing distributor-mediated transactions in North American and European cloud infrastructure deployments. India and Southeast Asia exhibit similar concentration as national broadband agencies centralize mounting hardware purchasing through single-source framework agreements.
Back Mount Frames Market Segmentation
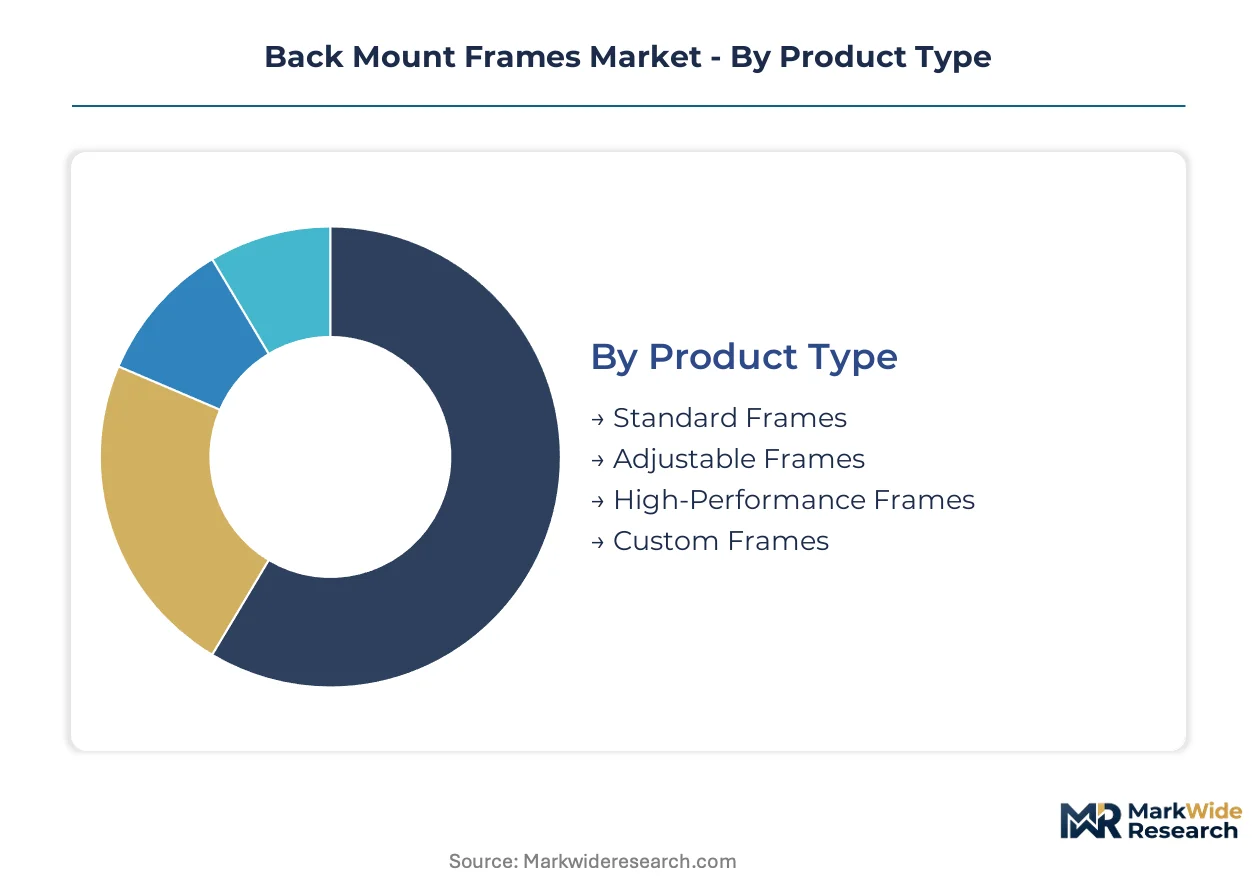
Back mount frames serve divergent functional requirements across telecommunications enclosures, medical device housings, and industrial control cabinets. Segmentation reveals how load specifications, material constraints, and access configurations fragment procurement patterns across end-use verticals.
Product Type:
Standalone frame assemblies dominate replacement-heavy mature markets, while embedded adjustable configurations integrate into modular infrastructure buildouts requiring field reconfiguration.
- Standard Frames:Fixed-dimension aluminum and steel extrusions with pre-drilled mounting patterns serve established rack specifications in legacy data center and telecom facilities. Procurement concentrates in North American federal infrastructure where FCC seismic certifications mandate tested assemblies for vibration resistance.
- Adjustable Frames:Field-reconfigurable depth settings accommodate changing rack densities without full replacement cycles. Demand clusters in hyperscale data center deployments across India and Southeast Asia where modular designs require rapid reconfiguration during capacity expansion.
- High-Performance Frames:Load-rated assemblies exceeding 300 kilograms for heavy industrial cabinet applications.
- Custom Frames:Application-specific fabrications for non-standard enclosure dimensions.
Volume placements concentrate in Standard Frames; the faster expansion belongs to Adjustable Frames.
Material:
Cost tiers separate premium metal assemblies from commodity-grade alternatives, with composite materials carving a mid-tier position in weight-sensitive mobility applications.
- Aluminum:Anodized extrusions dominate European procurement under REACH surface-coating restrictions that eliminate hexavalent chromium treatments from steel alternatives. Telecommunications cabinet manufacturers specify aluminum in global tenders regardless of final deployment geography.
- Steel:Cold-rolled configurations with trivalent chromium coatings retain cost advantage in heavy-load industrial segments exceeding 200-kilogram ratings.
- Composite:Carbon-fiber-reinforced polymers penetrate aerospace ground support and portable medical equipment where weight reduction commands premium positioning.
- Plastic:Injection-molded units serve recreational and light-duty applications with minimal load requirements.
Steel maintains volume leadership in industrial cabinets; aluminum gains share fastest in telecommunications and medical device specifications.
Application:
Application segmentation tracks how front-access constraints and vibration resistance requirements differentiate procurement across facility types and equipment mobility needs.
- Industrial:Seismic-rated steel and aluminum assemblies for control cabinets and manufacturing enclosures.
- Medical:Lightweight composite and aluminum frames for diagnostic device housings requiring frequent repositioning.
- Sports:Equipment mounting in training and competition facilities.
- Recreational:Cost-optimized plastic and basic metal units for consumer-grade installations.
Industrial applications anchor volume demand; medical equipment represents the steepest expansion trajectory as portable diagnostic systems proliferate.
End User:
Customer type determines whether procurement flows through consolidated framework agreements or fragmented distributor channels.
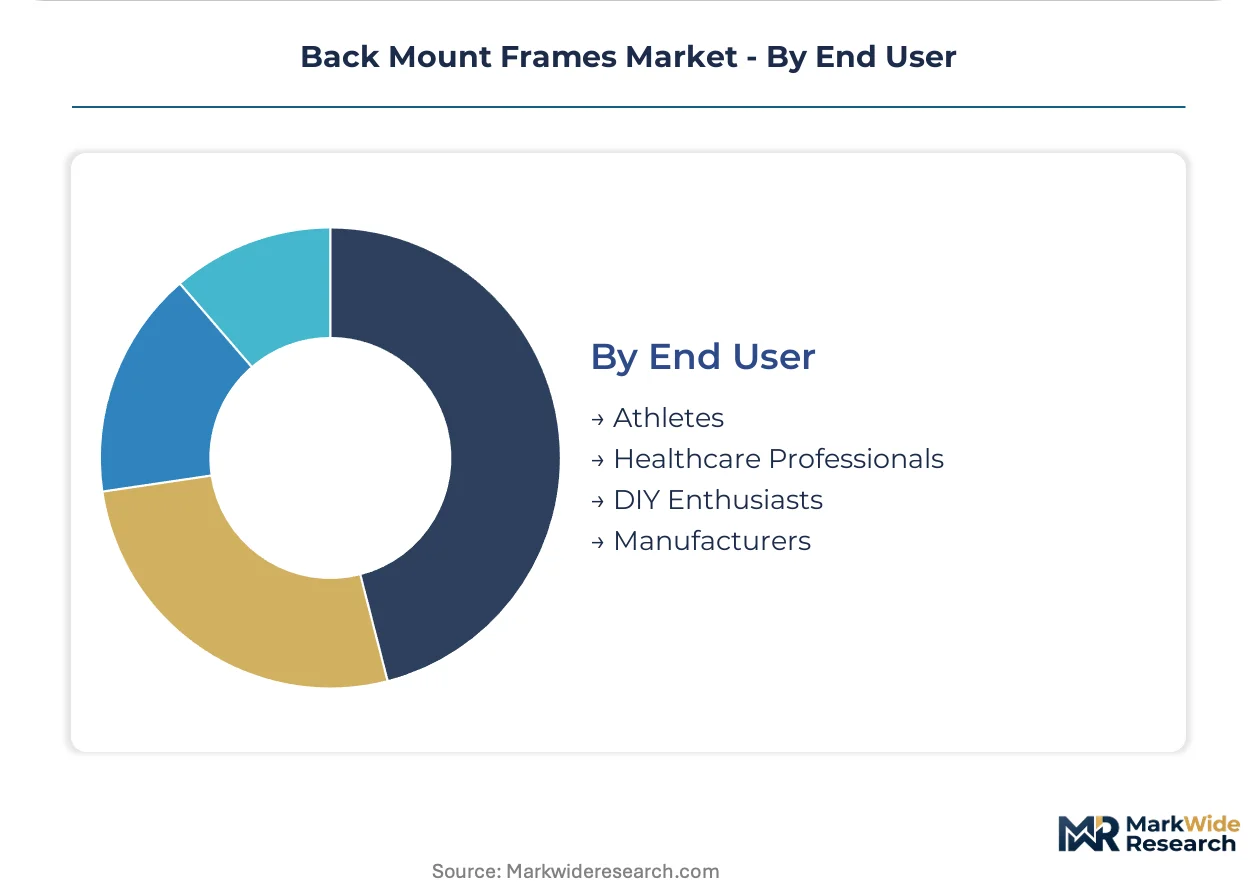
- Manufacturers:OEMs of telecommunications cabinets, medical devices, and industrial enclosures drive specification-setting for upstream frame suppliers.
- Healthcare Professionals:Hospital and clinic engineering teams prioritize weight reduction in mobile equipment procurement.
- Athletes:Training facility operators specify mounting hardware for specialized equipment installations.
- DIY Enthusiasts:Consumer purchasers of recreational and light-duty frame systems.
Manufacturers control the largest procurement volumes; healthcare professionals are expanding their specification influence fastest as diagnostic equipment mobility requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors global back mount frame production, with adjacent Dongguan and Guangzhou forming a dense supplier network serving telecommunications infrastructure buildouts across Asia-Pacific and Belt and Road corridors.
United States
Federal telecommunications infrastructure modernization and hyperscale data center expansion in Northern Virginia and Dallas-Fort Worth drive specification-grade frame demand. The FCC mandates structural integrity certifications for seismic and thermal stress resistance in federal deployments. Phoenix and Atlanta industrial zones concentrate domestic fabrication capacity for rapid-response cabinet assembly.
China
National broadband initiative acceleration and smart city infrastructure in the Yangtze River Delta generate massive standardized mounting hardware procurement. GB standards for structural safety and material composition reshape export specifications across Belt and Road supply chains. Suzhou and Hangzhou manufacturing clusters dominate aluminum extrusion and cold-rolled steel frame production for domestic and regional markets.
Germany
Industrial automation upgrade cycles and medical device manufacturing in Baden-Württemberg sustain premium frame specifications. REACH surface-coating restrictions eliminate hexavalent chromium treatments, pushing buyers toward anodized aluminum alternatives. Munich and Stuttgart engineering centers drive specification-setting for EU-wide telecommunications and medical equipment procurement.
India
National broadband expansion and smart city mandates in Maharashtra and Karnataka require massive cable management system deployment in dense urban corridors. BIS dimensional and material standards on imported mounting hardware create compliance barriers favoring domestic producers. Chennai and Pune industrial zones concentrate localized composite manufacturing that navigates import-duty landscapes.
Japan
Telecommunications infrastructure resilience upgrades and precision medical equipment manufacturing sustain demand for vibration-resistant assemblies. METI industrial standards and JIS certification requirements elevate procurement specifications for seismic-rated configurations. Osaka and Nagoya industrial corridors anchor domestic fabrication for specialized high-performance applications.
Back Mount Frames Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and load-rating dimensions, with seismic-rated and REACH-compliant aluminum assemblies commanding pricing separation from basic steel configurations. The vendor base organizes around three strategic archetypes: vertically integrated aluminum specialists, regional steel-frame fabricators with trivalent coating capabilities, and composite material innovators serving weight-sensitive mobility applications. Dominant competitive moves include backward integration into captive aluminum supply chains and strategic partnerships with hyperscale data center engineering teams that displace traditional distribution channels.
Among the named participants, CommScope exemplifies the vertically integrated archetype with upstream control over aluminum supply chains, while Cabac occupies a position within regional steel-frame specialization. Essentra India Private Limited anchors the localized manufacturing tier, navigating India's BIS compliance landscape through domestic composite production. These three represent the structural segmentation between premium-certified, regionally optimized, and import-duty-advantaged competitive positions.
| Leading Market Players |
|---|
| BOSCOM Communication Solutions |
| Comtec Cable Accessories Ltd. |
| CommScope |
| Vlatek Pty Ltd |
| Strong Link |
| Cabac |
| Essentra India Private Limited |
| ADC India Communications Ltd |
| Kronect Comunicatii SRL |
| Others |
Value Chain & Pricing Dynamics
Captive aluminum supply chains anchor CommScope's margin control across North American telecom deployments, positioning upstream control as the decisive pricing lever against spot-market-dependent competitors. This backward integration into extrusion and smelting operations insulates premium-tier producers from energy-intensive input volatility while forcing steel-frame rivals to absorb commodity price swings.
Pricing Analysis
Seismic certification value anchors price tiers across federal telecommunications procurement, with FCC-tested assemblies commanding substantial premiums over unrated alternatives. Price differentiation separates REACH-compliant anodized aluminum from trivalent chromium steel and commodity-grade plastic configurations. Cost compression in standard steel frames intensifies as Chinese extrusion capacity floods Asian markets. Hyperscale data center operators exhibit lowest price sensitivity due to consolidated framework agreements, while DIY recreational purchasers drive economy-tier volume.
Supply Chain Analysis
Skilled technician availability in Shenzhen, Dongguan, and Suzhou manufacturing clusters sustains China's dominance in precision aluminum extrusion for telecommunications-grade frames. Raw material sourcing draws from Australian bauxite, Russian smelter output, and domestic Chinese cold-rolled steel capacity. Single-source vulnerability concentrates in energy-intensive aluminum smelting operations subject to power rationing. Distribution runs through direct manufacturer relationships with hyperscale facility engineering teams, displacing traditional distributor channels in North American and European cloud infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive aluminum supply chains defines competitive positioning, with upstream control over extrusion capacity emerging as the decisive margin defense against commodity spot-market exposure.
For Market Incumbents: Extend certification portfolios to cover India's BIS dimensional standards and China's GB structural safety requirements before domestic producers solidify import-substitution advantages. Deepen captive supply of anodized aluminum extrusions to sustain REACH compliance leadership as European coating restrictions tighten. Carbon-fiber composite entrants threaten sub-200-kilogram load segments in portable medical equipment.
For New Entrants and Emerging Players: The premium-to-economy price gap in adjustable frame configurations offers white-space entry for mid-tier specialists serving modular data center expansion in India and Southeast Asia. Target smart city cable management deployments in Maharashtra and Karnataka where BIS compliance barriers disadvantage foreign incumbents. Pursue direct engineering partnerships with national broadband agencies to bypass entrenched distribution relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscale data center operators seeking captive mounting hardware supply. Long-term viability favors vertically integrated aluminum specialists with demonstrated FCC seismic certification and REACH anodization capabilities. Watch for India's PLI scheme expansion into telecommunications components as inflection signal for domestic production advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply chains insulate margins from energy-intensive smelting volatility concentrated in China and Russia. |
| Multi-Jurisdiction Certification Investment | Simultaneous FCC seismic, BIS dimensional, and GB structural compliance unlocks federal and Belt and Road procurement. |
| Direct Hyperscale Partnership Development | Engineering team relationships displace distributor channels in Northern Virginia and Dallas-Fort Worth data center corridors. |
| Carbon-Fiber Composite Scale-Up | Weight reduction specifications from portable medical OEMs in North America and Western Europe open premium positioning. |
| Localized Composite Manufacturing | Domestic production in Chennai and Pune industrial zones navigates India's BIS import-duty landscape. |
Study Parameters
Independent corroboration across telecommunications infrastructure procurement officers, data center facility engineering directors, medical device OEM supply chain managers, and aluminum extrusion plant managers underwrites the qualitative findings. Primary interview data combined with secondary validation from FCC certification databases, BIS standards publications, EU REACH regulatory filings, and hyperscaler capital expenditure disclosures. Bottom-up shipment analysis and top-down infrastructure investment triangulation anchor volume estimates.
Comparable historical reference periods spanning replacement-cycle-dominated mature markets and modular buildout-intensive emerging economies anchored the projection window. Segmentation modeling incorporated product type, material grade, load rating tier, application vertical, and end-user procurement channel across the analysis window. CAGRs derived from infrastructure deployment pipelines, regulatory compliance timelines, and material substitution elasticities in weight-sensitive applications.
Underlying measurement precision varies by segment; standardized frame volumes in North American federal infrastructure carry tighter precision than emerging composite material penetration rates. Forecasts reflect assumptions regarding aluminum price stabilization, BIS enforcement consistency, and hyperscale data center expansion continuity. Material deviation in Chinese energy policy, Indian import-duty restructuring, or REACH coating restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United States Upholstered Furniture Market
Furniture
Entryway Furniture Market
Furniture
Italy Office Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Children's Home Study Desks Market
Furniture
Europe School Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Ergonomic Chair Market
Furniture
North America High-End Furniture Market
Furniture
Rattan Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
North America Home Furniture Market
Furniture
Eco-Friendly Furniture Market