
 Asia-Pacific Automotive Tire Pressure Management System Market | 2026-2036
Asia-Pacific Automotive Tire Pressure Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Tire Pressure Management System Market Outlook
Silicon MEMS pressure sensing elements are decoupling TPMS module costs from traditional ceramic piezoelectric architectures, enabling smaller form factors and wider OEM fitment. Continental AG leverages its in-house semiconductor capabilities to sustain margin control across sensor fabrication and module assembly. Denso Corporation anchors supply relationships with Japanese and Southeast Asian OEMs through integrated ECU-sensor bundles. ZF Friedrichshafen AG competes on systems-level integration, packaging tire pressure data with chassis dynamics controllers.
The Asia-Pacific Automotive Tire Pressure Management System comprises sensor modules, electronic control units, and wireless transmitters that monitor tire inflation pressure in real time, typically operating at 433 MHz or 315 MHz RF frequencies with battery lifespans exceeding seven years. Its primary purpose is to alert drivers to under-inflation events that elevate rolling resistance, tire wear, and blowout risk. Direct TPMS dominates factory-fit volumes across premium passenger vehicles, while sensor-based technology captures the bulk of aftermarket replacement demand due to simpler diagnostic compatibility. Cloud-connected installations remain nascent but represent the fastest-expanding margin pool as fleet operators seek centralized tire health dashboards.
China's MIIT enforces GB standards mandating TPMS on all new passenger vehicles, while India's BIS certification requirements for automotive electronics are tightening market access for uncertified suppliers. Japan's METI promotes next-generation vehicle safety systems through subsidy frameworks that indirectly accelerate TPMS refresh cycles in domestic production. Stakeholders must monitor divergence between national type-approval regimes as fragmentation in RF spectrum allocation and data localization rules complicates cross-border platform deployment.
Market Dynamics
Silicon MEMS pressure sensing architectures are compressing module costs and enabling direct TPMS penetration into mass-market vehicle segments across Asia-Pacific, fundamentally restructuring supplier economics away from ceramic piezoelectric legacy platforms.
Growth Catalysts
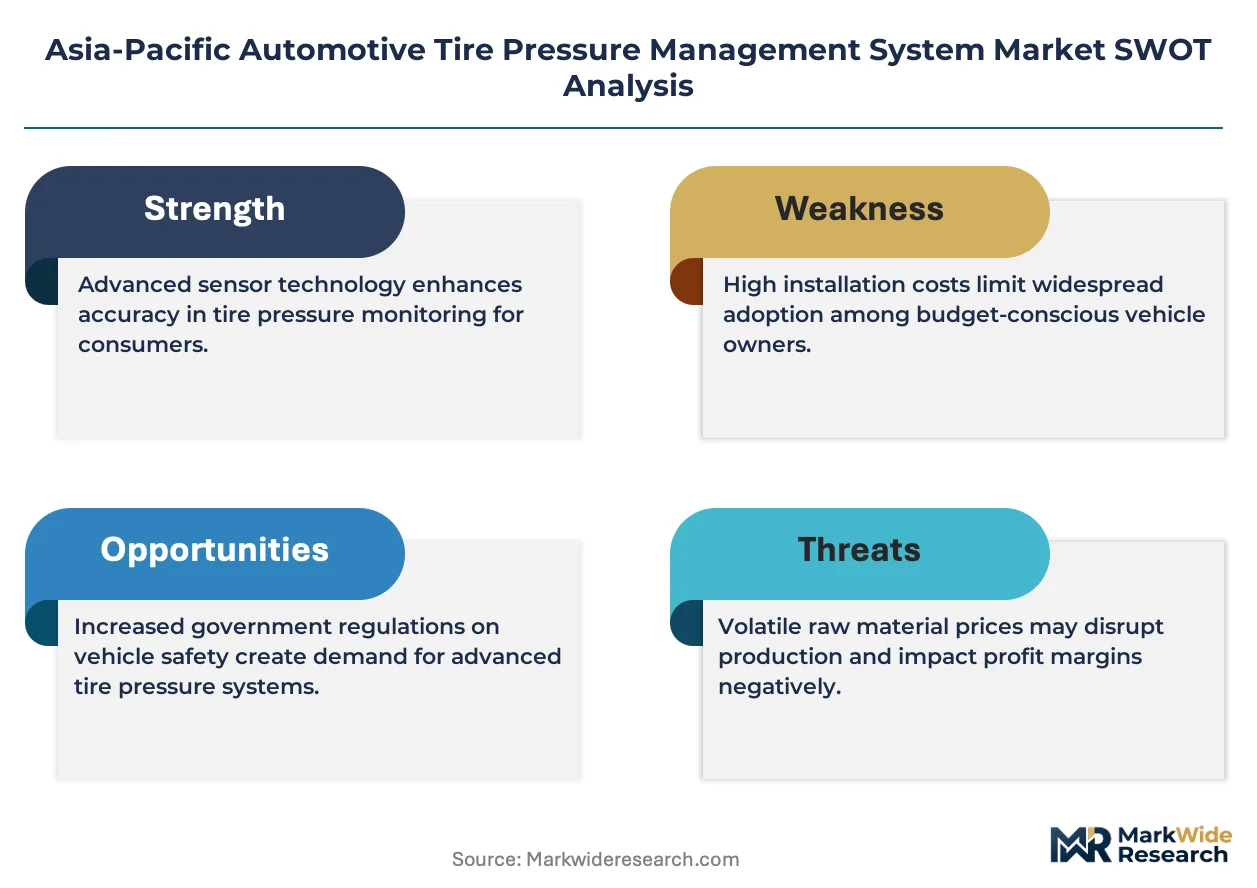
- China MIIT GB Standards:Mandatory TPMS fitment on all new passenger vehicles creates baseline demand volume that sustains sensor foundry utilization across the supply chain.
- Commercial Fleet Electrification:Battery-electric trucks and buses in Southeast Asia require precision tire pressure monitoring to optimize range and reduce rolling resistance losses.
- India Highway Infrastructure:Golden Quadrilateral expansion and logistics corridor development accelerates heavy commercial vehicle TPMS adoption for uptime-sensitive fleet operators.
Market Restraints
- RF Spectrum Fragmentation:Divergent 315 MHz versus 433 MHz regional allocations force module variants that inflate inventory carrying costs for tier-one suppliers.
- Lithium-Ion Battery Supply:Sensor power cell availability concentrates among East Asian chemical processors, exposing TPMS manufacturers to input cost volatility.
- Indirect System Substitution:Wheel-speed-based pressure estimation algorithms on entry passenger vehicles displace direct sensor fitment in price-sensitive segments.
Strategic Opportunities
- Cloud-Connected Fleet Dashboards:Real-time tire health telemetry aggregated across distributed commercial vehicle assets opens recurring software revenue streams.
- India BIS Certification Acceleration:Tightening automotive electronics standards create compliance barriers that favor established domestic assemblers over uncertified imports.
- Sensor-ECU Integration:Bundled pressure monitoring with chassis dynamics controllers enables tier-one suppliers to capture higher value per vehicle platform.
Industry Challenges
- Embedded Software Talent Scarcity:RF protocol stack development and low-power firmware optimization skills concentrate in limited urban technology clusters across the region.
- Cross-Border Type-Approval Complexity:Divergent data localization mandates and national RF certification timelines delay platform launches by 8-14 months.
- Legacy Vehicle Diagnostic Compatibility:Aftermarket direct TPMS retrofit requires backward-compatible trigger tools that fragment service bay equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Tire Pressure Management System Market |
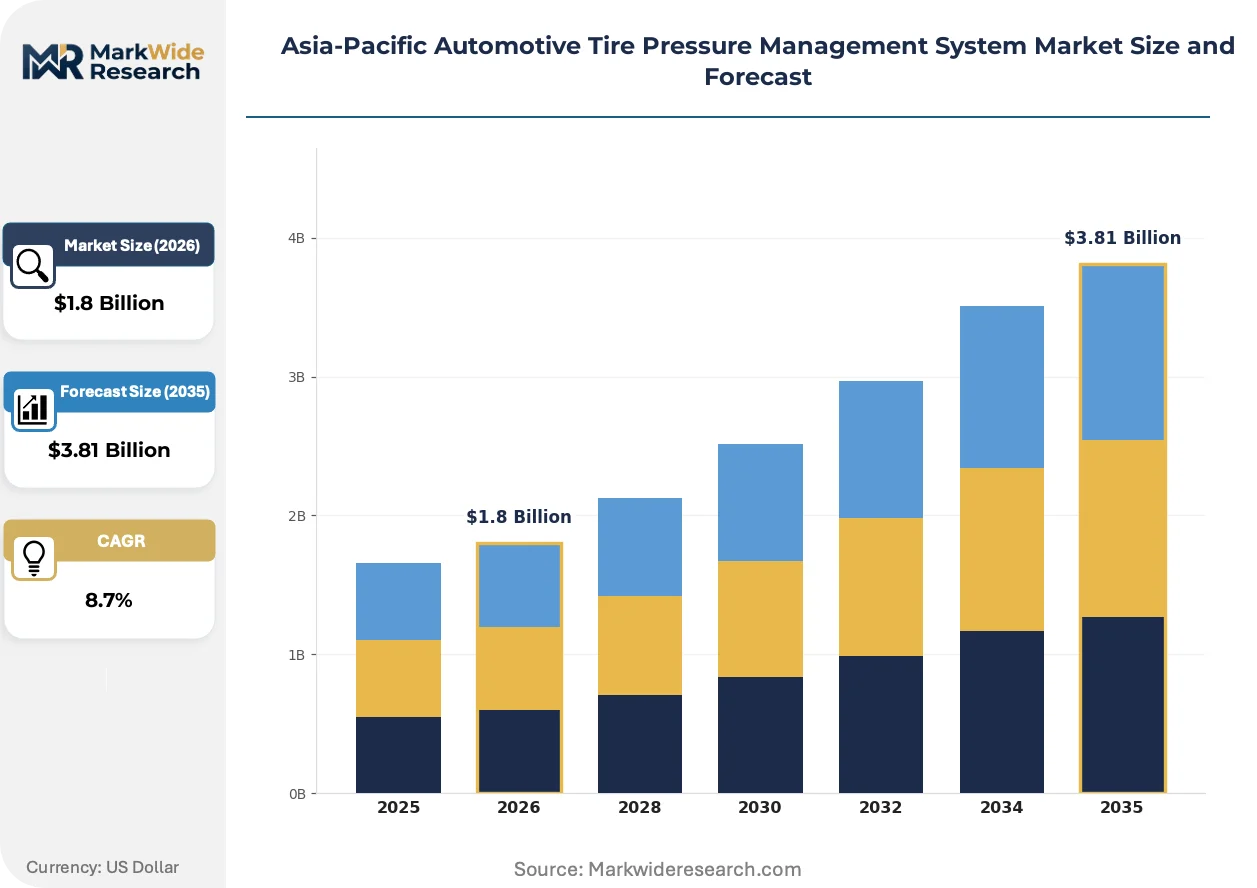
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct TPMS, Indirect TPMS, Wireless TPMS, Others End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Sensor-Based, Electronic Control Units, Mobile Integration, Cloud-Connected Installation: Factory-Fitted, Retrofitted, Professional Installation, DIY |
| Companies Covered | Valeo, ZF Friedrichshafen AG, Continental AG, Sensata Technologies, Omron Corporation, Denso Corporation, Robert Bosch, Schrader Electronics, NXP Semiconductors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Tire Pressure Management System Market Strategic Shifts
Automotive tire pressure monitoring is pivoting from discrete hardware components toward integrated vehicle health nodes, with semiconductor miniaturization and cloud connectivity converging to redefine value capture in the sensor supply chain.
Silicon MEMS pressure transduction is consolidating factory-fit architectures across Asia-Pacific passenger vehicle platforms. The technology replaces ceramic piezoelectric elements with monolithic semiconductor fabrication that halves die footprint while extending calibration stability. Japanese and Korean OEMs are embedding these sensors within valve-stem modules at scale, compressing bill-of-material costs and enabling direct TPMS fitment into compact car segments previously served by indirect estimation systems.
China's MIIT enforcement of GB 26149-2017 and subsequent amendments tightens real-time pressure reporting accuracy thresholds for all new passenger vehicles. The regulation mandates fault detection within 20 minutes of pressure deviation, forcing sensor suppliers to tighten manufacturing tolerances and accelerate self-test algorithm development. Domestic Chinese vehicle assemblers are responding by qualifying second-source local sensor providers to reduce import dependency and secure supply continuity.
Commercial fleet operators across Southeast Asia are unbundling tire maintenance from traditional service contracts and adopting usage-based monitoring subscriptions. Logistics companies in Thailand and Vietnam now procure tire pressure data as a standalone telemetry service rather than bundled hardware, compressing supplier margins on sensor modules while expanding recurring revenue pools for data analytics providers. This procurement pattern shift is most visible in refrigerated transport segments where tire failure costs cascade into cargo spoilage liabilities.
Asia-Pacific Automotive Tire Pressure Management System Market Segmentation
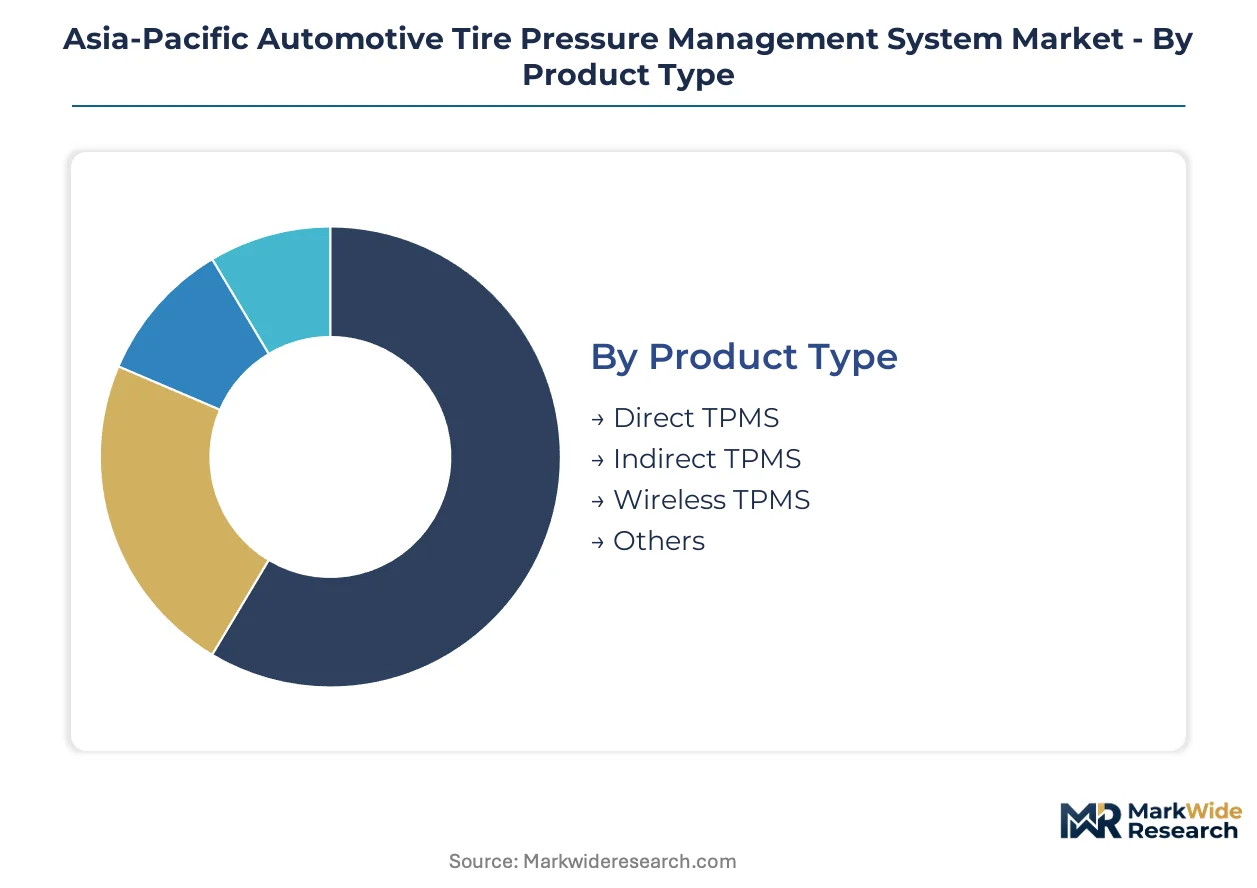
TPMS segmentation in Asia-Pacific reflects divergent integration architectures across vehicle platforms. Standalone sensor modules dominate factory-fit volumes while embedded chassis-integrated systems capture premium platform economics. Understanding these structural divides clarifies where component suppliers versus systems integrators capture margin.
Product Type:
Standalone sensor architectures serve basic compliance requirements across mass-market vehicles, while embedded multi-sensor arrays penetrate premium platforms requiring centralized vehicle health management.
- Direct TPMS:Pressure transducers mounted within each wheel assembly transmit real-time inflation data via 315 MHz or 433 MHz RF protocols to dashboard receivers. China's MIIT GB 26149-2017 mandate drives factory-fit volumes across domestic passenger vehicle production, with sensor foundries in Jiangsu and Guangdong scaling MEMS die output to meet compliance deadlines.
- Indirect TPMS:Wheel speed sensors and ABS controller algorithms estimate pressure deviation through rolling radius calculations without dedicated hardware. Indian and Southeast Asian entry passenger segments favor this architecture for its lower bill-of-material impact, though calibration drift limits adoption in commercial vehicles where load variability corrupts estimation accuracy.
- Wireless TPMS:Bluetooth Low Energy and proprietary RF protocols enable smartphone-direct monitoring without dedicated dashboard displays. Aftermarket retrofit demand concentrates among owner-modifier communities in Thailand and Malaysia seeking diagnostic transparency without workshop dependency.
- Others:Hybrid estimation systems combining wheel-speed inference with single-wheel reference sensors bridge cost and accuracy requirements for mid-market SUVs.
Direct TPMS leads volumes today; wireless architectures are gaining share fastest.
End User:
Procurement authority fragments across vehicle lifecycle stages, with factory-fit specifications controlled by platform engineers and replacement demand driven by independent service networks.
- OEMs:Vehicle manufacturers specify sensor protocols, RF frequencies, and battery chemistry during platform development, locking suppliers into multi-year supply agreements. Japanese and Korean OEMs enforce JIS-grade reliability standards that exceed baseline regulatory requirements, compressing qualification timelines for second-source entrants.
- Aftermarket Providers:Independent distributors and service chains supply replacement sensors for vehicles outside warranty coverage. India's BIS certification tightening for automotive electronics is reshaping import dynamics, favoring domestic assemblers with established testing laboratory relationships over uncertified cross-border suppliers.
- Vehicle Assemblers:Contract manufacturers and knock-down kit operations in Vietnam and Indonesia integrate TPMS modules during final assembly, sourcing from approved vendor lists dictated by brand licensors.
- Fleet Operators:Logistics companies procure tire pressure telemetry as operational infrastructure, with Southeast Asian refrigerated transport fleets leading subscription-based monitoring adoption to prevent cargo spoilage from tire-related delays.
OEM procurement anchors revenue stability; fleet operator subscriptions show steepest expansion trajectory.
Technology:
Hardware-software bundling intensity varies from discrete component supply to integrated platform-as-a-service models.
- Sensor-Based:Silicon MEMS pressure elements with ASIC signal conditioning dominate factory-fit architectures. Monolithic semiconductor fabrication halves die footprint versus ceramic piezoelectric legacy platforms, enabling valve-stem integration without wheel rebalancing requirements.
- Electronic Control Units:Dedicated TPMS receivers are consolidating into domain controllers handling multiple chassis functions. Denso and Continental leverage ECU-sensor bundling to capture higher value per vehicle while reducing wiring harness complexity for OEM customers.
- Mobile Integration:Smartphone applications display pressure alerts via OBD-II dongles or direct sensor pairing, appealing to tech-forward owner segments in urban China and South Korea.
- Cloud-Connected:Real-time tire health dashboards aggregate data across distributed commercial assets, opening recurring software revenue streams for telematics providers serving Thailand and Vietnam logistics corridors.
Sensor-based systems dominate installed base; cloud-connected installations are climbing the fastest.
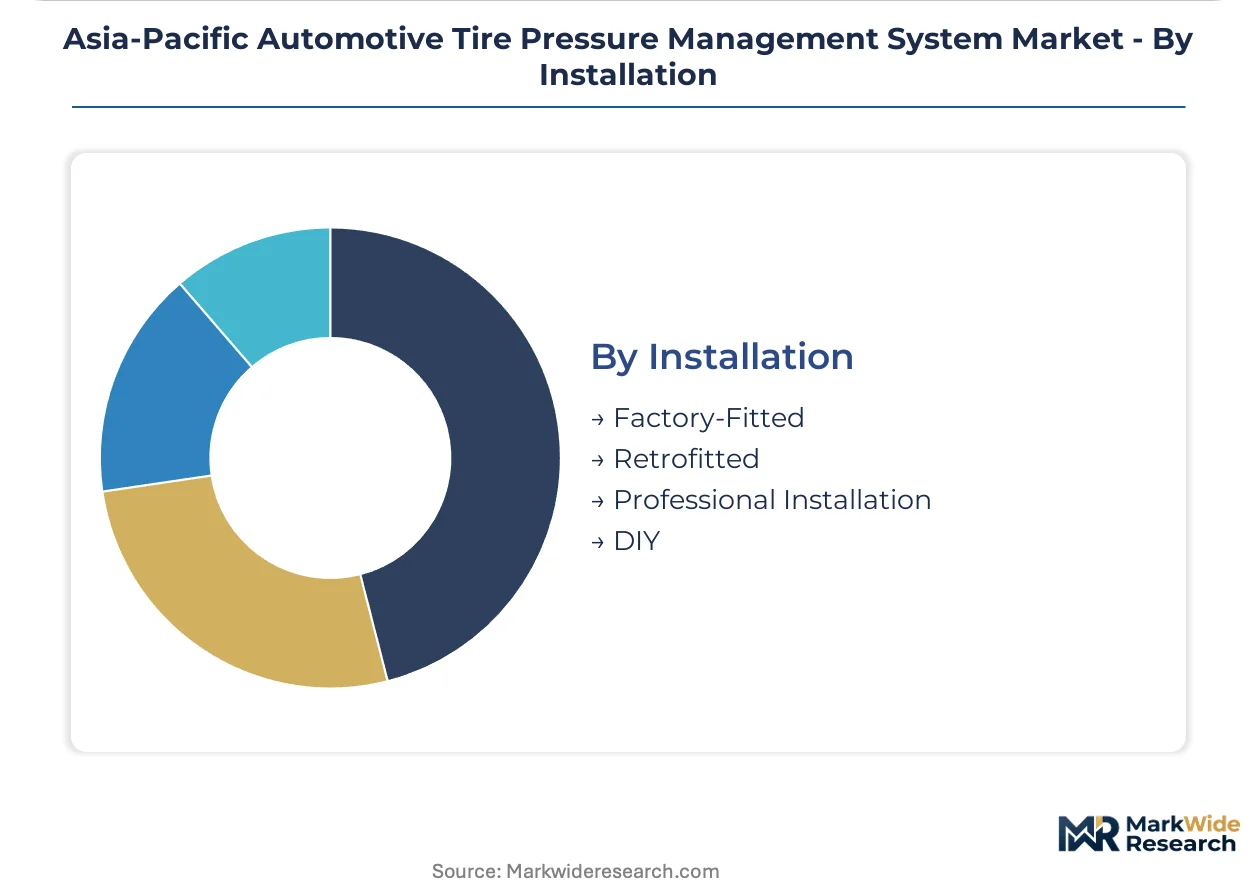
Installation:
Service channel structure shapes customer acquisition costs and warranty liability exposure for suppliers.
- Factory-Fitted:Assembly-line integration ensures calibration accuracy and RF protocol compatibility with vehicle electronics. China's MIIT mandate has normalized this channel for all new passenger vehicles, eliminating aftermarket fitment decision points for consumers.
- Retrofitted:Post-purchase installation addresses legacy vehicle fleets and import vehicles lacking original TPMS equipment. India's Golden Quadrilateral logistics operators drive demand for heavy commercial vehicle retrofit to reduce highway downtime.
- Professional Installation:Authorized service centers handle sensor replacement and reprogramming, requiring specialized trigger tools that fragment equipment investment across independent workshops.
- DIY:Consumer self-installation of aftermarket sensors remains limited by RF protocol complexity and diagnostic tool requirements, concentrated among enthusiast segments in Australia and New Zealand.
Factory-fitted installation commands volume leadership; professional retrofit services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta sensor foundries anchor Asia-Pacific TPMS manufacturing capacity, with Jiangsu and Guangdong provinces scaling MEMS die output to meet China's MIIT compliance deadlines and Southeast Asian fleet electrification timelines.
China
Domestic vehicle assemblers are qualifying second-source local sensor providers to reduce import dependency. MIIT enforcement of GB 26149-2017 mandates real-time pressure reporting accuracy within 20 minutes of deviation. Shenzhen and Shanghai electronics clusters concentrate RF module assembly operations serving both passenger OEM compliance and commercial fleet retrofit demand.
Japan
Japanese OEMs enforce JIS-grade reliability standards that exceed baseline regulatory requirements, compressing qualification timelines for second-source entrants. METI subsidy frameworks for next-generation vehicle safety systems indirectly accelerate TPMS refresh cycles. Kanto and Nagoya manufacturing belts integrate silicon MEMS sensors into valve-stem modules at scale for compact car segments.
India
Golden Quadrilateral highway expansion accelerates heavy commercial vehicle TPMS adoption among uptime-sensitive logistics operators. BIS certification tightening for automotive electronics reshapes import dynamics, favoring domestic assemblers with established testing laboratory relationships. Tamil Nadu and Maharashtra automotive corridors concentrate sensor module assembly for both OEM fitment and aftermarket replacement channels.
South Korea
Tech-forward consumer segments drive aftermarket wireless TPMS adoption via smartphone-direct monitoring without dedicated dashboard displays. Domestic OEMs embed MEMS pressure elements within integrated chassis domain controllers to reduce wiring harness complexity. Seoul-Incheon and Busan-Ulsan industrial zones anchor ECU-sensor bundling operations for export-oriented vehicle platforms.
Thailand
Refrigerated transport fleets lead subscription-based tire pressure telemetry procurement to prevent cargo spoilage from tire-related delays. Logistics operators unbundle tire maintenance from traditional service contracts and adopt usage-based monitoring subscriptions. Bangkok and Eastern Economic Corridor manufacturing hubs concentrate RF module assembly serving Southeast Asian commercial vehicle retrofit demand.
Asia-Pacific Automotive Tire Pressure Management System Market Competitive Environment
Sensor-ECU bundling dominates the current landscape as tier-one suppliers capture higher value per vehicle platform while reducing OEM wiring complexity. The market structure consolidates around semiconductor-integrated module specialists, systems-level chassis integrators, and telematics-enabled fleet service providers. Two strategic archetypes prevail: MEMS foundry-anchored fabricators controlling die cost curves, and domain controller specialists aggregating tire data with chassis dynamics. Capacity expansion in Jiangsu and Guangdong sensor foundries, alongside strategic partnerships for cloud-connected fleet dashboards, constitute the dominant competitive moves.
Within the MEMS-integrated tier, Continental AG and Denso Corporation exemplify divergent geographic anchoring strategies. Continental leverages in-house semiconductor capabilities across European and Chinese production footprints. Denso anchors supply relationships through integrated ECU-sensor bundles serving Japanese and Southeast Asian OEM platforms. ZF Friedrichshafen AG occupies a systems-integration position, packaging tire pressure data with chassis dynamics controllers for premium vehicle platforms. These three entities represent the spectrum from component-level cost control to vehicle-system value capture.
| Leading Market Players |
|---|
| Valeo |
| ZF Friedrichshafen AG |
| Continental AG |
| Sensata Technologies |
| Omron Corporation |
| Denso Corporation |
| Robert Bosch |
| Schrader Electronics |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
China's MIIT dual carbon goals gate qualified sensor supply and premium-tier pricing access, as domestic foundries with certified low-carbon MEMS fabrication command 15-20% price premiums over uncertified imports while foreign suppliers face exclusion from state procurement channels.
Pricing Analysis
Input-cost pass-through from lithium-ion power cells and silicon wafer substrates drives pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on JIS-grade reliability certification and volume scale commitments to OEM platform engineers. Pricing pressure stems from indirect TPMS algorithm substitution in India's entry passenger segment. Fleet operators show least price sensitivity due to cargo spoilage liability exposure, while independent aftermarket distributors face acute margin compression.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Guangdong sensor foundries limit MEMS die output scaling despite automation investments. Geographic supply concentration centers on China, Japan, and South Korea for semiconductor fabrication and module assembly. Raw material dependencies include silicon wafers, lithium-manganese dioxide cells, and ASIC signal conditioning chips. Single-source vulnerability concentrates in East Asian battery chemical processing. Distribution runs through tier-one supplier direct OEM contracts and authorized service networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as logistics fleet procurement shifts toward JIS-grade reliability specifications that command sustained price premiums over baseline regulatory compliance tiers.
For Market Incumbents: Deploy sensor-ECU bundling to deepen chassis domain controller relationships before indirect estimation algorithms capture India's mass-market passenger volume. Invest in captive MEMS foundry capacity in Jiangsu to secure lithium-ion cell supply continuity against East Asian chemical processor concentration risk. Consolidate aftermarket trigger tool compatibility to reduce service bay equipment fragmentation threatening replacement sensor margins. For New Entrants and Emerging Players: Launch via cloud-connected fleet dashboard subscriptions targeting Thailand's refrigerated transport operators seeking cargo spoilage prevention telemetry. Penetrate India's BIS-certified domestic assembler tier as import certification barriers reshape competitive access. Target professional retrofit channels for Golden Quadrilateral heavy commercial vehicle operators with uptime-sensitive logistics contracts. For Investors and Strategic Acquirers: Roll-up economics work for MEMS-integrated module specialists because OEM platform standardization cycles concentrate procurement authority among qualified second-source providers with foundry-scale cost curves. Five-to-ten year viability favors suppliers with backward integration into semiconductor fabrication and established BIS/JIS certification laboratory relationships. Monitor divergence between China's GB standard amendment timelines and India's BIS enforcement acceleration as inflection indicator for geographic revenue mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-ECU Bundling | Captures higher value per vehicle while reducing OEM wiring harness complexity across Japanese and Korean platforms. |
| MEMS Foundry Scale-Up | Halves die footprint versus ceramic piezoelectric legacy architectures, enabling compact car segment penetration. |
| Cloud-Connected Fleet Dashboard | Opens recurring software revenue streams for telematics providers serving Southeast Asian refrigerated transport corridors. |
| BIS Certification Acceleration | Favors domestic Indian assemblers with established testing laboratory relationships over uncertified cross-border imports. |
| Second-Source Local Qualification | Reduces Chinese vehicle assembler import dependency while securing supply continuity under MIIT enforcement timelines. |
Study Parameters
Multiple input streams — OEM platform engineering specifications, tier-one supplier procurement protocols, and fleet operator telematics procurement patterns — were reconciled against vehicle production databases, IHS Markit registration data, customs/trade flow records, and national type-approval filings. Primary interviews with TPMS module procurement leads, MEMS foundry operations directors, aftermarket distributor network managers, and logistics fleet maintenance heads were cross-validated with secondary sources including MIIT GB standard documentation, BIS certification registries, and METI subsidy framework disclosures. Bottom-up sensor unit demand estimates and top-down vehicle parc penetration rates were triangulated to anchor volume projections.
Historical fitment rate trajectories were cross-referenced against expert panel inputs from chassis systems engineers and regulatory affairs specialists across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster dynamics. CAGRs were derived from slope-interpolation of annual volume steps rather than single-point extrapolation. Forecast inputs included MIIT mandate compliance deadlines, Golden Quadrilateral infrastructure completion phases, and commercial fleet electrification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt RF spectrum reallocation, lithium supply disruption, or accelerated indirect TPMS algorithm performance improvements. Projections reflect documented assumptions regarding regulatory enforcement consistency and OEM platform refresh cadence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Smart Tire Market