
 India Winglets Market | 2026-2036
India Winglets Market Size, Share, and Industry Trends Forecast 2026-2036
India Winglets Market Insights
Modular retrofit kits bundled with structural health monitoring is expanding buyer choice across India's airline operators. Aviation Partners Boeing leverages its joint-venture platform to sustain technology transfer advantages in the domestic market. Hindustan Aeronautics Limited anchors indigenous manufacturing capabilities for military winglet programs. GKN Aerospace competes through specialized composite fabrication expertise serving both commercial and defense channels.
Winglets are aerodynamic surface extensions mounted at aircraft wingtips, typically fabricated from carbon-fiber-reinforced polymer composites with aluminum alloy substructures, designed to reduce induced drag by disrupting harmful wingtip vortices and improving lift-to-drag ratios by measurable margins. Blended winglets dominate current retrofit volumes across India's narrow-body fleet, while active control systems represent the emerging technology tier with higher margin potential. Commercial aviation absorbs the majority of installations, though military aviation programs through HAL are cultivating a parallel demand track with distinct certification requirements.
The Directorate General of Civil Aviation enforces airworthiness directives that mandate fatigue-life assessments for winglet modifications, while BIS standards govern composite material specifications for domestic suppliers. The PLI scheme for aerospace and defense manufacturing incentivizes local production of aerostructures, reshaping supplier economics for foreign OEMs. Stakeholders must monitor how DGCA's evolving certification timelines interact with airline fleet renewal cycles to capture retrofit windows before next-generation aircraft deliveries displace upgrade demand.
Market Dynamics
Composite manufacturing advances are compressing winglet production cycles while DGCA airworthiness mandates force retrofit timelines across India's narrow-body fleet. These intersecting pressures create a procurement window where airlines must upgrade before next-generation aircraft deliveries eliminate retrofit economics.
Growth Catalysts
- PLI scheme incentives:The Production Linked Incentive scheme for aerospace manufacturing subsidizes domestic aerostructure fabrication, lowering landed costs for carbon-fiber composite winglet assemblies.
- Fuel efficiency mandates:Commercial aviation operators face sustained pressure from aviation turbine fuel price volatility, driving adoption of drag-reducing wingtip devices as operational cost controls.
- MRO cluster concentration:Maintenance, repair, and overhaul facilities in Maharashtra and Karnataka provide installation capacity proximate to major airline hubs, reducing aircraft downtime for retrofit programs.
Market Restraints
- Carbon fiber supply concentration:Raw material dependence on specialized composite suppliers creates input cost volatility and delivery timeline uncertainty for domestic fabricators.
- Certification timeline friction:DGCA airworthiness directive compliance requires extensive fatigue-life assessment protocols that extend retrofit approval cycles beyond airline fleet planning horizons.
- Next-generation aircraft substitution:Boeing and Airbus deliveries of factory-winglet-equipped narrow-bodies progressively eliminate the addressable retrofit base for aftermarket suppliers.
Strategic Opportunities
- Active control system integration:Morphing winglet technologies that adjust geometry in flight represent an unpenetrated premium tier with higher margin profiles than static blended configurations.
- Military aviation parallel track:Hindustan Aeronautics Limited programs for indigenous fighter and transport platforms cultivate a separate certification pathway with distinct technical specifications.
- Structural health monitoring bundling:Sensor-embedded winglet systems that enable predictive maintenance create recurring revenue streams beyond hardware installation.
Industry Challenges
- Aerospace composites engineering talent scarcity:Specialized laminate design and non-destructive testing expertise concentrates at HAL and select private tier-one suppliers, constraining workforce scaling.
- Legacy fleet integration complexity:Retrofit engineering must accommodate wing structure variations across Boeing 737NG, A320ceo, and ATR 72-600 platforms without standardized mounting interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Winglets Market |
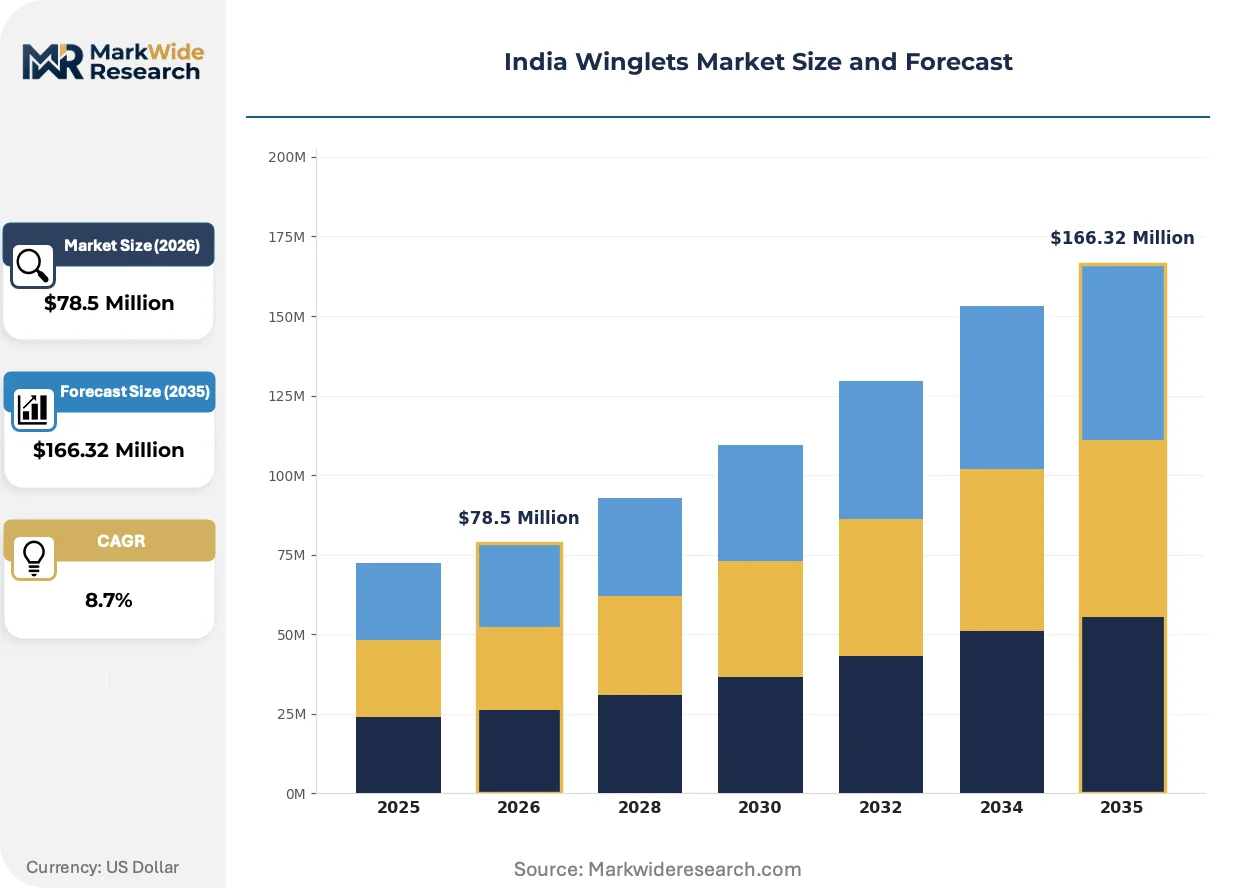
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $166.32 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Active Winglets, Blended Winglets, Others End User: Commercial Aviation, Military Aviation, Business Jets, Cargo Aircraft Technology: Passive Aerodynamic, Active Control, Hybrid Systems, Computational Fluid Dynamics Installation Type: Retrofit, OEM Installation, Aftermarket, Custom Solutions |
| Companies Covered | Aviation Partners Inc, Aviation Partners Boeing, Kaman Corporation, GKN Aerospace, FACC AG, Tamarack Aerospace Group, Winglet Technology LLC, RUAG Group, Hindustan Aeronautics Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Winglets Market Trends and Innovations
Active aerodynamic control systems are displacing passive blended geometries as the frontier of wingtip technology. This shift compresses the technology lifecycle for incumbent retrofit suppliers while opening new competitive terrain for sensor-integrated architectures.
Carbon-fiber-reinforced polymer manufacturing is converging with automated fiber placement robotics to reduce winglet production cycle times. Tier-one suppliers in Karnataka are adopting these systems to meet airline retrofit deadlines. This convergence is compressing the cost gap between imported and domestically fabricated aerostructures, reshaping supplier selection criteria for IndiGo and Air India procurement teams.
DGCA's evolving airworthiness directive framework is tightening fatigue-life assessment requirements for winglet modifications. Airlines must now submit extended structural monitoring protocols alongside initial installation approvals. Narrow-body operators with aging A320ceo fleets face the most acute compliance pressure, accelerating their retrofit scheduling to avoid grounded aircraft scenarios.
Buyer consolidation around full-fleet retrofit contracts is displacing single-aircraft upgrade purchasing. IndiGo and Air India now negotiate enterprise-level winglet agreements covering hundreds of airframes with performance-guarantee clauses. This pattern concentrates procurement leverage with the two largest domestic carriers, marginalizing smaller regional operators in supplier priority queues.
India Winglets Market Segmentation
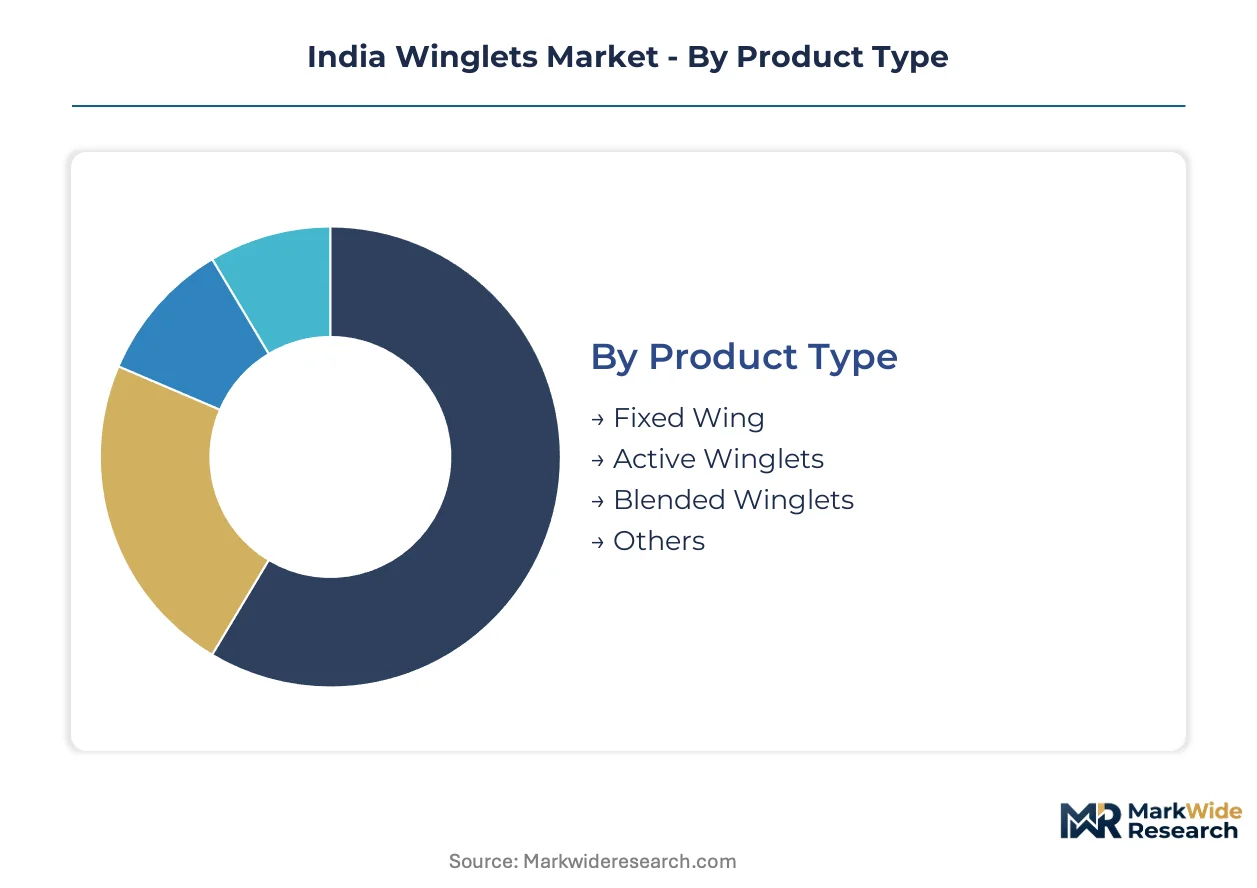
Winglet procurement patterns across India's aviation sector diverge sharply between high-volume narrow-body retrofits and emerging premium technologies. Fleet operators at IndiGo and Air India structure purchasing around fuel-payback periods, while defense programs through HAL pursue indigenous certification pathways with distinct technical specifications.
Product Type:
Blended winglets dominate current installation volumes across India's commercial fleet, while active systems command premium positioning for next-generation platforms.
- Blended Winglets:These smoothly curved wingtip extensions integrate carbon-fiber-reinforced polymer skins with aluminum substructures to reduce induced drag. Demand concentrates at IndiGo's A320ceo fleet in Delhi and Mumbai hubs, driven by aviation turbine fuel price volatility forcing operational cost controls.
- Active Winglets:Morphing geometries adjust aerodynamic profiles in-flight through embedded actuation systems. HAL's indigenous fighter programs in Bangalore anchor military demand, with DGCA fatigue-life assessments extending certification timelines beyond commercial retrofit windows.
- Fixed Wing:Static aerodynamic surfaces fabricated from conventional aluminum alloys serve legacy regional aircraft and cost-sensitive operators.
- Others:Experimental and hybrid configurations including split-scimitar derivatives occupy niche retrofit applications.
Today's leader: Blended Winglets. Tomorrow's challenger: Active Winglets.
End User:
Commercial operators generate retrofit volume, while defense procurement reshapes supplier economics through PLI scheme localization mandates.
- Commercial Aviation:Narrow-body fleet operators at IndiGo and Air India drive aftermarket demand for fuel-saving wingtip devices. Maharashtra's MRO clusters in Mumbai and Pune provide installation capacity proximate to major hubs, reducing aircraft downtime.
- Military Aviation:HAL programs for indigenous fighter and transport platforms cultivate separate certification pathways with BIS composite material specifications. The PLI scheme for aerospace manufacturing incentivizes domestic aerostructure fabrication for these programs.
- Business Jets:Private aviation operators in Delhi and Bangalore pursue custom winglet configurations for range extension.
- Cargo Aircraft:Dedicated freighter operators prioritize payload-optimized passive aerodynamic solutions over active control complexity.
Commercial Aviation captures the dominant revenue share. Military Aviation is climbing the fastest through HAL localization mandates.
Technology:
Passive systems anchor current retrofit economics, while sensor integration creates recurring revenue opportunities beyond hardware sales.
- Passive Aerodynamic:Fixed-geometry wingtip devices rely on composite laminate optimization without moving parts. Karnataka's aerospace manufacturing corridors adopt automated fiber placement robotics to compress production cycles for these assemblies.
- Active Control:Real-time geometric adjustment through flight-control-integrated actuators represents the premium technology tier. DGCA's evolving airworthiness directive framework tightens fatigue-life assessment requirements for these modifications.
- Hybrid Systems:Combined passive-active architectures balance fuel efficiency gains against certification complexity.
- Computational Fluid Dynamics:Simulation-driven design optimization tools reduce prototype iterations for domestic fabricators.
Passive Aerodynamic systems sustain current margins. Active Control systems offer the steepest expansion trajectory through structural health monitoring bundling.
Installation Type:
Retrofit programs face compressed timelines as next-generation aircraft deliveries progressively eliminate the addressable aftermarket base.
- Retrofit:Aftermarket installation on in-service narrow-bodies requires extensive wing structure modification. Airlines with aging A320ceo fleets face acute DGCA compliance pressure, accelerating scheduling to avoid grounded aircraft scenarios.
- OEM Installation:Factory-equipped winglet systems on Boeing and Airbus deliveries eliminate separate procurement decisions for fleet planners.
- Aftermarket:Third-party installation services concentrate in Maharashtra and Karnataka MRO clusters.
- Custom Solutions:Specialized engineering for unique platform requirements serves military and business aviation segments.
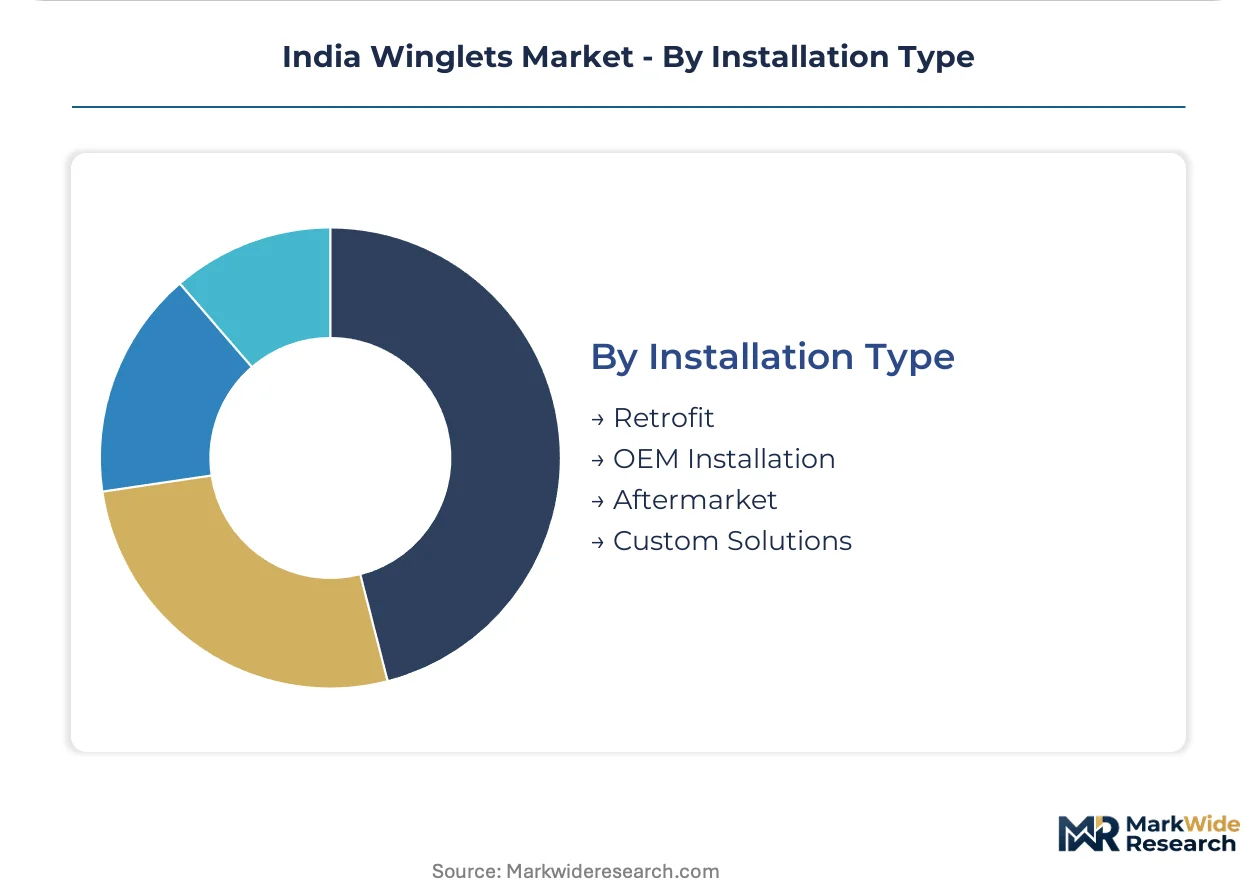
Retrofit commands current procurement attention. OEM Installation is gaining share fastest as factory-winglet-equipped deliveries displace upgrade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indian aerospace retrofit industry traces its modern lineage to Hindustan Aeronautics Limited's establishment in Bangalore during the 1940s, which seeded composite manufacturing expertise now diffusing into commercial aerostructures. This historical foundation shapes today's geographic concentration of winglet installation capacity.
Maharashtra
IndiGo's Mumbai hub operations and Air India's maintenance base at Chhatrapati Shivaji Maharaj International Airport generate concentrated retrofit demand for narrow-body fuel efficiency upgrades. The DGCA's airworthiness directive enforcement tightens compliance windows for aging A320ceo fleets operating from these facilities. MRO clusters in Mumbai and Pune provide proximate installation capacity, reducing aircraft downtime during wingtip device modification programs.
Karnataka
HAL's indigenous fighter programs in Bangalore anchor military aviation demand for active control winglets with distinct BIS composite specifications. The state's aerospace manufacturing corridors adopt automated fiber placement robotics to compress production cycles for carbon-fiber assemblies. Karnataka's PLI scheme beneficiaries fabricate aerostructures for both commercial retrofit and defense procurement channels.
Delhi-NCR
IndiGo's headquarters and primary maintenance operations at Delhi's Indira Gandhi International Airport structure procurement decision-making for fleet-wide retrofit contracts. The DGCA's central certification office processes fatigue-life assessments for winglet modifications, extending approval timelines for operators in this zone. Regional MRO facilities in Gurgaon and Noida support auxiliary installation capacity for business aviation and cargo operators.
Tamil Nadu
Chennai's emerging aerospace supply base serves tier-two fabrication requirements for composite laminate subcomponents. State industrial policy incentives attract foreign OEM supplier development programs targeting the narrow-body retrofit aftermarket. The Madras Institute of Technology and affiliated research centers feed specialized laminate design expertise into local manufacturing operations.
Telangana
Hyderabad's defense aviation ecosystem, centered on HAL's helicopter division and DRDO laboratories, cultivates parallel certification pathways for military winglet applications. The state's electronics manufacturing clusters support sensor-embedded structural health monitoring systems for next-generation active control architectures. Telangana's aerospace park development targets tier-one supplier attraction for composite aerostructure fabrication.
India Winglets Market Competitive Landscape
The competitive structure tilts toward joint-venture platforms and state-owned defense contractors. Aviation Partners Boeing leverages its transnational partnership to sustain technology transfer advantages in commercial narrow-body retrofits, while Hindustan Aeronautics Limited anchors indigenous capabilities through military program mandates. Three archetypes dominate: foreign OEM joint ventures, domestic public-sector defense fabricators, and specialized composite specialists. Competitive moves concentrate on PLI scheme localization partnerships and structural health monitoring bundling to extend revenue streams beyond hardware installation.
Among joint-venture and foreign-origin suppliers, Aviation Partners Boeing and GKN Aerospace occupy positions representing technology-led archetypes, while Hindustan Aeronautics Limited exemplifies the defense-anchored domestic fabricator category. These three entities sit within distinct competitive vectors—commercial retrofit technology transfer, specialized composite fabrication expertise, and indigenous military program execution—each responding to different regulatory and procurement incentive structures.
| Leading Market Players |
|---|
| Aviation Partners Inc |
| Aviation Partners Boeing |
| Kaman Corporation |
| GKN Aerospace |
| FACC AG |
| Tamarack Aerospace Group |
| Winglet Technology LLC |
| RUAG Group |
| Hindustan Aeronautics Limited |
| Others |
Pricing and Supply Chain Analysis
Joint-venture platforms between foreign OEMs and domestic defense contractors concentrate supply-side ownership in India's winglets market, tightening pricing discipline through technology-transfer gatekeeping and PLI scheme localization mandates. This ownership pattern forces aftermarket suppliers to absorb carbon fiber input volatility while passing limited cost recovery to airline procurement teams facing fuel-efficiency payback deadlines.
Pricing Analysis
Three-tier pricing structure across active control, blended composite, and fixed aluminum configurations segments buyer access by certification complexity and performance tier. Price differentiation hinges on DGCA fatigue-life assessment tier and bundled structural health monitoring service levels. Cost compression in passive retrofit assemblies is intensifying because automated fiber placement robotics at Karnataka manufacturing corridors compress production cycles. Low-cost regional operators exhibit acute price sensitivity, while full-fleet contract negotiators at IndiGo and Air India prioritize performance guarantees over unit economics.
Supply Chain Analysis
PLI scheme domestic-content thresholds reshaping sourcing are forcing tier-one suppliers to localize carbon-fiber-reinforced polymer fabrication or forfeit aerospace manufacturing incentives. Raw material supply draws from Japan, the United States, and specialized European composite specialists for aerospace-grade prepregs. Single-source vulnerability concentrates in Toray-grade carbon fiber feedstock, with tariff exposure on imported epoxy resin systems compounding input cost uncertainty. Distribution runs through Maharashtra and Karnataka MRO clusters proximate to IndiGo and Air India hub operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India winglets market functions as a regulatory compounder where DGCA airworthiness directive enforcement creates mandatory retrofit demand windows that override airline capital allocation discretion.
For Market Incumbents: Anticipate next-generation aircraft substitution eliminating narrow-body retrofit economics by accelerating active control system R&D partnerships with HAL's Bangalore fighter programs. Defensive consolidation through backward integration into carbon fiber preform manufacturing secures supply continuity against Toray-grade concentration risk. Certification investment in DGCA-approved fatigue-life assessment protocols extends competitive moats beyond hardware fabrication. For New Entrants and Emerging Players: Begin with sensor-embedded structural health monitoring systems for military aviation parallel tracks, where HAL indigenous programs offer separate certification pathways with less procurement concentration. The most penetrable white-space sits in Telangana's defense electronics clusters, where DRDO laboratory relationships enable active control actuator integration. A go-to-market angle targeting HAL subcontractor qualification bypasses direct competition with Aviation Partners Boeing's joint-venture lock on commercial retrofits. For Investors and Strategic Acquirers: Aerospace-focused private equity rolling up tier-two composite fabricators is the most active acquirer in this space, consolidating Karnataka and Tamil Nadu aerostructure suppliers ahead of PLI scheme qualification deadlines. Long-term viability hinges on positioning within defense procurement channels as commercial retrofit demand plateaus. The critical inflection signal to monitor is DGCA's issuance of extended fatigue-life assessment protocols for active control systems, which would validate premium technology tier economics.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Localization Partnership | Qualifies foreign OEMs for aerospace manufacturing incentives through Karnataka-based joint ventures. |
| Active Control System Certification | DGCA approval for morphing geometries opens premium pricing tier beyond passive retrofit economics. |
| Structural Health Monitoring Bundling | Sensor-embedded winglets create recurring revenue streams at IndiGo and Air India fleet contracts. |
| HAL Military Program Integration | Defense procurement channels offer parallel demand track with distinct BIS composite specifications. |
| Automated Fiber Placement Adoption | Robotics compression of production cycles narrows cost gap between imported and domestic aerostructures. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Delhi-NCR, Tamil Nadu, and Telangana, with primary inputs from each state-level aerospace manufacturing cluster. Primary interviews with DGCA certification officers, HAL program directors, airline fleet procurement managers, and MRO operations heads combined with secondary validation from BIS composite standards documentation, PLI scheme beneficiary registries, and DGCA airworthiness directive filings. Bottom-up triangulation across installation volume estimates at IndiGo and Air India retrofits converged with top-down aerostructure production capacity assessments at Karnataka manufacturing corridors.
Granularity-level modeling disaggregated revenue across product type, end user, technology, and installation type dimensions, with additional segmentation by state-level regulatory processing timelines. CAGRs were derived through logistic curve fitting to fleet replacement schedules and retrofit window constraints. Industry-specific forecast inputs incorporated aviation turbine fuel price volatility coefficients and DGCA certification backlog projections.
Several conditions sit outside the modeled scope, including geopolitical disruption to carbon fiber supply from Japanese and European sources, catastrophic airworthiness directive grounding orders, and acceleration of Boeing or Airbus factory-winglet-equipped delivery schedules. Forecasts reflect documented assumptions regarding PLI scheme continuity and DGCA staffing capacity for certification processing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
France Aviation Market
Aircraft
Aircraft Strut Market
Aircraft
Afterburner Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aircraft Aerostructures Market
Aircraft
US Aviation Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Commercial Aircraft Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Glider Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Europe Military Helicopters Market
Aircraft
Helicopter Wheels Market
Aircraft
Helicopter Lighting Market