
 A La Carte Market | 2026-2036
A La Carte Market Size, Share, and Industry Trends Forecast 2026-2036
A La Carte Market Analytics
Add-on customization revenue is tilting toward digital channels as mobile ordering platforms capture higher-margin individual-item sales. McDonald's Corporation leverages its app-based a la carte architecture to drive frequency through bundle-and-break-apart mechanics. Yum! Brands, Inc. sustains Taco Bell's "Build Your Own" format, which anchors higher check averages via incremental protein and sauce add-ons. Chipotle Mexican Grill, Inc. competes through its extra-charge guacamole and queso model, which differentiates per-unit profitability from base-burrito economics.
A la carte service denotes the practice of pricing and selling individual menu items separately rather than as fixed combinations, with each dish prepared to order based on customer selection from a discrete item list. This operational model requires point-of-sale systems capable of item-level inventory tracking and dynamic pricing adjustments for substitutions or additions. Main courses command the largest revenue share within product type segmentation, while beverages generate the highest incremental margin due to syrup-to-cup cost ratios and limited labor input. Service type segmentation shows delivery and takeaway expanding fastest as third-party logistics platforms reduce the historical dine-in dependency of a la carte profitability.
The FDA enforces calorie disclosure rules under Section 4205 of the ACA, compelling chains with twenty-plus locations to publish per-item nutritional data and thereby influencing reformulation toward lighter a la carte options. State-level health departments in California and New York supplement federal standards with sodium warning labels and trans-fat restrictions that reshape appetizer and dessert composition. Stakeholders must monitor how municipal bag bans and single-use packaging taxes alter the cost structure of individually wrapped a la carte items against consolidated set-menu plating.
Market Dynamics
Digital ordering platforms are compressing the traditional dine-in dependency of a la carte profitability, forcing operators to reconfigure kitchen workflows for item-level fulfillment speed rather than batch-plated efficiency.
Growth Catalysts
- Mobile app architecture:Quick-service chains deploy bundle-and-break-apart mechanics through proprietary ordering interfaces, driving purchase frequency via frictionless single-item selection.
- FDA Section 4205 enforcement:Calorie disclosure mandates under the ACA compel menu reformulation toward lighter standalone options, expanding addressable health-conscious demand.
- Third-party logistics platforms:DoorDash, Uber Eats, and regional equivalents normalize delivery and takeaway as primary a la carte channels, reducing real estate cost burdens.
Market Restraints
- Syrup commodity volatility:Beverage concentrate input costs fluctuate with corn and sugar futures, compressing the highest-margin category's profitability during inflationary cycles.
- Single-use packaging taxes:Municipal bag bans and container fees in California, New York, and Seattle add per-unit cost to individually wrapped items versus consolidated set-menu plating.
- Labor scarcity in back-of-house:Line cook and prep positions face persistent vacancy rates, constraining throughput capacity for made-to-order a la carte models.
Strategic Opportunities
- Ghost kitchen infrastructure:Delivery-only facilities in secondary US metros reduce rent per square foot while maintaining urban customer reach.
- Protein add-on modules:Incremental charging for double meat, plant-based substitutes, or premium cuts captures willingness-to-pay without base price increases.
- State sodium warning systems:California and New York disclosure requirements create first-mover advantage for reformulated appetizer and side portfolios.
Industry Challenges
- POS system fragmentation:Legacy point-of-sale architectures struggle with real-time inventory tracking for dynamic substitution pricing, requiring costly middleware upgrades.
- Cross-contamination protocols:Allergen management for build-your-own formats demands dedicated prep zones and staff certification, extending training timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A La Carte Market |
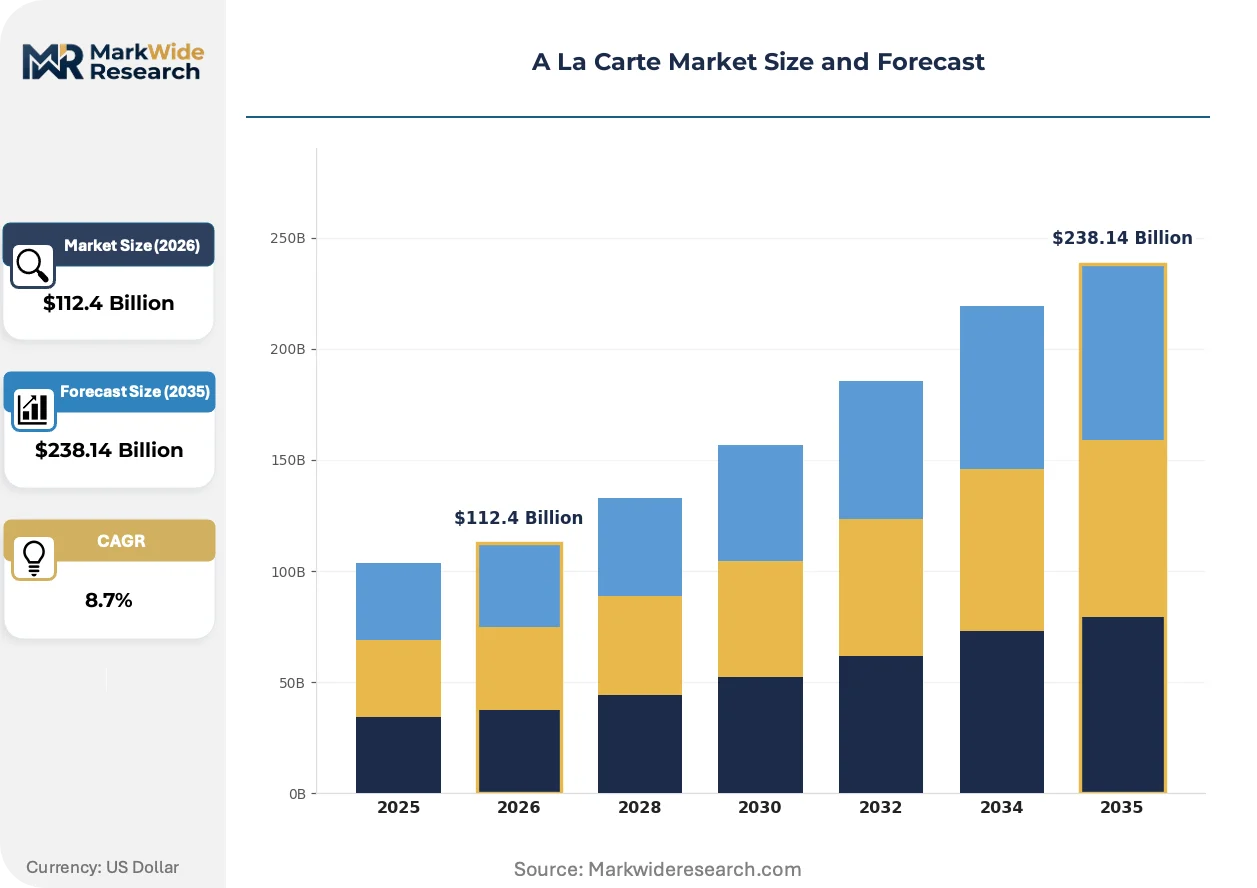
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Appetizers, Main Courses, Desserts, Beverages Menu Style: Set Menu, Buffet, Tasting Menu, Seasonal Menu Customer Type: Families, Couples, Business Groups, Tourists Service Type: Dine-in, Takeaway, Delivery, Catering |
| Companies Covered | McDonald’s Corporation, Yum! Brands, Inc., Restaurant Brands International Inc., Starbucks Corporation, Domino’s Pizza, Inc., Dunkin’ Brands Group, Inc., Chipotle Mexican Grill, Inc, Darden Restaurants, Brinker International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A La Carte Market Evolving Landscape
Kitchen automation and predictive analytics are redefining how a la carte operators balance customization speed with cost control, compressing the traditional trade-off between variety and throughput efficiency.
Computer vision inventory tracking is digitizing back-of-house operations through camera-based ingredient monitoring and automated reorder triggers. Mid-sized chains with 50-150 locations are piloting these systems fastest, seeking to reduce manual stock counts without enterprise-scale IT investment. The technology is digitizing how kitchens manage the complexity of item-level demand forecasting, shrinking waste from perishable components.
State-level sodium warning labels in California and New York are forcing appetizer and side-dish reformulation toward reduced-salt profiles. Manufacturers supplying chain restaurants report accelerated R&D cycles to maintain placement on disclosed-menu platforms. The regulation is reshaping supplier relationships, as operators demand cleaner-label inputs to avoid warning icon placement that depresses selection rates.
Subscription-based beverage programs are displacing traditional fountain cup economics in quick-service environments. Chains now offer monthly unlimited drink passes through mobile apps, converting variable syrup revenue into predictable recurring income. This model is concentrating most visibly in drive-thru-heavy US markets where frequency-based loyalty already dominates competitive strategy.
A La Carte Market Segmentation
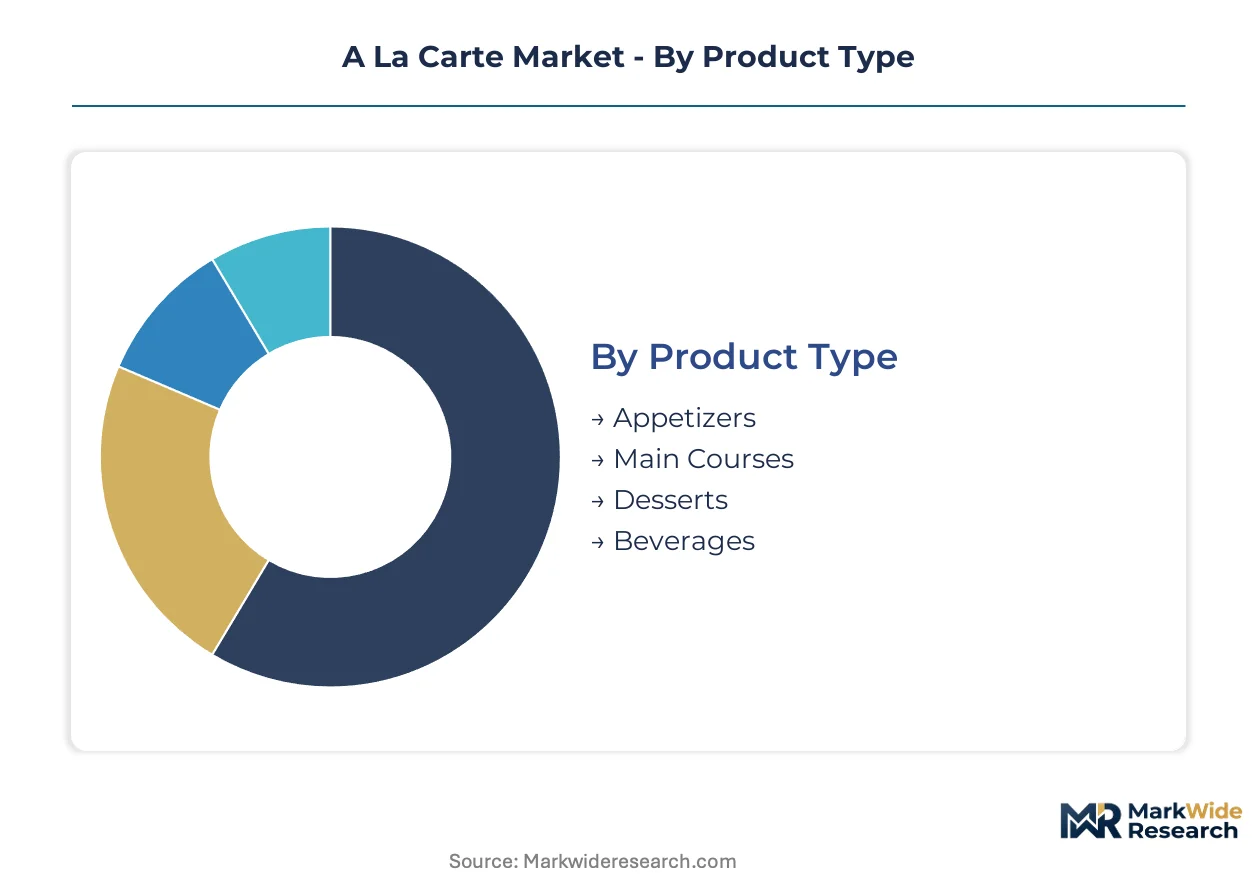
A la carte segmentation tracks how individual-item purchasing behavior fragments across occasion types, preparation formats, and fulfillment channels. Operators calibrate kitchen workflows and inventory systems against these divides to optimize per-unit profitability.
Product Type:
Operators sequence production capacity around daypart demand curves and margin profiles.
- Main Courses:Proteins and composed plates anchor check averages and drive kitchen labor allocation. Demand concentrates in US suburban markets where family-sized portions and protein-centric customization dominate evening dayparts.
- Beverages:Fountain drinks, specialty coffees, and alcoholic offerings generate the highest incremental margins due to syrup-to-cup cost ratios and minimal labor input. Digital subscription models in US drive-thru markets are displacing traditional per-transaction fountain economics.
- Appetizers:Shareable starters and small plates capture incremental occasion spending with lower ticket risk.
- Desserts:Individually portioned sweets and premium ice cream formats close meal occasions with high impulse attachment rates.
Established volume favors Main Courses; emerging adoption favors Beverages.
Menu Style:
Format selection determines ingredient flexibility, waste exposure, and pricing architecture.
- Set Menu:Fixed combinations reduce kitchen complexity and inventory SKUs while streamlining throughput. Corporate catering and US business-district lunch markets favor predictable per-head pricing with limited substitution requests.
- Buffet:Self-service formats minimize front-of-house labor but require volume-driven demand to justify food cost exposure. Tourist corridors in Orlando and Las Vegas sustain this model through high-turnover breakfast and brunch occasions.
- Tasting Menu:Multi-course progression formats command premium pricing through chef-driven narrative experiences.
- Seasonal Menu:Rotating ingredient availability creates urgency and justifies variable pricing across harvest cycles.
Operational simplicity favors Set Menu; experiential differentiation favors Tasting Menu.
Customer Type:
Party composition dictates seating configuration, pacing expectations, and upsell receptivity.
- Families:Multi-generational parties prioritize portion flexibility, children's options, and value-tier pricing. US suburban quick-service locations capture this segment through bundle-and-break-apart mechanics that accommodate varying appetites.
- Business Groups:Expense-account dining demands speed, dietary accommodation, and receipt clarity. Downtown US markets concentrate this demand during weekday lunch windows with pre-order and rapid-fire service protocols.
- Couples:Smaller parties tolerate longer preparation times and premium positioning.
- Tourists:Transient demand seeks recognizable items with minimal decision friction and multilingual menu support.
Frequency depth favors Families; margin expansion favors Business Groups.
Service Type:
Fulfillment channel selection is restructuring real estate requirements and labor deployment across the industry.
- Delivery:Third-party logistics platforms normalize off-premise a la carte consumption, compressing dine-in dependency. US urban markets show fastest adoption as DoorDash and Uber Eats reduce customer acquisition costs for operators.
- Takeaway:Counter pickup and curbside formats balance speed with order accuracy, requiring dedicated packaging workflows. Municipal bag bans in California and New York add per-unit cost to individually wrapped items versus consolidated set-menu plating.
- Dine-in:Traditional table service retains relevance for occasion-driven and experiential purchasing.
- Catering:Large-format a la carte ordering for events and institutions demands batch production protocols distinct from individual-item workflows.
Asset efficiency favors Delivery; margin preservation favors Takeaway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States treats a la carte purchasing as a default behavior through drive-thru customization and mobile app fragmentation, while European markets retain stronger set-menu traditions with a la carte emerging primarily in urban delivery corridors.
United States
Digital ordering platforms and drive-thru infrastructure normalize single-item purchasing across suburban and urban markets alike. The FDA enforces Section 4205 calorie disclosure mandates under the ACA, compelling menu reformulation toward lighter standalone options. Quick-service chains in Atlanta and Dallas-Fort Worth metro areas pilot predictive kitchen analytics to compress fulfillment times for item-level orders.
China
Delivery app ecosystems from Meituan and Ele.me accelerate a la carte adoption in tier-one cities where younger consumers reject fixed combinations. The State Administration for Market Regulation (SAMR) implements stricter food labeling standards for online catering platforms. Shanghai and Beijing restaurant clusters invest in ghost kitchen infrastructure to serve hyperlocal demand without dine-in real estate burdens.
Germany
Traditional Mittagstisch lunch culture resists full a la carte conversion, though Berlin and Munich see growth in customizable fast-casual formats. EFSA-aligned nutritional disclosure requirements pressure reformulation of sodium-heavy appetizer portfolios. The Rhine-Ruhr industrial corridor hosts pilot programs for automated beverage dispensing systems in workplace canteens seeking subscription-model revenue.
United Kingdom
Third-party delivery penetration in London and Manchester shifts casual dining toward item-level ordering despite historical pub-grub set-menu traditions. The Food Standards Agency mandates calorie labeling for out-of-home food businesses with over 250 employees. Birmingham's emerging food hall clusters experiment with multi-vendor a la carte platforms where customers assemble meals across separate kitchen operations.
Japan
Convenience store chains and automated restaurant formats extend a la carte logic into 24-hour urban consumption patterns. METI promotes food tech standardization for digital menu interoperability across platforms. The Osaka-Kobe manufacturing belt supplies precision cooking equipment enabling made-to-order throughput at volume scales previously requiring batch preparation.
A La Carte Market Competitive Landscape
Capability concentration sits with technology-integrated quick-service operators; scale advantage sits with legacy chains possessing dense real estate footprints. The market structures around three tiers: global franchisors with proprietary app ecosystems, regional specialists in build-your-own formats, and delivery-native brands operating through ghost kitchen infrastructure. Dominant competitive moves include strategic partnerships with third-party logistics platforms and backward integration into supply chain control for perishable customization components.
Within the global franchisor tier, McDonald's Corporation and Yum! Brands, Inc. occupy positions defined by mobile-first a la carte architecture, while Chipotle Mexican Grill, Inc. exemplifies the premium-fast-casual archetype built around incremental add-on economics. These three entities represent divergent strategic paths: frequency-driven app engagement, franchise-scaled customization formats, and ingredient-integrity positioning that commands per-unit pricing power.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Yum! Brands, Inc. |
| Restaurant Brands International Inc. |
| Starbucks Corporation |
| Domino's Pizza, Inc. |
| Dunkin' Brands Group, Inc. |
| Chipotle Mexican Grill, Inc |
| Darden Restaurants |
| Brinker International |
| Others |
Value Network & Pricing Analysis
The I-40 freight corridor connecting California agricultural suppliers to Texas distribution hubs concentrates perishable ingredient flows, with fuel surcharge volatility directly compressing margin structures for quick-service operators while enabling price differentiation between coastal premium sourcing and inland standard-tier markets.
Pricing Analysis
Long-term offtake contracts for poultry and beef proteins anchor base-menu pricing stability, while spot-market produce purchases introduce quarterly variability into salad and side-dish costs. Price differentiation hinges on USDA organic certification tier and geographic proximity to processing facilities, with West Coast operators absorbing higher delivery premiums. Cost compression in beverage syrup concentrates is intensifying because of corn futures volatility, squeezing the highest-margin category. Value-conscious suburban families exhibit greatest price sensitivity, while urban business groups tolerate premium positioning for speed and customization flexibility.
Supply Chain Analysis
Contract manufacturing concentration among Tyson Foods, Cargill, and JBS controls protein processing capacity for major quick-service chains, with regional co-packers filling specialty sauce and seasoning niches. Geographic supply concentration centers on Brazil, the United States, and Australia for beef; the United States and Thailand for poultry; and Mexico and California for fresh produce. Raw material dependencies include corn-derived sweeteners, soybean oil, and wheat flour for bun production. Single-source vulnerability in specialized packaging materials poses structural risk as municipal bag bans proliferate. Distribution runs through regional cold-chain distributors serving 50-150 location mid-market chains, with direct-to-store delivery dominating the largest franchisors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through third-party delivery platform aggregation, with DoorDash and Uber Eats capturing customer relationships and compressing operator margins through commission structures that now exceed historical food cost percentages.
For Market Incumbents: Build data moats through proprietary mobile app ecosystems that capture ordering behavior and enable dynamic pricing unmediated by third-party platforms. Defensive moves require backward integration into protein processing to secure supply during commodity spikes, and investment in ghost kitchen infrastructure to reduce real estate exposure. The threat of delivery platform disintermediation demands channel control through direct customer relationships. For New Entrants and Emerging Players: Build out ghost kitchen operations in secondary US metros where real estate costs remain below coastal thresholds and local demand density supports delivery-only economics. White-space targets include customizable fast-casual formats in suburban markets underserved by build-your-own concepts, and protein-add-on modules targeting health-conscious millennials. A direct-to-consumer mobile-first go-to-market angle bypasses platform commission structures. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy casual-dining parent companies seeking to divest underperforming a la carte brands with intact regional customer bases but outdated technology infrastructure. Long-term viability favors operators with digital ordering penetration above industry norms and supply chain flexibility to absorb ingredient volatility. The signal to watch is same-store sales decoupling from third-party delivery growth, indicating successful platform independence.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mobile App Development | McDonald's app architecture captures customer data and enables bundle-and-break-apart mechanics outside platform commissions. |
| Ghost Kitchen Infrastructure Expansion | Delivery-only facilities in Dallas-Fort Worth and Atlanta metros reduce rent per square foot while maintaining urban reach. |
| Protein Add-On Module Rollout | Chipotle's extra-charge guacamole model demonstrates per-unit profitability separation from base-product economics. |
| Supply Chain Backward Integration | Tyson Foods partnerships secure poultry volume commitments during commodity volatility cycles. |
| Subscription Beverage Program Launch | Monthly unlimited drink passes convert variable syrup revenue into predictable recurring income in drive-thru-heavy markets. |
Research Methodology
Cross-validation between operator earnings disclosures and third-party delivery platform commission data anchors the qualitative findings on margin compression dynamics. Primary interviews with quick-service chain procurement directors, ghost kitchen facility operators, and third-party logistics account managers combined with secondary validation from FDA menu labeling filings, state health department sodium warning regulations, and municipal packaging ordinance databases. Bottom-up location-level demand modeling and top-down national expenditure triangulation frame volume estimates across the projection horizon.
Calibration against historical same-store sales patterns and digital ordering adoption curves shapes the analytical framework. Segmentation dimensions modeled include product type, menu style, customer type, and service type, with daypart demand curves and regional regulatory clusters as industry-specific overlays. CAGRs derive from logistic diffusion curves for digital adoption and elasticity-adjusted price response functions. Forecast inputs incorporate mobile app penetration rates and ghost kitchen capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by delivery-native virtual brands or rapid platform commission restructuring would shift outcomes. Quarterly review of third-party delivery same-store sales decoupling metrics and municipal packaging tax implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
UAE Food Service Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Workplace Service Market
Food Service
Charbroiler Market
Food Service
Halal Food and Beverages Market
Food Service
Europe Cloud Kitchen Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Food Service Pasta Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Onboard Rail Catering Market
Food Service
Global Meal Kit Market
Food Service
Global Cafe and Bars Market
Food Service
Europe Vending Machine Market
Food Service
Food Service Dairy Products Market