
 Direct Fed Microbials Market | 2026-2036
Direct Fed Microbials Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Fed Microbials Market Intelligence
Strain-specific potency certification is unwinding commodity pricing across the direct fed microbials sector. Chr. Hansen Holding A/S leverages its culture collection depth to dominate high-value poultry applications. BASF SE anchors European supply through integrated fermentation capacity. Kemin Industries differentiates via species-specific formulation science for ruminant and monogastric segments.
Direct fed microbials comprise live bacterial cultures, typically Lactobacillus, Bacillus, and Enterococcus species, delivered at minimum viable counts measured in colony-forming units per gram to modulate gut microbiota and improve feed conversion efficiency in production animals. Probiotics within the product type category command the dominant margin pool due to veterinary prescription alignment and documented zootechnical performance claims. Application-wise, animal feed absorbs the bulk volume while aquaculture represents the fastest structural expansion as marine probiotic protocols displace prophylactic antibiotic use in shrimp and salmon operations.
The FDA Veterinary Feed Directive and EPA manure management standards jointly constrain antibiotic growth promoter use while elevating microbial alternative pathways in United States feed formulation. EU EFSA authorization requirements for feed additive strains enforce multi-year safety and efficacy dossiers that filter market access to capital-intensive players. Stakeholders must monitor strain patent cliffs and regulatory equivalence negotiations between FDA and EMA frameworks to time geographic expansion and R&D portfolio bets.
Market Dynamics
The FDA's Veterinary Feed Directive has fundamentally restructured how livestock producers formulate rations, forcing a wholesale pivot from antibiotic growth promoters toward validated microbial alternatives that demonstrate measurable feed conversion improvements.
Growth Catalysts
- Regulatory Displacement Mandates:The EPA's manure management standards now restrict antibiotic residue thresholds in agricultural runoff, compelling Midwest poultry integrators to certify probiotic-based feed programs that reduce environmental liability exposure.
- Strain Patent Expirations:Expiring intellectual property protections on foundational Lactobacillus and Bacillus cultures are democratizing access to production-ready inoculants for mid-tier feed compounders previously locked out of premium formulations.
- Aquaculture Protocol Standardization:Marine shrimp and salmon operations across Southeast Asia are institutionalizing probiotic hatchery protocols that displace chemotherapeutic bath treatments, creating pull-through demand for shelf-stable Bacillus spore concentrates.
Market Restraints
- Input Cost Volatility:Fermentation-grade dextrose and yeast extract prices fluctuate with corn futures and biofuel policy, compressing margins for culture producers lacking long-term carbohydrate supply contracts.
- Supply Concentration Risk:Master seed repositories and cryopreserved culture collections remain concentrated among three European heritage banks, creating single-point-of-failure exposure for new market entrants dependent on licensed strain deposits.
- Technical Viability Limits:Oxygen-sensitive anaerobic strains including Bifidobacterium species suffer logarithmic viability loss during pelleting temperatures above 75°C, restricting their deployment in standard steam-conditioned feed matrices.
Strategic Opportunities
- Underpenetrated Ruminant Segments:Dairy and beef operations in Brazil's Mato Grosso corridor remain underserved by species-specific formulations targeting rumen pH modulation and methanogenesis suppression.
- Precision Delivery Convergence:Integration of microencapsulation technologies with real-time rumen bolus sensors enables targeted release of probiotic payloads synchronized to animal physiological stress markers.
- Regulatory Equivalence Pathways:Mutual recognition agreements between FDA and Brazil's MAPA are streamlining strain authorization dossiers, reducing time-to-market for validated cultures already holding EFSA feed additive registrations.
Industry Challenges
- Multi-Year Certification Timelines:EFSA's full feed additive authorization requires 24-36 month safety and efficacy dossiers including target animal tolerance studies, freezing smaller developers out of European market access.
- Strain Characterization Skill Gaps:Whole-genome sequencing and metabolomic profiling capabilities required for regulatory-grade strain differentiation remain scarce among regional feed analysis laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Fed Microbials Market |
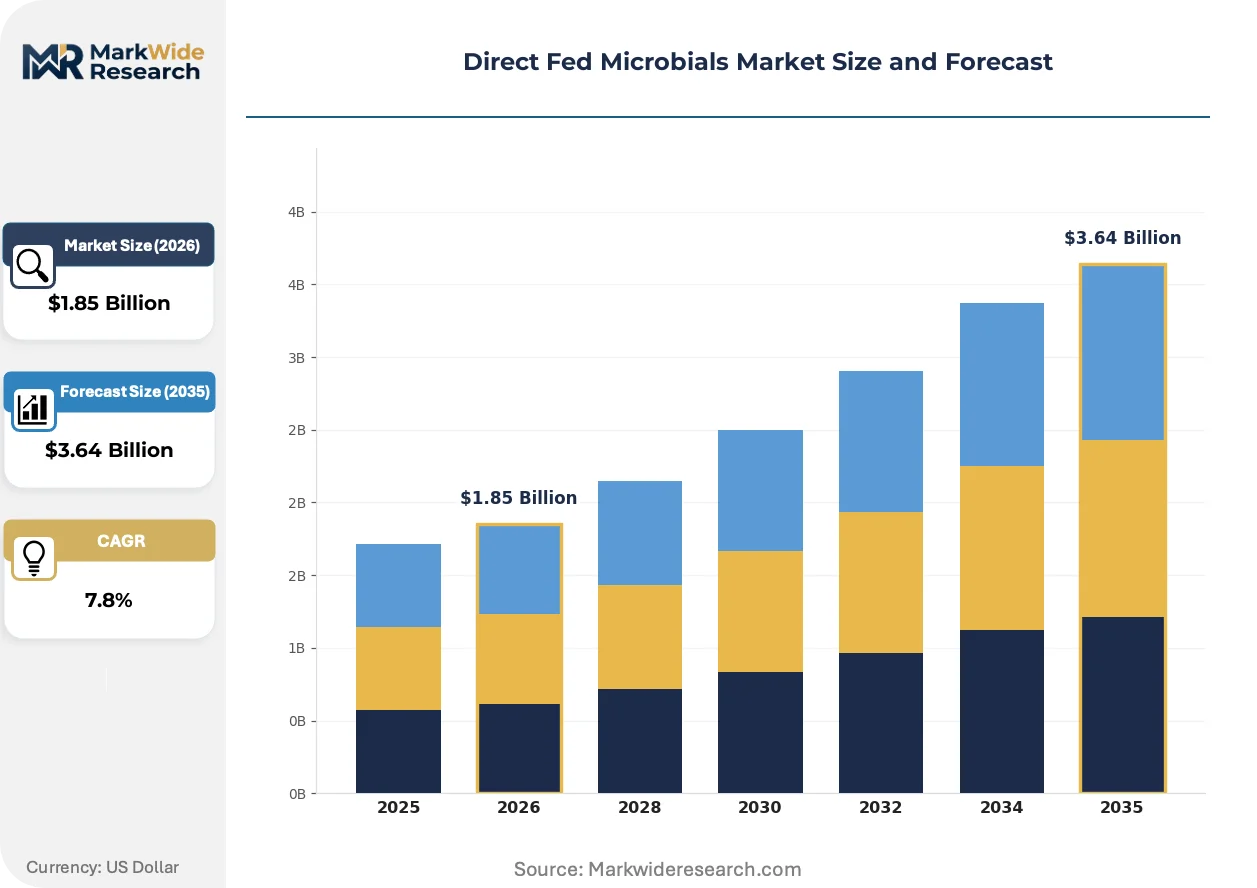
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Nutraceuticals Application: Animal Feed, Aquaculture, Pet Food, Crop Nutrition End User: Agriculture, Food Industry, Animal Husbandry, Pharmaceuticals Distribution Channel: Wholesale, Online, Retail, Direct Sales |
| Companies Covered | Cargill Incorporated, Chr. Hansen Holding A/S, Kemin Industries, Lallemand Inc., BASF SE, Novus International Inc., Koninklijke DSM N.V., Archer Daniels Midland Company, Bio-Vet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Fed Microbials Market Strategic Shifts & Innovations
Livestock nutrition is undergoing a fundamental recomposition as microbial solutions displace legacy pharmaceutical interventions, with formulation science, regulatory architecture, and procurement logic all shifting in parallel.
Multi-strain consortia engineered for synergistic colonization resistance are displacing single-species probiotic additives in commercial poultry operations. Integrated broiler producers in the US Southeast are adopting these cocktails at scale following documented reductions in necrotic enteritis incidence. The technology is displacing ionophore coccidiostats from starter ration formulations previously considered non-negotiable.
EFSA's 2023 updated guidance on qualified presumption of safety (QPS) status now requires whole-genome sequence screening for antimicrobial resistance determinants in all novel bacterial strains. This industrial consequence extends development timelines and capital requirements for culture collection banks seeking European market access. Ruminant-specific Enterococcus formulations face the most acute compliance burden given historical vancomycin resistance gene carriage.
Feed mill procurement directors are consolidating supplier relationships around vertically integrated fermentation houses that guarantee minimum viable count stability across 18-month shelf life claims. This consolidation is compressing spot-market spot purchases of unbranded cultures. The shift is most visible across Midwestern US swine operations where integrators now mandate certificate of analysis documentation for every lot delivered.
Direct Fed Microbials Market Segmentation
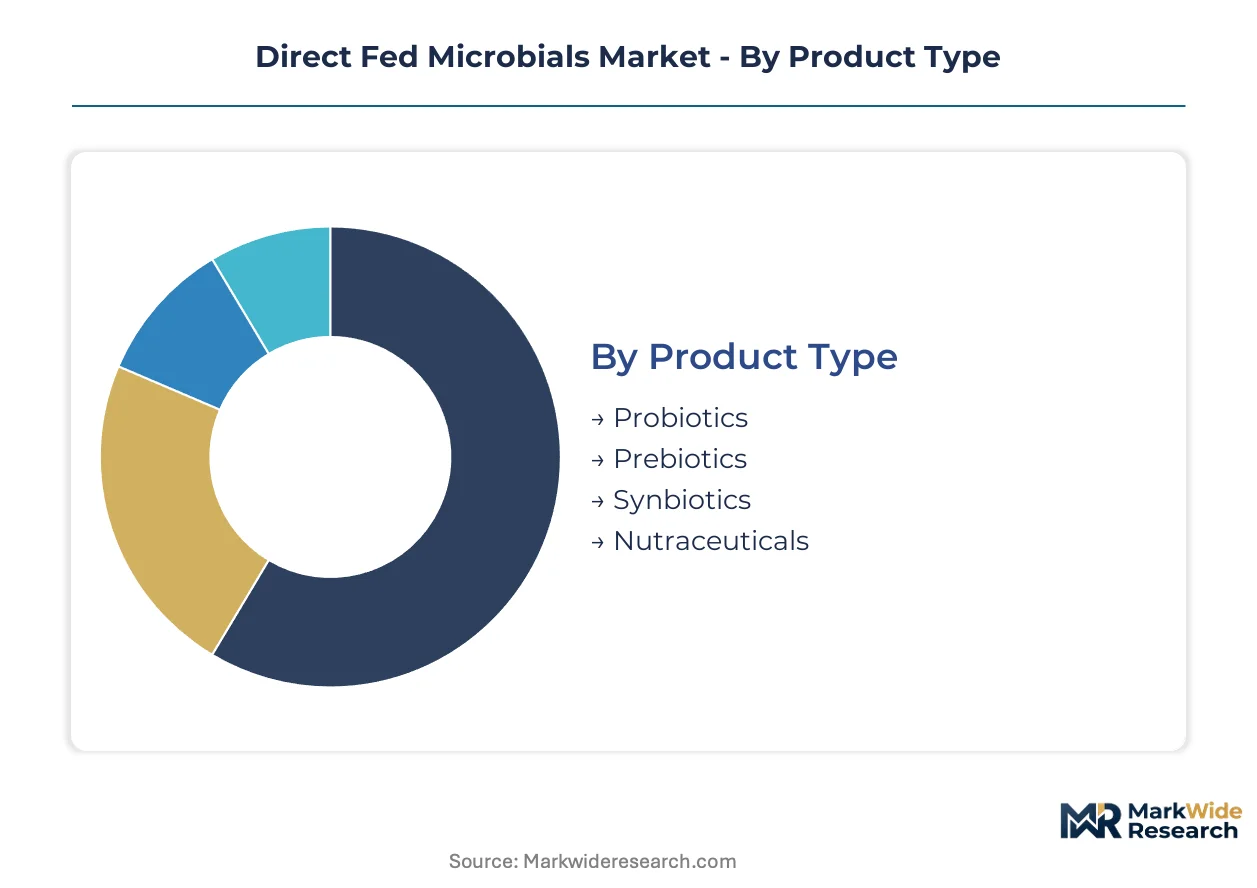
Direct fed microbials demand fragments across product technologies, application protocols, and procurement channels. Each segment carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Probiotics face acute substitution pressure from phytogenic feed additives and organic acid blends in cost-sensitive poultry rations.
- Probiotics:Live bacterial cultures of Lactobacillus, Bacillus, and Enterococcus species delivered at specified colony-forming units per gram. Midwestern US swine integrators drive bulk procurement following FDA Veterinary Feed Directive compliance mandates. Strain-specific potency certification now separates premium formulations from commodity alternatives.
- Prebiotics:Non-digestible oligosaccharides and inulin fractions that selectively nourish beneficial gut microbiota. European compound feed manufacturers favor these where EFSA QPS status requirements complicate live culture authorization timelines. Inulin from chicory root dominates ruminant applications for rumen fermentation modulation.
- Synbiotics:Combined probiotic-prebiotic formulations engineered for synergistic colonization resistance. Southeast Asian shrimp hatcheries deploy these to displace chemotherapeutic bath treatments.
- Nutraceuticals:Bioactive compounds with purported health benefits beyond basic nutrition, including specific microbial metabolites and postbiotic fractions.
Probiotics anchors the volume base while synbiotics gains share at the steepest rate.
Application:
Cost tier segmentation separates commodity feed supplementation from precision aquaculture protocols commanding formulation premiums.
- Animal Feed:Bulk incorporation into poultry, swine, and ruminant rations at inclusion rates of 0.01% to 0.1% by weight. Brazilian beef operations in Mato Grosso remain underserved by species-specific formulations targeting rumen pH modulation. EPA manure management standards now restrict antibiotic residue thresholds in agricultural runoff.
- Aquaculture:Marine probiotic deployment in shrimp and salmon hatcheries requiring shelf-stable Bacillus spore concentrates. Norwegian salmon producers lead protocol standardization following documented reductions in prophylactic antibiotic dependency. Water quality management drives recurring application cycles absent in terrestrial livestock.
- Pet Food:Premium companion animal nutrition incorporating human-grade microbial strains with digestive health positioning.
- Crop Nutrition:Agricultural biostimulant applications extending microbial benefits to plant root zone colonization and nutrient uptake enhancement.
Animal Feed absorbs the dominant procurement volume while aquaculture climbs the fastest.
End User:
Customer type fragmentation concentrates procurement authority among integrated livestock operations versus fragmented crop nutrition distributors.
- Agriculture:Broadacre farming operations incorporating direct fed microbials through soil amendment and crop biostimulant pathways. Midwestern US corn-soybean rotations drive seasonal demand spikes tied to planting windows.
- Food Industry:Meat and dairy processors specifying probiotic feed programs for antibiotic-free certification and residue compliance. Retailer procurement standards now mandate documented microbial alternative pathways for supplier qualification.
- Animal Husbandry:Dedicated livestock production facilities spanning commercial poultry houses, swine finishing barns, and dairy operations. Integrated broiler producers in the US Southeast adopt multi-strain consortia at scale following necrotic enteritis incidence reductions.
- Pharmaceuticals:Veterinary therapeutic applications and companion animal probiotic formulations requiring prescription alignment and documented zootechnical performance claims.
Animal Husbandry commands the procurement volume base while Food Industry gains share fastest through retailer-driven compliance mandates.
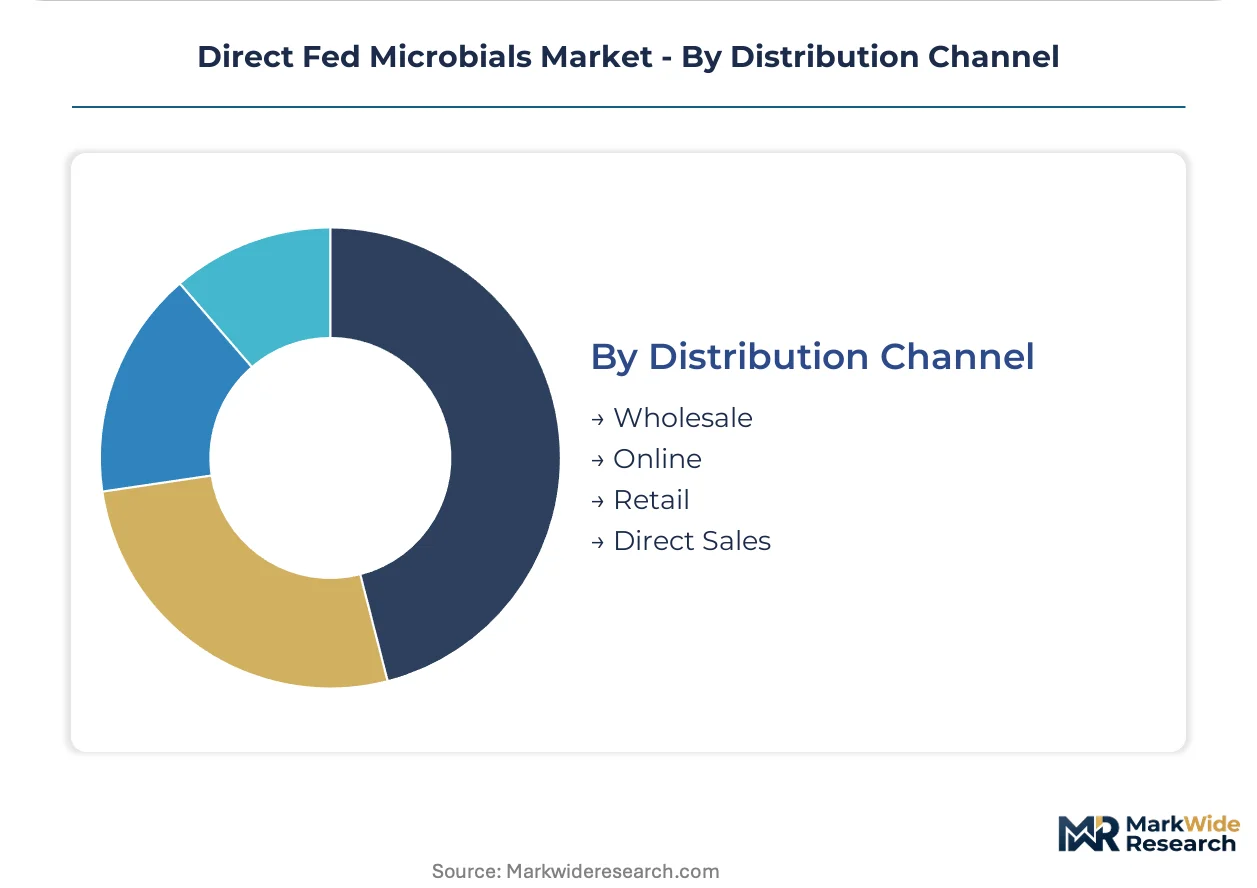
Distribution Channel:
Supply concentration among vertically integrated fermentation houses reshapes channel economics and spot-market viability.
- Wholesale:Bulk procurement through feed mill distributors and agricultural supply cooperatives serving regional livestock concentrations. Midwestern US poultry and swine operations drive consolidated purchasing through integrator-controlled supply chains.
- Online:Direct-to-producer platforms enabling smaller operations to access certified cultures without minimum order thresholds. E-commerce penetration remains limited by cold-chain requirements for oxygen-sensitive anaerobic strains.
- Retail:Farm supply stores and veterinary clinics serving hobby farmers and companion animal owners with packaged probiotic supplements.
- Direct Sales:Manufacturer-to-integrator relationships guaranteeing certificate of analysis documentation and 18-month shelf life stability claims. US swine operations now mandate lot-specific viability verification for every delivery.
Wholesale anchors volume throughput while Direct Sales expands most quickly through integrator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heritage culture banks in Denmark and Germany control master seed repositories that constrain new entrant access. Fermentation capacity clusters in the US Midwest and Brazil's agricultural corridors anchor supply for poultry and beef operations. Regulatory divergence between FDA and EFSA authorization timelines fragments geographic expansion strategies.
United States
Integrated poultry and swine operations in Iowa and North Carolina drive bulk procurement of certified probiotic feed additives. The FDA's Veterinary Feed Directive mandates documented microbial alternative pathways for antibiotic-free certification compliance. Midwest agricultural corridors concentrate feed mill demand where integrators now require lot-specific viability verification for every delivery.
Brazil
Beef operations in Mato Grosso and São Paulo states remain underserved by species-specific formulations targeting rumen pH modulation. MAPA's feed additive authorization pathways are streamlining through mutual recognition agreements with FDA frameworks. Southern Brazil's dairy clusters are adopting precision delivery technologies synchronized to animal physiological stress markers.
Germany
EFSA's qualified presumption of safety requirements enforce multi-year safety dossiers that filter market access to capital-intensive players. The country's heritage culture banks maintain cryopreserved strain collections that create single-point-of-failure exposure for licensed deposits. Bavaria's industrial biotechnology corridor anchors integrated fermentation capacity serving European compound feed manufacturers.
China
Aquaculture probiotic deployment in Guangdong and Fujian provinces is displacing chemotherapeutic bath treatments in shrimp hatcheries. SAMR's feed additive registration requirements are converging with international safety standards for microbial strain authorization. Yangtze River Delta feed compounders are consolidating supplier relationships around vertically integrated fermentation houses guaranteeing shelf-life stability.
India
Dairy cooperatives in Gujarat and Maharashtra are expanding probiotic feed programs to improve milk yield and reduce veterinary antibiotic dependency. FSSAI's feed safety regulations are elevating microbial alternative pathways in ration formulation standards. Punjab's poultry integration belt is adopting multi-strain consortia following documented reductions in necrotic enteritis incidence.
Direct Fed Microbials Market Key Industry Players
Concentration sits with integrated fermentation houses possessing captive culture collections and multi-year regulatory dossier capabilities. Three strategic archetypes dominate: heritage European culture banks with deep strain libraries, diversified agricultural conglomerates with backward integration into fermentation capacity, and mid-tier specialists targeting species-specific formulation science. Competitive moves center on M&A to secure strain patent portfolios and capacity expansion to guarantee 18-month shelf-life stability claims for integrator procurement mandates.
Within the heritage culture bank tier, Chr. Hansen Holding A/S and Lallemand Inc. exemplify players anchored by multi-decade strain collection depth. BASF SE represents the diversified chemical conglomerate archetype with integrated fermentation infrastructure spanning feed and pharmaceutical applications. Kemin Industries occupies a specialist position emphasizing species-specific formulation science for ruminant and monogastric segments.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Chr. Hansen Holding A/S |
| Kemin Industries |
| Lallemand Inc. |
| BASF SE |
| Novus International Inc. |
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| Bio-Vet |
| Others |
Cost & Logistics Intelligence
Bacillus spore concentrates displacing oxygen-sensitive anaerobic strains in standard feed matrices simultaneously shift production geography toward temperate fermentation corridors and compress pricing premiums for thermostable formulations. The substitution redraws supplier economics as integrators demand validated viability across steam-pelleting temperatures above 75°C.
Pricing Analysis
The FDA's Veterinary Feed Directive dictates the pricing tier structure across the direct fed microbials sector, separating certified probiotic formulations from unbranded commodity cultures. Three-tier pricing structure across premium, standard, and economy levels reflects strain-specific potency certification, volume scale procurement, and certificate of analysis documentation depth. Cost compression in economy tiers is intensifying because mid-tier feed compounders now access expiring Lactobacillus and Bacillus patents. Midwestern swine integrators demonstrate least price sensitivity due to regulatory compliance mandates, while regional poultry operations remain most sensitive to per-unit inclusion costs.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for fermentation-grade dextrose and yeast extract shipments from Southeast Asian suppliers. Production gravity centers on Denmark, Germany, and the United States Midwest, where heritage culture banks and integrated fermentation houses anchor supply. Raw material sourcing draws from corn futures-linked dextrose markets and biofuel policy-tethered yeast extract availability. Single-source vulnerability concentrates in European master seed repositories. Distribution runs through integrator-controlled wholesale channels with direct sales expanding fastest for certificate-of-analysis-mandated deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct fed microbials function as a platform economy where strain authentication protocols and regulatory dossier interoperability determine ecosystem participation. EFSA-FDA mutual recognition pathways represent the critical interoperability shift enabling cross-border formulation deployment.
For Market Incumbents: Shield market position by deepening captive strain collection depth through targeted acquisition of regional culture banks facing patent cliff exposure. Prioritize backward integration into fermentation-grade carbohydrate supply contracts to neutralize dextrose price volatility. Expand cryopreservation capacity in Brazil's agricultural corridor to preempt MAPA authorization bottlenecks.
For New Entrants and Emerging Players: FDA-Brazil MAPA mutual recognition fast-tracks offer the most penetrable regulatory pathway for validated cultures already holding EFSA registrations. Target Brazil's Mato Grosso beef operations with species-specific ruminant formulations addressing rumen pH modulation gaps. Deploy precision delivery technology partnerships as the primary go-to-market angle to differentiate from commodity probiotic suppliers.
For Investors and Strategic Acquirers: EFSA's 2023 QPS guidance update reshapes the acquisition landscape by extending development timelines and capital requirements for novel strain authorization. Five-to-ten year viability hinges on regulatory dossier depth rather than fermentation scale alone. Prioritize mid-tier specialists possessing whole-genome sequencing capabilities and metabolomic profiling infrastructure. Monitor strain patent expiration schedules as the critical inflection signal for democratization risk and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Collection Acquisition | Consolidates cryopreserved culture depth against patent cliff democratization. |
| Precision Delivery Technology Partnership | Enables microencapsulation integration with real-time rumen bolus sensors. |
| EFSA-FDA Regulatory Equivalence Investment | Streamlines multi-jurisdiction authorization dossiers for validated cultures. |
| Backward Integration into Carbohydrate Supply | Secures long-term dextrose contracts against biofuel policy volatility. |
| Multi-Strain Consortia R&D Expansion | Displaces single-species additives in Southeast US broiler operations. |
Research Approach
Initial hypotheses were tested against primary input from feed mill procurement directors, regulatory affairs leads at culture collection banks, integrator nutritionists, and veterinary microbiology researchers and refined through secondary validation against FDA Veterinary Feed Directive implementation records, EFSA feed additive authorization databases, USDA livestock production statistics, and SEC filings from publicly traded fermentation houses. Bottom-up strain-level demand modeling triangulated against top-down regional feed consumption aggregates.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within segmentation dimensions spanning product technology, application protocol, end-user procurement authority, and distribution channel concentration. CAGRs were derived from segment-level growth rate reconciliation. Modeled inputs incorporated regulatory authorization timelines, strain patent expiration schedules, and aquaculture protocol standardization trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-EPA regulatory displacement and EFSA QPS enforcement continuity; material deviation would warrant model refresh. Strain characterization capability gaps, feed mill consolidation patterns, and mutual recognition agreement progress represent specific risk factors that could revise forecasts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Mediterranean Metabolic Syndrome Support Ingredient Packs Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Organic Protein Powder Market